
 Brandy Flavor Market | 2026-2036
Brandy Flavor Market Size, Share, and Industry Trends Forecast 2026-2036
Brandy Flavor Market Outlook
REACH is consolidating the cost-of-entry calculus for European flavor houses, demanding exhaustive substance documentation and safety profiling. Kerry Group leverages its integrated taste and nutrition platform to sustain R&D intensity across multiple geographies. Givaudan anchors its competitive position through deep specialization in alcoholic beverage flavor architectures. Sensient Technologies competes on manufacturing scale, operating large-scale extraction and compounding facilities that serve multinational spirits clients.
Brandy flavor denotes a concentrated aromatic preparation designed to replicate or enhance the sensory profile of distilled grape or fruit brandy, typically comprising esters, aldehydes, oak lactones, and vanilla compounds in alcohol or propylene glycol carriers, manufactured through precision blending, solvent extraction, or enzymatic synthesis for application in beverages, confectionery, and culinary formulations. The vanilla and oak product types dominate margin pools due to their complexity and premium positioning in aged-spirit simulations, while fruit variants lead volume growth through cocktail innovation. Application concentration in cocktails reflects structural expansion in mixology culture, whereas baking and cooking segments remain mature with slower innovation cycles.
The European Food Safety Authority enforces stringent evaluation protocols for flavoring substances under EU Regulation 1334/2008, directly shaping product approval timelines and reformulation costs. The US Food and Drug Administration maintains separate Generally Recognized as Safe determinations that govern market access for imported flavor compounds. India's Food Safety and Standards Authority implements localized additive standards that require adaptation for multinational suppliers. Stakeholders must monitor divergence between regional purity specifications and emerging sustainability disclosure requirements to align portfolio investments with compliance trajectories.
Market Dynamics
EU Regulation 1334/2008 is tightening substance documentation requirements for flavoring compounds, forcing reformulation investments and consolidating the supplier base as smaller houses exit due to compliance cost burdens.
Growth Catalysts
- Premium cocktail programs:Bars in France and Spain are deploying aged-spirit simulations to reduce inventory costs while maintaining menu sophistication. Mixology certification programs accelerate flavor adoption.
- REACH compliance infrastructure:Established European flavor houses leverage existing safety profiling capabilities to capture market share from exiting competitors. Documentation depth becomes a competitive moat.
- Enzymatic synthesis advancement:Biocatalytic production of oak lactones and vanilla compounds reduces raw material dependency on tropical supply chains. Process yields improve extraction economics.
Market Restraints
- Grape-derived precursor volatility:Concentration of brandy spirit production in southwestern France creates supply vulnerability to vintage variation and climate impacts on raw material quality.
- EFSA evaluation timelines:Novel substance approval cycles extend 18-36 months, delaying product launches and tying up R&D capital without revenue certainty.
- Natural extract substitution:Synthetic vanillin and artificial oak alternatives compete on cost in mass-market applications, compressing margins for authentic replication formulations.
Strategic Opportunities
- India FSSAI alignment:Localized additive standards create first-mover advantage for suppliers establishing domestic compounding facilities ahead of multinational competitors.
- Non-alcoholic spirit applications:Zero-proof cocktail formulations require concentrated flavor architectures to compensate for absent ethanol carriers. This application segment expands addressable market beyond traditional spirits.
- CSRD disclosure mandates:Sustainability reporting requirements favor suppliers with verified supply chain transparency, enabling premium positioning through documented provenance.
Industry Challenges
- Flavor chemist specialization gap:Synthesis of complex ester profiles for aged brandy replication requires expertise in Maillard reaction chemistry that outpaces current training program output.
- Cross-regulatory harmonization friction:Divergence between FDA GRAS determinations and EFSA positive lists forces parallel safety studies, duplicating toxicology investment for multi-market products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brandy Flavor Market |
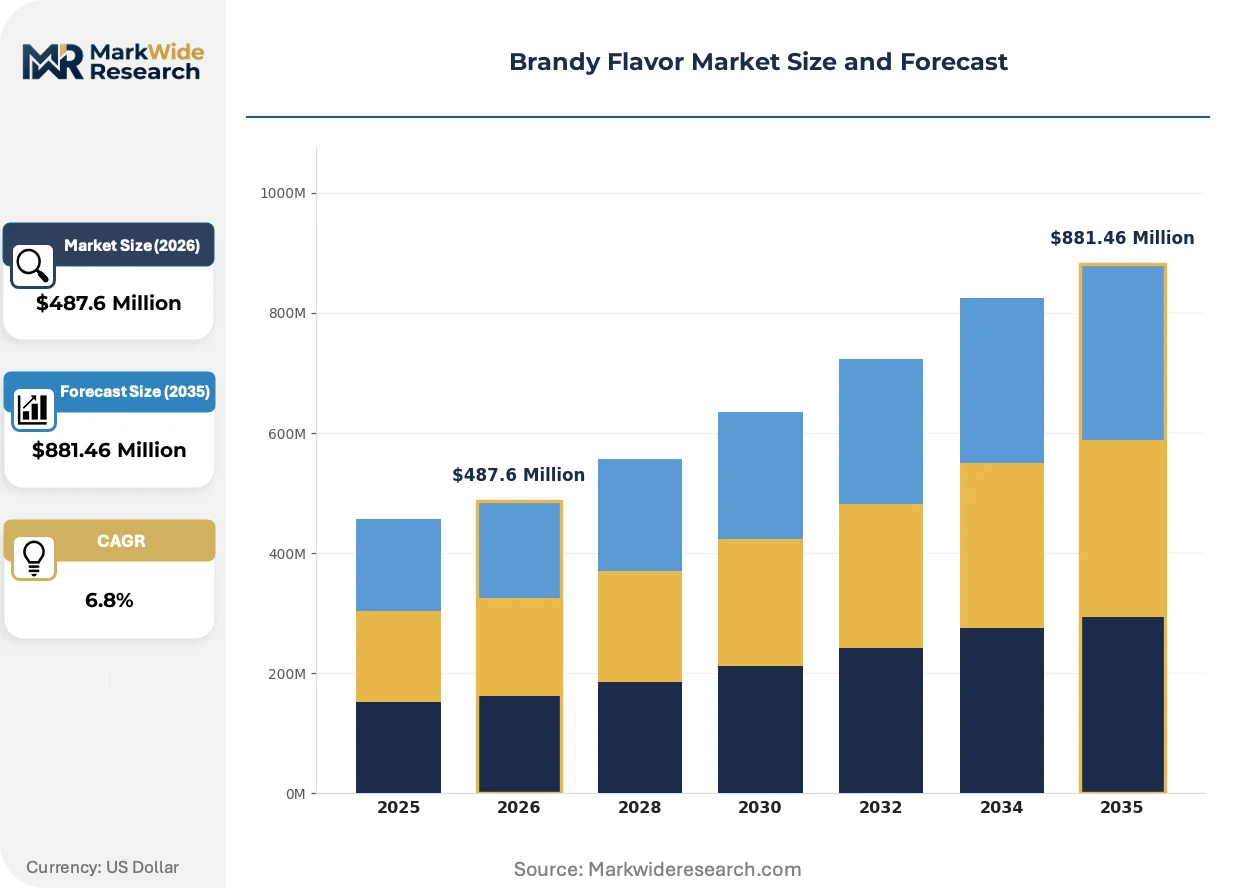
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit, Spice, Vanilla, Oak Application: Cocktails, Cooking, Baking, Infusions Packaging Type: Bottle, Can, Bag, Jar End User: Bars, Restaurants, Households, Events |
| Companies Covered | Kerry Group, Givaudan, Sensient Technologies, DSM-Firmenich, MANE, Symrise, Robertet, T. Hasegawa, Takasago International Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brandy Flavor Market Strategic Shifts
Precision fermentation and biosynthesis are displacing solvent extraction for high-value aromatic compounds, altering cost structures and geographic production patterns for premium flavor ingredients.
Bioreactor-based production of oak lactones and vanillin precursors is decentralizing manufacturing away from traditional extraction centers in Madagascar and Indonesia. Mid-sized flavor houses in Germany and the Netherlands are adopting this capability, reducing dependency on agricultural commodity cycles. Distributed production compresses lead times for custom formulations while insulating margins from harvest volatility.
REACH substance registration deadlines are forcing portfolio rationalization across European flavor suppliers. The regulation's exhaustive data requirements favor established players with dedicated regulatory affairs departments. Small and mid-sized houses are responding through collaborative registration consortia, sharing toxicology study costs to maintain market access for niche aromatic compounds.
Direct procurement relationships between craft distillers and specialty flavor suppliers are shortening traditional distribution chains. Boutique spirits producers in Oregon and Tasmania are bypassing broadline distributors to commission bespoke extraction profiles. This channel shift concentrates technical service demands on smaller supplier teams while rewarding formulation agility over manufacturing scale.
Brandy Flavor Market Segmentation
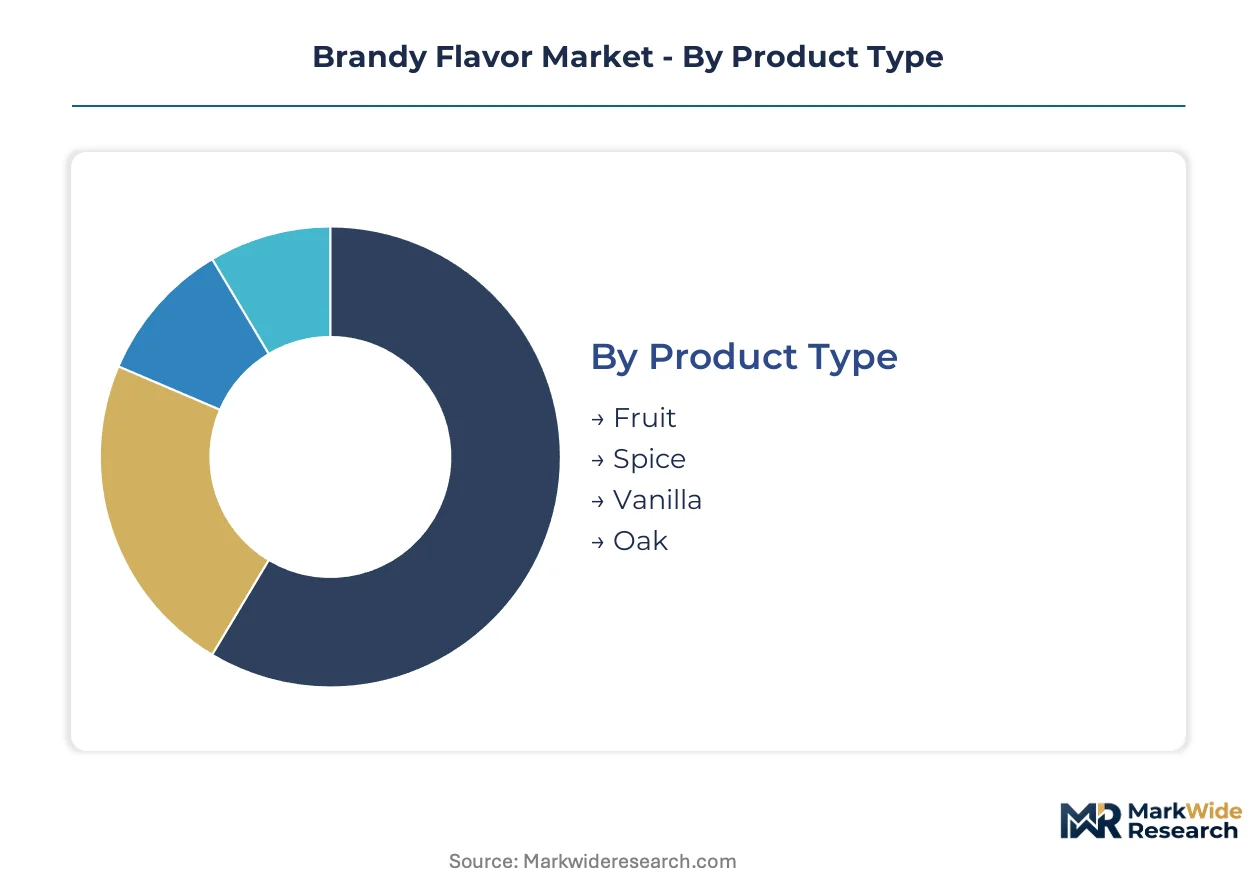
Brandy flavor segmentation reveals divergent compliance burdens across product architectures. EFSA substance approvals concentrate in premium formulations while mass-market variants face cost-driven substitution pressures. Understanding these fault lines enables targeted portfolio allocation against regulatory and demand trajectories.
Product Type:
EFSA evaluation protocols under EU Regulation 1334/2008 impose heaviest documentation requirements on oak and vanilla variants due to complex lactone and phenolic compound profiles. Fruit segments navigate lighter approval cycles but face natural extract authentication mandates.
- Vanilla:Concentrated vanillin and ethyl vanillin formulations in propylene glycol carriers demand exhaustive safety profiling for EFSA positive list inclusion. Premium cocktail programs in France and Spain absorb these compliance costs for aged-spirit simulation authenticity. Supply vulnerability to Madagascar vanilla bean harvest volatility drives enzymatic synthesis investment.
- Oak:Oak lactone concentrates and wood-derived phenolic extracts require REACH substance registration for European market access. German and Dutch flavor houses leverage bioreactor production to decouple from French cooperage supply chains. Mixology certification programs accelerate demand for precise tannin and toast-level replication.
- Fruit:Ester-based apple, pear, and grape profiles face lighter EFSA scrutiny but require vintage-consistent sourcing documentation.
- Spice:Cinnamaldehyde and clove-derived compounds trigger allergen labeling requirements under EU flavoring regulations.
Vanilla sits at the top of the volume ranking, with oak climbing the fastest.
Application:
Application segments stratify by technical service intensity and formulation complexity. Cocktail applications demand concentrated architectures to perform in diluted matrices, while thermal processing in baking imposes stability specifications.
- Cocktails:High-proof, low-dose concentrates designed for rapid dispersion in aqueous alcohol matrices. Bars in Barcelona and Paris deploy these formulations to reduce aged spirit inventory carrying costs while maintaining menu sophistication. Zero-proof cocktail expansion creates new demand for ethanol-free carrier systems.
- Cooking:Heat-stable formulations with Maillard-reactive precursors for sauce and reduction applications. Michelin-starred kitchens in Lyon commission bespoke extraction profiles for signature preparations. Flavor chemist specialization gaps constrain supply for complex aged-profile replication.
- Baking:Oven-stable vanilla and fruit esters with controlled volatility profiles for pastry applications.
- Infusions:Cold-extraction optimized compounds for non-thermal beverage integration.
Cocktails command the largest revenue pool, with cooking gaining share fastest.
Packaging Type:
Packaging configurations align with end-user scale and dispensing precision requirements. Food service channels prioritize portion control and contamination resistance, while household segments favor shelf stability and storage convenience.
- Bottle:Glass and PET formats with dropper or pourer closures for precise dosing control. Premium bars in Madrid specify amber glass for UV-sensitive oak lactone preservation. REACH-compliant labeling mandates extend to packaging material migration testing.
- Can:Aerosol and pressurized formats for rapid dispersion in high-volume service environments. Event catering operations in Bordeaux favor single-serve cans for portion standardization. FSSAI additive standards in India require localized can lining specifications.
- Bag:Flexible pouch formats for bulk food service dispensing systems.
- Jar:Wide-mouth containers for spoonable paste and crystalline formulations.
Bottle formats dominate value capture, with can packaging expanding most quickly.
End User:
End-user segmentation reflects divergent procurement sophistication and technical service demands. Commercial channels require formulation customization and regulatory documentation, while household segments prioritize retail accessibility and usage simplicity.
- Bars:Premium cocktail programs with dedicated mixology staff and inventory optimization mandates. Craft distillers in Oregon and Tasmania commission bespoke extraction profiles directly from specialty suppliers. CSRD disclosure requirements favor documented supply chain transparency for sustainability positioning.
- Restaurants:Kitchen-integrated applications with chef-driven specification development. Three-star establishments in Champagne region source oak variants tied to specific cooperage provenance. Cross-regulatory harmonization friction between FDA GRAS and EFSA positive lists complicates multinational supplier relationships.
- Households:Retail-packaged formats with simplified dosing instructions and recipe integration.
- Events:Single-serve and portion-controlled packaging for temporary service operations.
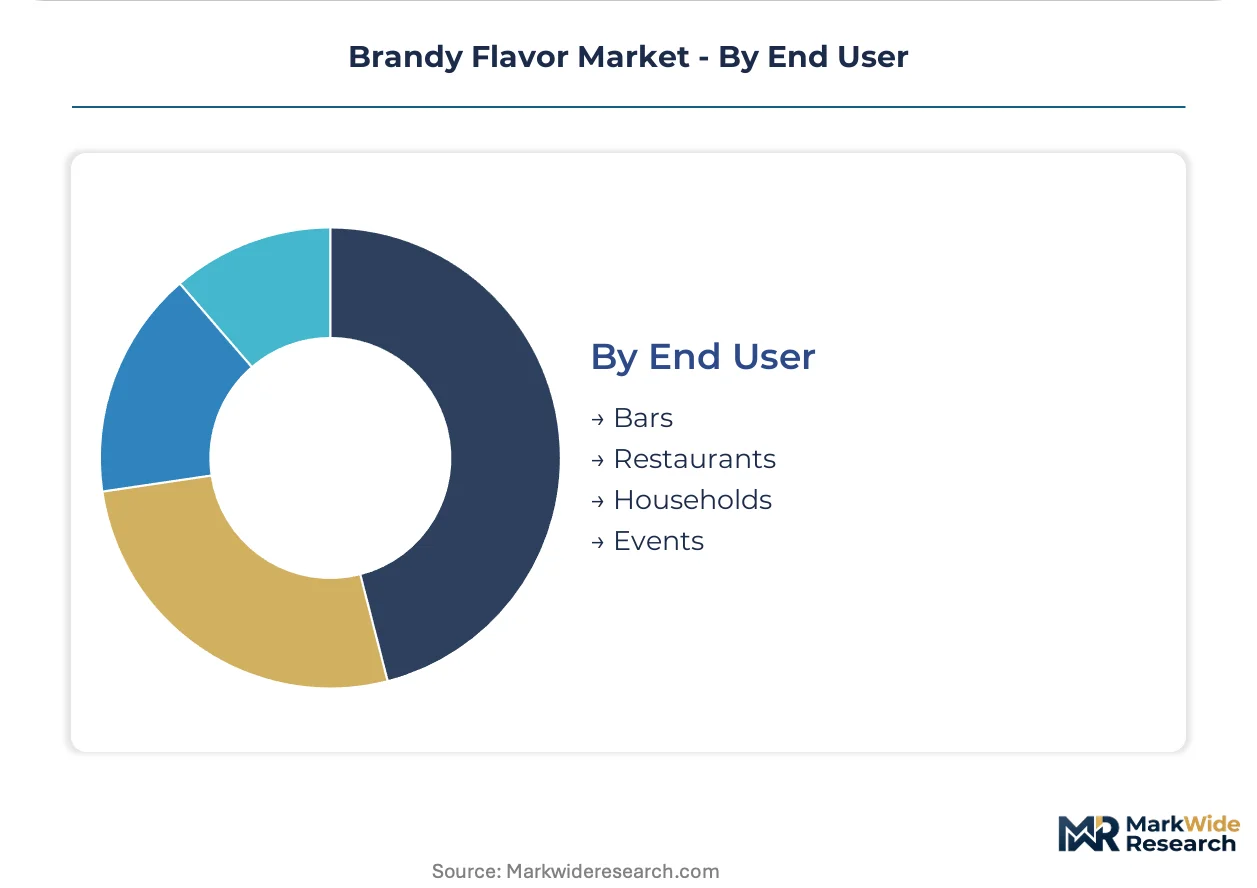
Bars anchor the highest-margin tier, with restaurants showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flavor chemist concentrations in Cognac and the Rhine-Ruhr corridor anchor European technical capabilities. Distillery heritage clusters in southwestern France and emerging craft spirits regions in Oregon and Tasmania drive formulation demand. Regulatory divergence between EFSA and FDA protocols shapes supplier geographic specialization.
France
Cognac cooperage traditions and aged-spirit authentication standards sustain premium oak and vanilla demand. EFSA positive-list compliance under EU Regulation 1334/2008 dominates supplier qualification protocols. The Charente-Maritime cluster concentrates enzymatic synthesis R&D for lactone replication.
Germany
Bioreactor manufacturing scale and REACH registration infrastructure attract flavor house investment. ECHA substance documentation deadlines favor established players with dedicated regulatory departments. The Rhineland-Palatinate region hosts precision fermentation facilities displacing tropical extraction dependencies.
United States
Craft distiller direct procurement patterns and zero-proof cocktail expansion reshape distribution channels. FDA GRAS determinations govern market access for imported compounds. Oregon's Willamette Valley anchors bespoke extraction relationships between boutique producers and specialty suppliers.
India
Domestic compounding facility investment accelerates ahead of FSSAI additive standard enforcement. Localized can-lining specifications and purity requirements favor early entrants establishing manufacturing presence. Maharashtra's Mumbai-Pune corridor concentrates flavor import and reformulation activity.
Spain
Mixology certification programs in Barcelona and Madrid drive cocktail application growth. EU flavoring regulations align with French compliance frameworks while permitting cost-advantaged production positioning. Catalonia's beverage innovation hubs test ethanol-free carrier systems for non-alcoholic applications.
Brandy Flavor Market Competitive Environment
The competitive structure tilts toward integrated taste-and-nutrition platforms with dedicated regulatory infrastructure. Tiering separates multinational flavor houses with REACH-compliant portfolios from regional specialists and emerging biotech entrants. Strategic moves concentrate on enzymatic synthesis capacity expansion and direct craft distiller channel development.
Within the integrated platform tier, Kerry Group and Givaudan exemplify divergent specialization paths—Kerry leveraging cross-category nutrition integration, Givaudan anchoring alcoholic beverage flavor architectures. Sensient Technologies occupies a position emphasizing manufacturing scale and extraction capacity. DSM-Firmenich represents the consolidated entity archetype combining nutritional and sensory science capabilities.
| Leading Market Players |
|---|
| Kerry Group |
| Givaudan |
| Sensient Technologies |
| DSM-Firmenich |
| MANE |
| Symrise |
| Robertet |
| T. Hasegawa |
| Takasago International Corporation |
| Others |
Value Chain & Pricing Dynamics
Backward integration into enzymatic synthesis capacity anchors supply security and pricing power for established European flavor houses, insulating margin structures from Madagascar vanilla harvest volatility and French cooperage supply constraints while compressing cost positions against synthetic substitutes.
Pricing Analysis
Bundled technical service and regulatory documentation commands premium positioning against unbundled commodity formulations. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant oak lactone concentrates from synthetic vanillin alternatives. Cost compression in mass-market fruit esters is intensifying because natural extract authentication mandates raise formulation overhead. Household retail segments exhibit highest price sensitivity; Michelin-tier restaurant channels absorb premium positioning for provenance-verified variants.
Supply Chain Analysis
Single-source vulnerability sits with Madagascar for vanilla bean feedstock and southwestern France for aged-spirit precursor authentication. Bioreactor production in Germany and the Netherlands draws from sugar feedstock and precision fermentation platforms, reducing tropical agricultural dependency. Tariff exposure on Indonesian oak chip imports threatens wood-derived phenolic extract economics. Distribution runs through direct procurement relationships between craft distillers and specialty suppliers, bypassing traditional broadline distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in brandy flavor rests on enzymatic synthesis cost curves flattening against natural extraction, while premium cocktail programs shift volume toward higher-margin oak and vanilla architectures.
For Market Incumbents: Hedge against synthetic substitution by deepening captive bioreactor capacity in Rhineland-Palatinate and securing REACH registration consortia positions for niche lactone compounds. Channel control through direct technical service relationships with Barcelona and Paris bar programs protects pricing power against emerging biotech entrants. For New Entrants and Emerging Players: FSSAI alignment in India opens a window for domestic compounding facility investment ahead of multinational establishment. Zero-proof cocktail formulations in Spain present the most penetrable application segment; commission ethanol-free carrier system development with Catalonia beverage innovation hubs to bypass incumbent ethanol-based formulation lock-in. For Investors and Strategic Acquirers: Roll-up economics work for mid-sized European flavor houses with REACH-compliant portfolios because regulatory documentation depth creates acquisition synergies through shared toxicology study pools. Watch enzymatic synthesis yield improvements as the inflection signal for synthetic-natural cost parity.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Synthesis Capacity Expansion | Bioreactor investment in Germany decouples production from Madagascar vanilla harvest cycles. |
| REACH Registration Consortium Formation | Shared toxicology costs preserve market access for smaller houses under ECHA deadlines. |
| Direct Craft Distiller Channel Development | Bypassing distributors captures technical service premiums in Oregon and Tasmania. |
| India FSSAI-Aligned Domestic Compounding | Localized production ahead of additive standard enforcement secures first-mover positioning. |
| Zero-Proof Cocktail Formulation R&D | Ethanol-free carrier systems expand addressable market beyond traditional spirits applications. |
Study Parameters
Direct dialogue with flavor chemists, regulatory affairs directors at European flavor houses, procurement leads at Cognac cooperages, and mixology program managers in Barcelona and Paris combined with secondary validation against EFSA positive list databases, REACH registration filings, FSSAI additive standards, and customs trade data. Bottom-up segment sizing triangulated against top-down industry revenue estimates across the analysis window.
Segment-level projections incorporate product type splits across vanilla, oak, fruit, and spice variants; application concentration in cocktails, cooking, baking, and infusions; packaging format adoption; and end-user procurement sophistication. CAGRs derived from elasticity-adjusted volume trajectories and price evolution assumptions, with enzymatic synthesis penetration rates and regulatory approval timelines as key industry-specific inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA evaluation timeline extensions, Madagascar vanilla harvest disruptions, or accelerated synthetic substitution in mass-market tiers. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Brandy Market
Alcoholic Beverages
Woozy Bottle Market
Alcoholic Beverages
Stout Market
Alcoholic Beverages
Cigar and Cigarillos Market
Alcoholic Beverages
Bahrain Alcoholic Beverages Market
Alcoholic Beverages
Whey Based Vodka Market
Alcoholic Beverages
Tequila Market
Alcoholic Beverages
Alcoholic Tea Market
Alcoholic Beverages
Beer Stabilizers Market
Alcoholic Beverages
Coffee Beer Market
Alcoholic Beverages
Global Soju Market
Alcoholic Beverages
US Alcohol E-Commerce Market
Alcoholic Beverages
North America Mezcal Market
Alcoholic Beverages
Ethyl Alcohol (Ethanol) Market
Alcoholic Beverages
Pre-Mixed/RTD Alcoholic Drinks Market
Alcoholic Beverages
Electrolyte Beer Market