
 Global Liquor Confectionery Market | 2026-2036
Global Liquor Confectionery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Liquor Confectionery Market Foresight
Gift buyers and travel retail consumers is reorganizing demand patterns across the liquor confectionery sector. Ferrero leverages its European manufacturing footprint to supply duty-free channels with premium assortments. Lindt & Sprüngli anchors its position through Swiss chocolate expertise paired with aged spirit infusions. Godiva competes in the gifting segment with boxed collections that emphasize artisanal liquor pairings.
Liquor confectionery denotes chocolate, candy, or gel-based products containing distilled spirits or liqueurs at concentrations typically below five percent alcohol by weight, manufactured through enrobing, shell molding, or injection processes to preserve volatile flavor compounds. The primary commercial purpose centers on premium gifting, travel retail impulse purchases, and adult-oriented indulgence occasions distinct from mainstream confectionery. Chocolates dominate value generation due to higher per-unit pricing and established consumer willingness to pay for cocoa-liquor combinations. Gummies represent the fastest-expanding format as producers experiment with tequila and vodka infusions targeting younger adult demographics. Whiskey and rum flavor profiles command the deepest margin pools, reflecting barrel-aged complexity that justifies premium positioning over neutral spirits.
FDA oversees alcohol content disclosure and labeling accuracy for products entering the United States, while EFSA harmonizes additive safety assessments across EU member states and REACH governs chemical migration limits from packaging into confectionery. Japan's Ministry of Health, Labour and Welfare enforces strict ethanol thresholds that shape product formulation for Asian export batches. Stakeholders must monitor evolving excise tax treatments of alcohol-containing foods in multiple jurisdictions, as reclassification could abruptly alter cost structures and channel eligibility.
Market Dynamics
EU alcohol labeling rules under EFSA and the EU Green Deal are tightening ingredient disclosure and sustainable packaging mandates, forcing reformulation across the supply chain. This regulatory compression intersects with premium gifting demand to create a bifurcated market structure.
Growth Catalysts
- Travel retail channel expansion:Duty-free operators in Germany and Japan are allocating expanded shelf space to boxed liquor chocolate assortments, driving impulse purchase frequency among transit passengers.
- REACH-compliant packaging innovation:Chemical migration limits from packaging into confectionery are accelerating adoption of barrier-coated paper and mono-material films that preserve volatile spirit flavor compounds.
- Gummy format experimentation:Producers are injecting tequila and vodka infusions into gel-based matrices, capturing younger adult demographics seeking novel texture-alcohol combinations.
Market Restraints
- Cocoa butter price volatility:Input cost swings for cocoa mass and cocoa butter compress margin pools for premium enrobed products, particularly affecting small-batch producers dependent on single-origin sourcing.
- Excise tax reclassification risk:Multiple jurisdictions are reviewing alcohol-containing food classifications, threatening abrupt cost structure disruption if products cross ethanol concentration thresholds triggering beverage taxation.
- Flavor compound stability limits:Volatile whiskey and rum aromatics degrade during thermal processing, constraining shelf life and geographic distribution radius for non-refrigerated channels.
Strategic Opportunities
- Japanese regulatory arbitrage:Ethanol thresholds enforced by Japan's Ministry of Health, Labour and Welfare create formulation expertise that transfers to other Asian markets with similarly strict limits.
- CSRD-aligned sustainable packaging:The EU Corporate Sustainability Reporting Directive creates procurement preference for confectionery suppliers demonstrating verified carbon footprint reduction across chocolate-liquor supply chains.
- E-commerce gifting platforms:Direct-to-consumer channels bypass traditional retail slotting fees, enabling artisanal producers to reach occasion-based buyers with customizable boxed collections.
Industry Challenges
- Confectionery-alcohol formulation expertise scarcity:The intersection of shell molding precision and spirit infusion chemistry requires specialized technicians, creating recruitment bottlenecks for scaling production.
- Multi-jurisdiction compliance synchronization:FDA alcohol content disclosure rules, EFSA additive assessments, and Japanese ethanol thresholds demand parallel certification tracks that extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Liquor Confectionery Market |
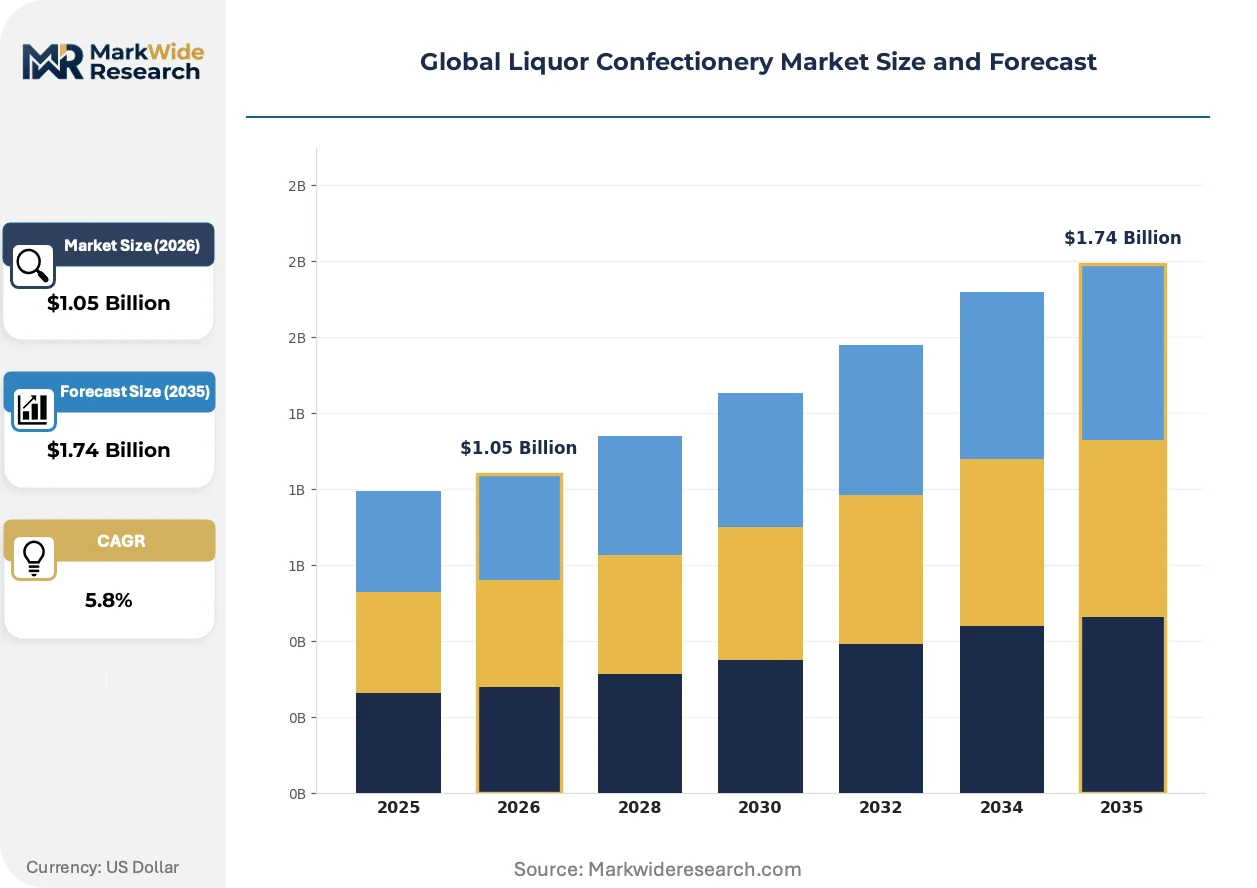
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.74 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Candy, Chewy Candy, Chocolates, Gummies, Lozenges, Jellies Flavor Profile: Rum, Whiskey, Brandy, Vodka, Tequila, Gin Packaging Type: Blister Packs, Boxes, Tins, Pouches, Wrappers, Bulk Containers Sales Channel: Supermarkets & Hypermarkets, Convenience Stores, Online Retailers, Specialty Stores, Duty-Free Shops, Wholesale Distributors |
| Companies Covered | Ferrero, Mars, The Hershey Company, Mondelez International, Neuhaus, Toms Gruppen, Lindt & Sprüngli, Godiva, Abtey Chocolate Factory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Liquor Confectionery Market Shifts & Advancements
Microencapsulation technologies and sustainable barrier materials are actively reshaping how volatile spirit flavors survive manufacturing thermal stress and shelf storage. These technical advances intersect with regulatory pressure to redefine competitive capability requirements.
Flavor microencapsulation using lipid-based wall systems is fragmenting traditional enrobing-dominated production methods. Mid-tier producers in the United States are adopting spray-dried spirit concentrates at accelerating pace to reduce alcohol content while preserving sensory intensity. This technology is fragmenting established supply relationships between distilleries and confectioners as flavor houses capture intermediate value.
REACH chemical migration limits and the EU Green Deal packaging mandates are compelling substrate transitions across European manufacturing. Industrial consequence includes accelerated R&D spend on cellulose-based barriers that prevent ethanol and ester loss to paper fibers. Premium boxed collections distributed through German travel retail channels are most affected, with several operators now requiring supplier sustainability scorecards as procurement gatekeepers.
Occasion-based purchasing through digital gifting platforms is compressing traditional seasonal sales concentration. Corporate procurement teams and individual celebration buyers are migrating toward subscription-box models that replace single-transaction retail purchases. This behavioral shift is most visible in United States urban markets where same-day delivery infrastructure supports impulse-driven adult indulgence occasions.
Global Liquor Confectionery Market Segmentation
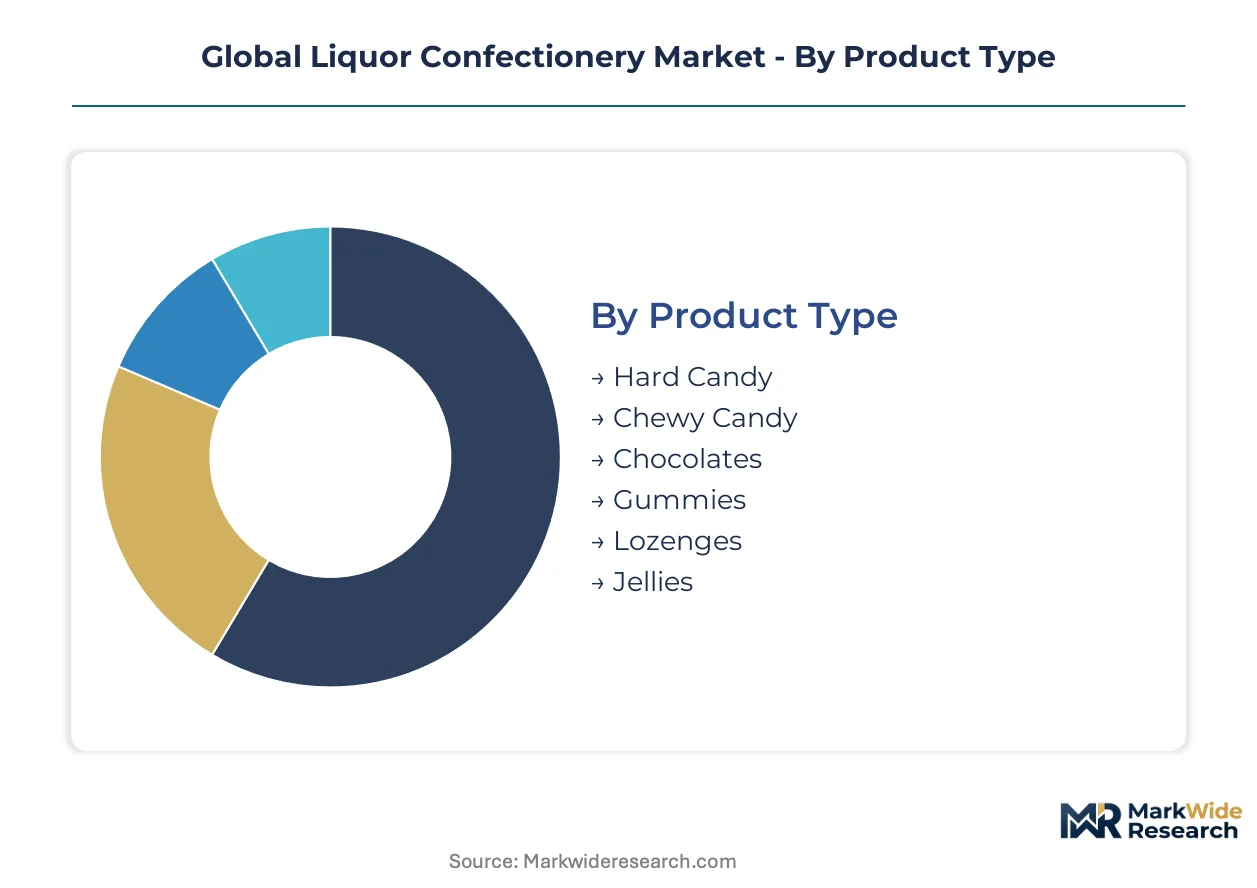
Liquor confectionery segmentation reveals how product format, flavor chemistry, and packaging economics interact with channel access rules. Distinct margin profiles emerge across segments based on alcohol concentration thresholds and thermal processing requirements.
Product Type:
Channel economics favor formats with extended ambient shelf stability and compact cubic efficiency for air freight.
- Chocolates:Enrobed and shell-molded cocoa matrices carry barrel-aged spirits at premium price points. German travel retail and Japanese department store channels concentrate demand for boxed assortments featuring whiskey and rum infusions.
- Gummies:Gelatin or pectin matrices enable tequila and vodka experimentation with lower thermal degradation risk. Younger adult demographics in United States urban markets drive volume through novelty-seeking trial.
- Hard Candy:High-boiled sugar glasses suspend alcohol at precise concentrations for extended stability.
- Chewy Candy:Aerated or pulled sugar matrices require moisture barriers to prevent spirit evaporation.
- Lozenges:Compressed tablet formats suit medicinal-positioned brandy or herbal liqueur combinations.
- Jellies:Pectin-set fruit bases accommodate lower-alcohol wine and vermouth infusions.
By volume, Chocolates leads. By growth pace, Gummies is climbing the fastest.
Flavor Profile:
Cost tier stratification follows barrel complexity and raw spirit procurement economics rather than neutral alcohol commodity pricing.
- Whiskey:Oak-derived vanillin and lactone compounds justify premium positioning through aged complexity. United States bourbon and Scotch whisky variants command deepest margin pools in gift-box channels.
- Rum:Molasses fermentation esters deliver tropical positioning flexibility. Caribbean-sourced distillates penetrate duty-free Caribbean and Latin American transit corridors.
- Brandy:Grape distillate bases align with European chocolate traditions and EFSA additive compliance frameworks.
- Vodka:Neutral spirit profiles minimize flavor interference but require higher concentrations for sensory impact.
- Tequila:Agave terroir positioning targets experiential gifting occasions in North American markets.
- Gin:Botanical complexity demands careful thermal protection of volatile terpenes during enrobing.
By revenue concentration, Whiskey dominates. By expansion trajectory, Tequila is gaining share fastest.
Packaging Type:
REACH chemical migration limits and EU Green Deal mandates are forcing substrate transitions that reshape procurement specifications.
- Boxes:Rigid paperboard structures with barrier coatings preserve volatile aromatics for premium gifting. German retailers now require supplier sustainability scorecards as procurement gatekeepers.
- Tins:Metal substrates offer complete ethanol and ester impermeability for extended ambient distribution.
- Blister Packs:Thermoformed plastic cavities suit individual portion control in travel retail.
- Pouches:Flexible films optimize cubic efficiency for e-commerce fulfillment.
- Wrappers:Single-serve foil laminates dominate impulse channels.
- Bulk Containers:Industrial totes serve foodservice and repackaging operations.
By procurement volume, Boxes leads. By sustainability-driven substitution rate, Pouches is expanding most quickly.
Sales Channel:
Margin structure varies sharply by slotting fee burden, excise tax exposure, and temperature control requirements.
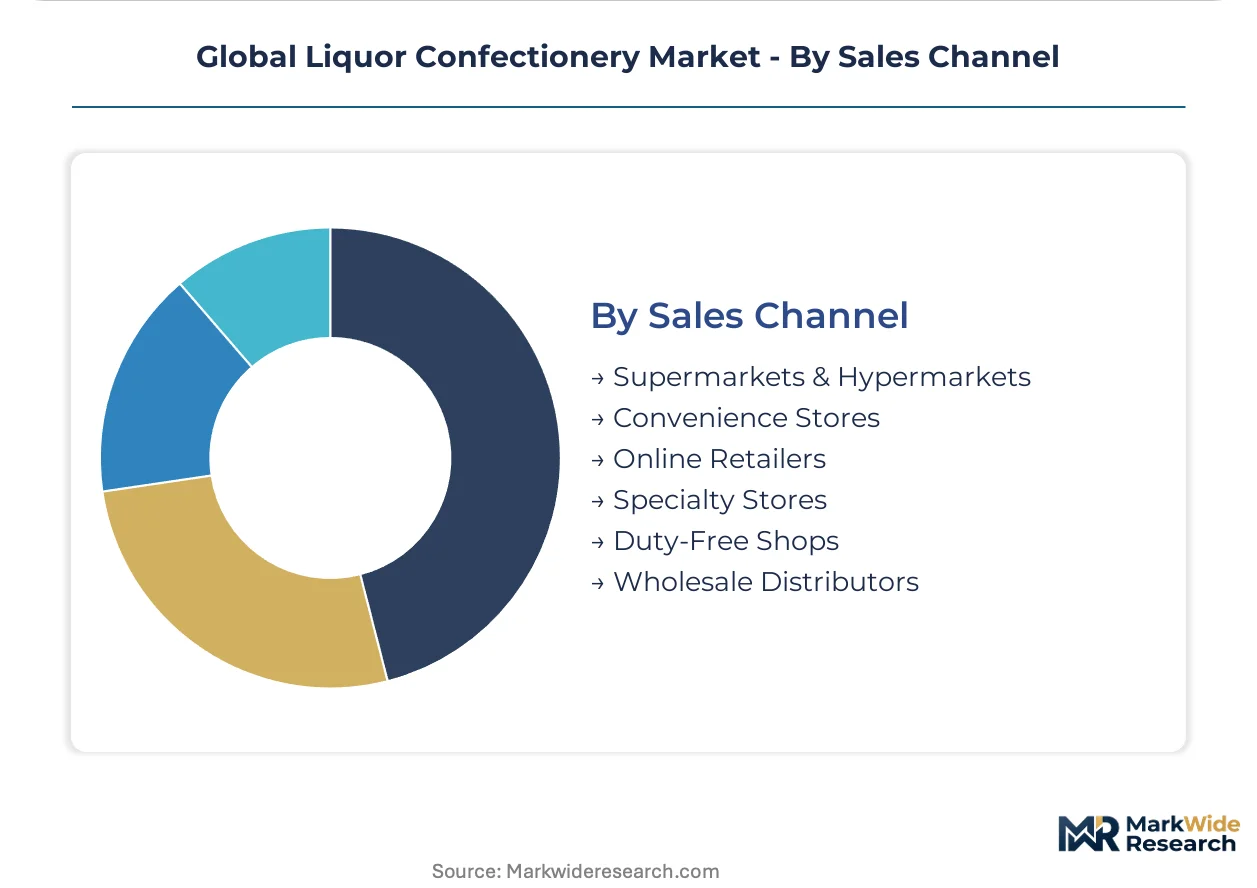
- Duty-Free Shops:Transit retail environments capture impulse purchase frequency with extended dwell time. Operators in Germany and Japan allocate expanded shelf space to boxed assortments with proven velocity.
- Online Retailers:Direct-to-consumer platforms bypass traditional retail slotting fees and enable customizable collections. Same-day delivery infrastructure in United States urban markets supports occasion-based adult indulgence.
- Supermarkets & Hypermarkets:Mass retail channels demand volume pricing and standardized assortment breadth.
- Convenience Stores:Grab-and-go positioning favors single-serve formats with immediate consumption intent.
- Specialty Stores:Curated selection and staff expertise justify premium price realization.
- Wholesale Distributors:B2B intermediaries serve hospitality and corporate gifting accounts with volume tiering.
By revenue per square meter, Duty-Free Shops leads. By customer acquisition efficiency, Online Retailers shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters for liquor confectionery concentrate in jurisdictions with established chocolate heritage and permissive alcohol-in-food regulatory frameworks. Distinctive demand patterns emerge across major economies where gifting culture and travel retail infrastructure intersect.
Germany
Duty-free operators at Frankfurt and Munich airports command premium shelf placement for boxed whiskey-chocolate assortments. EFSA harmonizes additive safety assessments across EU member states while REACH governs chemical migration limits from packaging. Cologne and Hamburg harbor industrial chocolate processors supplying travel retail channels across the continent.
United States
Bourbon-infused chocolate lines capture corporate gifting volume through e-commerce platforms with same-day delivery infrastructure. FDA oversees alcohol content disclosure and labeling accuracy for interstate commerce. Pennsylvania and Illinois host large-scale confectionery manufacturing campuses serving both domestic retail and export batches.
Japan
Department store basements in Tokyo and Osaka sustain year-round demand for precision-crafted rum chocolate collections. The Ministry of Health, Labour and Welfare enforces strict ethanol thresholds that shape product formulation for domestic consumption and regional export. Hokkaido dairy-chocolate clusters supply premium ingredients to Tokyo-based finishing operations.
Switzerland
Swiss chocolate expertise paired with aged spirit infusions anchors ultra-premium positioning in Asian duty-free corridors. Swissmedic regulates novel food ingredients while maintaining alignment with EFSA frameworks. Zurich and Geneva house specialized enrobing facilities serving global luxury retail accounts.
United Kingdom
Gin-botanical chocolate experimentation targets experiential gifting occasions in London and Manchester urban markets. Post-Brexit regulatory divergence from EU additive approvals creates parallel certification tracks for export batches. Birmingham and York retain historical confectionery manufacturing infrastructure now repurposed for premium liquor-infused lines.
Global Liquor Confectionery Market Competitive Landscape
Concentration sits with diversified confectionery conglomerates holding integrated cocoa supply chains and established duty-free relationships. Mid-tier specialists compete through flavor innovation and regional gifting expertise. Three archetypes dominate: heritage European chocolatiers with distillery partnerships, scale-driven multinationals with global distribution networks, and artisanal producers leveraging direct-to-consumer channels. Competitive moves center on sustainable packaging certification and microencapsulation technology licensing.
Within the heritage chocolatier tier, Lindt & Sprüngli and Godiva exemplify Swiss and Belgian chocolate expertise applied to spirit infusion. Ferrero anchors the scale-driven multinational segment with European manufacturing footprints optimized for travel retail supply. These three entities represent distinct competitive vectors: precision enrobing heritage, luxury gifting positioning, and operational scale across diversified confectionery portfolios.
| Leading Market Players |
|---|
| Ferrero |
| Mars |
| The Hershey Company |
| Mondelez International |
| Neuhaus |
| Toms Gruppen |
| Lindt & Sprüngli |
| Godiva |
| Abtey Chocolate Factory |
| Others |
Supply & Pricing Matrix
Ninety-day cocoa butter inventory cycles at European processors concentrate margin pressure on artisanal producers lacking forward-contract coverage. This lead-time exposure intersects with EFSA additive compliance costs to stratify pricing power across the value chain.
Pricing Analysis
REACH chemical migration limits dictate the pricing tier structure across liquor confectionery packaging substrates. Three-tier pricing structure across premium, standard, and economy levels separates Swiss enrobed assortments from mid-tier gummy lines and mass-market hard candy. Price differentiation hinges on certification grade and volume scale, with CSRD-aligned sustainability scorecards commanding procurement preference from German travel retail operators. Pricing pressure stems from cocoa butter price volatility, compressing margin pools for single-origin dependent producers. Corporate gifting buyers exhibit lowest price sensitivity, while convenience store impulse purchasers drive volume through economy-tier single-serve formats.
Supply Chain Analysis
Strategic stockpiling of aged spirits and cocoa mass dominates inventory strategy over just-in-time approaches due to fermentation and harvest seasonality. Manufacturing gravity centers on Switzerland, Germany, and Belgium, drawing from Caribbean rum distillates, Scottish whisky cooperages, and West African cocoa cooperatives. Supply chain risk concentrates in single-source vulnerability for premium barrel-aged spirits, with geopolitical disruption threatening aromatic compound consistency. Distribution runs through duty-free operators and direct-to-consumer platforms, bypassing traditional retail slotting fees for artisanal producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. EFSA and FDA parallel certification tracks create switching costs that protect incumbent formulation expertise from rapid competitive displacement.
For Market Incumbents: Shield proprietary enrobing techniques through patent filing on microencapsulation processes before flavor houses capture intermediate value. Deepen backward integration into cocoa cooperatives to secure single-origin supply against price volatility. Prioritize CSRD-aligned packaging certification to maintain German travel retail procurement access as sustainability scorecards harden into gatekeeping mechanisms. For New Entrants and Emerging Players: Lead with tequila-infused gummy experimentation targeting United States urban millennials through direct-to-consumer subscription models. White-space opportunity concentrates in same-day delivery gifting platforms where artisanal positioning bypasses retail slotting barriers. Penetrate Japanese regulatory arbitrage expertise for Asian market expansion, leveraging Ministry of Health, Labour and Welfare formulation compliance as competitive credential. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because microencapsulation technology licensing and distillery partnership networks concentrate capability scarcity with heritage European chocolatiers. Acquisition target archetype: mid-tier specialists holding REACH-compliant packaging innovation and established duty-free relationships. Signal to watch: excise tax reclassification debates in multiple jurisdictions crossing ethanol concentration thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Flavor houses capture intermediate value from traditional distillery-confectioner relationships. |
| CSRD-Aligned Sustainable Packaging | German travel retail operators require supplier sustainability scorecards as procurement gatekeepers. |
| Direct-to-Consumer Platform Launch | Same-day delivery infrastructure in United States urban markets supports occasion-based adult indulgence. |
| Distillery Partnership Deepening | Aged spirit procurement networks anchor premium positioning in whiskey and rum flavor profiles. |
| Japanese Regulatory Compliance Investment | Ministry of Health, Labour and Welfare expertise transfers to Asian markets with strict ethanol limits. |
Research Methodology
The analysis maps chocolate enrobing, gummy gel matrices, and hard candy sugar glasses, each validated through confectionery R&D directors, travel retail category buyers, and distillery technical partners. Primary interviews with brand managers, supply planners at cocoa processors, and channel sales heads at duty-free operators combined with secondary validation from EFSA additive assessments, FDA labeling guidance, and REACH chemical migration databases. Bottom-up volume triangulation against top-down value estimates anchored segmentation outputs.
Consistency checks against customs trade data and Nielsen retail audit benchmarks validated projection outputs across the analysis window. The analytical framework modeled product format, flavor chemistry, packaging substrate, and sales channel dimensions alongside regional regulatory cluster variations. CAGRs derived from historical trajectory analysis adjusted for excise tax reclassification risk and sustainable packaging mandate acceleration. Cocoa butter futures curves and barrel-aged spirit procurement indices fed industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside stable ethanol classification thresholds and intact travel retail infrastructure would require recalibration. Forecasts reflect assumptions regarding EFSA harmonization continuity and Japanese regulatory alignment persistence. Revision becomes warranted when excise tax reclassification crosses beverage taxation thresholds in multiple jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Europe Wine Market
Alcoholic Beverages
Bahrain Alcoholic Beverages Market
Alcoholic Beverages
Wine Cork Market
Alcoholic Beverages
South America Alcoholic Beverages Market
Alcoholic Beverages
North America Alcoholic Beverages Market
Alcoholic Beverages
Fruit Beer Market
Alcoholic Beverages
Cannabis-Based Alcoholic Beverages Market
Alcoholic Beverages
Decanter Market
Alcoholic Beverages
Europe Wine Coolers Market
Alcoholic Beverages
Alcohol-Free Pineapple Beer Market
Alcoholic Beverages
Woozy Bottle Market
Alcoholic Beverages
Wine Enzymes Market
Alcoholic Beverages
Non-Fuel Grade Alcohol Market
Alcoholic Beverages
North America Soju Market
Alcoholic Beverages
Alcoholic Ice Cream Market
Alcoholic Beverages
United States Beer Market