
 Wine Cork Market | 2026-2036
Wine Cork Market Size, Share, and Industry Trends Forecast 2026-2036
Wine Cork Market Intelligence
The rising preference for screw caps in the high-volume, ready-to-drink wine category is restructuring the traditional market for natural corks. Corticeira Amorim leverages its vast cork oak forest assets to dominate the natural cork supply chain. Jelinek Cork Group specializes in a diverse range of cork products beyond just wine stoppers, serving multiple industrial applications. Meanwhile, A. Silva USA competes by offering advanced TCA-free guaranteed corks for the premium North American market.
A wine cork is a stopper used to seal wine bottles, traditionally manufactured from the bark of the cork oak tree, Quercus suber. The material’s unique cellular structure provides the elasticity and low permeability essential for preserving wine quality and enabling controlled micro-oxygenation during aging. Natural corks command the premium end of the market due to superior aging properties. In contrast, agglomerated and technical corks offer a cost-effective solution for wines intended for earlier consumption, representing a high-volume product segment.
Regulations for food-contact materials enforced by bodies like the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) govern material composition. China’s GB standards also set strict requirements for imported stoppers. These rules ensure that stoppers do not leach harmful substances or undesirable flavors into the wine. Producer decisions on closure type will increasingly balance material science advancements against consumer perceptions of quality and sustainability.
Market Dynamics
The central structural force shaping the wine cork market is the bifurcation of demand between premium wineries prioritizing natural cork for aging and brand image, and high-volume producers adopting alternative closures for cost efficiency and consistency in ready-to-drink wines.
Growth Catalysts
- Premiumization in Wine:The global trend towards premium and ultra-premium wines, which rely on natural cork for optimal aging and perceived quality, directly fuels demand for high-grade natural and technical cork stoppers.
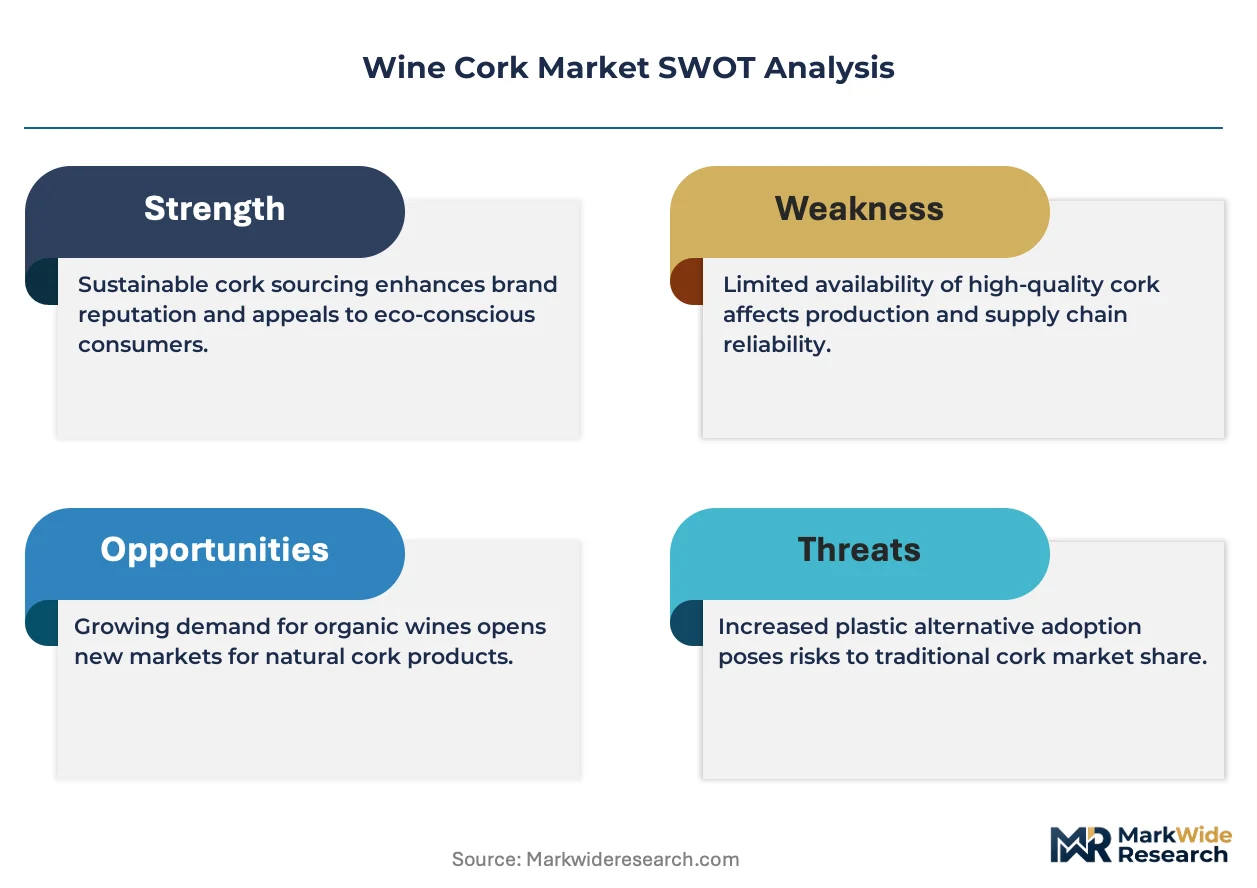
- Sustainability Mandates:European Union directives promoting circular economy principles and bio-based materials favor cork, a renewable and biodegradable resource, over petroleum-derived synthetic stoppers, influencing producer choices.
- New World Viticulture Expansion:Growth in wine production within Australia, Chile, and South Africa creates new, high-volume demand for a full range of cork products, from agglomerated stoppers to premium natural corks.
Market Restraints
- Alternative Closure Competition:Screw caps and synthetic stoppers present a significant substitution threat, having captured substantial share in the entry-level and mid-range wine segments due to lower costs and absence of TCA risk.
- Geographic Supply Concentration:The world’s cork oak forests are heavily concentrated in Portugal and Spain, making the raw material supply chain vulnerable to localized climate change impacts, disease, and labor issues.
- Perception of Faults:Despite technological advances in TCA detection, the lingering perception of "cork taint" remains a barrier for some winemakers, who opt for alternative closures to guarantee product consistency.
Strategic Opportunities
- Technical Corks for Sparkling Wine:Developing advanced, high-performance technical corks specifically engineered for the high-pressure environment of sparkling wines offers a significant growth avenue beyond still wines.
- Expansion in Emerging Wine Markets:Targeting the growing wine consumer base in China and other Asian markets provides an opportunity to establish natural cork as the premier closure choice as consumer preferences are being formed.
- Certified Sustainability Programs:Promoting and expanding Forest Stewardship Council (FSC) certification for cork forests offers a powerful marketing tool to appeal to environmentally conscious consumers and wineries.
Industry Challenges
- Quality Assurance at Scale:Implementing and maintaining cost-effective, non-destructive screening technologies to guarantee every individual cork is free from sensory defects like TCA remains a major operational challenge for suppliers.
- Harvesting Labor Scarcity:The manual, skilled labor required for debarking cork oak trees is diminishing in traditional regions like Portugal, posing a long-term threat to raw material harvesting capacity and cost.
- Navigating Global Food Safety Norms:Adhering to a complex web of food-contact regulations, including standards from the FDA in the US, EFSA in Europe, and China's GB standards, requires significant compliance investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wine Cork Market |
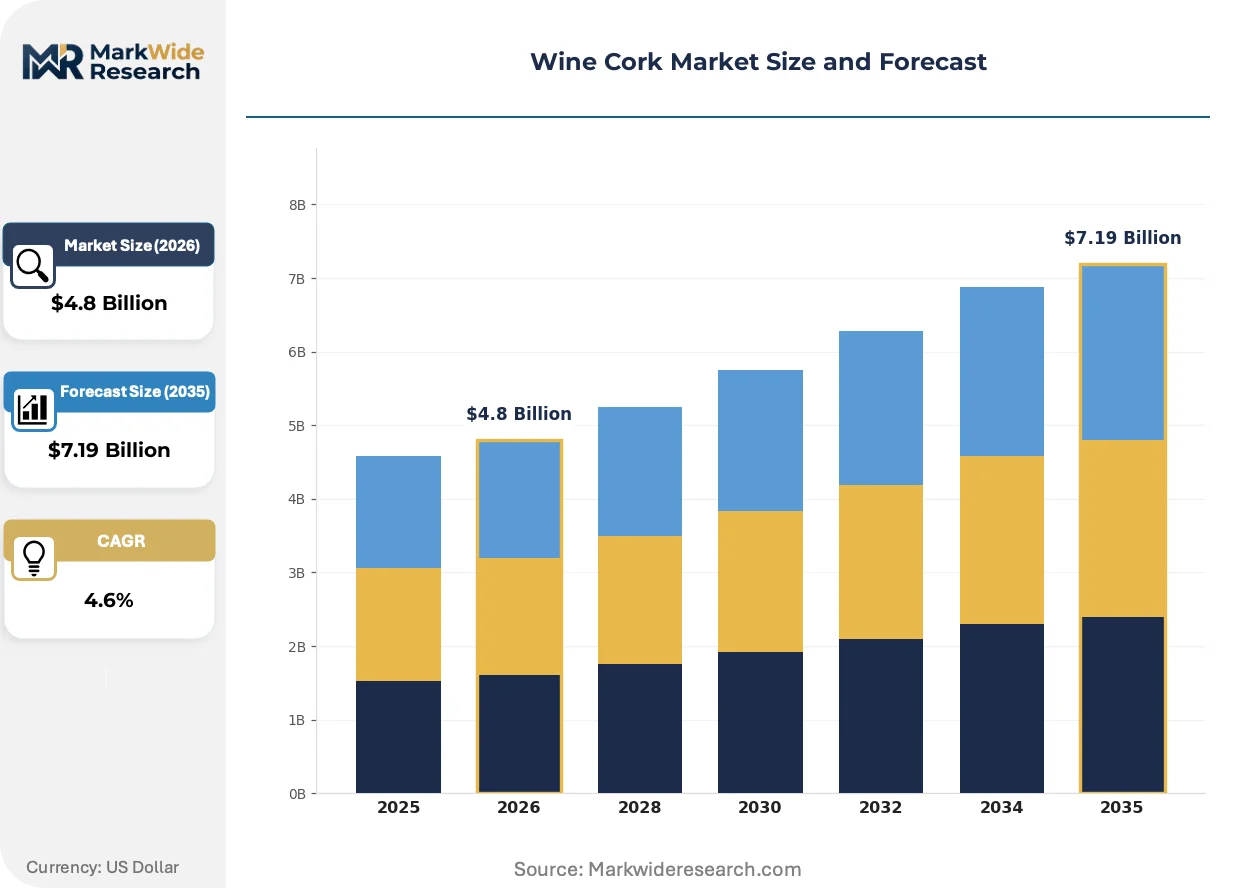
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Cork, Synthetic, Screw Cap, Glass Product Type: Natural Corks, Agglomerated Corks, Technical Corks, Composite Corks End User: Winery, Retail, Distributor, Importer Size: Standard, Long, Mini, Custom |
| Companies Covered | Precisionelite, We Cork, Corticeira Amorim, Zandur, Widgetco, Jelinek Cork Group, Waterloo Container Company, C. Ribeiro, A. Silva USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wine Cork Market Strategic Shifts & Innovations
Material science is driving a significant evolution in product offerings, allowing cork to compete on performance and consistency in segments previously lost to alternatives. These innovations are intersecting with a growing demand for verifiable sustainability, reshaping procurement criteria for wineries globally.
Advanced technical corks, which utilize purified micro-granules and food-safe binders, provide a TCA-free and consistent sealing solution. Wineries producing mid-tier and premium-by-the-glass wines are rapidly adopting these products for their predictable performance. This category of engineered stoppers is overtaking traditional agglomerated corks in quality-sensitive applications where natural cork's cost is prohibitive.
European Food Safety Authority (EFSA) regulations governing food-contact materials are becoming increasingly stringent, emphasizing consumer safety and material traceability. This regulatory pressure forces manufacturers to validate the safety of all components, from cork particles to adhesives in technical stoppers. The premium wine segment is most affected, as producers leverage compliance with these high standards as a mark of quality.
A notable behavioral shift is visible in how large winery consortiums approach closure purchasing, moving away from transactional orders toward long-term supply agreements with performance guarantees. This trend disrupts the conventional role of smaller, regional distributors, as major producers now work directly with global cork manufacturers to co-develop specifications. This direct-sourcing model is most prominent in North America and Europe.
Wine Cork Market Segmentation
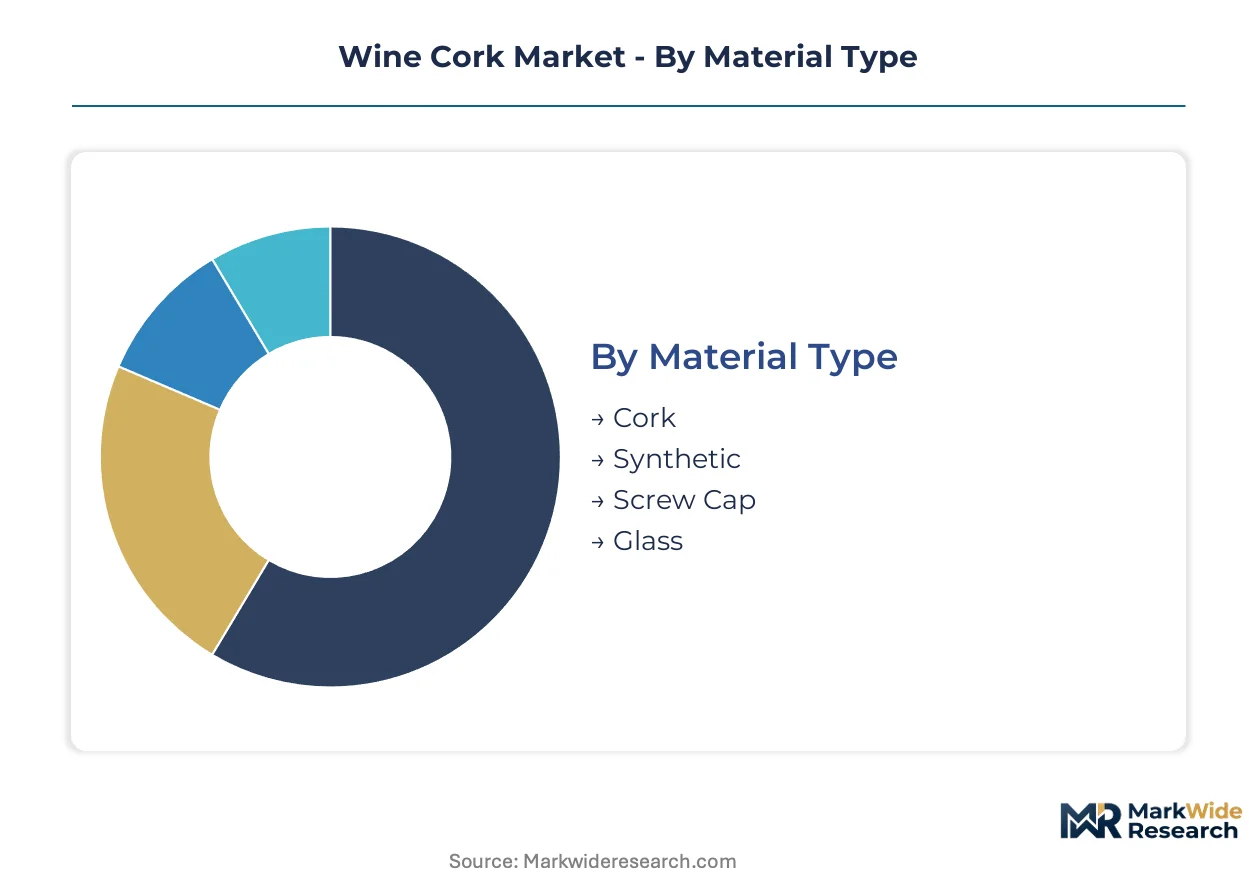
The wine cork market is segmented to understand the diverse preferences and operational requirements across the global wine industry. This segmentation highlights the critical factors influencing closure selection, from material properties to end-user needs, shaping procurement strategies for wineries worldwide.
Material Type:
The material type segmentation highlights how closures function, from traditional standalone stoppers to those integrated more seamlessly with bottling lines.
- Cork:Traditional closures punched from the bark of the cork oak tree, offering elasticity and controlled micro-oxygenation essential for wine aging. Demand concentrates in premium wineries across France and Italy, prioritizing natural cork for optimal maturation and brand perception.
- Synthetic:Plastic-based stoppers, typically manufactured from polyethylene, designed to replicate cork's sealing properties while eliminating the risk of TCA taint. These closures find application in entry-level wines and those intended for early consumption.
- Screw Cap:Aluminum or plastic caps with a threaded seal, providing an airtight, consistent closure with easy opening. High-volume, ready-to-drink wine categories, particularly in Australia and Chile, drive substantial adoption due to cost efficiency and absence of cork-related faults.
- Glass:Solid glass stoppers, often with an inert O-ring seal, offering an elegant, reusable, and entirely inert closure option for certain premium and specialty wines.
Cork leads volumes today; Screw Cap is gaining share fastest.
Product Type:
Product type differentiation reflects a spectrum of cost and performance, catering to diverse wine styles and price points.
- Natural Corks:Entirely punched from cork oak bark, these stoppers offer superior elasticity and controlled micro-oxygenation for long-term aging. Premium wineries globally, especially in Europe, prioritize natural corks for their heritage and quality attributes.
- Agglomerated Corks:Made from granulated cork particles bound together with food-safe adhesives, providing a cost-effective sealing solution for wines intended for earlier consumption. These are widely used in high-volume, value-oriented wine segments.
- Technical Corks:Engineered stoppers featuring a natural cork body with purified micro-granule discs at each end, ensuring TCA-free performance and consistency. Mid-tier and premium-by-the-glass wine segments are driving adoption due to predictable sealing and quality assurance.
- Composite Corks:Combine cork granules with other materials, often synthetic or natural rubber, to achieve specific performance characteristics at a moderate price point.
Natural Corks command the highest value segments; Technical Corks are expanding most quickly.
End User:
End user segmentation reveals distinct purchasing behaviors and supply chain roles across the wine industry ecosystem.
- Winery:Direct purchasers of corks for bottling their wines, making closure decisions based on wine style, aging potential, and brand positioning. Large winery consortiums in North America and Europe increasingly engage in direct, long-term supply agreements with manufacturers.
- Retail:Outlets selling wine, influencing consumer perception of closure types and sometimes purchasing corks for in-store bottling or promotional activities. Retailers often stock wines with closures appealing to broad consumer preferences.
- Distributor:Intermediaries purchasing corks from manufacturers and supplying them to smaller wineries or retailers, managing inventory and logistics. Regional distributors play a crucial role in reaching diverse, localized wine producers who lack direct procurement channels.
- Importer:Businesses facilitating the entry of corks into new markets, navigating international trade regulations and local distribution networks. Importers manage compliance with standards like China's GB standards for imported stoppers.
Wineries represent the primary demand source; Distributors facilitate broad market access.
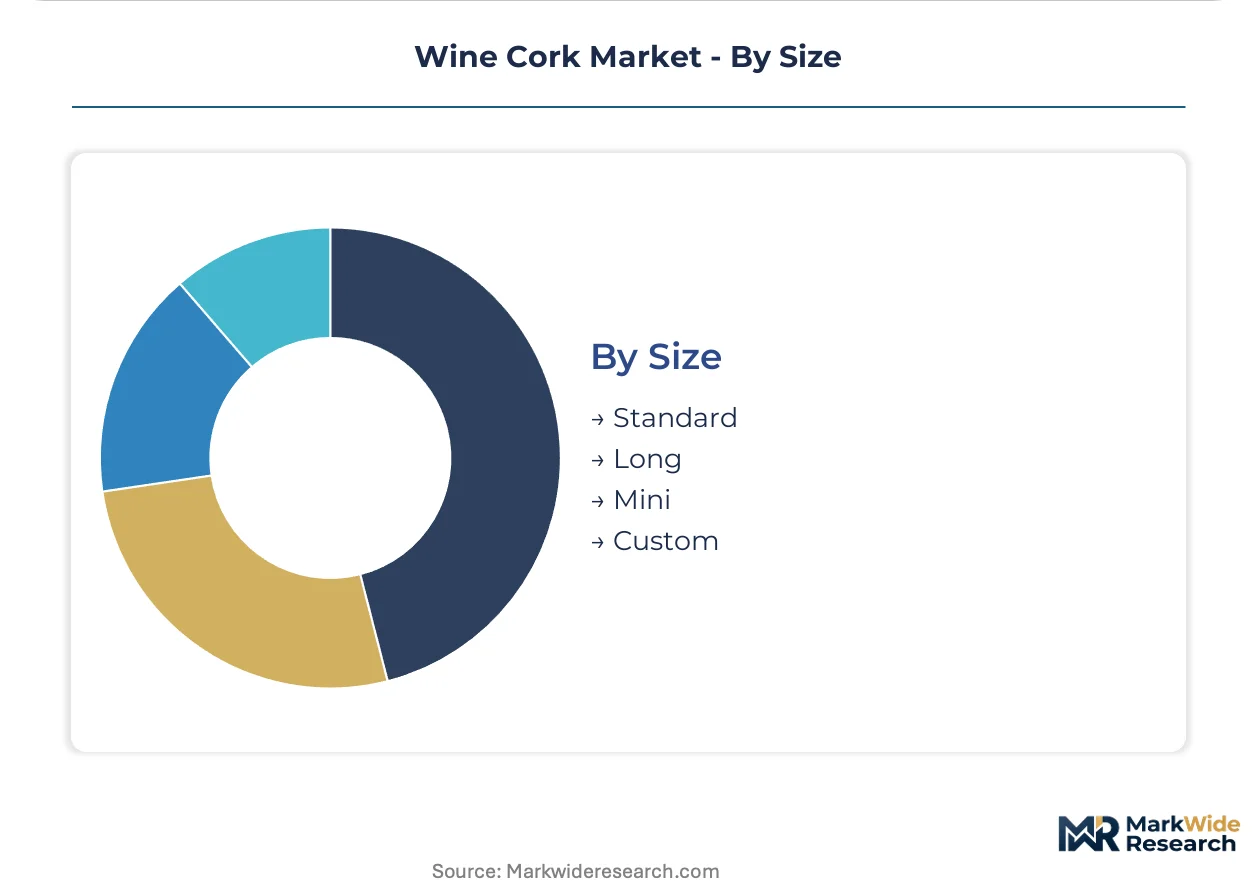
Size:
The size category reflects the volume-driven requirements and specialized applications within wine bottling.
- Standard:The most common cork length, typically used for still wines intended for consumption within a few years, balancing sealing performance with cost efficiency. Global wine production utilizes standard sizes for a vast majority of its output.
- Long:Longer corks, often 49mm or 54mm, preferred for premium wines designed for extended aging, providing a more robust and enduring seal. Premium wineries in traditional regions like Bordeaux and Tuscany frequently specify long corks.
- Mini:Shorter corks used for smaller format bottles or specific wine types, optimizing material use for niche products. These are often found in single-serve or specialty wine packaging.
- Custom:Tailored cork dimensions and finishes, often for luxury wines or unique bottle designs, emphasizing brand exclusivity and aesthetic appeal.
Standard corks dominate production volumes; Long corks maintain premium segment preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory distinctions shape the global wine cork market, influencing where production is incentivized or constrained by compliance costs. These variations create a nuanced landscape for sourcing and distribution across key viticulture regions. Wineries navigate diverse food safety and environmental mandates when selecting closures.
France
Premium wineries in France maintain strong demand for natural corks, emphasizing their role in optimal wine aging. The EU Green Deal encourages the use of sustainable, bio-based materials like cork, aligning with national environmental goals. Bordeaux's renowned châteaux consistently prioritize high-grade natural corks for their heritage wines.
Italy
Italian viticulture, with its deep traditions, drives consistent demand for natural corks across its diverse wine regions. EFSA regulations for food-contact materials ensure rigorous safety standards for all wine stoppers used in the country. Tuscany's prestigious wineries often specify long natural corks for their long-aging red wines.
Portugal
Portugal, as the world's leading cork producer, focuses on sustainable forest management and raw material supply. EU directives promoting circular economy principles reinforce cork's position as a preferred renewable resource. The Alentejo region, home to vast cork oak forests, drives significant harvesting and processing activities.
Australia
New World viticulture in Australia shows a bifurcated demand, with premium segments using natural cork and high-volume wines adopting screw caps. TGA (Therapeutic Goods Administration) standards for food safety indirectly influence material choices for wine closures. The Barossa Valley, a significant wine-producing region, balances traditional and alternative closure preferences.
Chile
Chilean wine production, known for its export focus, exhibits growing demand for consistent and cost-effective closures. Local food safety regulations ensure that all imported and domestically produced stoppers meet acceptable standards. The Central Valley, Chile's primary wine region, utilizes a range of cork products for its diverse wine portfolio.
Wine Cork Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting the diverse needs of the wine industry. The market exhibits a tiered structure, with a few large players dominating natural cork supply and numerous smaller entities innovating in technical corks. Strategic archetypes include integrated forest owners, specialized closure manufacturers, and diversified cork product suppliers. Companies pursue portfolio diversification and geographic expansion to capture new opportunities.
Among the integrated forest owners, Corticeira Amorim, a Portugal-based public company, anchors the natural cork supply chain with extensive forest assets. Jelinek Cork Group, a Canadian-headquartered entity, exemplifies a diversified cork product provider, extending beyond wine stoppers to industrial applications. A. Silva USA, operating in the North American market, represents specialists focused on advanced TCA-free guaranteed corks for premium segments.
| Leading Market Players |
|---|
| Precisionelite |
| We Cork |
| Corticeira Amorim |
| Zandur |
| Widgetco |
| Jelinek Cork Group |
| Waterloo Container Company |
| C. Ribeiro |
| A. Silva USA |
| Others |
Cost & Logistics Intelligence
Premium wineries' strong demand for natural corks, driven by optimal aging and brand image, forces suppliers to invest in quality assurance, which in turn influences pricing for specialized closures. This demand-side pull shapes the market's cost structure.
Pricing Analysis
Distributor margins reflect the diverse product types, from commodity agglomerated corks to highly specialized natural stoppers. The dominant pricing model is contract-based long-term offtake for premium natural corks, with per-unit transactional pricing for high-volume segments. Price differentiation stems from quality certification and volume scale. Cost compression in the entry-level segment intensifies due to screw cap competition. Premium wineries show the least price sensitivity, prioritizing quality over cost.
Supply Chain Analysis
Direct long-term supply agreements between global cork manufacturers and large winery consortiums characterize premium segment distribution. Raw material supply heavily concentrates in Portugal and Spain, which are primary sources of cork oak bark. Production of technical corks also relies on specialized food-safe binders. This geographic concentration presents a structural risk from localized climate change impacts. Regional distributors facilitate market access for smaller, independent wineries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wine cork market functions as a stable compounder, driven by sustained global premiumization trends in wine consumption. This consistent demand for quality closures provides predictable growth opportunities across segments.
For Market Incumbents:Deepen vertical integration into cork oak forest management to secure raw material supply against future scarcity. Invest heavily in advanced TCA detection and removal technologies to mitigate the lingering perception of cork taint. This defends market share against alternative closure competition. Expand R&D into next-generation technical corks for consistent performance.
For New Entrants and Emerging Players:Launch via certified sustainability programs to appeal to environmentally conscious wineries and consumers. Target the growing wine consumer base in China, establishing natural cork as the premier closure choice. The sparkling wine segment presents a specific opportunity for advanced technical corks. Focus on mid-tier wine producers seeking guaranteed TCA-free performance and consistency.
For Investors and Strategic Acquirers:Asymmetric upside sits with specialized closure manufacturers holding strong intellectual property in material science. The market's long-term viability is anchored in cork's renewable nature and its enduring appeal for premium wines. Acquisition targets include firms innovating in advanced TCA-free technologies or possessing strategic forest assets. A key signal to watch is the accelerating adoption of technical corks in premium-by-the-glass wine segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in TCA-free screening | Guarantees product consistency, mitigating a key historical barrier for natural corks. |
| Expand FSC certification | Appeals to environmentally conscious wineries and consumers, strengthening cork's sustainability credentials. |
| Develop sparkling wine technical corks | Captures a high-growth niche requiring specialized, high-performance closure solutions. |
| Secure long-term forest concessions | Ensures stable raw material supply, reducing vulnerability to geographic concentration risks. |
| Target emerging Asian markets | Establishes natural cork as the preferred closure as new consumer preferences are formed. |
Research Approach
Bottom-up winery procurement modeling reconciled against top-down cork manufacturer supply tracking forms the analytical core of this study. Primary interviews with winery procurement managers, cork sales directors, and regional distributors provided qualitative insights. These were validated against secondary data from EFSA reports, FDA guidelines, and trade association publications. This approach ensured comprehensive data triangulation.
An input-output matrix served as the analytical framework, modeling market dynamics across the analysis window. Segmentation dimensions included material type, product type, end user, and regional regulatory distinctions. Compound annual growth rates were derived from historical trend analysis and projected demand shifts. Key forecast inputs included global wine production volumes and evolving consumer closure preferences.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant climate change impacts on cork forests or sudden shifts in food safety regulations. Forecasts reflect assumptions regarding market stability and technological evolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
South Africa Tequila Market
Alcoholic Beverages
Pinot Noir Market
Alcoholic Beverages
Alcoholic Flavors Market
Alcoholic Beverages
Wine Bags Market
Alcoholic Beverages
Brewing Supplies Market
Alcoholic Beverages
United States Tequila Market
Alcoholic Beverages
Europe Kegs Market
Alcoholic Beverages
Beer Stabilizers Market
Alcoholic Beverages
Wine Aerator Market
Alcoholic Beverages
Gin and Tonic Tea Market
Alcoholic Beverages
Cigar Market
Alcoholic Beverages
Commercial Wine Dispenser Market
Alcoholic Beverages
South America Fermented Drinks Market
Alcoholic Beverages
US Alcohol E-Commerce Market
Alcoholic Beverages
Premix Bottled Cocktails Market
Alcoholic Beverages
Wine Production Machinery Market