
 India Tequila Market | 2026-2036
India Tequila Market Size, Share, and Industry Trends Forecast 2026-2036
India Tequila Market Insights
The FSSAI's mandatory nutritional labeling expansion for imported spirits is repositioning how distributors qualify tequila for Indian retail shelves. Diageo PLC leverages its established duty-free and premium retail networks to sustain shelf visibility amid tighter compliance windows. Radico Khaitan Limited anchors its domestic agave spirits portfolio through controlled distillery partnerships in Maharashtra. D'YAVOL Spirits differentiates via celebrity-backed branding that commands premium pricing in Mumbai's nightlife circuit.
Tequila denotes a distilled spirit produced exclusively from blue agave (Agave tequilana Weber) harvested primarily in Jalisco, Mexico, with a minimum alcohol content of 35% by volume and strict denomination-of-origin protections governing its labeling. Blanco expressions dominate Indian import volumes due to lower price points and cocktail versatility, while Reposado commands widening margin pools as aged-stock positioning gains traction in Delhi and Bangalore lounges. Distribution through online platforms represents the fastest-growing channel as state-level e-commerce alcohol permissions expand, though bars and restaurants still capture the highest per-occasion spend.
FSSAI import clearance protocols, BIS certification requirements for bottled spirits, and state excise authorities in Maharashtra and Karnataka collectively shape product registration timelines and tax-included pricing structures. CDSCO-adjacent quality benchmarks for ethanol purity further filter which Mexican distilleries qualify for sustained export relationships. Stakeholders must monitor pending state excise harmonization discussions and evolving e-commerce alcohol delivery permissions to calibrate inventory and channel investments.
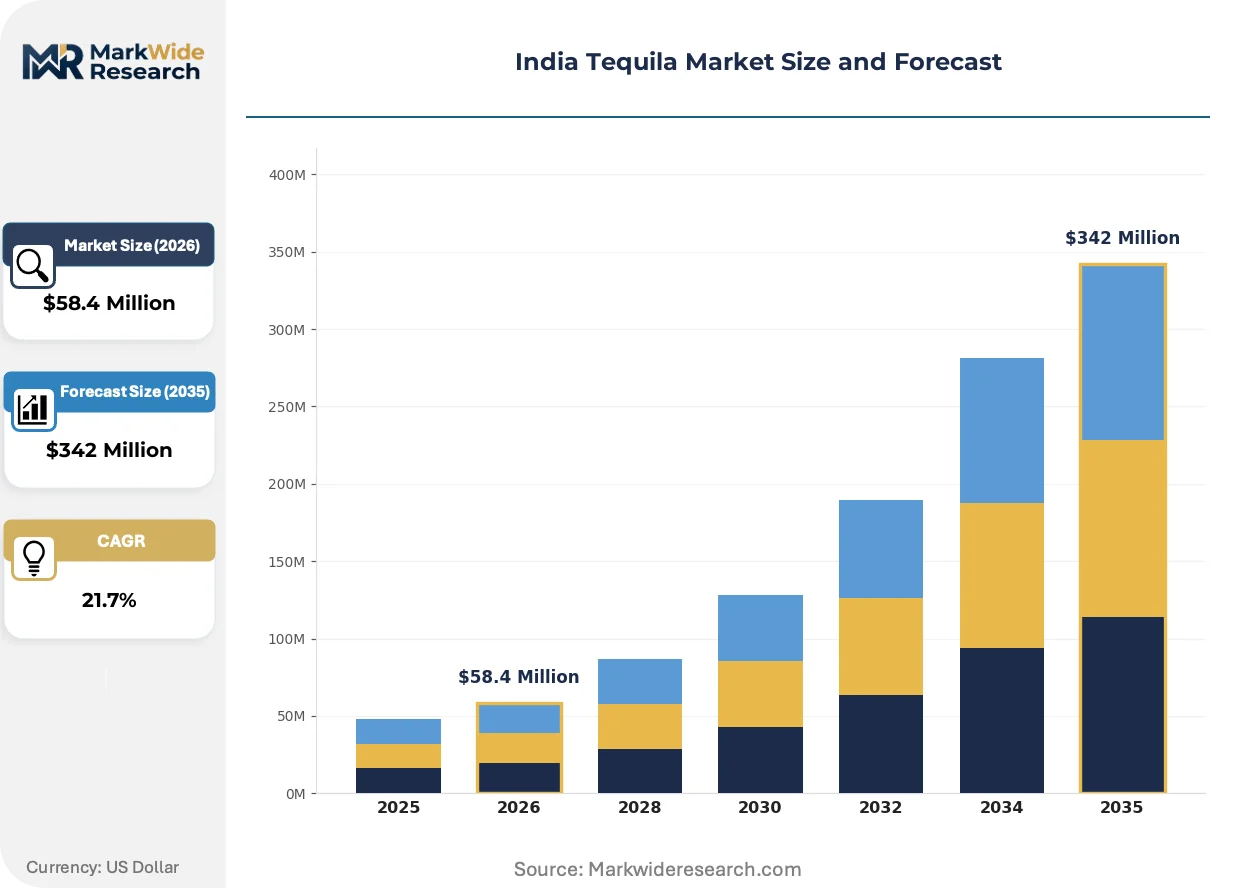
Market Dynamics
The India Tequila Market is being fundamentally restructured by the FSSAI's tightening nutritional labeling mandates for imported spirits, which are compressing registration timelines and forcing distributors to rebuild compliance workflows around documentation-heavy clearance protocols.
Growth Catalysts
- Maharashtra State Excise Liberalization:Expanded permissions for on-premise consumption in premium lounges are pulling agave-based cocktails into mainstream nightlife menus.
- Blue Agave Cultivation Trials:Experimental plots in Karnataka and Rajasthan are testing domestic agave viability, potentially reducing import dependency over the long term.
- E-Commerce Alcohol Permissions:State-level approvals for online spirits delivery in Karnataka and Maharashtra are opening direct-to-consumer channels previously blocked by excise monopolies.
Market Restraints
- Import Tariff Structure:Central excise duties combined with state-level ad valorem taxes push landed costs above comparable premium whiskies, constraining volume expansion.
- Jalisco Supply Concentration:Over 90% of certified blue agave production sits within five Mexican municipalities, exposing Indian importers to climate-driven harvest volatility.
- FSSAI Documentation Burden:Mandatory nutritional disclosure requirements for imported spirits are extending clearance timelines by 60-90 days versus prior norms.
Strategic Opportunities
- Goa and Kerala Beach Tourism:Underdeveloped tequila penetration in coastal hospitality corridors offers whitespace for agave-forward beverage programs targeting international visitors.
- Reposado Aging Positioning:Consumer education around barrel-aged expressions commands 40-60% pricing premiums over Blanco in Delhi and Bangalore lounges.
- PLI Scheme Alignment:Domestic bottling and labeling investments may qualify for production-linked incentives, reducing effective tax incidence on finished goods.
Industry Challenges
- Excise Compliance Talent Scarcity:Shortage of professionals versed in both Mexican CRT certification requirements and Indian state-level alcohol licensing is throttling expansion timelines.
- Cold Chain Infrastructure Gaps:Temperature-controlled warehousing for high-value aged stock remains concentrated in Mumbai and Delhi, limiting secondary city distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Tequila Market |
| Market Size in 2026 | $58.4 Million |
| Market Size in 2035 | $342 Million |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blanco, Reposado, Añejo, Extra Añejo Serving Method: Straight, Cocktails, Shots, Mixed Drinks Distribution Channel: Retail Stores, Online Platforms, Bars, Restaurants Customer Type: Individuals, Businesses, Events, Tourism |
| Companies Covered | Jose Cuervo, Diageo PLC, Radico Khaitan Limited, Bacardi Limited, Pernod Ricard SA, D’YAVOL Spirits, Campari Group, Becle, Loca Loka, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Tequila Market Trends and Innovations
Agave spirit positioning in India is pivoting from shot-based consumption toward crafted cocktail integration, with bartender education programs and premium mixology competitions accelerating category legitimacy among affluent urban drinkers.
Digital traceability platforms integrating blockchain-based provenance verification are unifying supply chain transparency for premium tequila imports. Mumbai-based distributors are adopting these systems to satisfy FSSAI audit requirements and justify price positioning. The technology is compressing information asymmetry between Jalisco distilleries and Indian retail buyers, enabling faster qualification of new supplier relationships.
FSSAI's phased implementation of nutritional labeling for all imported alcoholic beverages is tightening documentation standards for Mexican exporters. The regulation is forcing reformulation discussions around additive disclosure and calorie transparency. Premium brands with established compliance infrastructure are capturing shelf space as smaller importers struggle with extended clearance cycles.
Consumer preference is rotating from standardised nightclub pours toward curated home-bar builds, with affluent millennials in Bangalore and Pune driving demand for 750ml premium bottles through licensed e-commerce platforms. This channel shift is displacing traditional on-trade volume concentration, forcing distributors to reallocate marketing spend toward digital tasting content and influencer partnerships targeting residential consumption occasions.
India Tequila Market Segmentation
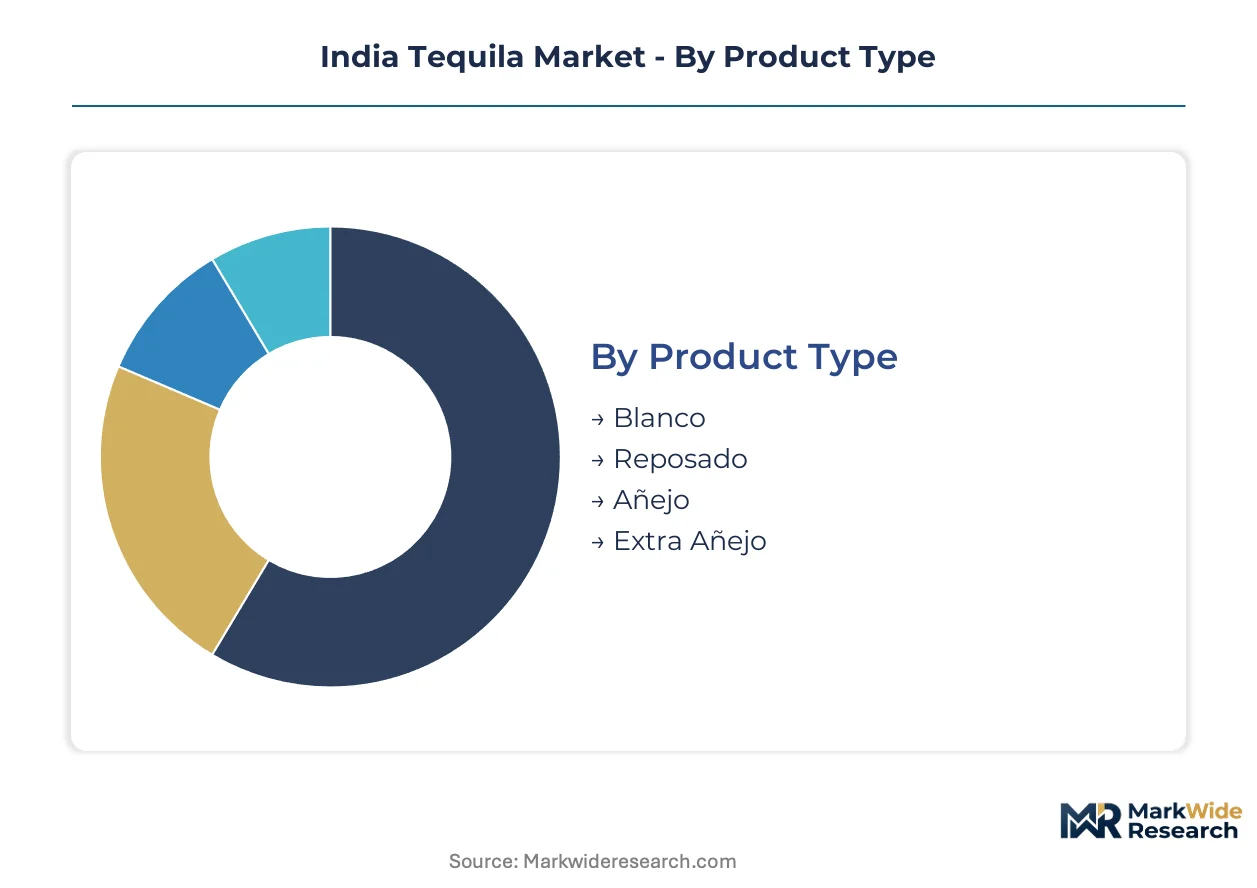
Tequila segmentation in India tracks how agave spirits traverse distinct consumption rituals, channel economics, and buyer psychographics. Each axis reveals where margin pools concentrate versus where volume scales fastest.
Product Type:
Customization intensity runs highest at the aged end of the spectrum, where barrel programs and vintage releases command narrative differentiation, while Blanco anchors standardized throughput.
- Blanco:Unaged spirit bottled immediately after distillation preserves the raw vegetal character of blue agave. Maharashtra and Karnataka lounges drive volume through margarita and paloma programs, though price ceilings limit premium positioning.
- Reposado:Two-to-twelve month oak rest develops vanilla and caramel notes that justify 40-60% pricing premiums in Delhi and Bangalore. Bartender education investments by distributors are rotating consumer preference toward this expression as the entry point for aged agave exploration.
- Añejo:One-to-three year barrel aging produces sipping-grade complexity. Limited cold-chain warehousing in Mumbai and Delhi constrains secondary city penetration.
- Extra Añejo:Ultra-aged stock exceeding three years in oak represents the smallest import volume tier. FSSAI documentation burdens disproportionately delay clearance for these high-value, low-velocity SKUs.
Most installed capacity flows through Blanco. Expansion is steepest in Reposado.
Serving Method:
Margin capture inverses against preparation complexity — straight pours extract maximum per-ounce yield while mixed formats sacrifice margin for volume throughput.
- Straight:Neat or on-rocks service in premium lounges commands the highest per-occasion spend. Consumer education around terroir and distillery provenance supports this format's growth in Mumbai's cocktail bars.
- Cocktails:Crafted agave-based mixed drinks anchor menu innovation at expanding premium venues in Delhi and Bangalore. Bartender competition circuits and spirits education programs accelerate legitimacy for tequila beyond traditional shot culture.
- Shots:Salt-and-lime ritual consumption dominates nightclub throughput but compresses brand equity and margin realization.
- Mixed Drinks:Highball and long-format combinations with juices or sodas represent the most price-elastic consumption tier, common in Goa and Kerala coastal hospitality.
Volume concentrates in Cocktails. Value realization peaks in Straight.
Distribution Channel:
Channel selection determines tax incidence, compliance burden, and brand control intensity — state excise monopolies fragment options across Maharashtra, Karnataka, and emerging markets.
- Retail Stores:Physical liquor outlets capture planned purchases and gift occasions. FSSAI nutritional labeling mandates are compressing SKU breadth as smaller importers withdraw from extended clearance timelines.
- Online Platforms:Direct-to-consumer delivery permissions in Karnataka and Maharashtra are opening inventory-light market entry. This channel is expanding most quickly as affluent millennials in Bangalore and Pune build home-bar assortments through licensed e-commerce.
- Bars:On-premise consumption venues generate highest per-occasion spend and brand discovery moments. Premium lounge expansion in Mumbai and Delhi is pulling agave-forward programs into mainstream nightlife.
- Restaurants:Food-paired agave service remains underdeveloped outside metropolitan cores, though Mexican cuisine expansion creates whitespace for category education.
Revenue realization peaks in Bars. Channel investment is rotating toward Online Platforms.
Customer Type:
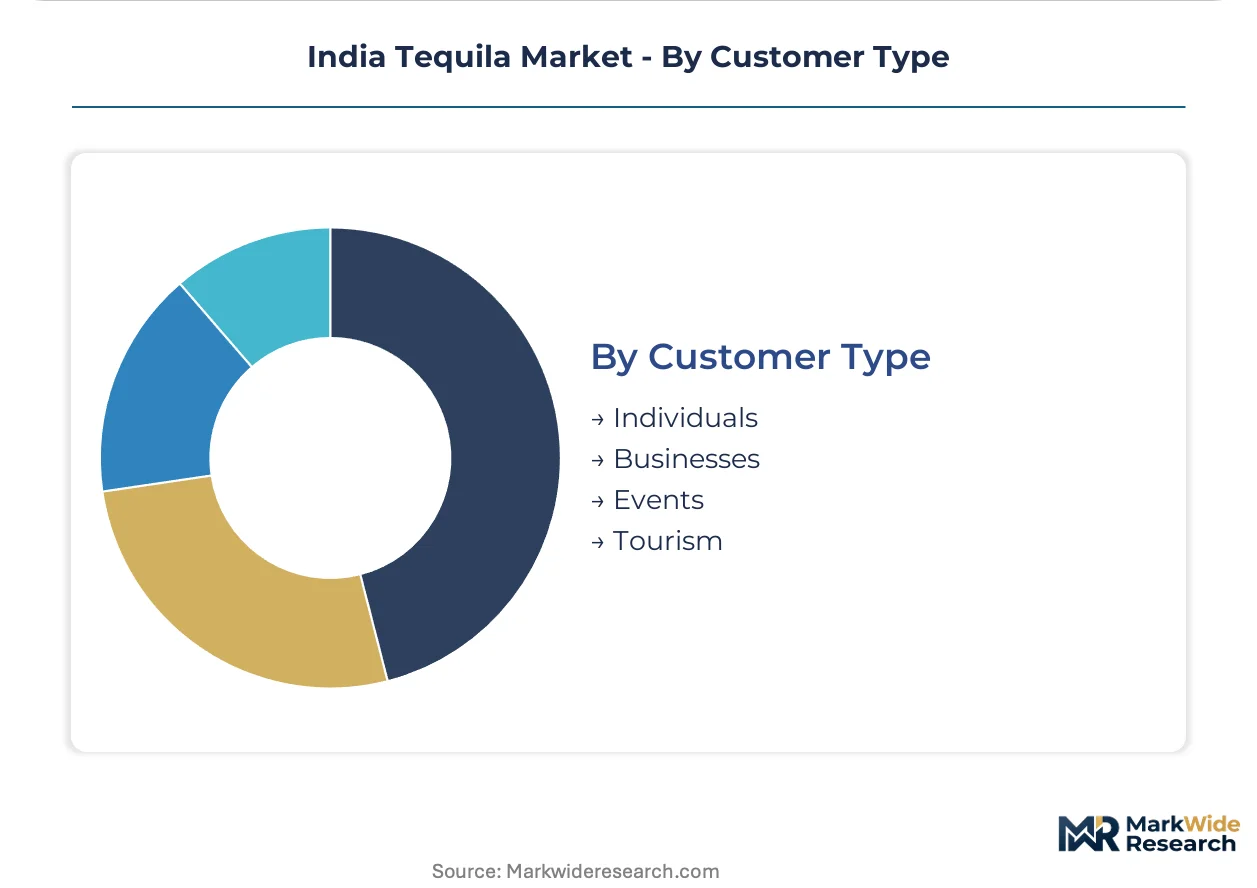
Buyer taxonomy separates recurring individual consumption from episodic commercial procurement, with distinct service and pricing architectures required for each.
- Individuals:Affluent urban millennials in Maharashtra and Karnataka drive recurring premium purchases through retail and e-commerce. Home-bar building trends favor 750ml bottle formats over on-trade pours.
- Businesses:Corporate gifting and hospitality procurement programs favor established brands with compliant documentation. FSSAI clearance reliability outweighs price in supplier selection.
- Events:Weddings and private celebrations generate concentrated volume spikes. Seasonal demand patterns in Delhi and Mumbai require distributor pre-positioning.
- Tourism:International visitors in Goa and Kerala coastal corridors represent underdeveloped agave penetration. Agave-forward beverage programs targeting this segment offer whitespace expansion.
Transaction frequency concentrates in Individuals. Average order value peaks in Businesses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tequila production traces its origins to 16th-century Jalisco, where Spanish distillation methods merged with indigenous agave cultivation. The spirit's denomination-of-origin protections, formalized by Mexico's Consejo Regulador del Tequila, now govern certified production across five Mexican states. India's emerging market structure reflects this heritage while adapting to local regulatory and consumption frameworks.
Maharashtra
Mumbai's premium lounge circuit drives Reposado and Añejo consumption through craft cocktail programs. The Maharashtra State Excise Department's expanded on-premise permissions enable agave-forward menu experimentation. Bandra and Lower Parel hospitality clusters host bartender education initiatives that rotate consumer preference beyond traditional shot culture.
Karnataka
Bangalore's affluent millennial demographic builds home-bar assortments through licensed e-commerce platforms permitted by state excise authorities. Experimental blue agave cultivation trials in rural Karnataka test domestic sourcing viability. The city's Indiranagar and Koramangala micro-distillery scene incubates local agave spirit innovation.
Delhi-NCR
Corporate gifting and hospitality procurement concentrate in Delhi's institutional buyer segment. FSSAI import clearance protocols filter supplier reliability above price in distributor selection. Gurugram's premium hotel bars anchor aged-expression positioning through curated sipping programs.
Goa
Coastal tourism corridors offer underdeveloped whitespace for agave-forward beverage programs targeting international visitors. The state's excise framework permits duty-advantaged pricing relative to mainland markets. Baga and Anjuna beach hospitality clusters remain receptive to category education investments.
Kerala
Highball and long-format mixed drinks dominate coastal hospitality consumption patterns. The Kerala State Beverages Corporation's retail monopoly shapes distribution economics for imported spirits. Kochi's emerging premium dining scene creates nascent demand for food-paired agave service.
India Tequila Market Competitive Landscape
Premium-margin players sit above commodity-margin players across compliance infrastructure and aged-stock warehousing capabilities. The market structures around three tiers: multinational spirits conglomerates with established duty-free networks, domestic distillers leveraging controlled production partnerships, and celebrity-backed entrants commanding nightlife circuit pricing power. Consolidation pressure favors players with FSSAI documentation expertise and cold-chain investments. Dominant competitive moves include strategic partnerships with Mexican CRT-certified distilleries and portfolio diversification into barrel-aged expressions.
Among multinational conglomerates, Diageo PLC and Pernod Ricard SA occupy positions defined by established import compliance infrastructure and premium retail network access. Bacardi Limited anchors a separate archetype through heritage brand equity in white spirits categories. Domestic specialist Radico Khaitan Limited exemplifies the controlled partnership model for agave spirit production. Celebrity-backed entrant D'YAVOL Spirits represents the branding-intensive vector targeting Mumbai's nightlife premiumization. Jose Cuervo and Campari Group sit within heritage tequila specialist positioning, while Becle's corporate structure reflects family-owned distillery consolidation.
| Leading Market Players |
|---|
| Jose Cuervo |
| Diageo PLC |
| Radico Khaitan Limited |
| Bacardi Limited |
| Pernod Ricard SA |
| D'YAVOL Spirits |
| Campari Group |
| Becle |
| Loca Loka |
| Others |
Pricing and Supply Chain Analysis
Blue agave harvest volatility in Jalisco transmits directly through landed cost structures, with climate-driven supply squeezes forcing Indian importers to absorb margin compression or push price adjustments through premium retail tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the India tequila landscape, with Reposado and Añejo expressions commanding substantial premiums over Blanco based on barrel-aging duration and distillery provenance. Price differentiation rests on FSSAI compliance certification tier and cold-chain warehousing access as primary drivers. Cost compression in the standard tier is intensifying because central excise duties combined with state ad valorem taxes elevate landed costs above competing premium whiskies. Nightclub operators exhibit highest price sensitivity, while corporate gifting buyers prioritize documentation reliability over per-bottle economics.
Supply Chain Analysis
Single-source vulnerability sits with Jalisco, where over ninety percent of certified blue agave production concentrates within five Mexican municipalities. Raw material dependencies center on mature blue agave hearts, American and French oak barrels, and CRT-certified distillery capacity. Tariff exposure runs through India's central excise structure and state-level alcohol licensing monopolies. Distribution runs through Mumbai and Delhi cold-chain hubs before radiating to secondary cities, with e-commerce permissions in Maharashtra and Karnataka opening direct-to-consumer bypass channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India tequila market compounds steadily as affluent urban millennials normalize agave spirits within home-bar rituals and premium lounge consumption.
For Market Incumbents: Anchor compliance infrastructure investments to capture shelf space as FSSAI documentation burdens force smaller importers into extended clearance cycles. Deepen cold-chain warehousing in Bangalore and Pune to preempt secondary city distribution gaps. Vertical integration into domestic agave cultivation trials in Karnataka and Rajasthan hedges against Jalisco harvest volatility. For New Entrants and Emerging Players: Launch via licensed e-commerce platforms in Maharashtra and Karnataka to bypass excise monopoly gatekeepers and build direct consumer relationships. Goa and Kerala coastal hospitality corridors offer the most penetrable whitespace, with international tourism creating receptive audiences for agave-forward beverage education. Celebrity-backed branding commands pricing power in Mumbai's nightlife circuit. For Investors and Strategic Acquirers: Consolidation pressure builds where FSSAI documentation expertise and aged-stock warehousing capabilities concentrate among premium-margin players. Long-term viability favors acquirers of distributors with established CRT-certified distillery partnerships and compliant import clearance workflows. Monitor state excise harmonization discussions as the signal indicating channel expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Agave Cultivation Partnership | Karnataka and Rajasthan trial plots reduce import dependency and hedge Jalisco climate exposure. |
| Blockchain Provenance Integration | Mumbai distributors deploy digital traceability to satisfy FSSAI audit requirements and justify premium positioning. |
| Reposado Barrel Program Expansion | Delhi and Bangalore lounges capture forty-to-sixty percent pricing premiums through aged-expression education. |
| E-Commerce Platform Licensing | Direct-to-consumer permissions in Maharashtra and Karnataka displace traditional on-trade volume concentration. |
| Bartender Education Investment | Craft cocktail legitimacy accelerates category rotation beyond traditional salt-and-lime shot culture. |
Research Methodology
Bottom-up lounge and retail modeling reconciled against top-down import volume tracking forms the analytical core of this study. Primary interviews with Maharashtra and Karnataka state excise officers, Mumbai and Delhi distributor operations heads, premium lounge beverage directors, and FSSAI regulatory consultants combined with secondary validation from CRT export certification databases, FSSAI labeling directives, state excise policy circulars, and Indian customs import records. Triangulation between consumption-side demand signals and supply-side clearance timelines ensures coherence across the projection horizon.
Input-output matrices model volume and value trajectories across product type, serving method, distribution channel, and customer type dimensions throughout the forecast period. CAGRs derive from segment-level growth rate blending anchored in channel permission expansions and demographic penetration curves. Forecast inputs incorporate state-level e-commerce alcohol policy trajectories and experimental domestic agave cultivation viability assessments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FSSAI regulatory acceleration or Jalisco climate disruption scenarios. Forecasts reflect documented assumptions regarding state excise harmonization progress and millennial consumption habit formation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Moonshine Market
Alcoholic Beverages
Stemware Market
Alcoholic Beverages
Craft Rum Market
Alcoholic Beverages
Premium Wine Cooler Market
Alcoholic Beverages
Wine Chocolate Market
Alcoholic Beverages
Pub Cellar Equipment Market
Alcoholic Beverages
Arak Market
Alcoholic Beverages
Oak Barrel Alternatives Market
Alcoholic Beverages
Whiskey Market
Alcoholic Beverages
Global Soju Market
Alcoholic Beverages
China Tequila Market
Alcoholic Beverages
Wine Fermentation Equipment Market
Alcoholic Beverages
US Wine Cooler Market
Alcoholic Beverages
Alcoholic Tea Market
Alcoholic Beverages
Premixed Margarita Market
Alcoholic Beverages
Herbal Distillates Market