
 RTD Canned Cocktail Market | 2026-2036
RTD Canned Cocktail Market Size, Share, and Industry Trends Forecast 2026-2036
RTD Canned Cocktail Market Analytics
Aftermarket service revenue from mixology subscription platforms and flavor customization apps is reconfiguring how beverage companies capture lifetime value beyond the initial purchase. Bacardi Limited leverages its Caribbean rum heritage to anchor authenticity messaging across Latin-flavored SKUs. Anheuser-Busch InBev competes through manufacturing scale and distributor relationships that dominate convenience store placement. Diageo differentiates via spirits-backed credibility, extending premium positioning from its core whiskey and gin portfolios into canned formats.
RTD canned cocktails are pre-mixed alcoholic beverages typically containing distilled spirits, carbonated or still mixers, and natural or artificial flavoring agents, packaged in aluminum cans with alcohol by volume ranging from 4% to 12%. These products serve commercial and retail channels by delivering bar-quality cocktails without dedicated bartending infrastructure or perishable ingredient management. The 355ml container size occupies the dominant margin pool due to its alignment with standard beer-can economics and retail cooler slotting conventions. Citrus flavor profiles sustain the highest velocity in convenience channels, while herbal formulations represent the fastest-growing sub-area as consumers seek sophisticated alternatives to sugary legacy offerings.
The US Alcohol and Tobacco Tax and Trade Bureau governs formula approval, labeling, and tax classification, directly determining which products qualify as spirits-based versus malt-based and thus their retail availability. FDA oversight of ingredient disclosure and allergen labeling intersects with TTB requirements, creating a dual compliance burden that favors larger producers with dedicated regulatory affairs functions. State-level alcohol beverage control boards in California, Texas, and Florida impose additional distribution restrictions that fragment market access. Stakeholders must monitor pending federal reclassification proposals and state direct-to-consumer shipping expansions that could unlock new channel economics.
Market Dynamics
Dual federal oversight from the TTB and FDA is compressing formulation timelines and forcing producers to maintain parallel compliance infrastructure, creating a structural advantage for scaled operators with dedicated regulatory affairs functions.
Growth Catalysts
- TTB Formula Modernization:Streamlined approval pathways for spirits-based RTD formulations are accelerating product velocity from concept to shelf.
- Urban Cluster Density:Convenience-forward consumers in New York City, Los Angeles, and Austin are normalizing premium canned formats across on-premise and off-premise channels.
- Flavor Science Advances:Natural extraction technologies are delivering authentic botanical profiles without artificial stabilizers, satisfying clean-label expectations.
Market Restraints
- Aluminum Input Volatility:Primary aluminum pricing swings directly compress margin pools for 355ml can formats.
- State Distribution Fragmentation:California, Texas, and Florida beverage control boards impose incompatible licensing tiers that block unified national rollout.
- Spirits Tax Classification:TTB determination of spirits-based versus malt-based status creates retail availability gaps in control states.
Strategic Opportunities
- Direct-to-Consumer Shipping Expansion:Pending state legislative reforms could unlock subscription-based revenue models bypassing traditional three-tier distribution.
- Herbal Formulation White Space:Sophisticated botanical SKUs targeting cocktail enthusiasts represent underdeveloped territory beyond citrus-dominant legacy offerings.
- Mixology Platform Convergence:Flavor customization apps paired with loyalty programs are capturing lifetime value beyond initial purchase.
Industry Challenges
- Dual Compliance Expertise Scarcity:Professionals fluent in both TTB formula law and FDA allergen labeling remain concentrated among large producers.
- Legacy Distributor Integration:Beer-centric wholesaler networks struggle to merchandise spirits-backed SKUs with appropriate cocktail education.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RTD Canned Cocktail Market |
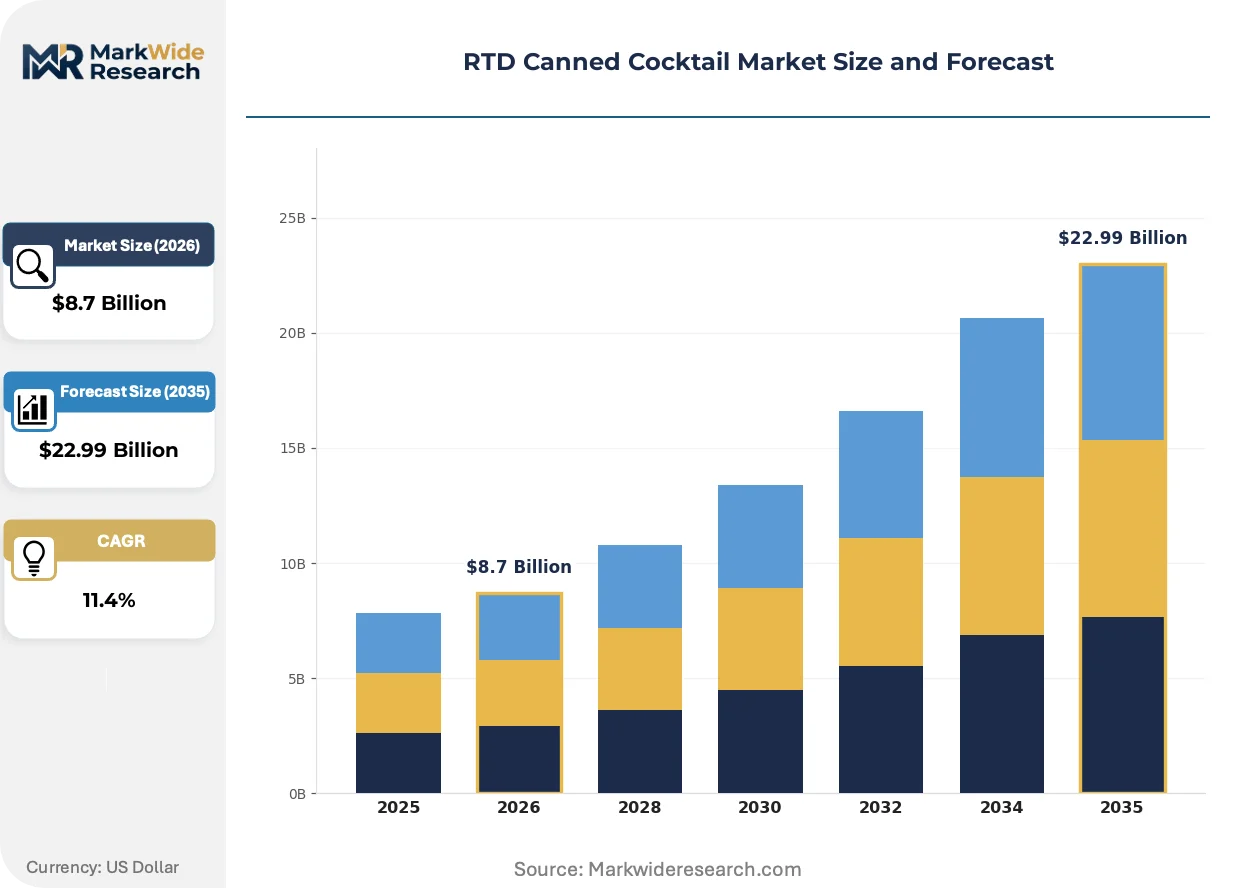
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Margarita, Mojito, Moscow Mule, Paloma Flavor Profile: Citrus, Berry, Herbal, Spicy Container Size: 200ml, 355ml, 500ml, 750ml Distribution Channel: Online, Supermarkets, Liquor Stores, Convenience Stores |
| Companies Covered | Pernod Ricard, Bacardi Limited, Anheuser-Busch InBev, Suntory, The Boston Beer Company, Diageo, Constellation Brands, Campari Group, Brown-Forman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RTD Canned Cocktail Market Evolving Landscape
Active differentiation is migrating from liquid formulation alone toward integrated digital-physical experiences, with producers competing on post-purchase engagement rather than shelf placement alone.
Natural botanical extraction is migrating from niche craft producers to mainstream manufacturing scale. Large-format canning lines in Texas and Florida are retrofitting nitrogen-dosing systems to preserve volatile aromatic compounds. This capability compression is collapsing the quality gap between mass-produced and artisanal herbal formulations.
Pending FDA updates to alcohol beverage nutrition labeling are forcing reformulation transparency. Producers must now disclose added sugars and serving-size standardization, which is compressing legacy recipes reliant on masked sweetener loads. Spirits-backed portfolios face the steepest adaptation curves as they retrofit established flavor architectures.
Subscription-based replenishment is displacing single-transaction purchasing in urban coastal markets. Younger cohorts in Austin and Los Angeles are locking into automated delivery of personalized flavor profiles. This behavioral pivot is forcing producers to build direct relationship infrastructure previously ceded to retailers.
RTD Canned Cocktail Market Segmentation
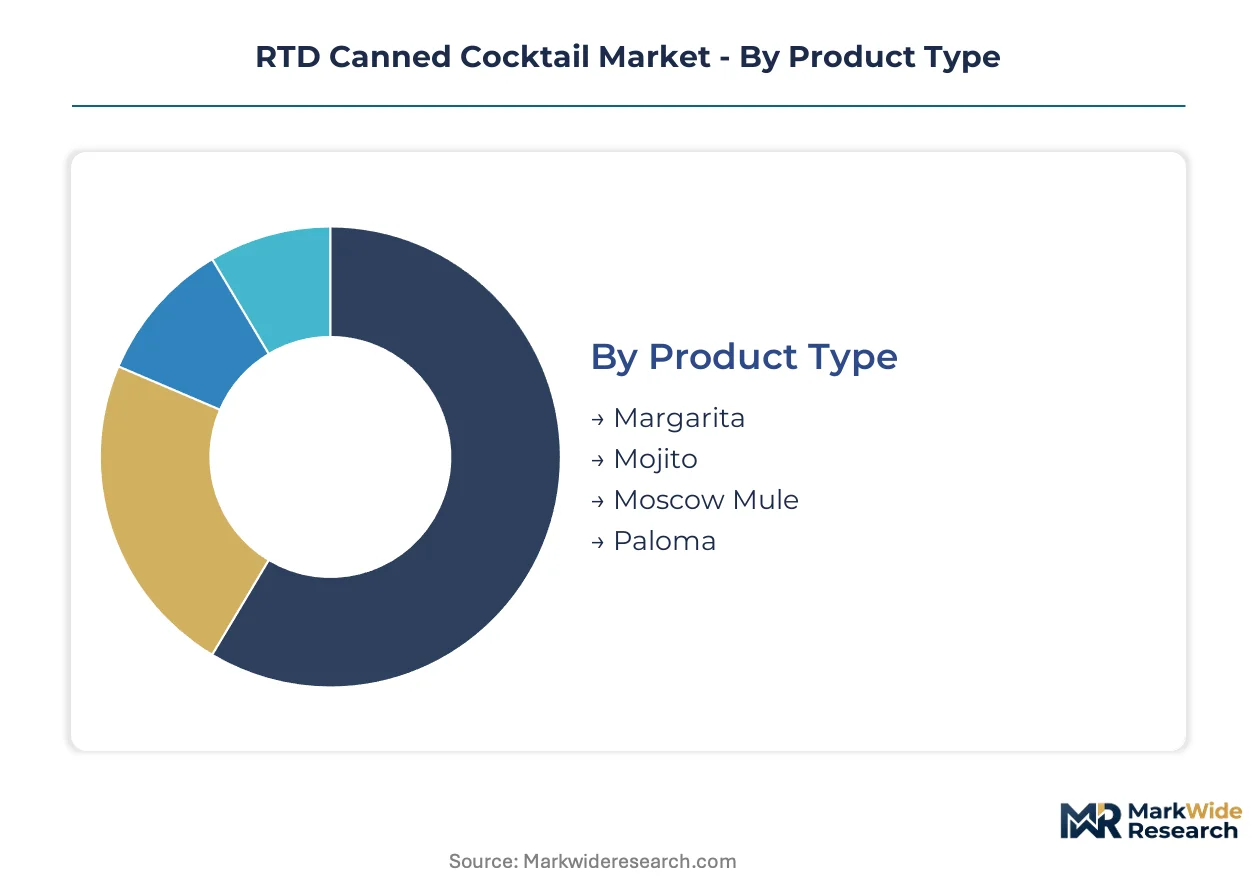
Segmentation in RTD canned cocktails determines formulation priorities, packaging economics, and channel access strategies. Distinct consumer occasions across on-premise and off-premise environments create divergent margin structures that reward precise targeting.
Product Type:
Classic cocktail archetypes anchor consumer recognition while enabling spirits-backed authenticity claims that differentiate from malt-based alternatives.
- Margarita:Tequila-forward formulations with lime and triple sec deliver the highest velocity in convenience channels. Demand concentrates in Texas and California where agave spirits heritage drives premium acceptance, though TTB formula approval timelines for tequila sourcing create production bottlenecks.
- Moscow Mule:Vodka and ginger beer combinations occupy dominant cooler placement in urban clusters. Ginger extract volatility and copper-colored can requirements for brand recognition impose sourcing complexity that favors scaled producers with dedicated ingredient procurement.
- Mojito:Rum-based profiles with mint and lime target Latin-flavor preference segments.
- Paloma:Grapefruit and tequila combinations represent emerging adoption in West Coast markets.
Established volume favors Margarita; emerging adoption favors Paloma.
Flavor Profile:
Consumer palates are bifurcating between mass-appeal refreshment and sophisticated botanical complexity, reshaping R&D allocation across producer portfolios.
- Citrus:Lemon, lime, and grapefruit formulations dominate shelf-stable stability and cost efficiency. Demand concentrates in convenience stores and supermarkets where familiarity drives impulse purchase, though commodity citrus pricing swings directly compress margin pools.
- Herbal:Botanical infusions with rosemary, basil, and lavender target cocktail enthusiasts seeking alternatives to sugary legacy offerings. Natural extraction technology advances are collapsing quality gaps between craft and mass production, with nitrogen-dosing systems preserving volatile aromatic compounds.
- Berry:Strawberry, raspberry, and blackberry profiles occupy mid-tier positioning.
- Spicy:Jalapeño and chili formulations serve niche heat-preference segments.
Mainstream velocity anchors Citrus; steepest expansion trajectory belongs to Herbal.
Container Size:
Packaging economics align with channel cooler constraints and consumption occasion duration, creating distinct margin architectures across format tiers.
- 355ml:Standard beer-can dimensions dominate retail cooler slotting and manufacturing line efficiency. Demand concentrates in supermarkets and convenience stores where single-serve occasions prevail, with aluminum input volatility representing the primary margin risk.
- 200ml:Miniature formats target on-premise sampling and airline distribution. Premium per-ounce pricing in New York City and Los Angeles hospitality channels offsets higher packaging cost ratios, though limited production line availability constrains supply.
- 500ml:Multi-serve cans occupy sharing occasions and outdoor recreation.
- 750ml:Large formats target party and event consumption with economy positioning.
Manufacturing scale favors 355ml; premium per-unit economics favor 200ml.
Distribution Channel:
Channel selection determines regulatory compliance burden, merchandising investment requirements, and consumer relationship depth.
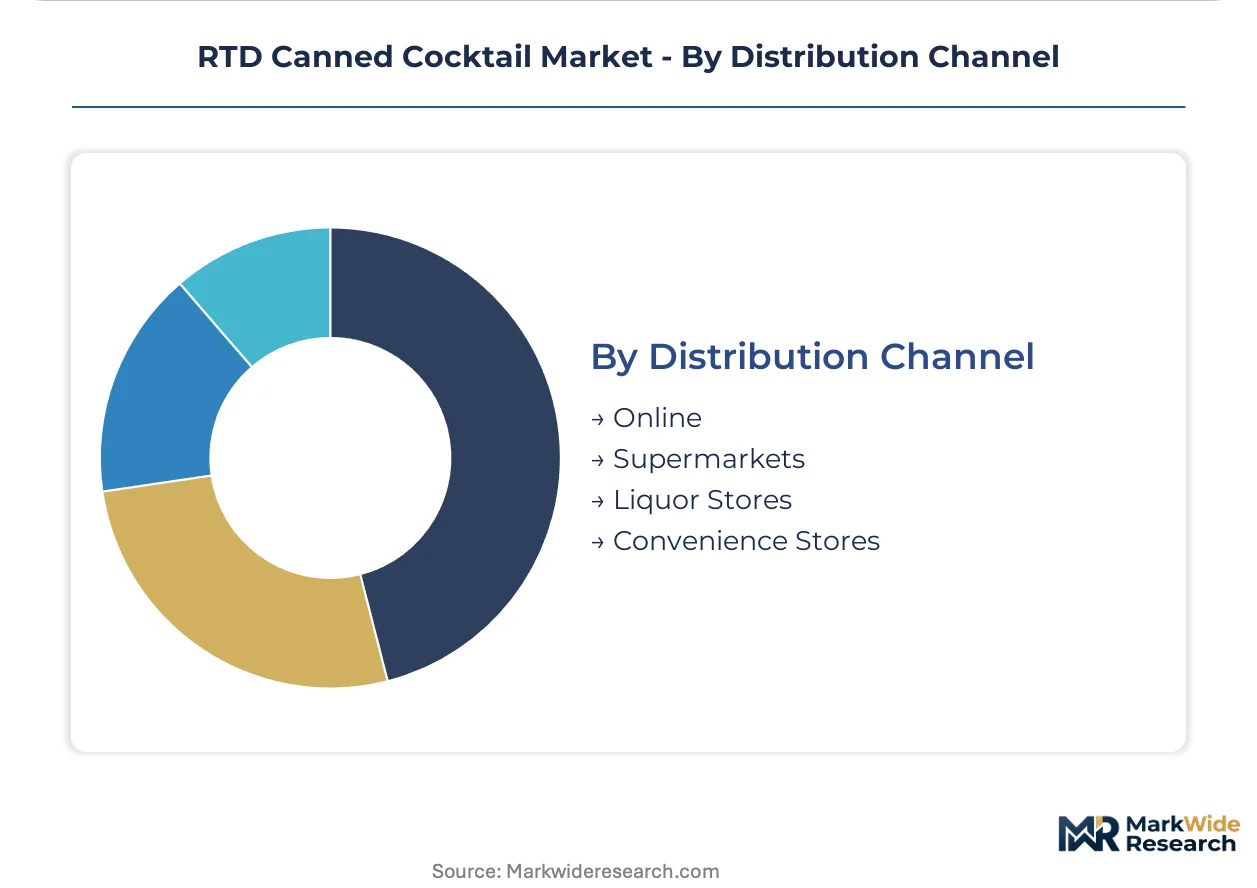
- Convenience Stores:Impulse-driven velocity depends on cooler placement and single-serve pricing accessibility. Demand concentrates in Texas and Florida where state beverage control boards permit broader spirits-based RTD availability, though distributor education gaps on cocktail merchandising constrain execution.
- Online:Direct-to-consumer and third-party platforms enable subscription replenishment and flavor customization. Younger cohorts in Austin and Los Angeles are normalizing automated delivery, pending state legislative reforms on direct shipping that could unlock subscription economics.
- Supermarkets:Grocery placement requires navigation of state-level licensing tiers.
- Liquor Stores:Spirits-specialist channels favor premium positioning and educated staff.
Volume concentration sits with Convenience Stores; relationship depth potential sits with Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns bifurcate sharply across geographies. Urban clusters in the United States normalize premium single-serve formats, while European markets emphasize lower-ABV sessionability. Asian demand concentrates in travel retail and hospitality channels with distinct flavor localization requirements.
United States
Millennial and Gen-Z cohorts in New York City, Los Angeles, and Austin drive premium convenience adoption across on-premise and off-premise channels. The Alcohol and Tobacco Tax and Trade Bureau governs formula approval and spirits-based versus malt-based classification, directly determining retail availability in control states. Texas beverage control boards permit broader spirits-based RTD distribution than California or Florida, creating fragmented market access.
Canada
Provincial liquor monopolies in Ontario and British Columbia favor lower-ABV formulations aligned with beer-alternative positioning. Health Canada intersects with provincial regulators on nutrition labeling and ingredient disclosure standards. Toronto and Vancouver urban clusters show emerging subscription replenishment behavior mirroring US coastal markets.
United Kingdom
London and Manchester hospitality channels emphasize premium spirits-backed credibility over malt-based alternatives. The UK Food Standards Agency and HMRC excise classification create compliance complexity for imported formulations. Supermarket chains in Southeast England are expanding dedicated RTD cooler space ahead of continental European markets.
Germany
Bavaria and North Rhine-Westphalia retail channels prioritize price-accessible formats with clean-label ingredient transparency. EU REACH regulations on flavor compound safety intersect with national BfR beverage guidelines. Berlin's on-premise scene experiments with herbal botanical profiles beyond dominant citrus legacy offerings.
Australia
New South Wales and Victoria convenience channels show strongest velocity for 355ml standard formats aligned with beer-can economics. FSANZ labeling requirements and state liquor licensing boards impose dual compliance burdens. Sydney's premium hospitality sector drives demand for sophisticated botanical formulations targeting cocktail enthusiasts.
RTD Canned Cocktail Market Competitive Landscape
Capability concentration sits with spirits-backed heritage players; scale advantage sits with beverage conglomerates with manufacturing and distributor relationships. The market structures around three tiers: global spirits houses with authentic cocktail credibility, multinational brewers leveraging canning infrastructure, and regional specialists targeting flavor innovation. Dominant competitive moves include portfolio diversification into spirits-backed formats and strategic partnerships with mixology platforms for post-purchase engagement.
Within the spirits heritage tier, Bacardi Limited and Diageo exemplify authenticity positioning anchored in Caribbean rum and premium whiskey portfolios respectively. Anheuser-Busch InBev occupies the scale-driven end with manufacturing and convenience store placement advantages. These three entities represent the competitive archetypes reshaping shelf space allocation and consumer relationship models.
| Leading Market Players |
|---|
| Pernod Ricard |
| Bacardi Limited |
| Anheuser-Busch InBev |
| Suntory |
| The Boston Beer Company |
| Diageo |
| Constellation Brands |
| Campari Group |
| Brown-Forman |
| Others |
Value Network & Pricing Analysis
Overcapacity in Texas canning facilities is compressing contract manufacturing rates and tilting bargaining power toward brands with volume commitments, while simultaneously pressuring regional pricing postures as fixed costs spread across underutilized lines.
Pricing Analysis
Long-term offtake agreements between spirits-backed producers and co-manufacturers dominate contract structures, insulating against aluminum spot volatility while locking in minimum volume thresholds. Three-tier pricing structure across premium, standard, and economy levels separates heritage rum portfolios from malt-based alternatives and private-label entrants. Pricing pressure stems from commodity citrus concentrate swings that directly squeeze margin pools in high-velocity SKUs. Convenience store buyers exhibit highest price sensitivity, whereas direct-to-consumer subscribers accept premium positioning for personalized flavor profiles.
Supply Chain Analysis
Tariff exposure between Mexico and the United States dominates supply chain risk profiles for tequila-forward formulations that anchor velocity in southwestern markets. Primary aluminum sourcing concentrates in Canada, China, and domestic smelters, while natural botanical extraction relies on French and Moroccan supplier networks. Single-source vulnerability in ginger extract procurement for Moscow Mule SKUs creates formulation bottlenecks during harvest disruptions. Distribution runs through beer-centric wholesaler networks that struggle with spirits-backed SKU education, fragmenting last-mile execution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against craft cocktail bars and home mixology kits that threaten to reclaim occasions lost to canned convenience formats.
For Market Incumbents: Entrench spirits-backed authenticity through backward integration into agave and rum supply chains, securing proprietary ingredient access that malt-based competitors cannot replicate. Deepen distributor education investments to overcome beer-wholesaler merchandising gaps that constrain cocktail SKU execution. Prioritize TTB compliance infrastructure as a structural moat against smaller entrants facing dual federal oversight burdens. For New Entrants and Emerging Players: Build out herbal formulation capabilities targeting cocktail enthusiasts in Austin and Los Angeles, where sophistication preferences outpace mainstream citrus saturation. Exploit state-level direct-to-consumer shipping reforms to establish subscription relationships before incumbent distributor lock-in solidifies. Lead with mixology platform partnerships that capture post-purchase engagement rather than competing solely on shelf placement economics. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-enabled brands with flavor customization apps, suggesting superior lifetime value capture versus transactional competitors. Over the medium-term horizon, acquisition targets should combine spirits heritage credibility with direct-to-consumer infrastructure. Watch for state legislative inflections on direct shipping as signals of channel economics disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Launch | Bypasses three-tier distribution fragmentation in California and Florida control states. |
| Herbal Formulation R&D Investment | Captures fastest-expanding consumer segment beyond citrus-dominant legacy offerings. |
| Mixology Platform Partnership | Locks in subscription replenishment behavior among Austin and Los Angeles cohorts. |
| Regulatory Affairs Capacity Buildout | Accelerates TTB formula approval timelines that bottleneck tequila-sourced SKUs. |
| Aluminum Supply Agreement | Hedges input volatility that compresses margin pools for 355ml standard formats. |
Research Methodology
A standing panel of brand managers, category buyers at convenience chains, TTB regulatory consultants, and co-manufacturing executives provided ongoing calibration across primary interview cycles. Secondary validation drew from Nielsen retail audit data, TTB formula approval databases, SEC 10-K filings of publicly traded beverage conglomerates, and aluminum commodity trade records. Bottom-up SKU velocity modeling triangulated against top-down category spend estimates to anchor volume projections.
Scenario-bracketing around aluminum price volatility, state distribution reforms, and consumer occasion substitution generated high-low pathways across the projection horizon. Segmentation dimensions encompassed product archetype, flavor profile, container format, and channel access tier, with spirits-based versus malt-based classification as an industry-specific modeling layer. CAGRs derived from category penetration curves adjusted for demographic cohort transition rates and urban cluster density effects.
The forecast holds incumbent behavior within observed patterns; aggressive direct-to-consumer investments by Anheuser-Busch InBev or Diageo would shift outcomes beyond modeled boundaries. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Wine Glass Market
Alcoholic Beverages
Ready to Serve Cocktails Market
Alcoholic Beverages
Wine Cork Market
Alcoholic Beverages
Organic Alcoholic Beverages Market
Alcoholic Beverages
Sake and Plum Wine Market
Alcoholic Beverages
Spain Alcohol E-Commerce Market
Alcoholic Beverages
N-Hexyl Alcohol Market
Alcoholic Beverages
Crystal Malt Market
Alcoholic Beverages
North America Beer Market
Alcoholic Beverages
Herbal Distillates Market
Alcoholic Beverages
Europe Craft Beer Market
Alcoholic Beverages
Hogshead Barrel Market
Alcoholic Beverages
Canned Alcoholic Beverages Market
Alcoholic Beverages
Global Malted Barley Market
Alcoholic Beverages
Japan Tequila Market
Alcoholic Beverages
Cigar Market