
 Vodka Market | 2026-2036
Vodka Market Size, Share, and Industry Trends Forecast 2026-2036
Vodka Market Intelligence
E-commerce as a distribution channel is reconfiguring brand discovery and consumer purchasing habits. Large portfolio holders like Diageo plc leverage extensive marketing budgets to dominate digital shelf space. Pernod Ricard S.A. differentiates through its focus on premium and super-premium brand experiences online. Meanwhile, Tito’s Handmade Vodka sustains its market position through a consistent brand narrative and strong off-trade presence.
Vodka is a distilled alcoholic beverage composed primarily of water and ethanol, produced from fermented cereal grains or potatoes. The spirit undergoes distillation, often multiple times, and filtration to achieve a neutral character. The market structure shows a clear division between high-volume classic vodka and higher-margin premium and flavored vodka categories. Sales volumes are split between on-trade channels, like bars, and off-trade retail, with the latter holding a dominant share.
Regulatory frameworks, including the U.S. TTB's standards of identity and the EU's spirit drink definitions overseen by bodies like EFSA, govern production and labeling. These rules ensure product consistency and define categories like flavored vodka. Navigating differing international advertising laws and taxation policies remains a central challenge. Success for distillers depends on adapting brand messaging and channel strategies to specific regional consumer preferences and legal environments.
Market Dynamics
The primary structural force shaping the vodka market is the bifurcation between high-volume, price-sensitive standard products and high-margin, narrative-driven premium and craft spirits. This division influences everything from agricultural sourcing and distillation techniques to channel strategy and marketing investments.
Growth Catalysts
- Craft Distillation:The proliferation of small-batch and craft distillation methods allows for significant product differentiation, creating new flavor profiles and brand stories that appeal to consumers seeking authenticity and unique experiences.
- Premiumization in Key Markets:Consumer preference for premium and super-premium vodkas, particularly in mature markets like the United States and the United Kingdom, drives value growth and encourages innovation in quality and packaging.
- E-commerce Channel Expansion:The growth of online retail and direct-to-consumer sales platforms provides brands with new avenues to reach consumers, bypassing traditional distribution gatekeepers and enabling more targeted marketing.
Market Restraints
- Input Cost Volatility:Fluctuation in the price and quality of agricultural inputs, such as cereal grains and potatoes, creates cost pressure and supply chain challenges for distillers, particularly smaller, non-contracted producers.
- Divergent Advertising Regulations:A complex web of differing international and local regulations on alcohol advertising, such as those governed by the U.S. TTB versus European standards, complicates the execution of cohesive global marketing campaigns.
- Inter-category Competition:Vodka faces intense competition for consumer share of throat from other spirit categories, especially gin and tequila, which are experiencing their own waves of premiumization and innovation in on-trade channels.
Strategic Opportunities
- Flavored Vodka in Emerging Economies:There is significant opportunity to introduce sophisticated flavored and infused vodkas to developing spirits markets in regions like Southeast Asia and Latin America, where consumer palates are evolving.
- Non-traditional Base Ingredients:Experimentation with alternative base ingredients beyond traditional grains or potatoes, such as grapes, quinoa, or milk whey, offers a path to create novel products with distinct flavor profiles and marketing angles.
- Geographical Indication (GI) Protection:Pursuing and promoting official GI designations, similar to the protections for Polish Vodka, can build regional brand equity, command premium pricing, and protect production heritage from imitation.
Industry Challenges
- Supply Chain Consistency for Craft Producers:Smaller distillers often face difficulties in securing a consistent supply of high-quality raw materials, which is essential for maintaining a uniform product character and scaling production effectively.
- Navigating Global Taxation Regimes:Managing the wide variance in excise duties and taxation policies across different countries and even sub-national jurisdictions, such as individual states in the United States or India, presents a significant compliance burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vodka Market |
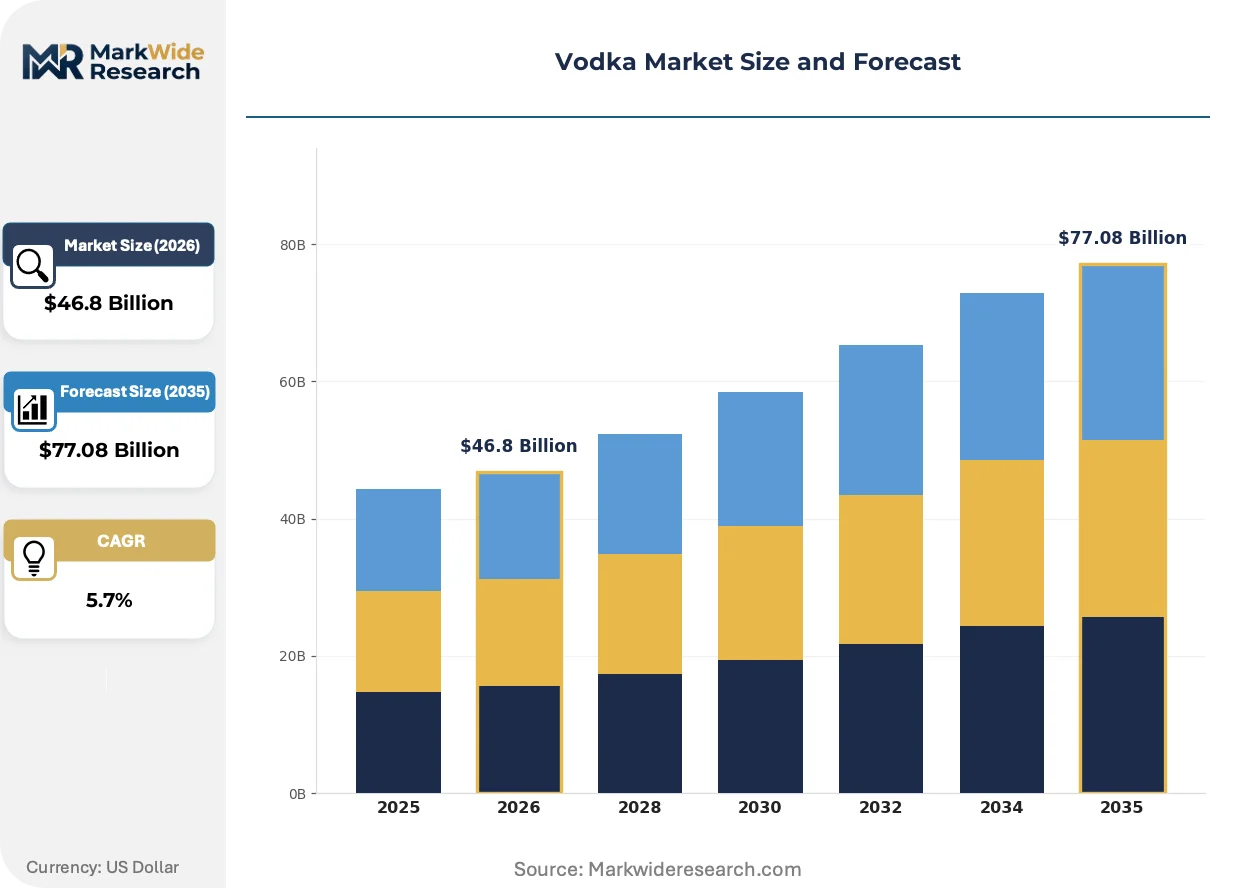
| Market Size in 2026 | $46.8 Billion |
| Market Size in 2035 | $77.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavored Vodka, Premium Vodka, Organic Vodka, Classic Vodka, Craft Vodka Distribution Channel: On-Trade, Off-Trade, E-Commerce, Duty-Free Stores, Liquor Chains Consumer Age Group: 21-30 Years, 31-45 Years, 46-60 Years, 60+ Years Packaging Type: Glass Bottles, Plastic Bottles, Cans, Miniatures, Gift Sets |
| Companies Covered | Bacardi Ltd., Absolut, Diageo plc, Ketel One, Grey Goose, Pernod Ricard S.A., Smirnoff, Tito’s Handmade Vodka, LVMH Moët Hennessy Louis Vuitton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vodka Market Strategic Shifts & Innovations
Product science and digital commerce are converging to redefine the vodka category. Innovations in distillation and filtration are creating new sensory experiences, while online platforms transform how consumers discover, learn about, and purchase spirits, shifting influence from the shelf to the screen.
Advanced filtration and finishing techniques are a central focus of product development. Methods involving specific types of charcoal, lava rock, or even crystals are used post-distillation to modify the spirit's texture and purity. Super-premium and craft segments are the primary adopters of these capital-intensive processes. This intense focus on finishing is hybridizing the spirit's traditionally neutral profile with subtle characteristics of mouthfeel and terroir, borrowing concepts from the wine and whiskey worlds.
Regulatory definitions are evolving to accommodate market realities. The U.S. TTB's revision of its standards of identity removed the requirement that vodka be neutral and without distinctive character. This policy change provides legal support for distillers to create and market vodkas that intentionally express the flavors of their base ingredients. Craft producers in the United States benefit most, gaining the freedom to innovate beyond the neutrality paradigm.
Consumer purchasing behavior is shifting toward digital-first discovery and subscription models. This evolution disrupts traditional on-premise and off-premise retail channels, where physical placement and distributor relationships were paramount for brand visibility. Curated e-commerce platforms and direct-to-consumer websites are becoming key arenas for brand building, a trend most advanced in markets like the United Kingdom and major U.S. metropolitan areas.
Vodka Market Segmentation
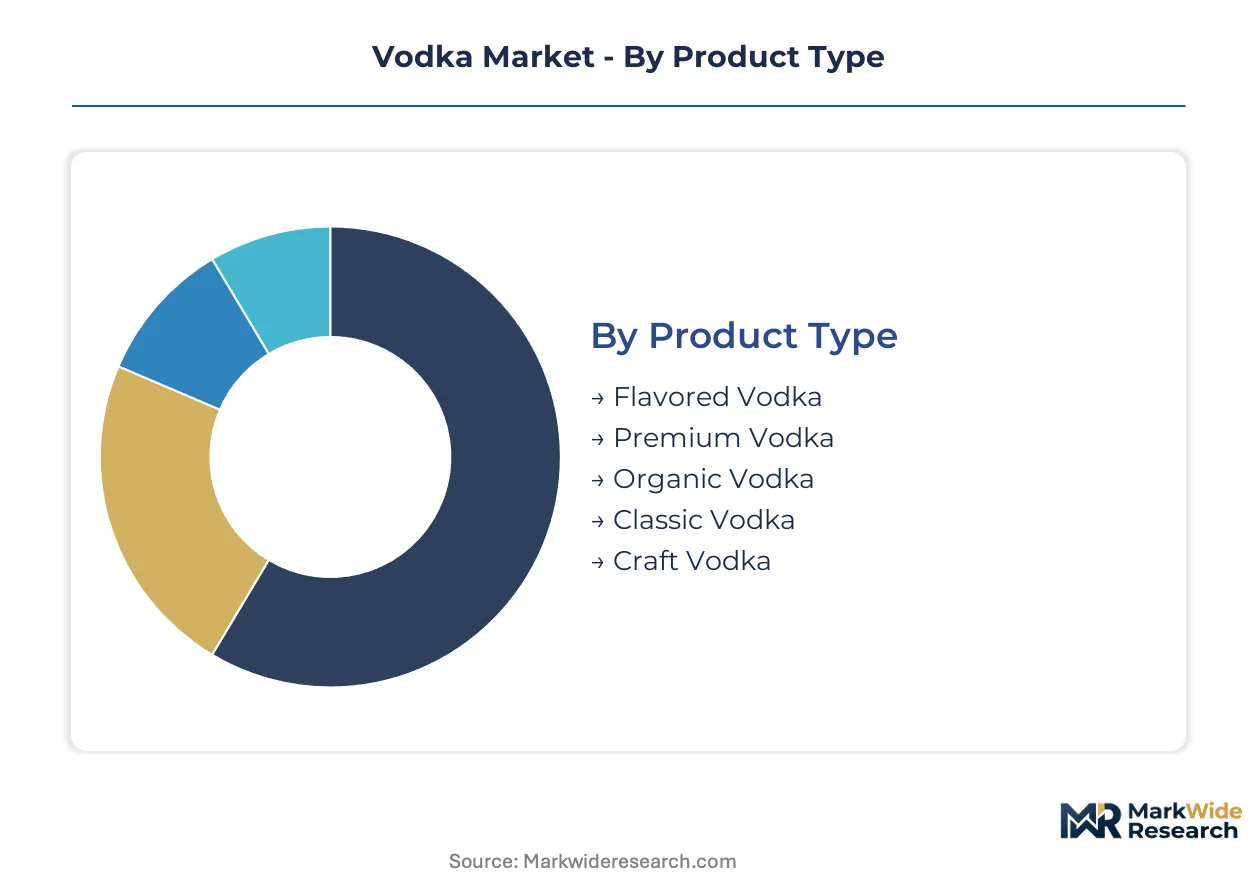
Segmentation analysis for the vodka market helps distillers understand diverse consumer preferences, distribution channels, and product innovations. This detailed breakdown reveals how brands tailor their offerings to specific demographic groups and purchasing behaviors, driving strategic market positioning.
Product Type:
The product type segmentation for vodka reveals a broad use-case spectrum, from traditional consumption to experimental mixology.
- Premium Vodka:Characterized by higher quality ingredients, multiple distillations, and refined filtration processes, often emphasizing smoothness. Consumer preference in the United States and the United Kingdom drives demand, emphasizing quality and brand experience.
- Flavored Vodka:Infused with natural or artificial flavors, moving beyond neutral profiles to offer diverse taste experiences for cocktails and mixed drinks. Emerging economies, particularly in Southeast Asia and Latin America, show evolving palates for sophisticated flavors.
- Classic Vodka:Traditional, neutral spirit made from fermented grains or potatoes, often targeting high-volume, price-sensitive consumers seeking versatility.
- Craft Vodka:Small-batch production focusing on unique base ingredients or distillation methods, appealing to authenticity-seeking consumers and local provenance.
- Organic Vodka:Produced from organically certified agricultural inputs, catering to consumers prioritizing natural ingredients and sustainable production methods.
The dominant share belongs to Classic Vodka, while Premium Vodka is closing the gap fastest.
Distribution Channel:
Distribution channels illustrate where supply concentration occurs and how brands reach consumers across various retail environments.
- Off-Trade:Sales through retail outlets like supermarkets, liquor stores, and convenience stores, where consumers purchase for home consumption. This channel holds a dominant share of sales volumes, driven by consumer convenience and competitive pricing across global markets.
- E-Commerce:Online sales platforms and direct-to-consumer websites facilitate brand discovery and purchase, bypassing traditional physical retail. Expansion in markets like the United Kingdom and major U.S. metropolitan areas shifts purchasing habits towards digital-first engagement.
- On-Trade:Sales in establishments such as restaurants, bars, and clubs, driving significant volume and brand visibility through cocktail culture.
- Liquor Chains:Specialized retail stores offering a broad selection of alcoholic beverages, often providing competitive pricing and expert advice to consumers.
- Duty-Free Stores:Retail outlets in international airports and border crossings, catering to travelers seeking tax-exempt purchases and exclusive product offerings.
Off-trade channels command the largest portion of sales, with e-commerce platforms demonstrating the most dynamic expansion.
Consumer Age Group:
The consumer age group segmentation highlights distinct purchasing behaviors and brand loyalties across different demographic cohorts.
- 21-30 Years:This demographic represents new legal drinking age consumers and early career professionals, often influenced by social media trends and novel product experiences. They show strong interest in flavored and craft vodkas, particularly in urban centers across the United States.
- 31-45 Years:This group comprises established professionals with higher disposable incomes, often seeking premium and super-premium spirits for social occasions and personal indulgence. Preference for quality and brand heritage drives their consumption in mature markets like the United Kingdom.
- 46-60 Years:Consumers in this age bracket often exhibit strong brand loyalty, preferring established premium brands and classic vodka styles for consistent quality.
- 60+ Years:This demographic typically favors traditional spirits and values consistency, often purchasing familiar brands for home consumption.
Consumers aged 31-45 years contribute significantly to premium segment growth, while the 21-30 years group drives innovation adoption.
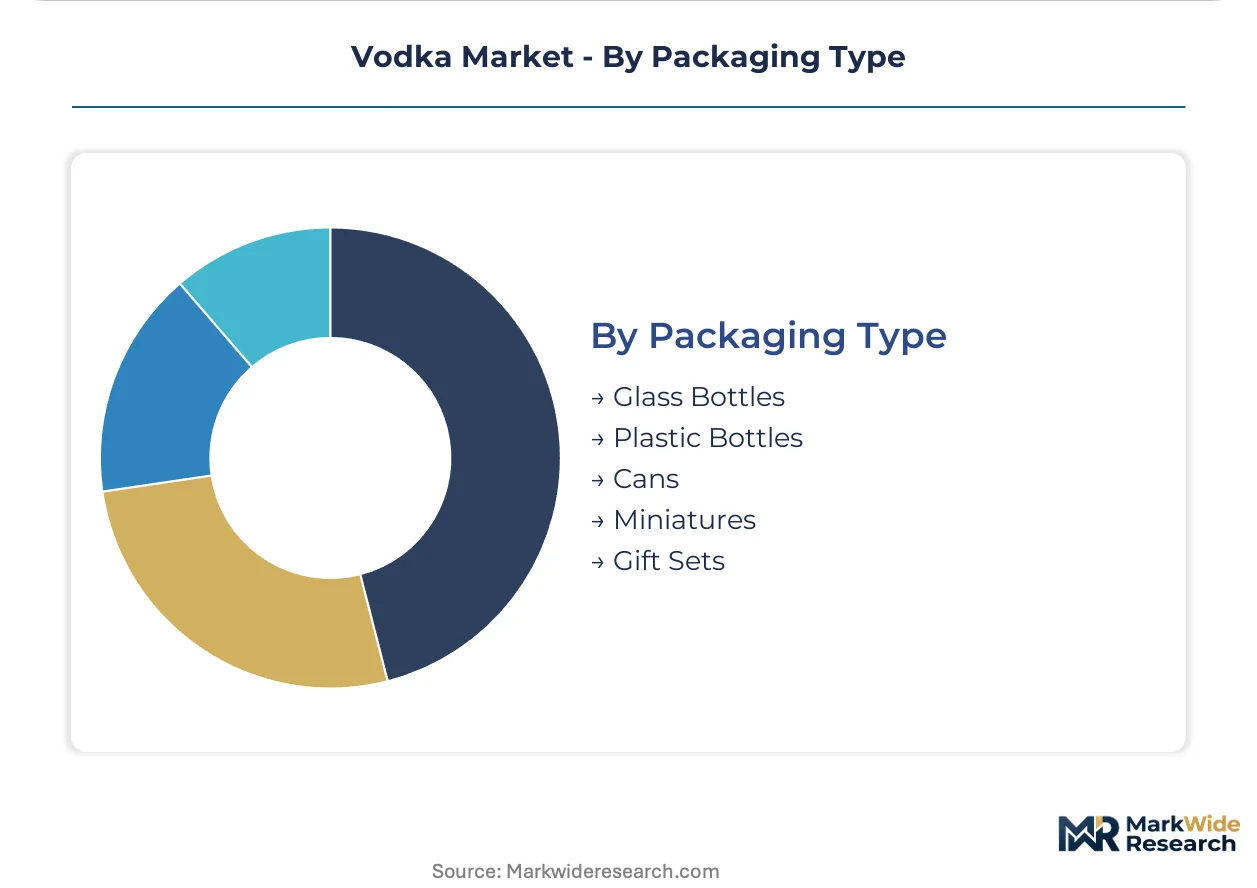
Packaging Type:
Packaging type segmentation reflects diverse application needs, from bulk consumption to gifting and single-serve convenience.
- Glass Bottles:Standard packaging solution offering aesthetic appeal, material inertness, and a perception of quality, available in various sizes. This format dominates the premium and super-premium segments, particularly in markets where presentation and brand image are paramount.
- Cans:Lightweight, portable, and recyclable aluminum containers, increasingly used for ready-to-drink vodka cocktails and single-serve options. This format is growing in popularity for outdoor events and convenience-focused consumption, especially among younger demographics in the United States.
- Plastic Bottles:Lightweight and shatter-resistant, often chosen for large-volume, price-sensitive products or specific event applications where glass is restricted.
- Miniatures:Small-sized bottles, typically 50ml, used for sampling, travel, or inclusion in gift sets, offering convenience and trial opportunities.
- Gift Sets:Curated collections often including a bottle of vodka with accompanying glassware or accessories, targeting seasonal and special occasion purchases.
Glass bottles remain the primary packaging choice for premium vodka, as cans gain traction for convenience and single-serve formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The extensive global shipping networks, anchored by major port cities, facilitate the efficient distribution of raw materials and finished vodka products, underpinning regional market dynamics. Consumption patterns are influenced by local cultural preferences, economic development, and evolving regulatory environments across diverse geographies. This interplay shapes demand for classic, premium, and flavored vodka categories.
United States
Strong consumer demand for premium and craft vodkas drives market expansion across the United States. The U.S. TTB's revised standards of identity support innovation, allowing distillers greater freedom to express base ingredient flavors. Major metropolitan areas like New York City and Los Angeles are hubs for cocktail culture, influencing national trends and product differentiation.
United Kingdom
The United Kingdom's well-developed e-commerce infrastructure significantly influences brand discovery and purchasing habits for vodka. European Union spirit drink definitions, even post-Brexit, continue to shape product labeling and quality standards. London's vibrant on-trade scene, including bars and restaurants, remains a critical channel for premium and super-premium vodka consumption.
Poland
Robust traditional consumption patterns and a strong cultural heritage underpin the Polish vodka market. Geographical Indication (GI) protection for Polish Vodka, overseen by national authorities, safeguards its authenticity and premium positioning. Distilleries in regions like Poznań maintain high production volumes, supplying both domestic and export markets with classic styles.
China
Growing disposable incomes and an evolving palate for Western spirits fuel demand for imported premium vodka in China. The country's national food safety regulations, enforced by bodies like SAMR, ensure product quality and consumer trust. Major urban centers such as Shanghai and Beijing are key consumption points, driving trends in flavored and luxury vodka segments.
Brazil
Evolving consumer preferences and a large young demographic contribute to the expanding flavored vodka segment in Brazil. ANVISA, the national health surveillance agency, regulates alcoholic beverage production and labeling, impacting market entry. São Paulo, as a major economic hub, showcases significant on-trade growth and experimentation with vodka-based cocktails.
Vodka Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, ranging from multinational conglomerates to niche craft distilleries. This structure reflects a bifurcation between high-volume standard products and narrative-driven premium offerings. Dominant strategic archetypes include global portfolio holders, regional specialists, and craft innovators. Competitive moves often involve portfolio diversification and geographic expansion to capture new consumer segments.
Large portfolio holders like Diageo plc leverage extensive marketing budgets to dominate digital shelf space and traditional retail channels. Pernod Ricard S.A. differentiates through its focus on premium and super-premium brand experiences, particularly online, targeting affluent consumers. Meanwhile, Tito’s Handmade Vodka sustains its market position through a consistent brand narrative and strong off-trade presence, appealing to authenticity-seeking consumers across the United States.
| Leading Market Players |
|---|
| Bacardi Ltd. |
| Absolut |
| Diageo plc |
| Ketel One |
| Grey Goose |
| Pernod Ricard S.A. |
| Smirnoff |
| Tito’s Handmade Vodka |
| LVMH Moët Hennessy Louis Vuitton |
| Others |
Cost & Logistics Intelligence
Global shipping networks, anchored by major port cities, influence the cost dynamics of vodka production and distribution. This concentration shapes pricing power and drives differentiation across premium and classic vodka categories.
Pricing Analysis
Pricing stratifies across premium, standard, and economy tiers, reflecting distinct market segments. Quality grade, including distillation methods and filtration, along with established brand heritage, drives significant price differentiation. Cost compression in the standard vodka segment is intensifying due to agricultural input volatility. Classic vodka consumers exhibit the highest price sensitivity, while premium segment buyers prioritize quality and brand experience.
Supply Chain Analysis
Geographical Indication (GI) protections, such as those safeguarding Polish Vodka, function as a form of export control, limiting the flow of authentically labeled products. Supply concentrates in traditional production hubs like Poland and increasingly in craft-focused regions within the United States. The industry relies heavily on cereal grains and potatoes as primary raw materials. Commodity price volatility for these agricultural inputs represents a significant structural risk. Distribution runs primarily through off-trade retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vodka market presents a significant fragmentation opportunity, driven by evolving consumer palates seeking diverse flavor profiles and authentic brand narratives. This shift creates distinct niches across product types and consumption occasions.
For Market Incumbents: Harden digital shelf space dominance through extensive marketing budgets, leveraging e-commerce platforms for brand discovery. Consolidate market share by diversifying portfolios into premium and super-premium categories, countering inter-category competition from gin and tequila. Invest in advanced distillation and filtration R&D to maintain product quality and differentiation against craft innovators.
For New Entrants and Emerging Players: Establish a beachhead in flavored vodka segments within evolving palates of emerging economies like Southeast Asia. Target younger demographics (21-30 years) in major urban centers with novel products using non-traditional base ingredients. Utilize direct-to-consumer e-commerce platforms as a primary go-to-market angle, fostering brand loyalty and direct engagement.
For Investors and Strategic Acquirers: Niche craft distillers with strong brand narratives represent attractive acquisition targets for long-term portfolio diversification. The premium and super-premium segments demonstrate sustained viability over the coming years. Watch e-commerce channel expansion rates and digital-first brand engagement as key inflection indicators for future growth and market penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Premiumization | Elevates brand perception and captures higher margins from affluent consumers in mature markets. |
| E-commerce Platform Integration | Expands brand discovery and direct consumer reach, bypassing traditional retail gatekeepers. |
| Craft Ingredient Sourcing Partnerships | Secures consistent supply of unique raw materials for product differentiation and authenticity. |
| Flavored Vodka Line Extension | Addresses evolving palates in emerging economies, particularly in Southeast Asia and Latin America. |
| Geographical Indication (GI) Pursuit | Protects heritage and commands premium pricing for specific regional vodka products like Polish Vodka. |
Research Approach
Desk research of industry association reports and government trade statistics preceded structured interviews with distillery owners, brand managers, and retail buyers. Regulatory experts also provided crucial insights. This approach combined primary qualitative data with secondary quantitative validation, ensuring bottom-up and top-down triangulation.
Macroeconomic stability and consumer preferences were held fixed, while regulatory shifts and input cost volatility were varied across the analysis window. The analytical framework modeled product type, distribution channel, consumer age group, and packaging type. Compound annual growth rates (CAGRs) were derived from historical data trends, with disposable income growth and per capita alcohol consumption as key inputs.
Stress conditions across input cost volatility and inter-category competition were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions. Material shifts in global taxation regimes or consumer preferences would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Global Premium Alcoholic Beverage Market
Alcoholic Beverages
Fruit Wine Market
Alcoholic Beverages
E-Commerce Liquor Market
Alcoholic Beverages
Europe Craft Spirits Market
Alcoholic Beverages
Malaysia Alcohol E-Commerce Market
Alcoholic Beverages
Alcopop Market
Alcoholic Beverages
Beer Pasteurization Equipment Market
Alcoholic Beverages
Malt Whiskey Market
Alcoholic Beverages
Luzhou-Flavor Liquor Market
Alcoholic Beverages
Flavored Whiskey Market
Alcoholic Beverages
Wine Filtering Machine Market
Alcoholic Beverages
Craft Rum Market
Alcoholic Beverages
Cocktail Mixers Market
Alcoholic Beverages
Apple Wine Market
Alcoholic Beverages
Dark Beer Market
Alcoholic Beverages
South America Alcoholic Beverages Market