
 Asia-Pacific Magnet Wire Market | 2026-2036
Asia-Pacific Magnet Wire Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Magnet Wire Market Outlook
Project finance for dedicated magnet wire capacity is tilting competitive advantage toward firms with balance-sheet scale. Furukawa Electric Co., Ltd. leverages its integrated copper smelting and wire drawing operations to control input costs across Southeast Asian facilities. Tongling Jingda Special Magnet Wire Co., Ltd. anchors its position through massive enamelled copper wire output serving domestic electric motor manufacturers. Sumitomo Electric Industries Ltd. differentiates via ultra-fine conductor technology for precision coil applications in automotive sensors.
Magnet wire comprises insulated electrical conductors, typically copper or aluminum, coated with enamel or film insulation rated by thermal class and dielectric strength, engineered to carry current within compact electromagnetic assemblies such as motors, transformers, and generators. Enamelled copper wire dominates volume owing to superior conductivity and thermal performance in high-slot-fill motor designs, while enamelled aluminum wire gains traction in cost-sensitive transformer and coil applications where weight reduction offsets efficiency trade-offs. The application split shows electric motors capturing the largest share as EV powertrain and industrial automation demand intensifies, with transformers remaining a stable, margin-defensive segment tied to grid infrastructure renewal.
China's GB standards and SAMR enforcement mandate higher thermal class ratings and reduced volatile organic compound emissions in enamel coating processes, directly elevating compliance costs for regional producers. Japan's METI and South Korea's MFDS enforce JIS and KC certification requirements that restrict market access for uncertified insulation systems in automotive and consumer electronics end uses. Stakeholders must monitor how India's BIS adoption of IEC thermal class harmonization affects import eligibility and domestic substitution timelines.
Market Dynamics
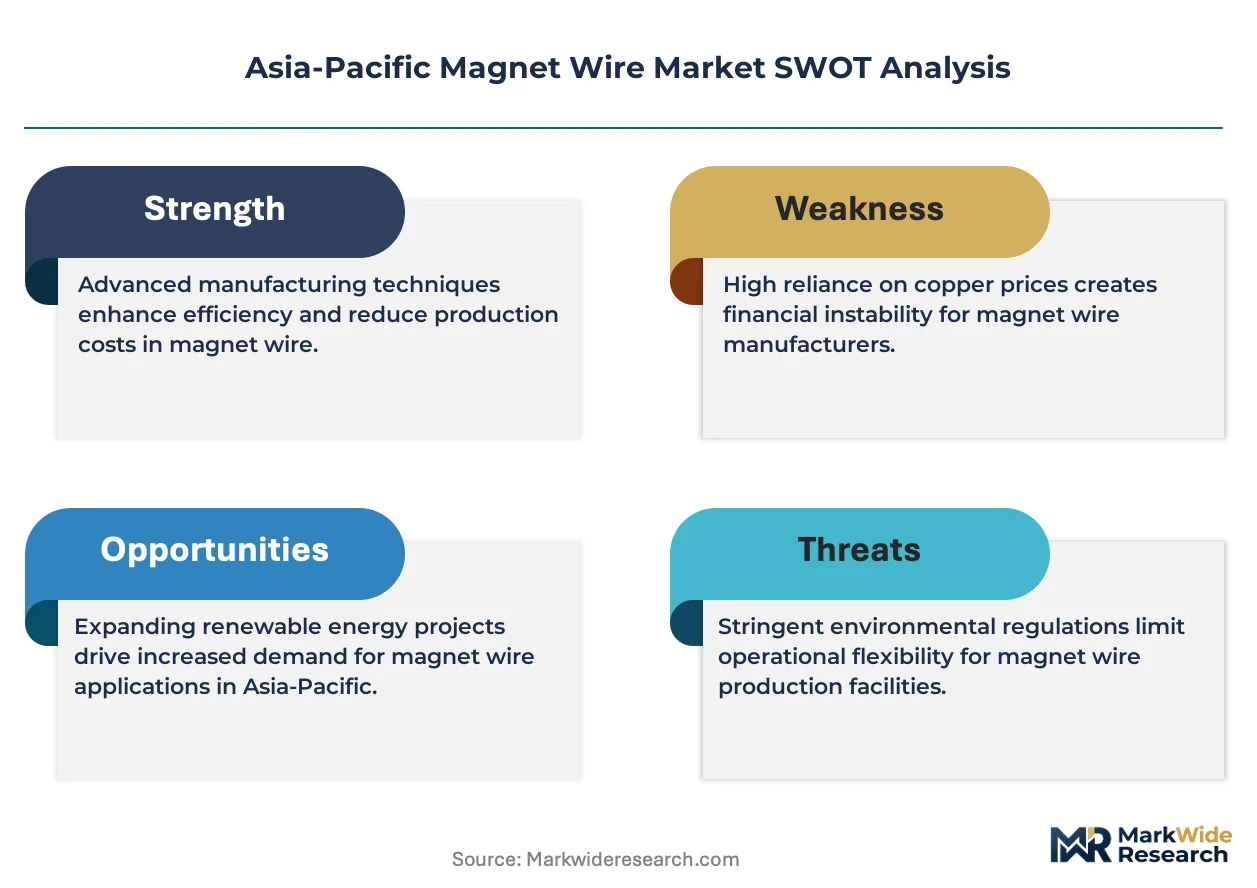
Electric vehicle powertrain electrification is compressing magnet wire thermal class requirements while China's dual carbon goals and Japan's METI efficiency mandates force insulation system upgrades across Southeast Asian supply chains.
Growth Catalysts
- China's dual carbon goals:Binding emission reduction targets under SAMR enforcement are accelerating enamel coating process upgrades and high thermal class wire adoption across Jiangsu and Zhejiang manufacturing corridors.
- EV motor procurement:Powertrain manufacturers are specifying 200°C+ thermal class enamelled copper wire for high-slot-fill designs in traction motors and auxiliary systems.
- Japan's METI efficiency mandates:JIS certification requirements for automotive-grade insulation systems are filtering supply bases and consolidating procurement toward certified regional producers.
Market Restraints
- Copper price volatility:LME copper futures swings directly compress margin structures for wire drawers without captive smelting capacity or long-term concentrate offtake agreements.
- GB standards compliance costs:China's SAMR-mandated volatile organic compound emission reductions in enamel coating processes require capital-intensive solvent recovery and thermal oxidation equipment.
- Aluminum substitution ceiling:Enamelled aluminum wire gains traction in weight-sensitive transformer applications but faces conductivity and termination reliability barriers in high-performance motor slots.
Strategic Opportunities
- India's BIS harmonization:Adoption of IEC thermal class standards creates import eligibility pathways for certified insulation systems while accelerating domestic substitution timelines.
- Ultra-fine conductor convergence:Precision coil applications in automotive sensors and consumer electronics are driving demand for sub-0.05mm conductor technology paired with thin-film polyimide insulation.
- MFDS automotive certification:South Korea's KC mark requirements for EV components are creating certified-supplier premiums for wire producers with established testing protocols.
Industry Challenges
- Enamel formulation chemistry expertise:Solvent-based to water-based coating transitions require specialized polymer science capabilities scarce across mid-tier regional producers.
- Multi-standard certification timelines:Parallel GB, JIS, and IEC qualification processes for global OEM supply contracts extend product approval cycles by 18-24 months.
- High-frequency winding equipment integration:Hairpin motor stator production lines demand magnet wire with enhanced mechanical properties and precise dimensional tolerances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Magnet Wire Market |
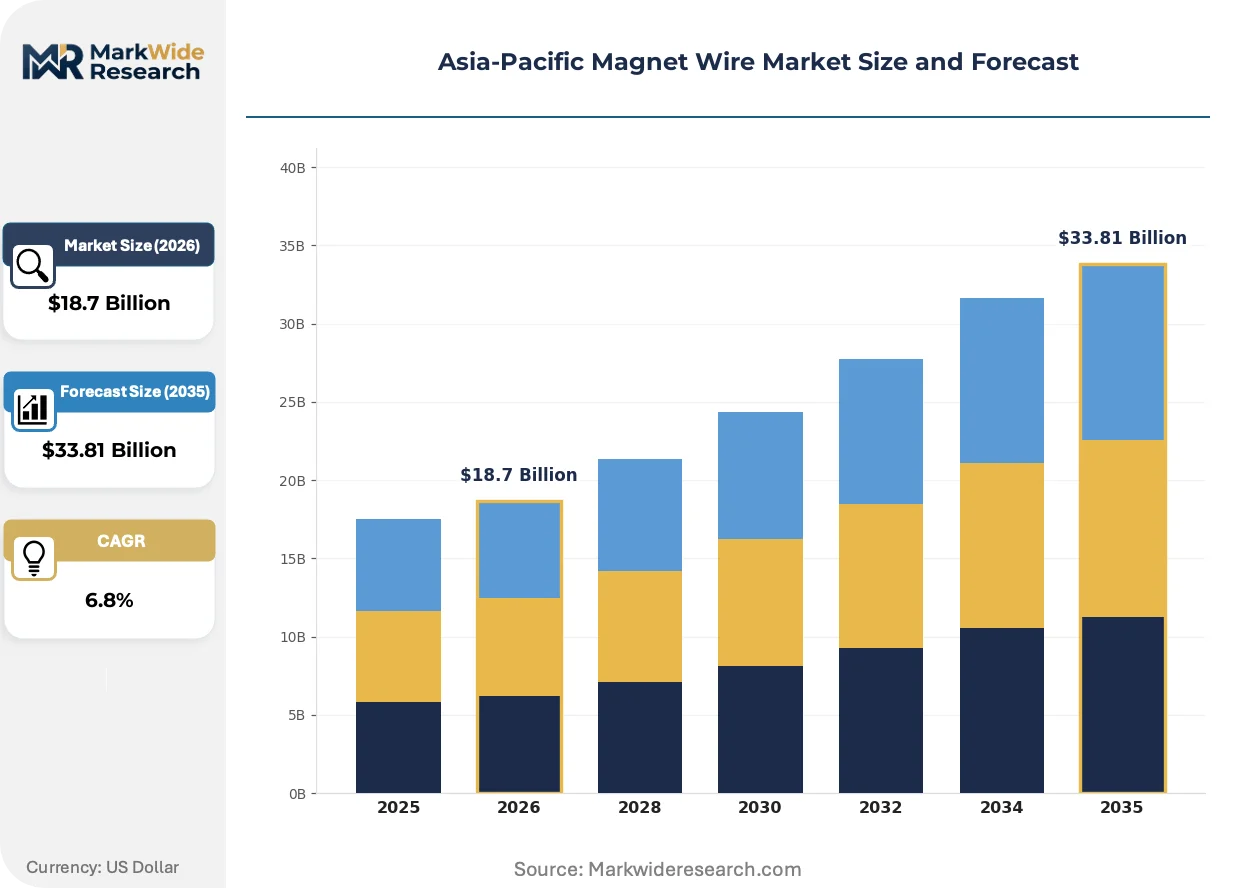
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enamelled Copper Wire, Enamelled Aluminum Wire, Bare Copper Wire, Bare Aluminum Wire Application: Electric Motors, Transformers, Generators, Coils End User: Automotive, Aerospace, Industrial Equipment, Consumer Electronics Industry Vertical: Power Generation, Telecommunications, Manufacturing, Renewable Energy |
| Companies Covered | Hitachi Metals Ltd., Furukawa Electric Co., Ltd., LS Cable & System Ltd., Fujikura Ltd., IRCE S.p.A, Tongling Jingda Special Magnet Wire Co., Ltd., Samdong Co., Ltd., Elektrisola, Sumitomo Electric Industries Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Magnet Wire Market Strategic Shifts
Process instrumentation and coating control systems are digitizing quality assurance workflows across Asia-Pacific magnet wire production lines. Three developments are compressing competitive differentiation timelines.
Inline laser micrometry combined with machine vision defect detection is digitizing enamel thickness uniformity monitoring. Tier-1 automotive suppliers are mandating real-time statistical process control data streams for IATF 16949 compliance. This technology is digitizing supplier audit protocols and compressing qualification cycles for new insulation system approvals.
China's GB/T standards revision under MEE oversight is tightening volatile organic compound emission thresholds for enamel baking ovens. Wire producers are retrofitting catalytic oxidation and regenerative thermal oxidizer systems to maintain operating licenses. High-volume Jiangsu and Zhejiang facilities face the steepest retrofit capital requirements and shortest compliance deadlines.
Direct mill relationships are displacing traditional distributor channels for EV powertrain procurement teams. Motor manufacturers are consolidating magnet wire suppliers to three certified partners per thermal class tier. This concentration is most visible in China's Yangtze River Delta where CATL, BYD, and NIO anchor procurement volumes through annual framework agreements with technical audit clauses.
Asia-Pacific Magnet Wire Market Segmentation
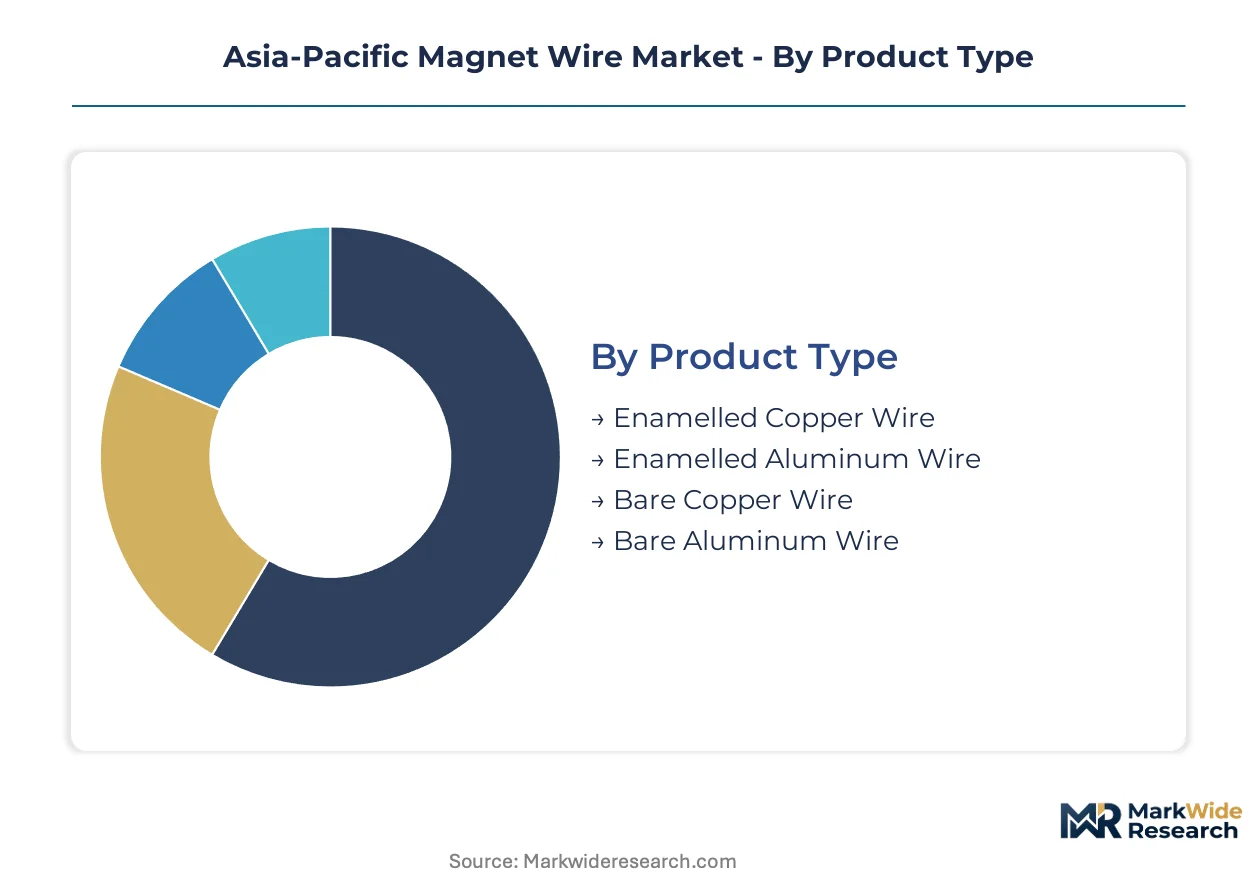
Magnet wire segmentation reveals how thermal class requirements and conductor chemistry split procurement patterns across Asia-Pacific manufacturing corridors. Product material choices and application specifications determine supplier qualification tiers and pricing bandwidths in this supply-constrained market.
Product Type:
Material composition and insulation chemistry separate segments by conductivity performance and cost structure in motor and transformer slot fill applications.
- Enamelled Copper Wire:Polyimide or polyester-imide insulated conductors rated 180°C to 220°C thermal class dominate high-slot-fill EV traction motor designs across Jiangsu and Zhejiang manufacturing clusters. Procurement teams at CATL and BYD specify this grade for power density optimization in hairpin stator windings.
- Enamelled Aluminum Wire:Anodized or organic-coated aluminum conductors reduce winding weight by approximately one-third versus copper equivalents, gaining traction in distribution transformer applications where termination reliability constraints are less severe. Cost-sensitive grid infrastructure projects in India specify this material for margin preservation.
- Bare Copper Wire:Uninsulated high-purity conductors serve as feedstock for in-house enameling operations at integrated motor manufacturers and specialized rewinding shops.
- Bare Aluminum Wire:Rod or drawn forms supply transformer OEMs performing proprietary insulation processes for custom dielectric specifications.
Enamelled copper wire holds installed capacity. Enamelled aluminum wire is rotating up the share rankings.
Application:
End-use thermal and mechanical stress profiles dictate insulation system selection and supplier certification requirements across the region.
- Electric Motors:Traction motor and auxiliary system windings demand 200°C+ thermal class ratings with enhanced mechanical properties for high-frequency hairpin forming operations. EV powertrain electrification concentrates procurement volumes in China's Yangtze River Delta.
- Transformers:Distribution and power transformer windings utilize lower thermal class specifications with emphasis on partial discharge resistance and long-term thermal aging stability. Grid infrastructure renewal across India and Southeast Asia sustains steady demand.
- Generators:Stator and rotor windings for utility-scale and industrial generation require specialized corona-resistant insulation systems for high-voltage operation.
- Coils:Inductor, solenoid, and relay windings span thermal classes from 130°C to 180°C with emphasis on dimensional precision for automated winding equipment.
Electric motors command the steepest expansion trajectory. Coils maintain stable niche positioning.
End User:
Customer certification requirements and volume scale separate procurement tiers by technical audit intensity and framework agreement structure.
- Automotive:IATF 16949-certified suppliers with JIS and GB automotive-grade insulation system approvals capture EV powertrain and sensor coil procurement. METI efficiency mandates filter supply bases toward certified regional producers.
- Aerospace:AS9100 quality systems with NADCAP special process accreditation required for aircraft motor and generator windings.
- Industrial Equipment:Servo motor and pump motor manufacturers specify standard thermal class ratings with shorter qualification cycles than automotive tiers.
- Consumer Electronics:Miniature motor and transformer applications drive demand for ultra-fine conductor technology with thin-film polyimide insulation.
Automotive holds installed capacity. Consumer electronics is rotating up the share rankings.
Industry Vertical:
Capital deployment cycles and regulatory compliance intensity shape magnet wire specification patterns across infrastructure-linked sectors.
- Power Generation:Utility-scale renewable and thermal plant construction drives generator and transformer winding demand with emphasis on 30-year service life insulation systems.
- Telecommunications:Data center power infrastructure and 5G base station power supplies utilize high-frequency magnetics with specialized core and winding materials.
- Manufacturing:Industrial automation equipment and machine tool motor replacement cycles sustain mid-tier thermal class consumption.
- Renewable Energy:Wind turbine generator and solar inverter transformer specifications prioritize partial discharge resistance and wide-temperature operation.
Power generation holds installed capacity. Renewable energy is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals and Japan's METI efficiency mandates are accelerating insulation system upgrades across Asia-Pacific manufacturing corridors. National regulators are tightening thermal class requirements and emission standards. Industrial clusters in Jiangsu, Zhejiang, and the Yangtze River Delta concentrate magnet wire procurement volumes for EV powertrains.
China
CATL and BYD anchor EV powertrain demand for 200°C+ thermal class enamelled copper wire in hairpin stator applications. SAMR enforcement of GB standards mandates volatile organic compound emission reductions in enamel coating processes. Jiangsu and Zhejiang manufacturing corridors house the densest concentrations of motor and transformer OEMs procuring certified insulation systems.
Japan
Automotive sensor coil and precision motor manufacturers specify ultra-fine conductor technology with thin-film polyimide insulation. METI efficiency mandates filter supply bases toward JIS-certified regional producers for automotive-grade applications. Chubu and Kansai industrial zones concentrate wire drawing and enameling operations serving domestic precision coil demand.
South Korea
EV component manufacturers are consolidating magnet wire suppliers to certified partners per thermal class tier under KC mark requirements. MFDS automotive certification creates supplier premiums for wire producers with established testing protocols. Seoul Capital Area and Busan-Ulsan corridors host motor manufacturers driving procurement specifications for high-slot-fill designs.
India
Distribution transformer OEMs specify enamelled aluminum wire for weight-sensitive grid infrastructure projects where cost preservation dominates. BIS adoption of IEC thermal class harmonization affects import eligibility and domestic substitution timelines. Maharashtra and Gujarat manufacturing clusters sustain mid-tier thermal class consumption for industrial motor replacement cycles.
Vietnam
Foreign direct investment in motor manufacturing is expanding enamelled copper wire demand for export-oriented industrial automation equipment. The country's national standards body is aligning thermal class certification with regional harmonization frameworks. Northern industrial provinces around Hanoi and Hai Phong concentrate new winding operations serving ASEAN supply chain integration.
Asia-Pacific Magnet Wire Market Competitive Environment
On the supply side, the industry is consolidating around three certified supplier tiers per thermal class category. Integrated copper smelters and wire drawers with captive enameling operations command input cost advantages over merchant market participants. Strategic archetypes span backward-integrated metals producers, high-volume enameling specialists, and ultra-fine conductor technology developers. Dominant competitive moves include multi-standard certification investments and direct mill relationships displacing traditional distributor channels.
Within the integrated metals producer tier, Furukawa Electric Co., Ltd. and Sumitomo Electric Industries Ltd. exemplify Japanese manufacturers with upstream control over copper refining and wire drawing operations. Tongling Jingda Special Magnet Wire Co., Ltd. anchors the high-volume enameling specialist archetype through massive output serving domestic electric motor manufacturers. These three occupy positions reflecting divergent strategic bets on certification depth versus scale economies versus conductor miniaturization capability.
| Leading Market Players |
|---|
| Hitachi Metals Ltd. |
| Furukawa Electric Co., Ltd. |
| LS Cable & System Ltd. |
| Fujikura Ltd. |
| IRCE S.p.A |
| Tongling Jingda Special Magnet Wire Co., Ltd. |
| Samdong Co., Ltd. |
| Elektrisola |
| Sumitomo Electric Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
Copper price volatility on the LME directly determines both the spread between integrated and merchant wire producers and the geographic clustering of enameling capacity around captive smelting operations in China and Japan. This commodity exposure compresses margin structures for wire drawers without long-term concentrate offtake agreements while rewarding backward-integrated manufacturers with input cost stability.
Pricing Analysis
Certification level creates the primary spread across the Asia-Pacific magnet wire market. Three-tier pricing structure across automotive-grade JIS/GB-certified, industrial IEC-standard, and economy transformer-grade products reflects the 18-24 month qualification investment required for EV powertrain supply contracts. Cost compression in merchant-market enamelled aluminum wire is intensifying because distribution transformer OEMs in India prioritize weight reduction over thermal performance. Automotive procurement teams at CATL and BYD demonstrate the lowest price sensitivity due to technical audit clauses and annual framework agreements, while industrial motor replacement buyers in Vietnam exhibit highest elasticity.
Supply Chain Analysis
Export-control scrutiny on advanced coating chemistry and precision winding equipment constrains technology transfer into emerging enameling operations. Raw material supply concentrates in China, Chile, and Indonesia for copper cathode and rod feedstock, with Jiangsu and Zhejiang provinces hosting the densest wire drawing and enameling clusters. Solvent-based enamel formulations draw from specialized polymer suppliers in Japan and Germany, creating single-source vulnerability for water-based coating transitions. Distribution runs through direct mill relationships displacing traditional distributor channels, with EV powertrain manufacturers consolidating to three certified partners per thermal class tier.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EV powertrain electrification is accelerating magnet wire thermal class requirements faster than regional enameling capacity can qualify, creating a high-growth disruption justified by China's SAMR enforcement tightening emission thresholds under dual carbon goals.
For Market Incumbents: Harden certification moats by accelerating multi-standard GB-JIS-IEC parallel qualification investments before 18-24 month approval cycles lock out late entrants. Secure captive copper smelting capacity or long-term concentrate offtake agreements to defend margin position against LME volatility. Prioritize direct mill relationships with CATL, BYD, and NIO through technical audit clauses that embed switching costs. For New Entrants and Emerging Players: Vietnam's northern industrial provinces around Hanoi present underpenetrated demand for enamelled copper wire serving export-oriented industrial automation equipment manufacturers. Target India's Maharashtra and Gujarat clusters for enamelled aluminum wire penetration where BIS harmonization creates import eligibility pathways. Pursue MFDS automotive certification in South Korea's Seoul Capital Area to capture KC mark premiums before supply consolidation completes. For Investors and Strategic Acquirers: The market sits at a certification-intensity phase that favors backward-integrated copper producers with captive enameling operations over merchant wire drawers. Long-term viability over the next decade rests on securing positions in Jiangsu and Zhejiang manufacturing corridors where motor and transformer OEM procurement concentrates. Watch for BIS adoption timelines in India as the signal indicating whether domestic substitution or import eligibility will dominate volume flows.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Standard Certification Investment | Parallel GB, JIS, and IEC qualification secures EV powertrain supply contracts with CATL and BYD procurement teams. |
| Backward Integration into Copper Smelting | Captive cathode production insulates margin structures from LME volatility affecting merchant wire drawers. |
| Water-Based Coating Transition | MEE-mandated VOC emission reductions require solvent recovery equipment retrofitting across Jiangsu facilities. |
| Direct Mill Relationship Consolidation | Annual framework agreements with technical audit clauses displace distributor channels for EV procurement. |
| Ultra-Fine Conductor Capability Buildout | Sub-0.05mm precision coil technology captures automotive sensor demand under Japan's METI efficiency mandates. |
Study Parameters
A standing panel of enameling plant managers, EV powertrain procurement leads at CATL and BYD, transformer OEM technical directors, and SAMR regulatory affairs specialists provided ongoing calibration throughout the research process. Primary interviews with these stakeholders combined with secondary validation from customs trade data, SEC 10-K filings of listed wire producers, GB standards documentation, and IHS Markit vehicle production databases. Bottom-up capacity utilization surveys across Jiangsu and Zhejiang manufacturing corridors triangulated against top-down demand modeling from EV powertrain and grid infrastructure project pipelines.
Scenario-bracketing around China's dual carbon goal enforcement intensity and India's BIS harmonization timeline shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include conductor material chemistry, thermal class rating, application end-use, and regional certification cluster. CAGRs derived from elasticity-adjusted volume projections incorporating hairpin motor adoption rates and transformer renewal cycles throughout the forecast period.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by state-backed Chinese copper producers would shift outcomes beyond modeled ranges. Material shifts in SAMR enforcement timelines or BIS adoption schedules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Ferrite Magnet Market
Magnetic Materials
Gadolinium Market
Magnetic Materials
Plastic Bonded Magnet Market
Magnetic Materials
Magnetite Nanoparticles Market
Magnetic Materials
Amorphous Soft Magnetic Materials Market
Magnetic Materials
Nanocrystalline Soft Magnetic Material Market
Magnetic Materials
Magnetic Material Magnetization and Testing Equipment Market
Magnetic Materials
Soft Ferrite Core Market
Magnetic Materials
Neodymium [Nd-Fe-B] Magnet Market
Magnetic Materials
Magnetostrictive Materials Market
Magnetic Materials
Japan Neodymium Iron Boron Magnet Market
Magnetic Materials
Ferrofluid Market
Magnetic Materials
Global Soft Magnetic Composites (Smcs) Market
Magnetic Materials
Superconducting Magnets Market
Magnetic Materials
Rare Earth Magnet Market
Magnetic Materials
Global Soft Magnetic Alloys Market