
 Lecithin Market | 2026-2036
Lecithin Market Size, Share, and Industry Trends Forecast 2026-2036
Lecithin Market Analysis
Pharmaceutical-grade lecithin demand is repositioning the competitive landscape toward high-purity phospholipid suppliers. Cargill Incorporated leverages its integrated oilseed processing network to sustain cost advantages across soy and sunflower lecithin streams. Lipoid GmbH specializes in egg and synthetic phospholipid formulations for injectable drug delivery systems. Archer-Daniels-Midland Company dominates North American commodity lecithin supply through its crushing and refining infrastructure.
Lecithin denotes a mixture of phospholipids—primarily phosphatidylcholine, phosphatidylethanolamine, and phosphatidylinositol—typically extracted via hexane or ethanol degumming of crude vegetable oils at 60-80°C, functioning as an amphiphilic emulsifier that stabilizes oil-water interfaces in processed foods, pharmaceuticals, and cosmetics. Soy lecithin occupies the largest volume share due to abundant soybean crushing capacity, though sunflower lecithin is gaining fastest as non-GMO and allergen-free positioning commands premium pricing in European formulations. Emulsifier applications generate the deepest margin pools, particularly where pharmaceutical and personal care buyers require certified lipid excipients with documented traceability.
EU REACH and the F-Gas Regulation enforce residual solvent limits and environmental accountability across lecithin imports into Europe, while FDA food additive regulations govern GRAS status and labeling requirements in the United States. India's FSSAI and BIS standards are tightening contaminant thresholds for edible-grade imports, reshaping supplier qualification protocols for Asian market access. Stakeholders must monitor evolving pharmaceutical-grade certification requirements and regional oilseed supply shifts to secure phospholipid sourcing positions.
Market Dynamics
Clean-label formulation mandates from EU REACH and FDA GRAS frameworks are forcing food and pharmaceutical manufacturers to displace synthetic emulsifiers with plant-derived phospholipids, tightening purity specifications across the value chain.
Growth Catalysts
- EU F-Gas Regulation:Residual solvent limits on imported lecithin are accelerating ethanol extraction adoption over hexane degumming in European-bound supply chains.
- Injectable drug delivery:Liposome formulation demand from oncology and vaccine developers is pulling pharmaceutical-grade phosphatidylcholine volumes upward.
- Sunflower seed crushing:Black Sea and Eastern European oilseed infrastructure expansion is diversifying non-GMO lecithin feedstock availability.
Market Restraints
- Crude vegetable oil volatility:Soybean and sunflower seed price swings transmit directly to lecithin raw material costs, compressing processor margins.
- German production concentration:Specialized phospholipid manufacturing clusters around Ludwigshafen and Cologne create geographic supply vulnerability for high-purity grades.
- Enzymatic emulsifier substitution:Microbial transglutaminase and lipase formulations are capturing clean-label bakery applications from lecithin.
Strategic Opportunities
- India FSSAI edible-grade imports:Tightening BIS contaminant thresholds favor qualified EU and US suppliers with documented traceability systems.
- Cell-cultured meat:Growth medium lipid supplementation requirements open novel phospholipid applications outside traditional food processing.
- EU Green Deal bioeconomy incentives:Circular oilseed processing subsidies support solvent recovery investments and carbon footprint reduction claims.
Industry Challenges
- Pharmaceutical-grade certification timelines:EMA and FDA lipid excipient master file approvals require 18-36 month documentation cycles, delaying market entry.
- Phospholipid fractionation capex:Chromatographic separation equipment for high-purity phosphatidylcholine demands multi-million dollar facility investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lecithin Market |
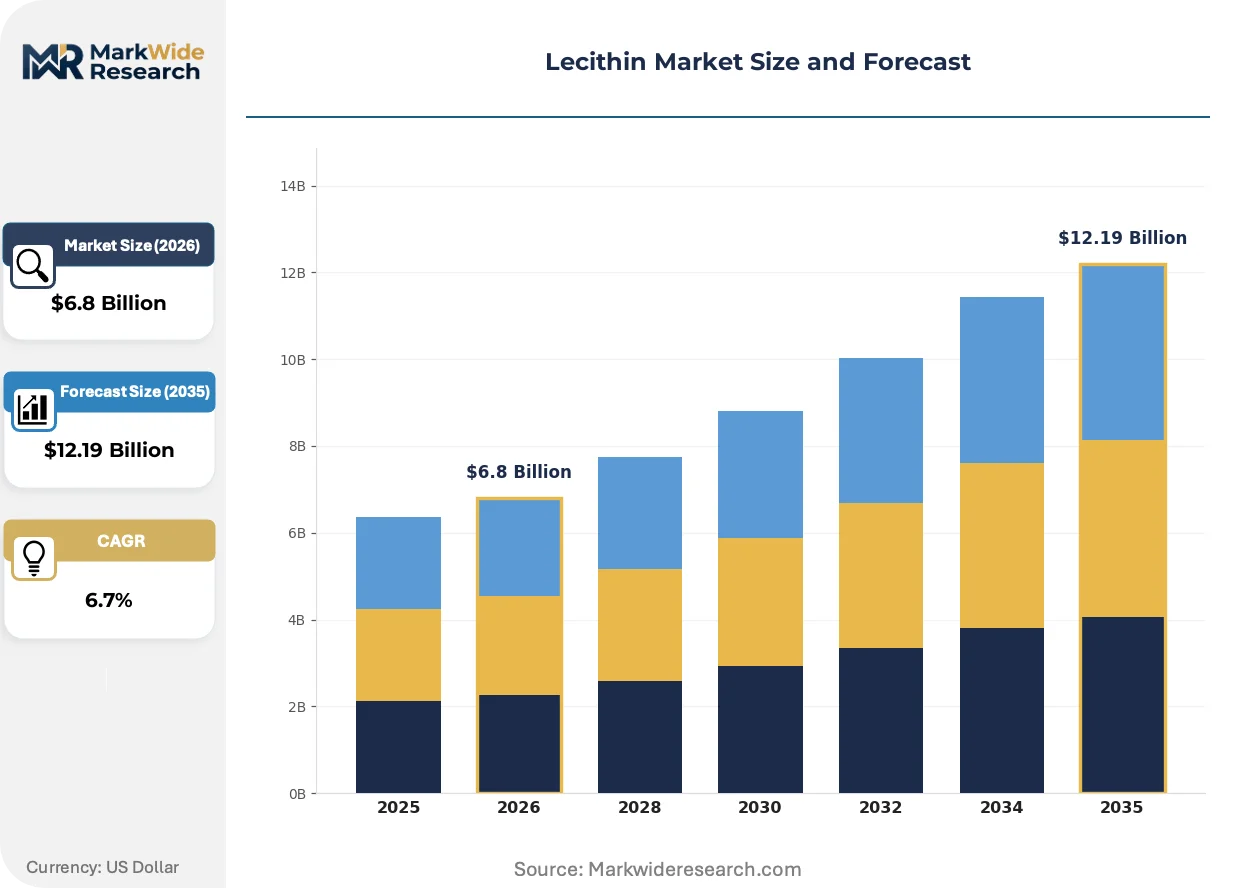
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Egg Lecithin, Soy Lecithin, Sunflower Lecithin, Synthetic Lecithin End User: Food & Beverage, Pharmaceuticals, Personal Care, Animal Feed Application: Emulsifier, Antioxidant, Stabilizer, Fat Replacer Form: Liquid, Powder, Granular, Softgel |
| Companies Covered | Wilmar International Limited, Lipoid GmbH, Cargill Incorporated, American Lecithin Company, Sonic Biochem Extractions Pvt. Ltd., Archer-Daniels-Midland Company, DuPont de Nemours Inc., Lecico GmbH, Bunge Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lecithin Market Emerging Trajectories
Enzymatic degumming and membrane filtration technologies are displacing conventional solvent extraction, while regulatory jurisdictions compete to set the strictest purity benchmarks for food and pharmaceutical-grade phospholipids.
Enzymatic degumming using phospholipase A1 and C enzymes is absorbing water-degummed oil streams that previously yielded low-quality lecithin. Major European oilseed processors are retrofitting crushing facilities with enzyme injection systems to capture higher-value phospholipid fractions. This technology is absorbing mid-tier commodity lecithin volumes into premium food-grade and feed-grade channels, compressing the historical price spread between technical and refined grades.
EU REACH substance registration requirements and the F-Gas Regulation's environmental accountability provisions are tightening residual solvent documentation for all lecithin imports into European customs territories. Processors must now submit comprehensive supply chain audits proving hexane or ethanol recovery rates and waste stream management. Pharmaceutical and infant nutrition formulators in Germany, France, and the Netherlands are responding by qualifying only suppliers with ISO 22000 and EXCiPACT certification, excluding smaller crushers lacking compliance infrastructure.
Direct procurement relationships between end-use manufacturers and oilseed processors are fragmenting the traditional trader-dominated distribution model. Large food and pharmaceutical compounders in North America and Western Europe are establishing annual volume contracts with named crushing facilities, bypassing commodity brokers. This pattern is most visible in sunflower lecithin sourcing, where non-GMO and allergen-free claims require field-to-facility traceability that traders cannot document.
Lecithin Market Segmentation
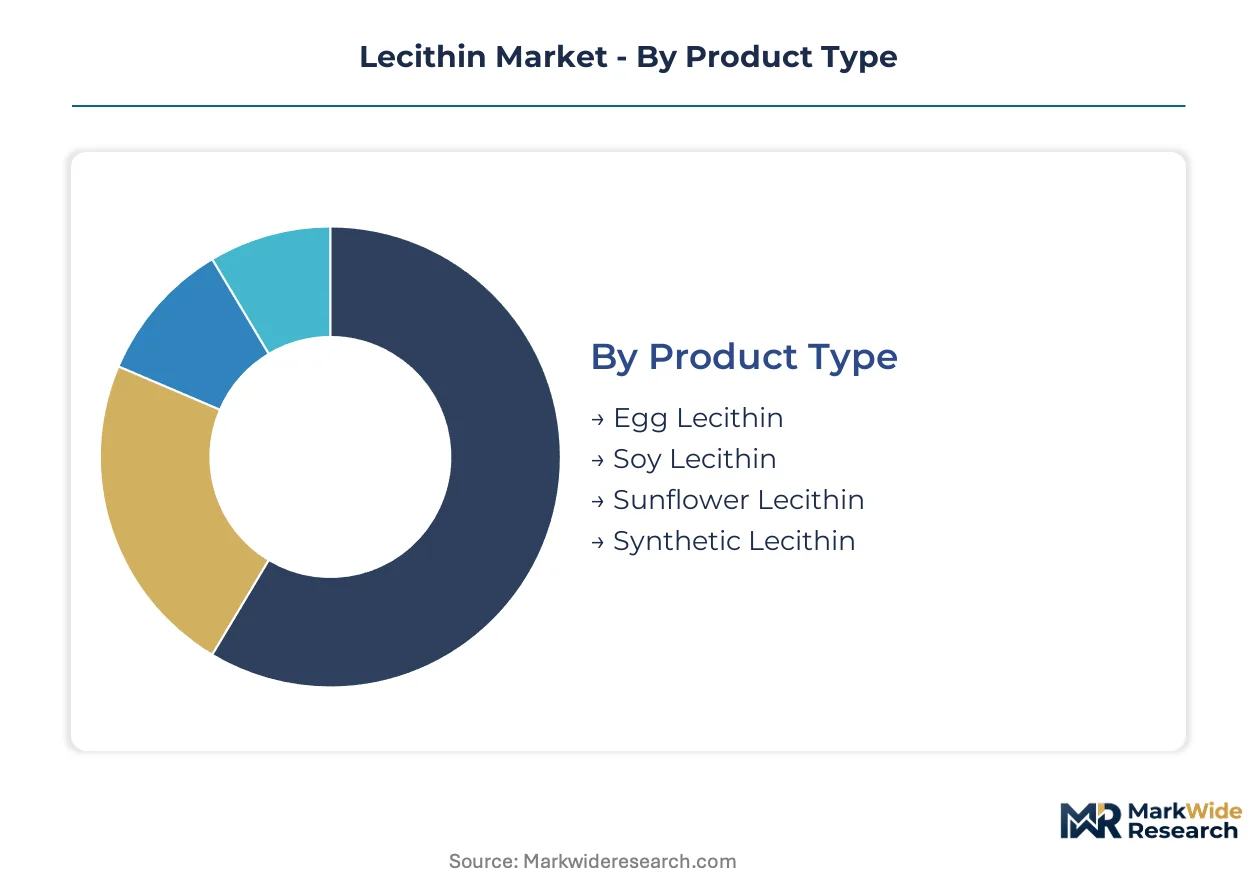
Lecithin market segmentation reveals how phospholipid specifications align with end-use performance requirements. Product origin and purity grades determine pricing tiers across food, pharmaceutical, and industrial applications.
Product Type:
Extraction source and phospholipid composition define functional suitability for regulated applications.
- Soy Lecithin:Derived from hexane or ethanol degumming of crude soybean oil, containing 15-35% phosphatidylcholine. Crushing infrastructure in Argentina, Brazil, and the US Midwest sustains volume supply for commodity food emulsifier applications. FDA GRAS status and established supply chains anchor this segment in processed food manufacturing.
- Sunflower Lecithin:Non-GMO phospholipid mixture extracted from Black Sea and Eastern European oilseed crushing. EU REACH documentation requirements and allergen-free positioning command premium pricing in German and French clean-label formulations. Black Sea infrastructure expansion is diversifying feedstock availability beyond traditional soy dependence.
- Egg Lecithin:Animal-derived phospholipid with high phosphatidylcholine content for liposome drug delivery systems.
- Synthetic Lecithin:Chemically synthesized phospholipid formulations meeting pharmaceutical-grade purity specifications.
Soy lecithin leads on scale; sunflower lecithin leads on momentum.
End User:
Regulatory stringency and performance specifications segment demand across application verticals.
- Food & Beverage:Clean-label emulsifier demand from EU and US processed food manufacturers is displacing synthetic additives. Bakery, confectionery, and beverage applications require documented non-GMO and allergen-free certification for retail distribution.
- Pharmaceuticals:Injectable liposome formulations from oncology and vaccine developers pull pharmaceutical-grade phosphatidylcholine volumes upward. EMA and FDA lipid excipient master file approvals require 18-36 month documentation cycles, concentrating supply among qualified European and North American processors.
- Personal Care:Skin and hair care emulsions utilizing phospholipid-based delivery systems for active ingredients.
- Animal Feed:Feed-grade lecithin for aquaculture and livestock nutrition applications.
Food and beverage commands absolute volume; pharmaceuticals commands absolute margin.
Application:
Functional performance requirements determine phospholipid grade selection and processing intensity.
- Emulsifier:Amphiphilic phospholipid stabilization of oil-water interfaces in processed foods, cosmetics, and drug delivery systems. This application generates the deepest margin pools where pharmaceutical and personal care buyers require certified lipid excipients with documented traceability.
- Antioxidant:Phospholipid chelation of metal ions and free radical scavenging in edible oils and nutritional supplements.
- Stabilizer:Viscosity modification and texture control in chocolate, margarine, and baked goods.
- Fat Replacer:Reduced-calorie lipid mimetic properties in light and diet food formulations.
Emulsifier applications dominate revenue contribution; antioxidant applications are climbing the fastest on functional food positioning.
Form:
Physical state determines handling logistics, dosage precision, and shelf stability across manufacturing environments.
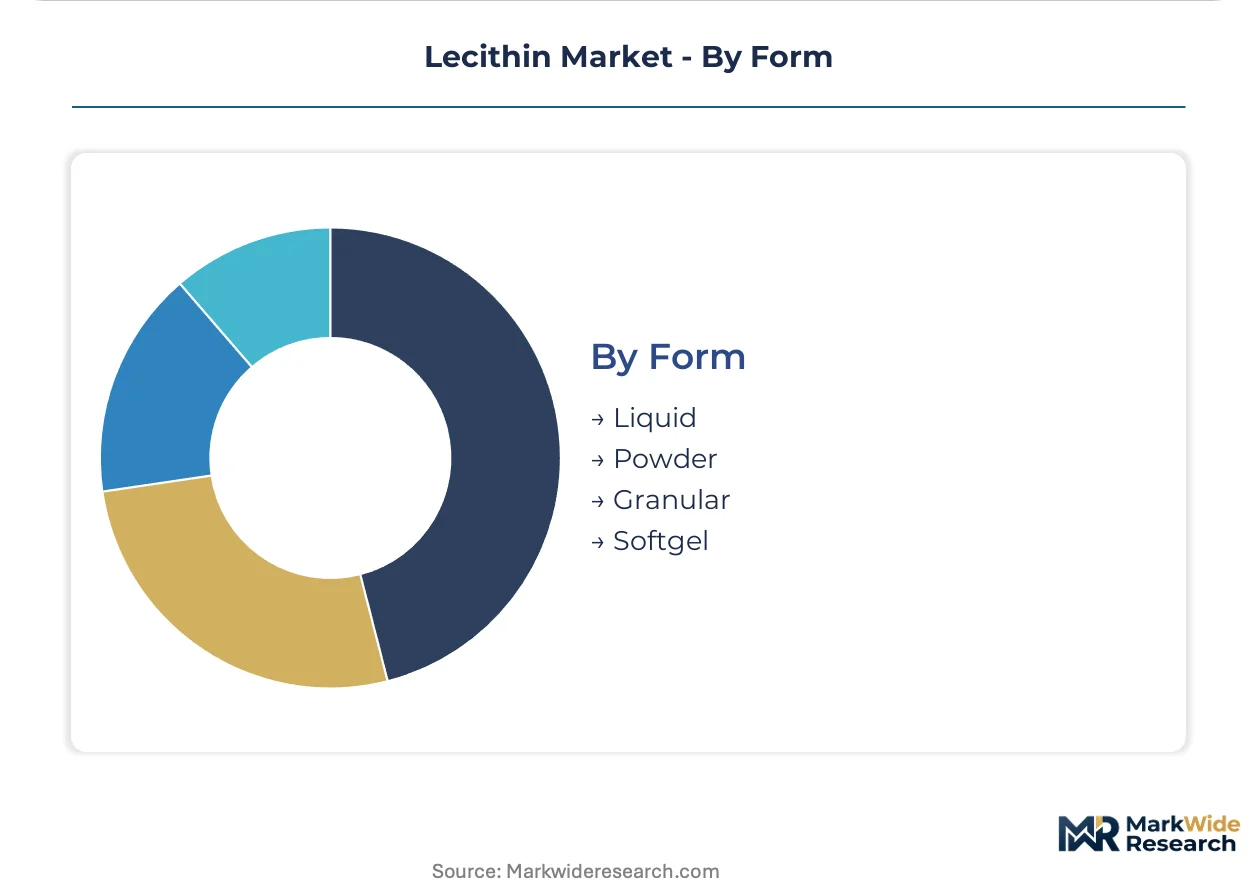
- Liquid:Standard fluid lecithin from crude oil degumming, requiring temperature-controlled storage and pumping infrastructure. Bulk tanker delivery dominates food processor procurement for high-volume emulsifier applications.
- Powder:Spray-dried or acetone-precipitated phospholipid for precise dosing in dry mixes and nutritional supplements. Powdered forms command premium pricing for pharmaceutical and infant nutrition formulations requiring exact unit dosing.
- Granular:Free-flowing agglomerated particles for intermediate handling characteristics.
- Softgel:Pre-formed gelatin capsules containing liquid lecithin for direct consumer supplementation.
Liquid lecithin leads on tonnage throughput; powder lecithin leads on value per kilogram.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing lecithin production geography as processors relocate to jurisdictions with lower compliance costs while maintaining EU REACH-equivalent quality documentation.
Germany
Pharmaceutical-grade phospholipid demand from Merck KGaA and Boehringer Ingelheim drives specialized production in Ludwigshafen and Cologne clusters. EMA lipid excipient master file requirements enforce ISO 22000 and EXCiPACT certification across all qualified suppliers. Lipoid GmbH and Lecico GmbH anchor high-purity manufacturing infrastructure that serves injectable drug delivery formulations across European oncology and vaccine pipelines.
United States
FDA GRAS status for soy and sunflower lecithin sustains emulsifier demand from Cargill Incorporated and Archer-Daniels-Midland Company crushing networks. EPA residual solvent guidelines for hexane degumming operations shape processor compliance investments in Illinois and Iowa oilseed corridors. The Midwest soybean belt maintains commodity lecithin supply dominance through integrated crushing-refining infrastructure.
India
FSSAI edible-grade import standards and tightening BIS contaminant thresholds reshape supplier qualification for bakery and confectionery applications. CDSCO pharmaceutical-grade lipid excipient registration timelines delay market entry for unqualified foreign processors. Maharashtra and Gujarat oilseed crushing clusters expand degumming capacity to capture import substitution opportunities in domestic food processing.
Argentina
Abundant soybean crushing infrastructure in Rosario and Buenos Aires provinces sustains volume supply for international commodity lecithin markets. National agricultural inspection protocols for genetically modified organism documentation align with EU REACH import requirements. Crushing cooperatives and multinational processors compete on traceability systems for European clean-label formulations.
China
NMPA pharmaceutical-grade phospholipid registration and GB standards for food additive purity create dual compliance tracks for domestic and export-oriented processors. Yangtze River Delta oilseed crushing expansion diversifies feedstock beyond traditional soy dependence. Zhejiang and Jiangsu province facilities invest in enzymatic degumming technology to meet EU-bound residual solvent specifications.
Lecithin Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade phospholipid supply consolidating around certified European processors while commodity food-grade lecithin remains fragmented across global oilseed crushers. Three archetypes dominate: integrated agribusiness conglomerates with captive crushing capacity, specialized phospholipid fractionators serving pharmaceutical formulators, and regional oilseed processors competing on traceability documentation. Competitive moves center on backward integration into oilseed crushing and strategic partnerships with pharmaceutical compounders seeking lipid excipient security of supply.
Among integrated agribusiness conglomerates, Cargill Incorporated and Archer-Daniels-Midland Company exemplify scale-driven positioning through captive soybean and sunflower processing networks. Within the specialized phospholipid tier, Lipoid GmbH occupies a position defined by pharmaceutical-grade certification depth and injectable drug delivery formulation expertise. These three companies represent divergent strategic paths: commodity scale, vertical integration, and premium specialization.
| Leading Market Players |
|---|
| Wilmar International Limited |
| Lipoid GmbH |
| Cargill Incorporated |
| American Lecithin Company |
| Sonic Biochem Extractions Pvt. Ltd. |
| Archer-Daniels-Midland Company |
| DuPont de Nemours Inc. |
| Lecico GmbH |
| Bunge Limited |
| Others |
Supply Flow & Price Mechanics
Specialized phospholipid chemist concentrations in Ludwigshafen and Cologne widen labor-cost differentials between pharmaceutical-grade and commodity lecithin tiers, compressing margin spreads for processors lacking EXCiPACT certification infrastructure.
Pricing Analysis
Distributor margins on pharmaceutical-grade phospholipids absorb 15-25% of end-user price points, while direct-to-OEM contracts for commodity food-grade lecithin trade at volume-discounted rates. Three-tier pricing structure across pharmaceutical, food-grade, and feed-grade certification levels anchors differentiation, with ISO 22000 documentation commanding measurable premiums. Cost compression in commodity soy lecithin is intensifying because Black Sea sunflower expansion erodes conventional non-GMO positioning. Food processors exhibit highest price sensitivity; injectable drug developers prioritize supply security over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Cargill Incorporated and Archer-Daniels-Midland Company, bypassing traditional commodity brokers. Supply concentrates in Argentina, Germany, and India for distinct tier requirements—volume soy crushing, pharmaceutical-grade fractionation, and import-substitution edible processing respectively. Raw material flows draw from soybean, sunflower seed, and egg yolk feedstocks, with hexane and ethanol solvent recovery systems representing critical capex dependencies. Single-source vulnerability around German phospholipid clusters creates geographic concentration risk for high-purity grades. Distribution runs through named crushing facility contracts with documented traceability chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Pharmaceutical-grade phosphatidylcholine demand from liposome drug delivery developers is displacing volume-based competition with specification-driven procurement.
For Market Incumbents: Acquire enzymatic degumming technology assets to capture water-degummed oil streams previously lost to low-margin technical grades. Consolidate backward into Black Sea sunflower crushing cooperatives to secure non-GMO feedstock claims against synthetic emulsifier substitution. EMA lipid excipient master file certification represents the priority defensive moat. For New Entrants and Emerging Players: Enter via India FSSAI edible-grade import qualification, where tightening BIS thresholds exclude unqualified traders and favor documented EU suppliers. Target Maharashtra and Gujarat oilseed clusters for domestic crushing partnerships that bypass CDSCO pharmaceutical registration delays. Lead with field-to-facility traceability systems that commodity brokers cannot replicate. For Investors and Strategic Acquirers: Valuations sit cheapest among regional oilseed processors lacking pharmaceutical-grade certification infrastructure but possessing solvent recovery assets convertible to EU REACH compliance. Five-to-ten-year viability hinges on liposome formulation penetration in oncology and vaccine pipelines. Watch enzymatic emulsifier adoption rates in clean-label bakery as the signal for commodity lecithin demand elasticity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Cargill Incorporated secures captive sunflower supply for EU non-GMO positioning. |
| Pharmaceutical-Grade Certification Investment | Lipoid GmbH extends EMA master file coverage into liposome oncology formulations. |
| Enzymatic Degumming Technology Deployment | Processors capture water-degummed streams previously yielding technical-grade only. |
| Direct-to-OEM Procurement Contracts | Large compounders bypass traders with named-facility annual volume agreements. |
| India FSSAI Supplier Qualification | EU processors establish documented traceability for edible-grade import growth. |
Methodological Framework
Multiple input streams — primary interviews with oilseed procurement directors, pharmaceutical formulation scientists, and regulatory affairs specialists; secondary validation through EU REACH substance registrations, FDA GRAS filings, and FSSAI import notifications; customs trade data from Argentina and India — were reconciled through bottom-up volume modeling and top-down market sizing triangulation.
Historical crushing capacity utilization was cross-referenced against panel input from phospholipid fractionation equipment vendors to anchor projections across the analysis window. Segmentation dimensions modeled include extraction source, end-use regulatory tier, physical form, and geographic production hub. CAGRs were derived from elasticity-adjusted demand curves incorporating pharmaceutical liposome pipeline visibility and clean-label food formulation substitution rates.
Inputs from EMA lipid excipient master file databases and CDSCO registration portals were available through the study window; gaps in cell-cultured meat growth medium specifications introduce uncertainty bands around novel application forecasts. Periodic stress-testing of base assumptions regarding enzymatic emulsifier substitution velocity and EU Green Deal bioeconomy subsidy durability is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Anti-Caking Market
Food Additives and Ingredients
Brazil Food Ingredient Market
Food Additives and Ingredients
Italy Food Acidulants Market
Food Additives and Ingredients
Plant Based Preservatives Market
Food Additives and Ingredients
Spain Food Preservatives Market
Food Additives and Ingredients
Russia Food Preservatives Market
Food Additives and Ingredients
Australia Food Additives Market
Food Additives and Ingredients
Oleic Acid Market
Food Additives and Ingredients
Ammonia Caramel Market
Food Additives and Ingredients
Anti-Caking Agents Market
Food Additives and Ingredients
Sucroglycerides Market
Food Additives and Ingredients
South America Feed Additives Market
Food Additives and Ingredients
Wheat & Rice Flour Substitute-Resistant Starch Market
Food Additives and Ingredients
Canada Food Preservatives Market
Food Additives and Ingredients
Food Inclusions Market
Food Additives and Ingredients
China Food Enzymes Market