
 Feed Anti-Caking Agents Market | 2026-2036
Feed Anti-Caking Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Feed Anti-Caking Agents Market Analysis
European silicate producers is decoupling from traditional phosphate-linked supply chains as energy costs reshape mineral processing economics. Solvay SA leverages synthetic amorphous silica expertise to anchor premium positioning in moisture-sensitive aquaculture formulations. Cargill Incorporated sustains backward integration into mineral sourcing, controlling quality consistency across its compound feed network. BASF SE differentiates through surface-modified silica technologies that reduce dosage rates in pelleted ruminant diets.
Feed anti-caking agents are inorganic or organic compounds, typically silica-based minerals or carbonate salts, added at 0.5-2.0% inclusion rates to prevent particle agglomeration during storage and transport. Their primary function is preserving free-flow properties in hygroscopic feed ingredients exposed to variable humidity. Silica products command the widest formulation penetration due to high adsorptive surface area and thermal stability during pelleting at 80-90°C. Powder forms retain volume leadership across bulk commodity feed channels, though granule grades are gaining share in automated dosing systems where dust minimization determines operational compliance. Application concentration tilts toward livestock feeds, where tonnage scale and extended storage cycles amplify clumping losses.
The European Food Safety Authority (EFSA) and the US Food and Drug Administration (FDA) enforce divergent purity thresholds for mineral carriers, compelling producers to maintain dual certification streams for cross-Atlantic supply. China's Ministry of Agriculture and Rural Affairs (MARA) implemented revised feed additive catalogues that reclassify certain silicate grades, reshaping import qualification pathways for foreign suppliers. India's Food Safety and Standards Authority of India (FSSAI) is aligning feed mineral standards with Codex Alimentarius frameworks, tightening heavy metal limits that directly affect calcium carbonate sourcing from geological deposits. Stakeholders must monitor evolving maximum residue limits for trace contaminants as regulatory jurisdictions tighten analytical detection protocols without harmonized transition timelines.
Market Dynamics
Energy cost volatility is fragmenting mineral processing economics across silicate and carbonate supply chains, forcing producers to relocate calcination capacity toward stranded gas assets or abandon phosphate-linked integration entirely.
Growth Catalysts
- Tropical Storage Expansion:Brazil's compound feed sector is scaling silica-based additive programs to combat moisture-driven clumping in high-humidity warehousing corridors.
- EFSA Purity Benchmarks:Tighter EU Feed Hygiene Regulation thresholds are accelerating replacement of ungraded mineral carriers with certified silicate grades in cross-border trade.
- Pelleting Temperature Tolerance:Surface-modified silica technologies are penetrating ruminant feed formulations by maintaining adsorptive stability at 80-90°C processing windows.
Market Restraints
- Energy Input Volatility:Natural gas and electricity price spikes are compressing margins for synthetic amorphous silica producers dependent on high-temperature precipitation processes.
- Supply Concentration Risk:Granule-grade conditioning agent production clusters heavily in China's Shandong province, creating single-point vulnerability for automated dosing system suppliers.
- Divergent Certification Burden:EFSA and FDA maintain non-harmonized heavy metal thresholds, forcing dual-stream compliance costs on mineral carrier exporters.
Strategic Opportunities
- Aquaculture Formulation Premiums:Moisture-sensitive shrimp and fish feed producers in Southeast Asia represent underpenetrated demand for high-purity synthetic silicates.
- Automated Dosing Adoption:Dust-minimizing granule grades are capturing share in European compound feed mills upgrading to enclosed pneumatic transfer systems.
- India FSSAI Alignment:Codex-linked heavy metal limits are opening import pathways for certified calcium carbonate suppliers meeting tightened geological deposit standards.
Industry Challenges
- Dual Certification Timelines:Cross-Atlantic suppliers face non-synchronized analytical detection protocol transitions without harmonized grace periods from EFSA or FDA.
- Surface Chemistry Expertise Gap:Formulation of dosage-reducing modified silicates requires specialized colloid science talent scarce in traditional mineral processing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feed Anti-Caking Agents Market |
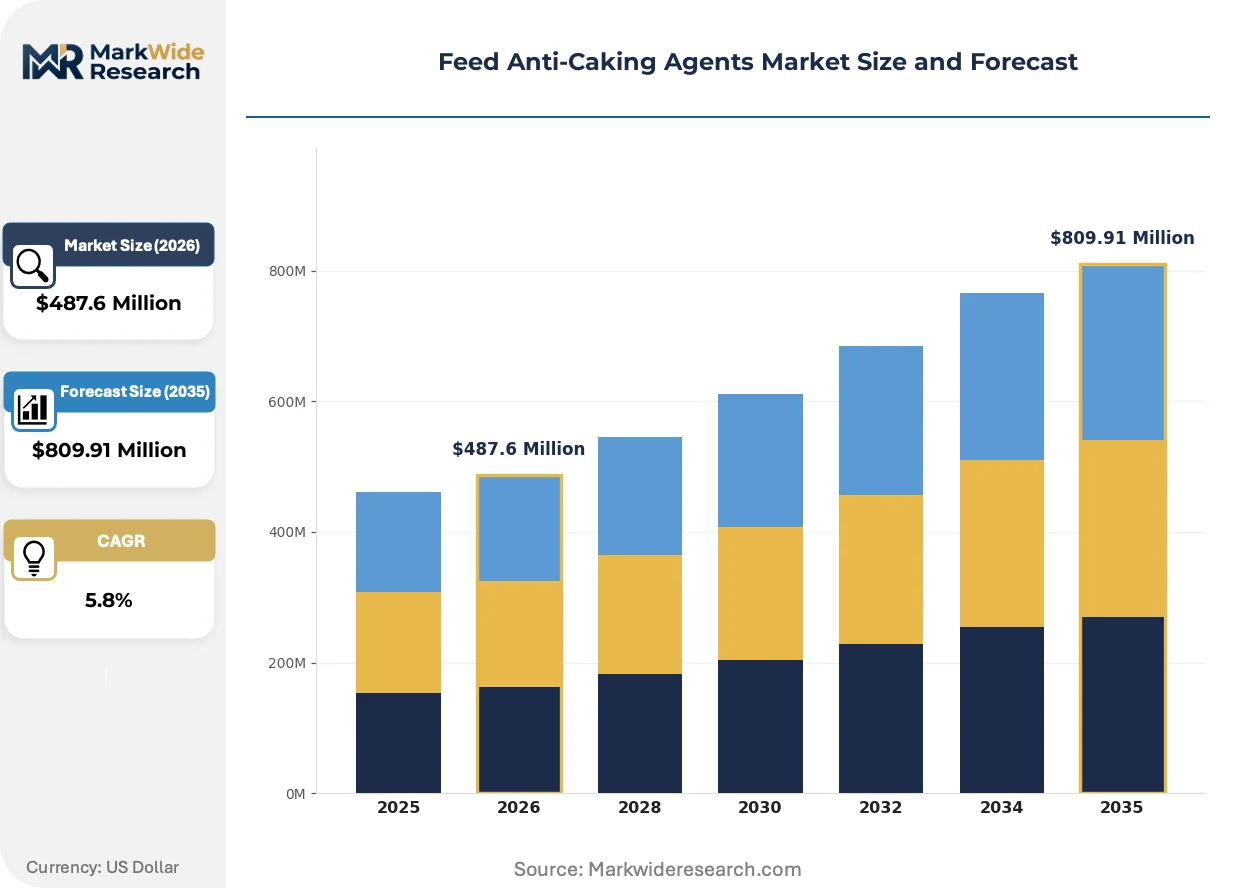
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Carbonate, Sodium Bicarbonate, Magnesium Oxide, Silica Application: Animal Feed, Pet Food, Aquaculture, Livestock Form: Powder, Granules, Pellets, Liquid End User: Farmers, Feed Manufacturers, Distributors, Retailers |
| Companies Covered | Solvay SA, Cargill Incorporated, J.M. Huber Corporation, Brenntag AG, PQ Corporation, BASF SE, Bentonite Performance Minerals LLC, Univar Solutions Inc., Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feed Anti-Caking Agents Market Emerging Trajectories
Synthetic amorphous silica is displacing natural diatomaceous earth across premium feed formulations as surface engineering capabilities advance. Regulatory jurisdictions are tightening trace contaminant thresholds without coordinating implementation calendars. Procurement concentration among integrated feed mill networks is compressing supplier negotiation leverage.
Surface-modified silica technologies are consolidating formulation share in pelleted ruminant diets by enabling 15-30% dosage reduction without flowability loss. Large compound feed producers in North America and Europe are adopting these grades fastest, driven by cost-per-ton optimization targets. The technology is consolidating supplier margins toward performance-premium tiers and away from commodity mineral carriers.
REACH and EU Feed Hygiene Regulation amendments are tightening purity documentation requirements for mineral carriers entering the animal nutrition chain. Producers must now maintain batch-level heavy metal certificates across divergent EFSA and national competent authority interpretations. Aquaculture formulation suppliers face the steepest compliance burden due to extended residue testing protocols for export-certified shrimp and fish feeds.
Integrated feed mill consolidation in China's Shandong province is compressing procurement channels for granule-grade anti-caking agents. Buyers are shifting from spot-market mineral sourcing toward multi-year conditioning agent contracts with embedded quality consistency guarantees. This behavioral shift is most visible in livestock feed channels where tonnage scale and extended storage cycles amplify clumping loss risks.
Feed Anti-Caking Agents Market Segmentation
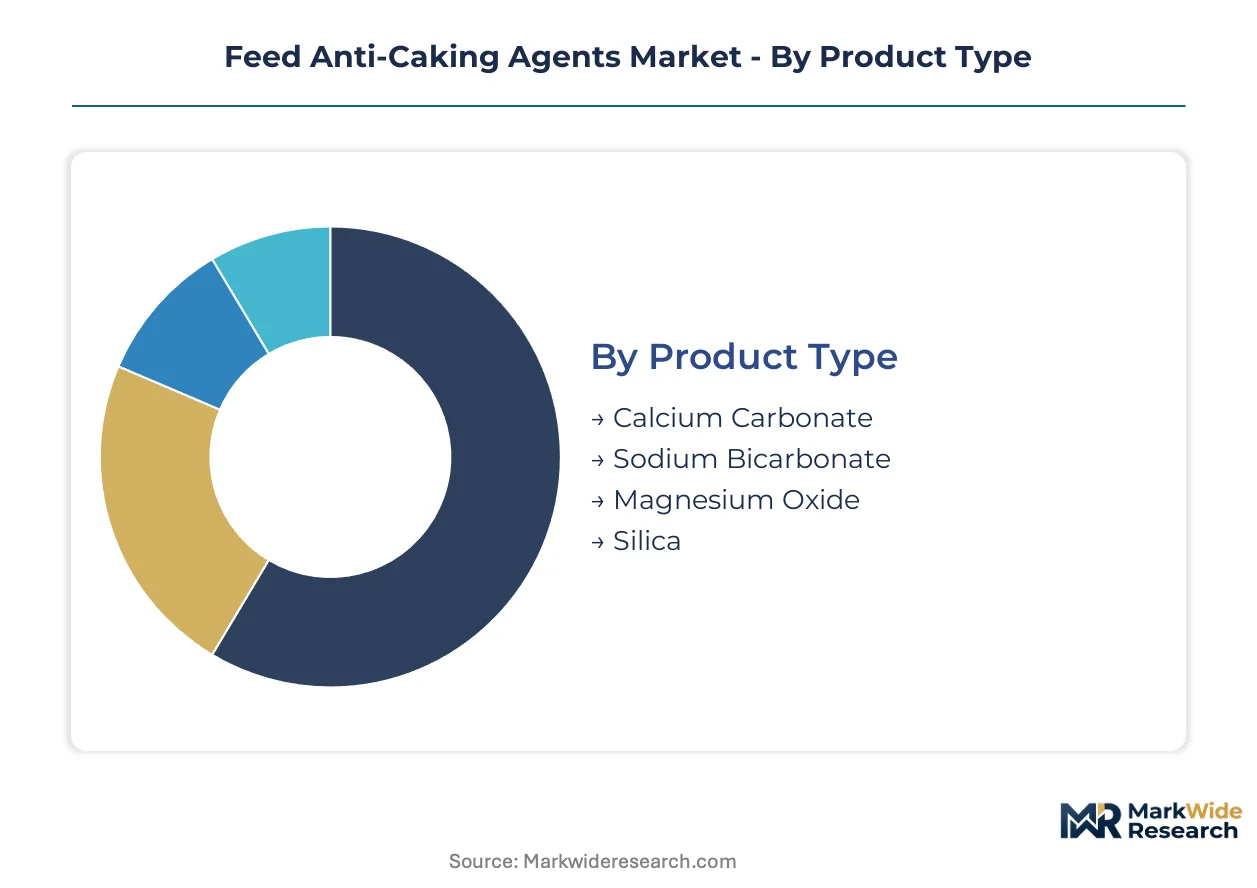
Segmentation in feed anti-caking agents reveals how formulation requirements diverge across climate zones, processing temperatures, and automation levels. Buyers prioritize surface area specifications in tropical storage environments while automated dosing systems drive granule-grade procurement decisions.
Product Type:
Cost tiers separate commodity mineral carriers from engineered synthetic grades with performance premiums.
- Silica:Synthetic amorphous silica delivers the highest adsorptive surface area among mineral carriers, maintaining flowability under 80-90°C pelleting stress. Demand concentrates in Brazil's tropical warehousing corridors where moisture-driven clumping risks are most acute. Surface-modified variants enable dosage reduction in ruminant formulations without sacrificing adsorptive capacity.
- Calcium Carbonate:Geologically sourced calcium carbonate offers the lowest unit cost among anti-caking minerals, though heavy metal certification requirements are tightening under India's FSSAI alignment with Codex standards. Procurement in China and India increasingly requires batch-level contaminant documentation for cross-border feed trade.
- Sodium Bicarbonate:This carbonate salt provides mild alkalinity control alongside anti-caking functionality in poultry layer feeds.
- Magnesium Oxide:High-purity magnesite grades serve niche ruminant buffer applications with dual nutritional purpose.
Silica leads volumes today; surface-modified silica grades are expanding most quickly in premium formulations.
Application:
Application segmentation tracks where extended storage cycles and humidity exposure create the steepest clumping losses.
- Livestock:Cattle, swine, and poultry feeds consume the largest tonnage of anti-caking agents due to bulk commodity scale and multi-week storage intervals. Compound feed mills in China's Shandong province consolidate procurement of granule-grade conditioning agents for automated dosing in enclosed pneumatic systems.
- Aquaculture:Shrimp and fish feed producers in Southeast Asia represent underpenetrated demand for high-purity synthetic silicates, where moisture sensitivity in export-certified formulations commands performance premiums. Extended residue testing protocols under EU and Japanese import standards raise compliance burdens for mineral carrier suppliers.
- Animal Feed:General-purpose feed channels span multiple species with standardized inclusion rates.
- Pet Food:Premium kibble and extruded formulations require cosmetic-grade mineral carriers with dust-minimizing properties.
Livestock dominates tonnage; aquaculture offers the steepest margin expansion trajectory.
Form:
Form selection hinges on operational compliance requirements in material handling systems.
- Powder:Fine-ground mineral powders retain volume leadership across bulk commodity feed channels where cost-per-ton optimization governs procurement. Dust generation during pneumatic transfer creates occupational exposure liabilities that European compound feed mills increasingly refuse to absorb.
- Granules:Dust-minimizing granule grades are capturing share in automated dosing systems where enclosed pneumatic transfer determines operational compliance. China's Shandong province concentrates production capacity for granule-grade conditioning agents, creating single-point supply vulnerability.
- Pellets:Pre-agglomerated carrier forms suit specialized ruminant mineral premix applications.
- Liquid:Suspension-based anti-caking systems serve niche aquaculture feed coating processes.
Powder retains volume leadership; granules are climbing the fastest in automated European mills.
End User:
End user segmentation reflects consolidation pressure across the feed value chain.
- Feed Manufacturers:Integrated compound feed mills in North America and Europe drive specification-setting for surface-modified silica technologies, leveraging multi-year conditioning agent contracts with embedded quality guarantees. Procurement concentration compresses supplier negotiation leverage toward performance-premium tiers.
- Farmers:On-farm feed mixing operations in developing markets source commodity-grade mineral carriers through distributor networks with limited technical specification requirements.
- Distributors:Wholesale mineral traders manage inventory across multiple certification streams for EFSA and FDA divergent thresholds.
- Retailers:Specialty pet food retailers influence cosmetic-grade mineral sourcing for premium positioning.
Feed manufacturers command specification authority; farmer-direct procurement is gaining share fastest in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting anti-caking agent production toward jurisdictions with lower energy costs and streamlined mineral certification pathways. Producers are relocating calcination capacity to stranded gas assets while abandoning phosphate-linked integration models that no longer pencil out under European energy pricing.
United States
Compound feed manufacturers in the Midwest and Southeast are scaling automated dosing systems that favor dust-minimizing granule grades. FDA maintains divergent heavy metal thresholds from EFSA, forcing dual-stream compliance on mineral carrier exporters serving cross-Atlantic trade. Iowa and Illinois concentrate procurement authority among integrated feed mill networks consolidating multi-year conditioning agent contracts.
Brazil
Tropical storage corridors in São Paulo and Paraná are driving silica-based additive adoption to combat moisture-driven clumping in high-humidity warehousing. ANVISA aligns feed mineral standards with Codex frameworks, tightening purity documentation for imported carbonate carriers. Compound feed producers in the Center-West region are expanding additive programs as soybean meal exports amplify storage cycle risks.
Germany
REACH amendments and EU Feed Hygiene Regulation tightening are accelerating replacement of ungraded mineral carriers with certified silicate grades. EFSA purity benchmarks now require batch-level heavy metal certificates across divergent national competent authority interpretations. Industrial clusters in North Rhine-Westphalia and Bavaria concentrate surface-modified silica formulation expertise for premium ruminant feed applications.
China
Shandong province anchors granule-grade conditioning agent production capacity, creating single-point supply vulnerability for automated dosing system suppliers. MARA's revised feed additive catalogues reclassify certain silicate grades, reshaping import qualification pathways for foreign suppliers. Integrated feed mills in the Yangtze River Delta are consolidating procurement away from spot-market mineral sourcing toward multi-year contracts with embedded quality guarantees.
India
FSSAI alignment with Codex Alimentarius frameworks is tightening heavy metal limits that directly affect calcium carbonate sourcing from geological deposits. Poultry layer feed producers in Maharashtra and Gujarat represent expanding demand for mild alkalinity control alongside anti-caking functionality. Batch-level contaminant documentation is becoming mandatory for cross-border feed trade with Middle Eastern and Southeast Asian markets.
Feed Anti-Caking Agents Market Vendor Landscape
European producers anchor the premium synthetic silica tier; Chinese specialists hold volume leadership in granule-grade conditioning agents. The vendor base splits between consolidated multinational chemical conglomerates with mineral processing heritage and regional mineral traders serving spot-market procurement channels. Three archetypes dominate: surface chemistry innovators commanding performance premiums, backward-integrated feed conglomerates controlling captive mineral sourcing, and commodity mineral traders managing inventory across multiple certification streams. Competitive moves concentrate on M&A to secure geological deposit access and technology licensing to bridge surface-modification expertise gaps.
Within the premium synthetic tier, Solvay SA and Evonik Industries AG exemplify European chemical conglomerates leveraging colloid science capabilities for moisture-sensitive formulation positioning. Cargill Incorporated occupies a distinct archetype as a feed-sector incumbent with captive mineral sourcing integration. BASF SE and PQ Corporation represent diversified chemical producers with mineral processing heritage extending into surface-modified silica technologies. These groupings illustrate how competitive positioning stratifies between performance-premium innovators and scale-driven commodity suppliers.
| Leading Market Players |
|---|
| Solvay SA |
| Cargill Incorporated |
| J.M. Huber Corporation |
| Brenntag AG |
| PQ Corporation |
| BASF SE |
| Bentonite Performance Minerals LLC |
| Univar Solutions Inc. |
| Evonik Industries AG |
| Others |
Supply Flow & Price Mechanics
Natural gas price benchmarks cascade through synthetic amorphous silica production economics, compressing margins for European calcination facilities while rewarding producers with access to stranded gas assets in the Middle East and North America. This input-cost divergence stratifies pricing tiers across mineral carrier grades, with surface-modified silicates commanding performance premiums as ungraded carbonates face downward pressure from energy-intensive processing.
Pricing Analysis
Distributor margins absorb the steepest compression as integrated feed manufacturers leverage multi-year conditioning agent contracts to bypass wholesale channels entirely. Three-tier pricing structure across premium, standard, and economy levels separates surface-modified synthetic silicates from natural diatomaceous earth and ungraded calcium carbonate, with certification grade under EFSA and FDA dual-stream requirements driving the widest spreads. Pricing pressure stems from energy input volatility in high-temperature precipitation processes, eroding margins for synthetic producers without captive gas supply. Compound feed mills in developed markets exhibit lowest price sensitivity, prioritizing dosage reduction and quality consistency over unit cost, while spot-market buyers in emerging markets remain highly elastic.
Supply Chain Analysis
Dual-sourcing mandates from European compound feed manufacturers now require qualified suppliers across at least two regulatory jurisdictions to mitigate single-point failure risks. Production gravity centers on China for granule-grade conditioning agents, Germany for surface-modified silica expertise, and Brazil for tropical-storage-optimized formulations. Raw material flows draw from sedimentary silica deposits, synthetic precipitation feedstocks, and geological carbonate reserves. Single-source vulnerability concentrates in Shandong province's granule-grade capacity, where any disruption cascades through automated dosing system supply chains. Distribution runs through integrated feed mill procurement networks that are consolidating away from mineral traders toward direct manufacturer relationships with embedded quality guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as procurement concentration among integrated feed mills shifts specification authority toward performance-premium grades and away from commodity mineral carriers. The demand pivot toward surface-modified silicates with dosage-reduction capabilities justifies this framing.
For Market Incumbents: Anticipate margin compression in ungraded mineral carriers as energy costs reshape processing economics, forcing consolidation of calcination capacity toward stranded gas assets. Defensive positioning requires deepening backward integration into geological deposit access and accelerating certification investments for EFSA-FDA dual-stream compliance. Surface chemistry expertise gaps present the most acute threat as formulation demands shift toward colloid-science-intensive modified silicates. For New Entrants and Emerging Players: Enter via aquaculture formulation channels in Southeast Asia, where moisture-sensitive shrimp and fish feed producers remain underpenetrated by high-purity synthetic silicates. White-space targets include granule-grade production capacity outside China's Shandong province and certified calcium carbonate sourcing for India's FSSAI-aligned import pathways. A technical-service-led go-to-market approach, emphasizing dosage optimization and residue-testing protocol navigation, offers the strongest beachhead against established mineral traders. For Investors and Strategic Acquirers: Asymmetric upside sits with surface-chemistry innovators possessing colloid science capabilities applicable across moisture-sensitive formulations. Long-term viability favors producers with captive mineral sourcing and multi-jurisdictional certification infrastructure that can withstand regulatory divergence without duplicative compliance costs. The signal to watch is procurement contract duration extension among integrated feed mills, indicating successful embedding of quality guarantees and pricing power stabilization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Geological Deposits | Captive silica and carbonate sourcing insulates margins from commodity volatility and certification bottlenecks. |
| Surface Modification Technology Licensing | Colloid science partnerships bridge expertise gaps for traditional mineral processors seeking dosage-reduction positioning. |
| Multi-Jurisdictional Certification Infrastructure | Dual EFSA-FDA compliance streams unlock cross-Atlantic trade without duplicate analytical protocol investments. |
| Granule-Grade Capacity Expansion | Automated dosing system adoption in European and North American mills captures dust-minimization compliance premiums. |
| Aquaculture Formulation Technical Service Buildout | Residue-testing protocol navigation and moisture-optimization consulting penetrate Southeast Asian export-certified feed channels. |
Methodological Framework
Bottom-up livestock and aquaculture feed modeling reconciled against top-down mineral processing capacity tracking forms the analytical core of this study. Primary interviews with compound feed procurement directors, mineral carrier plant managers, regulatory affairs specialists at additive suppliers, and distribution channel partners were validated against secondary sources including EFSA guidance documents, FDA CFR Title 21 feed additive regulations, MARA catalogues, customs trade data, and SEC filings from diversified chemical producers. Triangulation between demand-side specification trends and supply-side capacity investments ensures coherence across volume and value estimates.
Input-output matrices map silica and carbonate grade production through pelleting temperature tolerances, surface area specifications, and automated dosing compatibility requirements across the projection horizon. Segmentation dimensions modeled include product type, application species, physical form, and end-user consolidation tier, with CAGRs derived from elasticity-adjusted demand curves and capacity utilization trajectories. Industry-specific forecast inputs incorporate regulatory transition timelines for heavy metal threshold harmonization and energy cost scenarios for calcination economics.
Inputs from regulatory filings and trade databases were available through the study window; gaps in real-time procurement contract terms and undisclosed surface-modification process yields introduce uncertainty bands around supplier margin estimates. Deviation in EFSA-FDA synchronization timelines or abrupt natural gas price shocks would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Argentina Food Enzymes Market
Food Additives and Ingredients
Anti-Caking Agents Market
Food Additives and Ingredients
Australia Food Colorants Market
Food Additives and Ingredients
Europe Food Emulsifiers Market
Food Additives and Ingredients
Activated Cake Emulsifier Market
Food Additives and Ingredients
Gelatin Films Market
Food Additives and Ingredients
Neohesperidin Market
Food Additives and Ingredients
Mexico Anti Caking Market
Food Additives and Ingredients
Quillaja Saponaria Ingredient Market
Food Additives and Ingredients
Food Grade Sodium Selenite Market
Food Additives and Ingredients
Bread Preservatives Market
Food Additives and Ingredients
Egg Wash Substitute Market
Food Additives and Ingredients
China Food Additives Market
Food Additives and Ingredients
Mexico Food Preservatives Market
Food Additives and Ingredients
Germany Anticaking Market
Food Additives and Ingredients
India Food Color Industry Market