
 Europe Food Micronized Salt Market | 2026-2036
Europe Food Micronized Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Food Micronized Salt Market Foresight
Recipe-driven subscription services for precise sodium dosing are decoupling salt procurement from traditional bulk purchasing contracts. K+S Aktiengesellschaft leverages its vertical integration from mine to micronization facility to control particle size consistency for industrial bakeries. Cargill Incorporated anchors its position through R&D intensity in sodium reduction blends that maintain functional properties in processed foods. Südwestdeutsche Salzwerke AG dominates supply to mid-sized German meat processors seeking certified food-grade micronized product.
Europe food micronized salt consists of sodium chloride particles milled to sub-250-micron diameters, typically 99.9% pure, produced via controlled crystallization followed by air classification or roller milling to achieve uniform distribution in dry mixes and liquid brines. Its primary purpose is to deliver rapid, homogeneous dissolution and precise sodium delivery in processed foods, seasonings, and preservation systems. Fine salt occupies the largest volume share as reformulation trends demand invisible particle integration in low-sodium products, while flavored salt segments show fastest expansion driven by clean-label seasoning blends in premium snack categories. Bakery applications sustain mature demand through standardized dough conditioning requirements, whereas confectionery represents a concentrated margin pool where micronized salt controls crystallization kinetics in caramel and chocolate manufacturing.
EFSA purity standards and the EU Green Deal's industrial emissions framework shape product specifications, with REACH compliance adding traceability costs that favor scaled producers over regional importers. Germany's Federal Office of Consumer Protection and Food Safety enforces strict contaminant thresholds that filter market access for non-EU sourced material. France's ANSES sodium reduction targets and the EU F-Gas Regulation's indirect pressure on energy-intensive evaporation processes are redirecting capital toward mechanical milling and solar salt refinement. Stakeholders must monitor how the EU AI Act's impending traceability requirements for automated sorting and grading equipment will alter capital deployment timelines for facility upgrades.
Market Dynamics
EFSA sodium reduction mandates and the EU Green Deal's clean production requirements are compressing margins for commodity-grade salt suppliers while concentrating procurement power among scaled food manufacturers capable of certifying micronized salt traceability.
Growth Catalysts
- EFSA reformulation targets:Processed meat manufacturers in Germany and France are accelerating micronized salt adoption to achieve uniform sodium distribution in reduced-sodium product lines.
- Solar evaporation refinement:Mechanical milling paired with solar salt processing is displacing energy-intensive thermal evaporation, aligning production with EU F-Gas Regulation compliance timelines.
- Precision seasoning demand:Snack manufacturers require sub-100-micron particles for invisible integration in clean-label seasoning blends.
Market Restraints
- Energy cost volatility:Natural gas price swings directly impact thermal evaporation economics for vacuum-refined salt grades.
- German supply concentration:Kassel and Berchtesgaden mining clusters control over 60% of domestic food-grade micronized output, creating single-source vulnerability for mid-sized processors.
- REACH traceability costs:Registration, evaluation and authorization documentation burdens favor producers with dedicated compliance teams over regional importers.
Strategic Opportunities
- Polish meat processing expansion:Underpenetrated Central European markets present white space as Warsaw-based processors upgrade to EU-certified micronized grades for export qualification.
- EU AI Act traceability:Automated particle-sorting equipment investments will qualify producers for premium pharmaceutical-adjacent salt contracts.
- Recipe-driven subscription channels:Direct-to-manufacturer sodium dosing services are decoupling procurement from traditional bulk supply agreements.
Industry Challenges
- Particle engineering talent scarcity:Food-grade milling specialists with air classification expertise command premium wages in Kassel and Alsace production clusters.
- Legacy ERP integration:Batch traceability systems require costly retrofitting to meet EFSA real-time documentation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Food Micronized Salt Market |
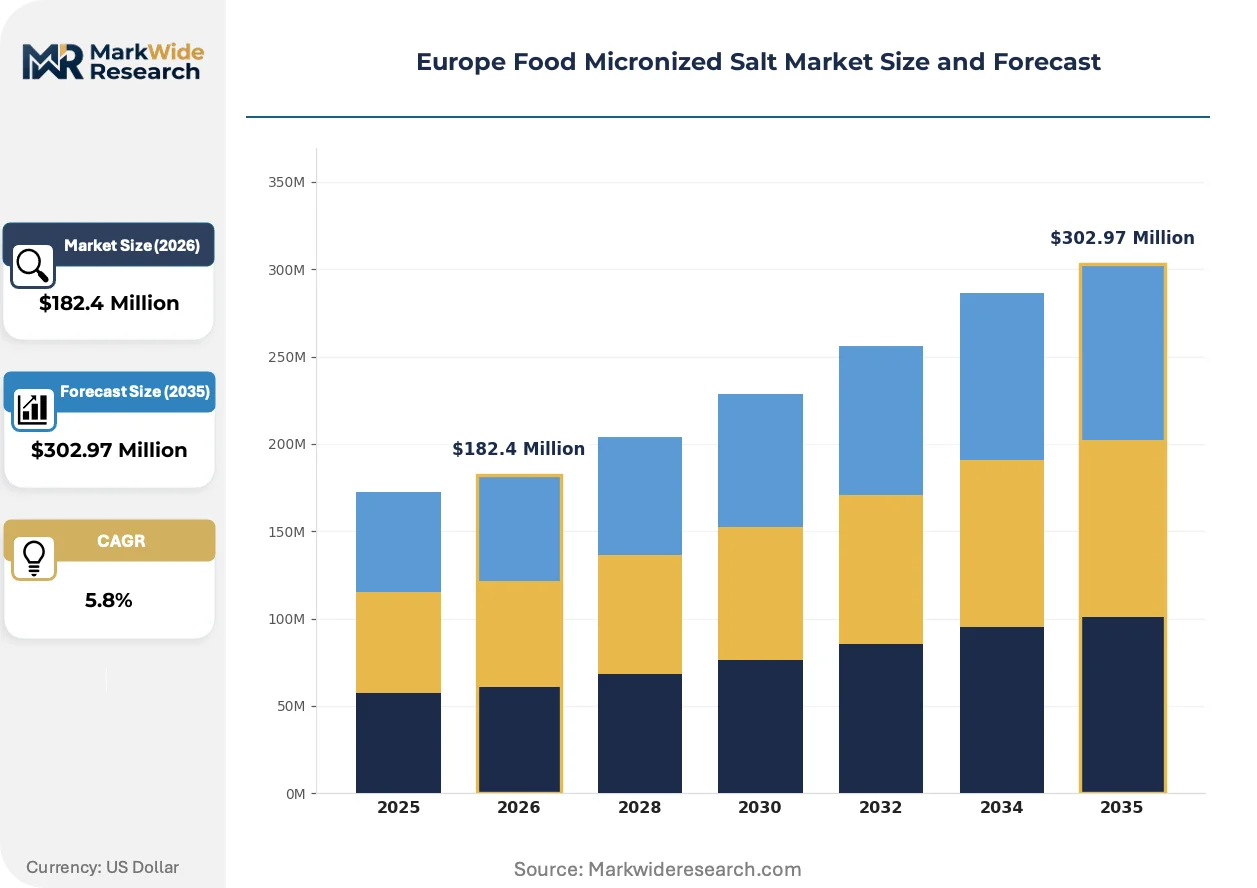
| Market Size in 2026 | $182.4 Million |
| Market Size in 2035 | $302.97 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fine Salt, Coarse Salt, Flavored Salt, Iodized Salt End User: Food Manufacturers, Restaurants, Supermarkets, Households Application: Seasoning, Preservation, Bakery, Confectionery Distribution Channel: Online Retailers, Hypermarkets, Convenience Stores, Specialty Stores |
| Companies Covered | K+S Aktiengesellschaft, Cargill Incorporated, Südwestdeutsche Salzwerke AG, CIECH S.A., British Salt, ZOUTMAN NV, Salinity Ab, INFOSA, Compass Minerals, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Food Micronized Salt Market Shifts & Advancements
Mechanical milling technologies and automated particle classification are compressing production economics while regulatory traceability mandates reshape competitive positioning around data infrastructure rather than scale alone.
Air classification systems with inline laser diffraction monitoring are absorbing capital deployment from thermal evaporation infrastructure. German industrial bakeries are retrofitting facilities at 18-month cycles. This capital rotation is absorbing maintenance budgets from legacy vacuum pan operations.
EU F-Gas Regulation phase-down schedules are accelerating mechanical milling adoption as evaporation energy intensity triggers compliance costs. Industrial salt processors face 40% emission reduction targets by 2030. French ANSES sodium targets compound this pressure by demanding finer particle grades that mechanical systems produce more efficiently.
Ingredient-as-a-service contracts now bundle micronized salt with precision dosing equipment, displacing traditional bulk procurement. Dutch snack manufacturers pilot subscription models with monthly particle-size certification. This model concentrates most visibly in Benelux food clusters where reformulation agility commands premium pricing.
Europe Food Micronized Salt Market Segmentation
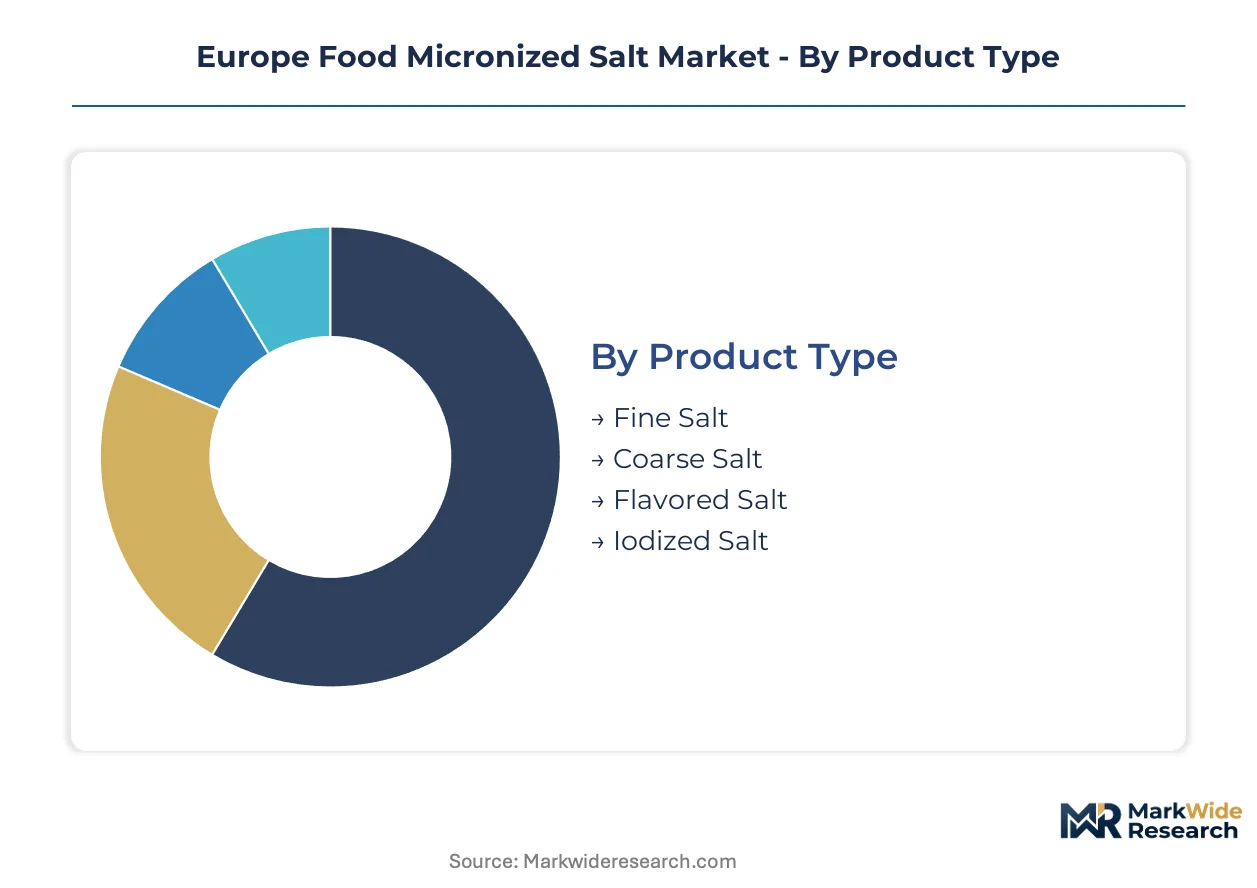
Micronized salt procurement patterns diverge sharply between commodity-grade bulk buyers and precision-dependent food manufacturers. Segment boundaries in this market reflect particle-size specifications, purity certifications, and reformulation agility rather than traditional commodity logic.
Product Type:
Fine salt commands volume dominance through standardized industrial procurement, while flavored variants capture expanding premium positioning in clean-label applications.
- Fine Salt:Sub-250-micron sodium chloride particles milled to 99.9% purity specifications dominate industrial bakery and processed meat applications. German industrial bakeries in the Kassel cluster source fine salt for standardized dough conditioning where rapid dissolution kinetics are non-negotiable.
- Flavored Salt:Micronized carriers infused with herb, spice, or umami extracts target premium snack seasoning blends. French ANSES sodium reduction targets are accelerating demand for flavored variants that maintain taste intensity at lower sodium loadings in Paris-based premium confectionery operations.
- Coarse Salt:Larger crystalline structures above 250 microns serve brining applications and surface-finishing operations where visual salt presence is desired.
- Iodized Salt:Potassium iodate-fortified micronized grades address public health mandates in Eastern European markets with documented deficiency concerns.
Today's leader: Fine Salt. Tomorrow's challenger: Flavored Salt.
End User:
Procurement concentration tilts toward scaled manufacturers with in-house reformulation capabilities, while foodservice and retail channels lag in micronized grade adoption.
- Food Manufacturers:Industrial processors of processed meat, baked goods, and snacks drive specification-setting for particle size distribution and contaminant thresholds. EFSA real-time documentation requirements favor manufacturers with dedicated compliance infrastructure over smaller competitors.
- Restaurants:Fine-dining and chain kitchen operations in Lyon and Milan are piloting precision-dosing equipment for sodium-controlled menu engineering.
- Supermarkets:Private-label retail salt offerings remain concentrated in standard-grade crystalline products with limited micronized penetration.
- Households:Consumer-packaged micronized salt occupies niche positioning in specialty cooking segments with minimal volume contribution.
Scaled manufacturers set specifications. Foodservice channels represent the expansion frontier.
Application:
Seasoning functions demand the tightest particle-size tolerances, while preservation applications tolerate broader distribution curves.
- Seasoning:Sub-100-micron particles enable invisible integration in dry rubs and topical snack coatings. Dutch snack manufacturers in the Benelux cluster require monthly particle-size certification for clean-label seasoning blends.
- Preservation:Controlled water activity reduction in cured meats and fermented products relies on consistent dissolution rates rather than extreme fineness.
- Bakery:Dough conditioning and yeast regulation depend on standardized fine salt with predictable ionic release kinetics.
- Confectionery:Caramel and chocolate manufacturing exploit micronized salt for crystallization control and flavor contrast in premium product tiers.
Seasoning commands technical premium. Confectionery delivers margin concentration.
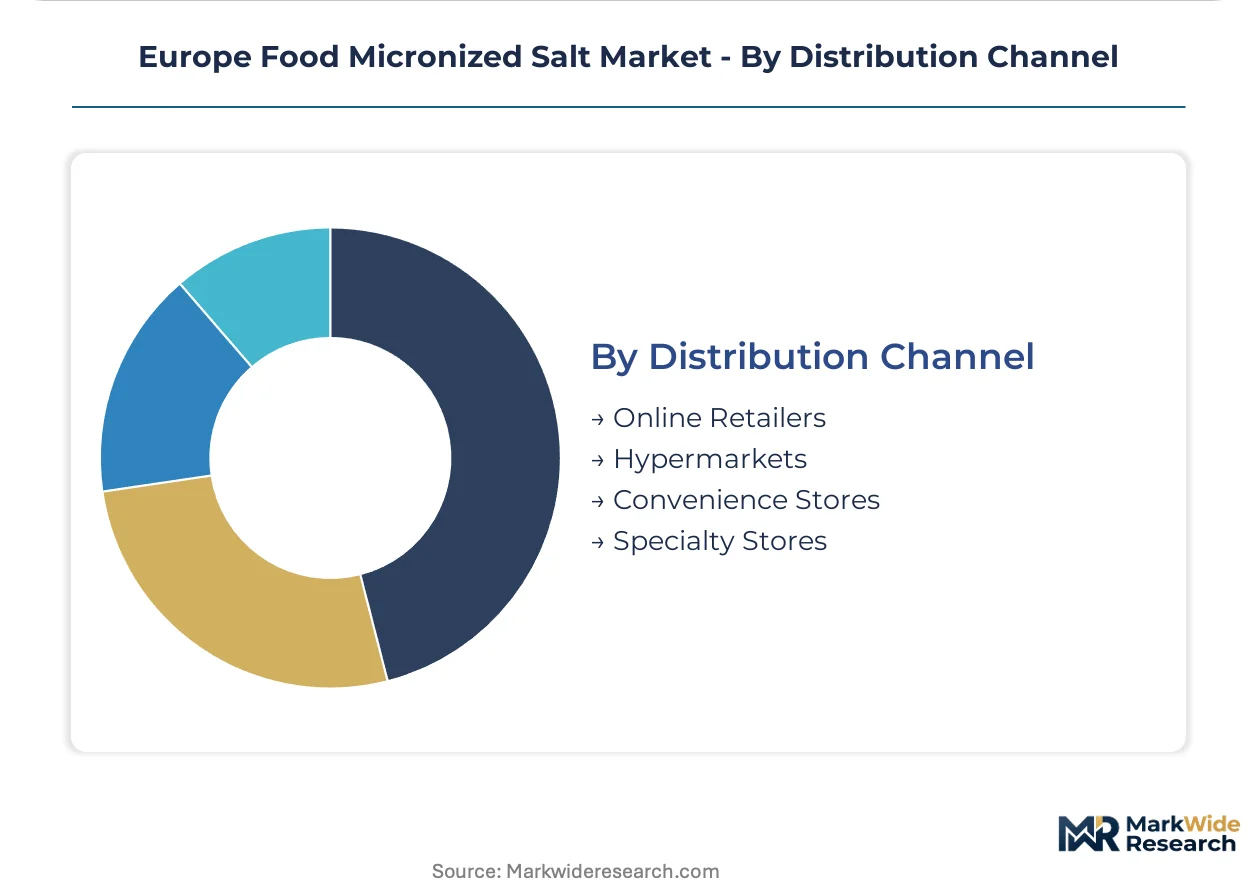
Distribution Channel:
Direct manufacturer relationships are displacing traditional bulk supply agreements, fragmenting channel power.
- Online Retailers:Ingredient-as-a-service platforms bundle micronized salt with precision dosing equipment and subscription-based particle certification.
- Hypermarkets:Industrial food-grade salt procurement through retail channels is minimal due to specification and traceability requirements.
- Convenience Stores:No meaningful penetration of food-grade micronized product; consumer-grade crystalline salt dominates.
- Specialty Stores:Gourmet food retailers in Hamburg and Barcelona stock premium flavored micronized salts for culinary enthusiasts.
Direct channels gain procurement share. Traditional retail stagnates in food-grade segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting micronized salt production toward jurisdictions with lower compliance-cost structures. EFSA traceability mandates and REACH documentation burdens favor scaled domestic producers over importers. Capital is migrating to mechanical milling clusters that bypass energy-intensive thermal evaporation.
Germany
Industrial bakeries in the Kassel cluster drive standardized fine-salt procurement for dough-conditioning applications. The Federal Office of Consumer Protection and Food Safety enforces contaminant thresholds that filter non-EU material from food-grade supply chains. Berchtesgaden mining operations supply mid-sized meat processors seeking certified micronized product with full batch traceability.
France
ANSES sodium reduction targets accelerate demand for sub-100-micron particles in premium snack seasoning. The EU F-Gas Regulation pressures energy-intensive evaporation, redirecting investment toward solar salt refinement in coastal production zones. Paris-based confectionery operations exploit flavored micronized grades for clean-label taste intensity at reduced sodium loadings.
Poland
Warsaw-based meat processors upgrade to EU-certified micronized grades for export qualification into Western European retail channels. REACH registration costs disadvantage regional importers against scaled domestic refiners. Poznań-area production clusters are absorbing mechanical milling capacity expansions serving Central European reformulation demand.
Netherlands
Benelux snack manufacturers pilot ingredient-as-a-service contracts bundling precision-dosing equipment with monthly particle-size certification. The EU AI Act's impending traceability requirements for automated sorting equipment are accelerating capital deployment timelines. Rotterdam logistics hubs consolidate distribution for reformulation-agile food manufacturers.
Spain
Solar evaporation infrastructure in Mediterranean coastal zones aligns production with EU Green Deal emission reduction mandates. Barcelona specialty retailers stock premium flavored micronized salts for culinary enthusiast segments. Madrid-based food manufacturers leverage mechanical milling partnerships to bypass natural gas price volatility in thermal refining.
Europe Food Micronized Salt Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. The supplier base concentrates around mining-integrated refiners with captive crystallization capacity and independent toll-milling operators serving regional processors. Three archetypes dominate: vertically integrated mine-to-micronization players, R&D-intensive sodium-reduction blend specialists, and regional certified-grade suppliers. Competitive dynamics revolve around backward integration into mining assets and portfolio diversification into precision-dosing service contracts.
Among Germany-based integrated refiners, K+S Aktiengesellschaft and Südwestdeutsche Salzwerke AG exemplify the mining-integrated archetype with upstream control over crystallization feedstock. Cargill Incorporated represents the R&D-intensive multinational tier, occupying a position defined by formulation science capabilities rather than mineral extraction. These three anchors illustrate how competitive positioning separates mineral-access players from technology-driven solution providers.
| Leading Market Players |
|---|
| K+S Aktiengesellschaft |
| Cargill Incorporated |
| Südwestdeutsche Salzwerke AG |
| CIECH S.A. |
| British Salt |
| ZOUTMAN NV |
| Salinity Ab |
| INFOSA |
| Compass Minerals |
| Others |
Supply & Pricing Matrix
Natural gas futures volatility cascades through thermal evaporation economics into three-tier pricing stratification across premium micronized grades, standard food-grade certification tiers, and commodity bulk salt. Kassel and Berchtesgaden production clusters leverage captive mining feedstock to defend margin structures against Rotterdam-imported solar salt alternatives.
Pricing Analysis
Distributor margins compress pricing transparency for mid-sized Polish meat processors lacking direct refinery relationships. Three-tier pricing structure across pharmaceutical-adjacent certification, EFSA-compliant food-grade, and commodity bulk levels separates buyers by traceability documentation intensity. Cost compression in standard food-grade tiers intensifies as German industrial bakeries consolidate procurement volumes. Private-label supermarket channels exhibit highest price sensitivity; precision-dosing subscription services demonstrate lowest sensitivity due to reformulation agility premiums.
Supply Chain Analysis
Particle engineering specialists in Alsace and Kassel command wage premiums that constrain mechanical milling capacity expansion. Germany, Poland, and Spain anchor supply concentration through mining-integrated refiners, Central European toll milling, and Mediterranean solar evaporation respectively. Sodium chloride feedstock draws from Berchtesgaden underground deposits, Spanish coastal solar ponds, and Polish rock salt mines. Single-source vulnerability concentrates in Kassel cluster thermal evaporation assets exposed to natural gas price swings. Distribution runs through Rotterdam logistics hubs consolidating Benelux snack manufacturer procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe food micronized salt represents a late-cycle quality story as EFSA sodium reduction mandates and ANSES reformulation targets concentrate procurement power among manufacturers certifying sub-100-micron particle consistency.
For Market Incumbents: Cement backward integration into captive crystallization capacity to defend against solar salt refiners exploiting EU F-Gas Regulation compliance timelines. Expand mechanical milling footprints in Poznań and Barcelona production clusters to displace energy-intensive thermal evaporation economics. Prioritize ERP retrofitting investments enabling real-time batch traceability documentation ahead of EU AI Act automated sorting mandates. For New Entrants and Emerging Players: Ingredient-as-a-service digital platforms offer white-space entry targeting Dutch and Belgian snack manufacturers piloting subscription-based particle certification models. Polish meat processing export qualification demand presents the most penetrable geography for EU-certified micronized grade market share capture. Lead with precision-dosing equipment bundling to bypass incumbent bulk supply contract lock-in. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH traceability documentation burdens disadvantage regional importers against scaled domestic refiners with dedicated compliance infrastructure. Target acquisition archetypes include toll-milling operators in Central Europe possessing air classification expertise and existing EFSA certification pathways. Monitor EU AI Act implementation timelines as inflection indicator for capital deployment into automated particle-sorting equipment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mining Assets | K+S and Südwestdeutsche Salzwerke secure captive sodium chloride feedstock against solar salt price volatility. |
| Mechanical Milling Capacity Expansion | Spanish and Polish production clusters bypass EU F-Gas Regulation thermal evaporation compliance costs. |
| Precision-Dosing Service Launch | Dutch snack manufacturers pilot subscription models decoupling procurement from traditional bulk agreements. |
| ERP Traceability Retrofit | German industrial bakeries enable real-time EFSA documentation ahead of automated sorting mandates. |
| Coastal Solar Evaporation Investment | Mediterranean production zones align with EU Green Deal emission reduction targets for food-grade refinement. |
Research Methodology
Multiple input streams — primary interviews with food manufacturing procurement directors, mechanical milling plant engineers, and EFSA regulatory compliance officers; secondary validation through customs trade databases, EU F-Gas Regulation implementation filings, and SEC disclosures from listed salt refiners — were reconciled using bottom-up volume modeling and top-down market sizing triangulation.
Historical production capacity utilization rates were cross-referenced against expert panel assessments of reformulation-driven particle-size specification shifts. Segmentation dimensions modeled include product grade tier, end-use application intensity, and regional regulatory compliance cluster. CAGRs were derived through exponential smoothing of annual volume projections. Forecast inputs incorporated solar evaporation yield variability and natural gas price trajectory sensitivity.
The model assumes a particular technology adoption path; alternative pathways for AI-enabled automated particle sorting would alter the outlook for capital deployment timelines and compliance cost structures. Forecasts reflect assumptions regarding EFSA sodium reduction mandate enforcement intensity and EU Green Deal industrial emissions framework implementation pace. Material deviation in German natural gas pricing or REACH registration cost inflation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Spain Food Enzymes Market
Food Additives and Ingredients
Africa Microbial Food Culture Market
Food Additives and Ingredients
Asia- Pacific Food Micronized Salt Market
Food Additives and Ingredients
Low Methoxyl Pectin Market
Food Additives and Ingredients
Excipients Market
Food Additives and Ingredients
Natural Food and Beverage Preservatives Market
Food Additives and Ingredients
Lactoperoxidase Market
Food Additives and Ingredients
Carrageenan Gum Market
Food Additives and Ingredients
Gum Hydrocolloid Market
Food Additives and Ingredients
Western Europe Food Phosphate Market
Food Additives and Ingredients
United Kingdom Anti Caking Market
Food Additives and Ingredients
Food Antimicrobial Additives Market
Food Additives and Ingredients
Alpha-Amylase Baking Enzyme Market
Food Additives and Ingredients
Antistaling Agent Market
Food Additives and Ingredients
Vinasse Market
Food Additives and Ingredients
Calcium Inosinate Market