
 Meat Stabilizers Blends Market | 2026-2036
Meat Stabilizers Blends Market Size, Share, and Industry Trends Forecast 2026-2036
Meat Stabilizers Blends Market Outlook
Premium phosphate-free specification tiers is unwinding legacy cost-driven procurement across meat processing. Cargill, Incorporated leverages its integrated hydrocolloid supply chain to anchor clean-label formulations in North American processed meat channels. Kerry Group differentiates through fermentation-derived stabilizer expertise, while Palsgaard competes on emulsifier-stabilizer synergies for high-fat meat applications.
Meat stabilizers blends comprise functional ingredient systems—typically combining hydrocolloids, phosphates, starches, and proteins at specified ratios—to control water binding, texture, and shelf stability in muscle food products. These formulations undergo dry blending or spray-drying processes to achieve homogeneous dispersion in comminuted or whole-muscle matrices, serving primarily to reduce purge loss and maintain organoleptic consistency through distribution cycles. Natural product type segments command expanding margin pools as retailer clean-label mandates harden, while phosphate-based categories face structural compression from regulatory scrutiny in Western markets. Processed meat applications dominate volume, though packaged meat segments exhibit faster specification upgrading as convenience formats proliferate.
FDA oversight of phosphate additive declarations and USDA FSIS labeling standards directly reshape stabilizer blend composition requirements in the United States, forcing migration toward legume-derived and seaweed-extracted alternatives. EFSA evaluations of phosphates as food additives, coupled with EU MDR-adjacent supply chain documentation expectations, tighten market access for non-compliant formulations. Stakeholders must monitor evolving maximum permitted levels for synthetic phosphate salts across multiple jurisdictions while building formulation flexibility to switch between natural and mineral-based systems without line disruption.
Market Dynamics
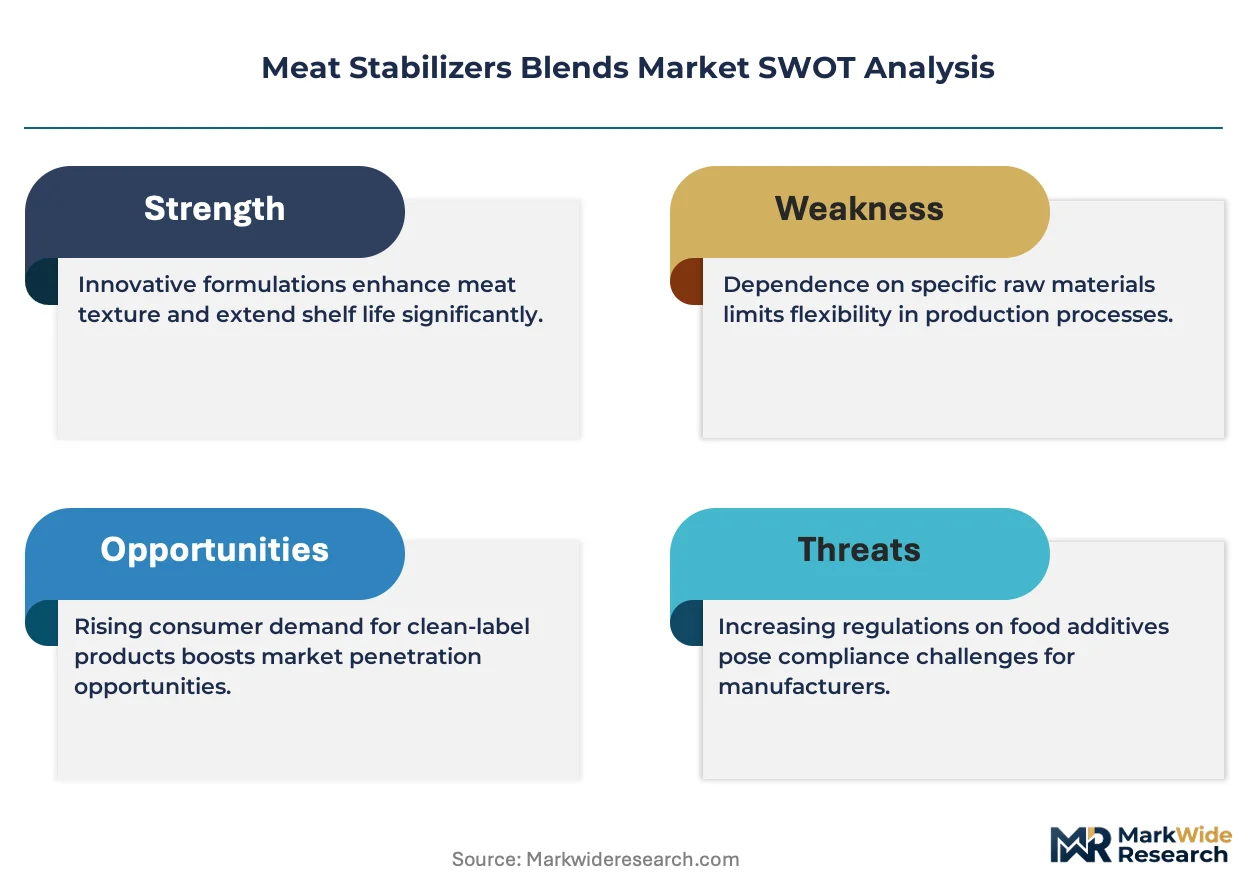
Clean-label mandates from major retailers are compressing phosphate-dependent formulation architectures, forcing meat processors to rebuild stabilizer systems around seaweed-extracted carrageenan and legume-derived proteins without sacrificing water-binding performance.
Growth Catalysts
- USDA FSIS phosphate-labeling enforcement:Tightened declaration requirements accelerate migration toward natural hydrocolloid systems in US processed meat channels.
- Convenience format proliferation:Packaged meat segments drive specification upgrading as shelf-stable, ready-to-cook products demand superior purge control.
- German sausage tradition:Premium cured meat consumption sustains high-margin stabilizer demand in European artisanal processing.
Market Restraints
- Seaweed supply volatility:Carrageenan and agar extraction depends on Philippine and Indonesian harvest cycles vulnerable to climate disruption.
- Clean-label cost premium:Natural hydrocolloid systems command 15-40% higher input costs versus phosphate-based alternatives, squeezing mid-tier processor margins.
- EFSA phosphate evaluations:Pending reclassification of synthetic phosphate salts as food additives creates formulation uncertainty across EU member states.
Strategic Opportunities
- Plant-based meat analogues:Emerging application segment requires novel stabilizer architectures for texture mimicry in extruded protein matrices.
- Fermentation-derived hydrocolloids:Precision fermentation enables microbial cellulose and xanthan gum production with supply chain decoupling from agricultural commodities.
- EU Green Deal procurement incentives:Sustainability-linked sourcing mandates favor stabilizer suppliers with verified low-carbon extraction credentials.
Industry Challenges
- Reformulation expertise scarcity:Meat processors lack in-house capability to switch between phosphate and natural systems without line disruption or yield loss.
- Dual-system inventory complexity:Maintaining parallel natural and mineral-based stabilizer stocks strains working capital and forecasting accuracy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meat Stabilizers Blends Market |
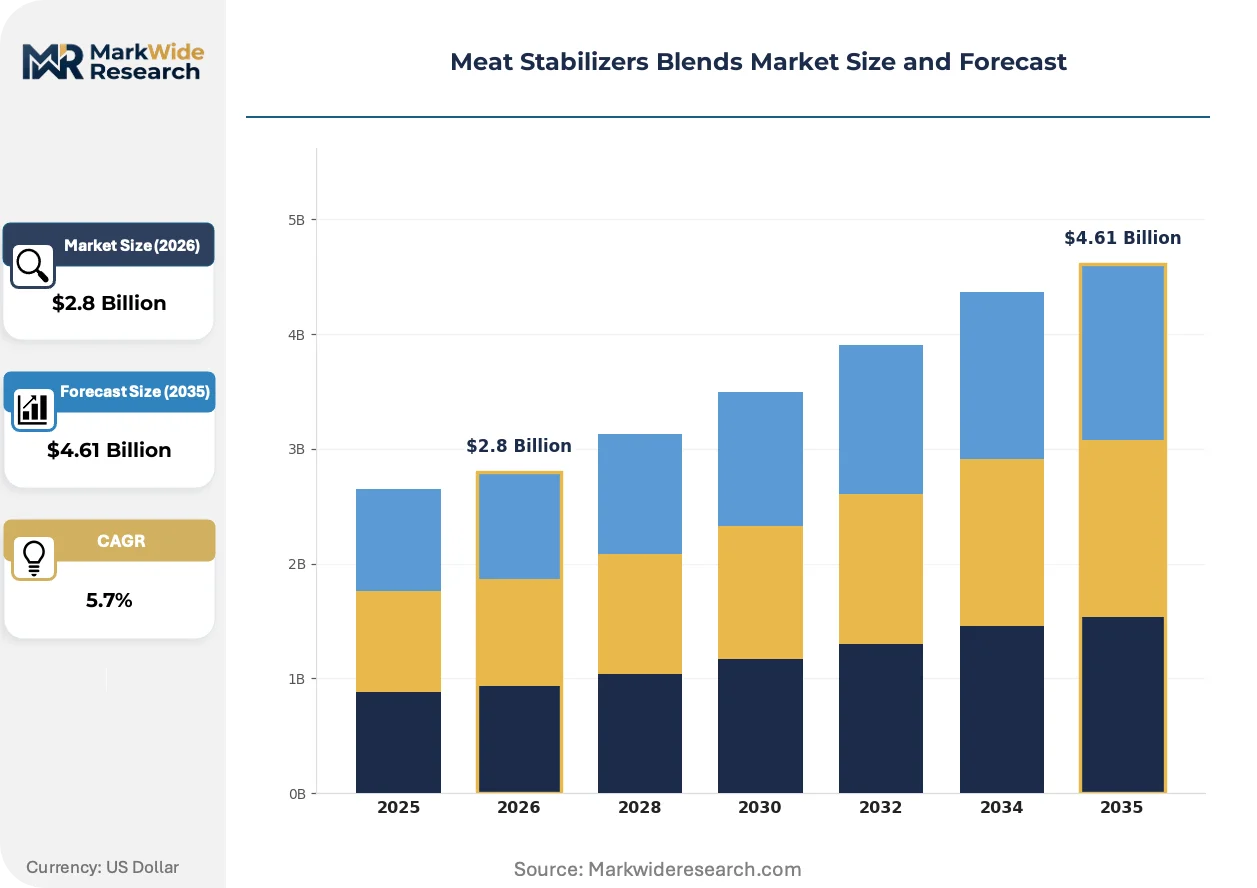
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Phosphate-Based, Fermented Application: Processed Meat, Packaged Meat, Fresh Meat, Cured Meat Form: Powder, Liquid, Granular, Paste End User: Food Manufacturers, Retailers, Food Service, Distributors |
| Companies Covered | Cargill, Incorporated, DuPont, Tate & Lyle, Palsgaard, ADM, CP Kelco, Ashland, Hydrosol GmbH and Co. KG, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meat Stabilizers Blends Market Strategic Shifts
Formulation science is pivoting from cost-optimized phosphate dependence toward functional equivalence through botanical extraction and microbial production, reshaping supplier-processor relationships and raw material sourcing geographies.
Seaweed-derived carrageenan and agar-agar systems are displacing traditional phosphate blends in comminuted meat applications. Mid-sized US processors are adopting these alternatives at accelerated pace to meet retailer clean-label mandates. This displacement is compressing legacy phosphate suppliers while expanding margin pools for integrated hydrocolloid producers with captive seaweed supply.
EU MDR-adjacent supply chain documentation expectations tighten traceability requirements for stabilizer ingredients entering European markets. Manufacturers must now provide granular origin data for hydrocolloid sources and processing aids. Small-to-mid tier exporters face compliance barriers that favor larger suppliers with established regulatory affairs infrastructure.
Retail buyer concentration is consolidating specification-setting power among three to five national grocery chains in major Western markets. These buyers now mandate clean-label compliance as a condition of shelf access, bypassing traditional processor discretion. Germany and France exhibit the most aggressive private-label reformulation timelines, with discounter chains leading the transition.
Meat Stabilizers Blends Market Segmentation
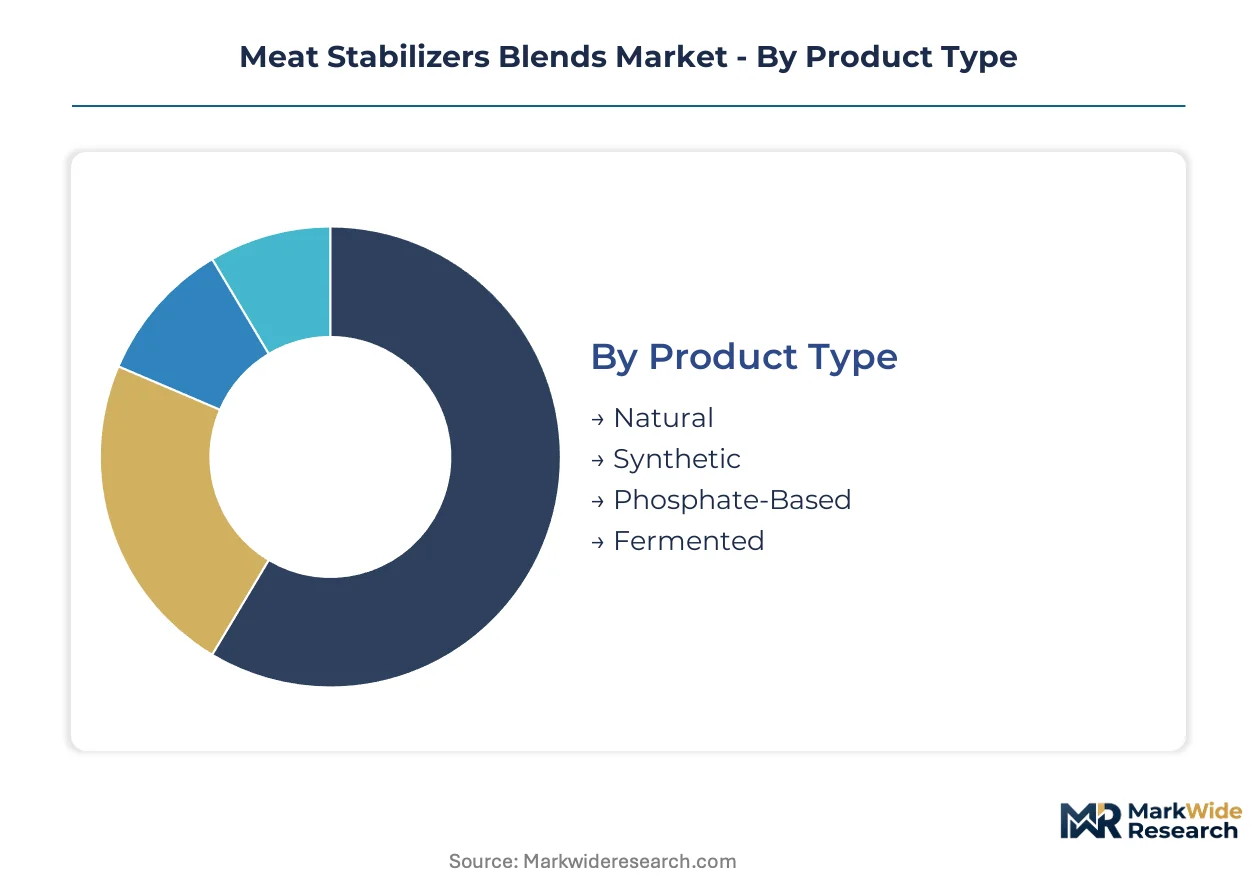
Meat stabilizer blend specifications diverge sharply across product architectures and downstream channels. Procurement patterns cluster around phosphate-free mandates in Western retail while industrial meat processing sustains legacy formulation demand.
Product Type:
Margin pools concentrate in fermentation-derived and seaweed-extracted systems as synthetic phosphate categories face regulatory compression.
- Natural:Carrageenan, agar-agar, and legume protein blends extracted from Philippine and Indonesian seaweed harvests. German sausage processors and North American clean-label retailers drive premium pricing for these phosphate alternatives as USDA FSIS labeling enforcement hardens.
- Synthetic:Chemically modified starches and cellulose derivatives engineered for cost-optimized water binding. Mid-tier US and Brazilian processors maintain demand despite retailer pressure, constrained by reformulation expertise scarcity and line disruption risks.
- Phosphate-Based:Sodium tripolyphosphate and pyrophosphate salts facing structural decline from EFSA reclassification evaluations.
- Fermented:Microbial cellulose and xanthan gum from precision fermentation platforms with supply chain decoupling from agricultural commodities.
Natural holds installed capacity. Fermented is rotating up the share rankings.
Application:
Volume concentrates in comminuted meat processing while specification upgrading accelerates in convenience formats.
- Processed Meat:Ground meat, sausages, and deli products requiring emulsion stability and purge control. US and German channels dominate procurement as clean-label mandates force hydrocolloid system rebuilds without yield sacrifice.
- Packaged Meat:Ready-to-cook and shelf-stable formats demanding superior moisture retention through distribution cycles. Discounter chains in France and Germany mandate phosphate-free compliance fastest here.
- Fresh Meat:Whole-muscle applications with minimal stabilizer penetration limited to surface treatments.
- Cured Meat:Traditional preservation contexts where nitrate interactions constrain stabilizer selection.
Processed Meat anchors volume procurement. Packaged Meat is climbing the fastest.
Form:
Supply concentration favors powder formats with spray-drying infrastructure while liquid systems gain traction in continuous processing lines.
- Powder:Homogeneous dry blends achieving specified particle size distribution for uniform dispersion in comminuted matrices. European and North American processors prefer this format for inventory stability and dosing precision.
- Liquid:Pre-hydrated hydrocolloid suspensions eliminating dust handling and hydration time in high-throughput operations.
- Granular:Intermediate particle size for specific texture applications in coarse-ground meat products.
- Paste:High-viscosity concentrated systems for artisanal processors with batch mixing operations.
Powder commands production scale. Liquid is gaining share fastest.
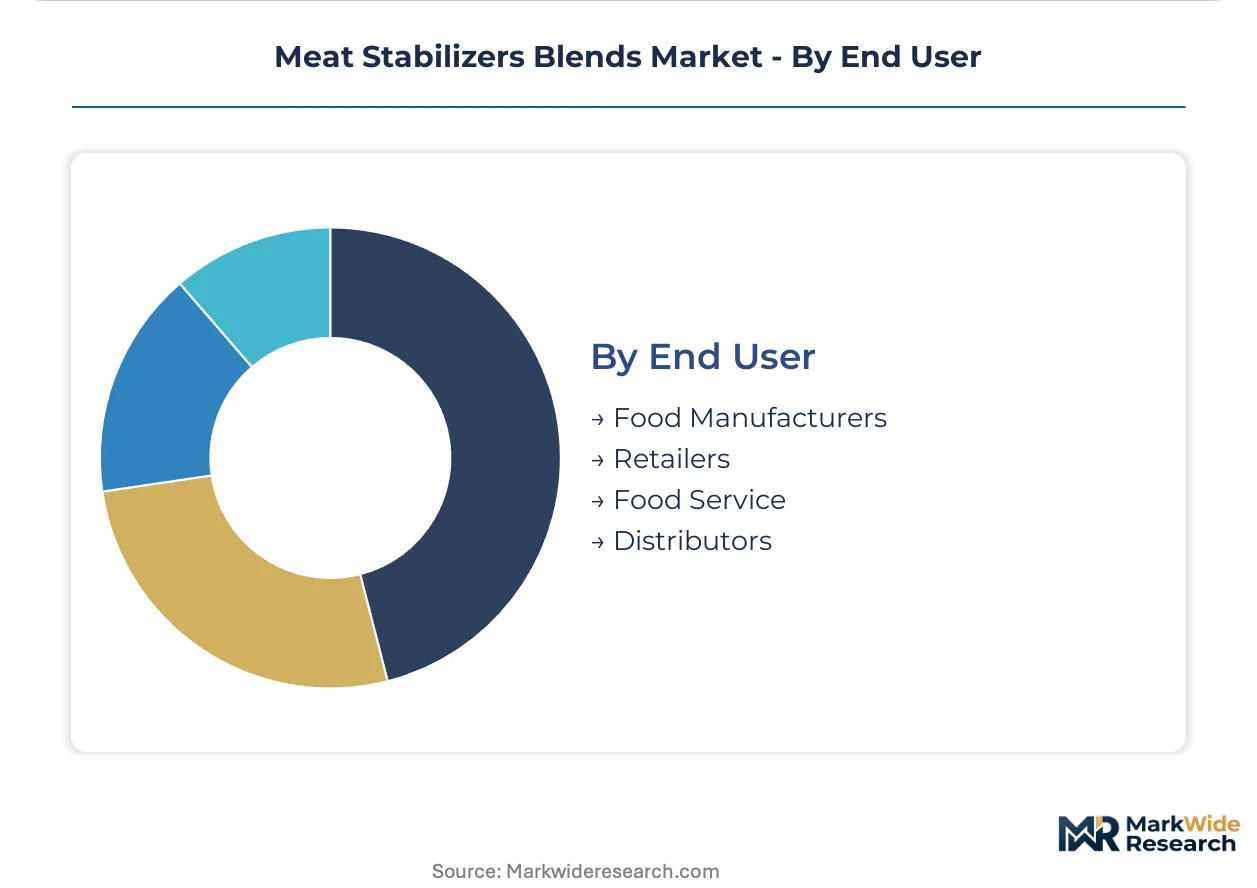
End User:
Purchasing power concentrates among consolidated retail buyers while food service channels lag in specification upgrading.
- Food Manufacturers:Integrated meat processors with in-house R&D capability driving formulation innovation. German and US processors lead phosphate-to-natural transitions.
- Retailers:Private-label chains in France, Germany, and the US mandating clean-label compliance as shelf access condition.
- Food Service:Restaurant and institutional buyers prioritizing cost stability over label claims.
- Distributors:Intermediary channels with limited formulation influence but inventory consolidation power.
Food Manufacturers hold technical leadership. Retailers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in meat stabilizer blends track closely to processed meat trade patterns, with Germany and the United States running structural deficits in natural hydrocolloid inputs while maintaining surplus positions in formulated stabilizer systems.
United States
USDA FSIS phosphate-labeling enforcement drives rapid specification migration toward carrageenan and legume protein systems. The FDA maintains strict oversight of additive declarations, forcing processors toward natural alternatives. Chicago and the Midwest meatpacking corridor anchor domestic stabilizer demand as Tyson Foods and JBS USA accelerate clean-label reformulation.
Germany
Sausage and cured meat traditions sustain premium stabilizer consumption unmatched elsewhere in Europe. EFSA evaluations of synthetic phosphate salts create regulatory uncertainty, pushing processors toward seaweed-extracted systems. The Bavarian meat processing cluster around Munich and Nuremberg leads phosphate-to-natural transitions across artisanal and industrial channels.
China
SAMR oversight of food additive standards tightens documentation requirements for imported stabilizer systems. Domestic processors in Shandong and Jiangsu provinces expand local hydrocolloid extraction capacity to reduce Philippine seaweed dependency. Qingdao anchors emerging carrageenan production infrastructure serving both domestic meat processors and export markets.
Brazil
ANVISA regulatory alignment with Codex standards shapes stabilizer import specifications for the Mercosur trade bloc. Cost-optimized phosphate systems dominate mid-tier beef processing despite retailer pressure. São Paulo state concentrates meatpacking operations where JBS and BRF drive gradual specification upgrading in export-bound product lines.
Indonesia
Seaweed harvest volatility in Sulawesi and Kalimantan directly constrains global carrageenan supply availability. The national food and drug regulator enforces halal certification requirements that complicate stabilizer import logistics. Makassar and the eastern archipelago anchor extraction infrastructure vulnerable to climate disruption and shipping constraints.
Meat Stabilizers Blends Market Competitive Environment
Listed leaders compete with private specialists across formulation expertise and supply chain integration depth. The vendor base organizes around three tiers: integrated agribusiness conglomerates with captive hydrocolloid supply, fermentation-focused biotechnology platforms, and regional blending operations serving single-country markets. Two strategic archetypes dominate competitive positioning: those controlling upstream seaweed extraction assets and those mastering microbial production systems. M&A activity concentrates on fermentation technology acquisitions and Southeast Asian seaweed supply consolidation.
Within the integrated agribusiness tier, Cargill, Incorporated and ADM exemplify upstream control strategies through captive supply of legume-derived proteins and starch systems. Kerry Group occupies a distinct position among fermentation-derived specialists, leveraging biotechnology platforms for microbial cellulose production. Palsgaard anchors the emulsifier-stabilizer synergy segment with Danish technical heritage in high-fat meat applications.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| DuPont |
| Tate & Lyle |
| Palsgaard |
| ADM |
| CP Kelco |
| Ashland |
| Hydrosol GmbH and Co. KG |
| Kerry Group |
| Others |
Value Chain & Pricing Dynamics
USDA FSIS phosphate-labeling enforcement gates both supplier qualification and price tier differentiation simultaneously, forcing processors to pay premiums for clean-label compliance or absorb margin compression from reformulation costs. Natural hydrocolloid systems command substantial input cost premiums over legacy phosphate alternatives, bifurcating procurement budgets between compliant and non-compliant supply tiers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-scale discounts dominating negotiated terms. Price differentiation separates fermentation-derived premium tiers from commodity seaweed-extracted grades, with certification level and customization depth driving spread expansion. Cost compression in mid-tier phosphate alternatives is intensifying because retailer clean-label mandates are accelerating specification migration. Small-to-mid tier processors exhibit highest price sensitivity due to working capital constraints, while integrated meatpackers with captive R&D absorb premiums most readily.
Supply Chain Analysis
Strategic-stockpile preferences dominate among processors vulnerable to Philippine and Indonesian seaweed harvest disruptions, with just-in-time adoption limited to large buyers with multi-source contracts. Raw material supply concentrates in Indonesia, the Philippines, and China for carrageenan and agar extraction, while fermentation platforms expand in Denmark and the United States. Philippine seaweed harvest volatility creates single-source vulnerability for carrageenan-dependent formulators. Distribution runs through integrated agribusiness conglomerates with captive hydrocolloid supply and regional blending operations serving single-country markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation-as-a-service attach rates are expanding faster than commodity stabilizer sales, as processors outsource phosphate-to-natural system rebuilds to avoid yield loss and line disruption.
For Market Incumbents: Compound defensive positioning through backward integration into Philippine and Indonesian seaweed extraction assets to secure supply continuity against climate disruption. Deepen fermentation platform capacity in Denmark and North American biotechnology clusters to capture margin expansion from microbial cellulose demand. Certification investment in EU MDR-adjacent documentation capabilities creates switching-cost barriers against mid-tier competitors lacking regulatory affairs infrastructure. For New Entrants and Emerging Players: Lead with precision fermentation-derived hydrocolloid specialization targeting US and German processors facing urgent phosphate replacement timelines. Plant-based meat analogues represent the most penetrable application segment, with texture mimicry requirements unserved by legacy stabilizer architectures. A formulation-partnership go-to-market angle with mid-sized processors lacking in-house R&D capability accelerates adoption without direct incumbent confrontation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed regional blending operations in Southeast Asia and Eastern Europe lacking fermentation technology access. Long-term viability across the analysis window favors biotechnology platforms with supply chain decoupling from agricultural commodity volatility. The signal to watch is EFSA phosphate reclassification timing, which would force accelerated specification migration and expand addressable market for compliant alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seaweed Extraction | Cargill and ADM are securing Philippine and Indonesian harvest assets to stabilize carrageenan supply. |
| Precision Fermentation Scale-Up | Kerry Group expands Danish microbial cellulose capacity to serve German sausage processor demand. |
| Clean-Label Certification Program | Palsgaard pursues EU MDR-adjacent documentation to maintain shelf access for French discounter chains. |
| Joint Venture with Plant-Based Meat Producers | Hydrocolloid suppliers partner with extruded protein specialists to develop texture-mimicry systems. |
| Long-Term Supply Agreement with Retail Chains | Stabilizer blenders contract directly with Kroger and Albertsons to lock phosphate-free specification mandates. |
Study Parameters
The analysis maps natural, synthetic, phosphate-based, and fermented stabilizer sub-sectors, each validated through meat processor R&D directors, regulatory affairs leads at hydrocolloid suppliers, retail category buyers, and food service procurement managers. Primary interview findings triangulate against FDA additive filings, USDA FSIS labeling guidance documents, EFSA evaluation reports, customs trade data for seaweed-derived inputs, and SEC 10-K disclosures from listed agribusiness conglomerates. Bottom-up volume builds from application-level demand models reconcile with top-down market sizing from supplier revenue aggregation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, application, form, and end-user channel, with regional regulatory cluster effects incorporated for US, EU, and Chinese markets. CAGRs derive from regression analysis of historical specification migration patterns and forward projection of retailer clean-label mandate diffusion curves. Input assumptions incorporate seaweed harvest yield volatility, fermentation platform capacity expansion timelines, and phosphate regulatory reclassification probability weightings.
Forecasts assume regulatory continuity in USDA FSIS labeling enforcement and EFSA additive evaluation regimes; material policy shifts would require re-modeling specification migration trajectories. Revision becomes warranted when Philippine or Indonesian climate disruption crosses thresholds that trigger carrageenan supply rationing to meat processor customers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
North America Feed Additives Market
Food Additives and Ingredients
Amaranth (E123) Market
Food Additives and Ingredients
Oxidized Starch Market
Food Additives and Ingredients
Africa Anti Caking Agent Market
Food Additives and Ingredients
Italy Food Additives Market
Food Additives and Ingredients
Plant-Based Emulsifiers Market
Food Additives and Ingredients
Food Grade Sodium Hydroxide Market
Food Additives and Ingredients
Sucroglycerides Market
Food Additives and Ingredients
Dairy Starter Culture Market
Food Additives and Ingredients
Italy Food Acidulants Market
Food Additives and Ingredients
Beverage Clouding Agent Market
Food Additives and Ingredients
Carrageenan Market
Food Additives and Ingredients
Italy Food Enzymes Market
Food Additives and Ingredients
Asia-Pacific Malt Ingredient Market
Food Additives and Ingredients
Microencapsulated Food Ingredient Market
Food Additives and Ingredients
Cook-Up Starch Market