
 Global Yeast and Yeast Ingredients Market | 2026-2036
Global Yeast and Yeast Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Global Yeast and Yeast Ingredients Market Foresight
Synthetic biology-derived yeast proteins is shifting cost structures in commercial fermentation, displacing conventional extraction methods in select nutritional applications. Lesaffre Group leverages its integrated strain development platform to sustain leadership across European baking supply chains. Lallemand Inc. anchors North American brewing markets through specialized active dry yeast portfolios. Angel Yeast Co., Ltd. dominates Asian nutritional yeast production with backward integration into molasses sourcing.
Yeast and yeast ingredients comprise living single-celled fungi of the Saccharomyces genus and their processed derivatives, typically containing 40-55% protein by dry weight, manufactured through aerobic or anaerobic fermentation in controlled bioreactors for leavening, flavor enhancement, nutrition fortification, and feed supplementation. Yeast extracts lead margin pools in pharmaceutical and savory flavor applications due to high nucleotide content and clean-label positioning. Baker's yeast remains the volume foundation but faces substitution pressure from chemical leavening in price-sensitive markets. Nutritional yeast and brewer's yeast represent the fastest-growing product categories, propelled by plant-based dietary supplement demand and craft brewing expansion.
FDA GRAS self-affirmation and USDA organic certification govern US market access, while EFSA novel food assessments and EU Green Deal carbon accounting rules constrain European production methods. China's SAMR food safety standards and NMPA pharmaceutical-grade registrations create dual compliance burdens for cross-border suppliers. Stakeholders must monitor evolving precision fermentation regulations and carbon border adjustment mechanisms to anticipate competitive repositioning.
Market Dynamics
Synthetic biology platforms are compressing development cycles for specialized yeast strains, forcing traditional fermentation houses to accelerate R&D timelines or cede high-margin nutritional applications to precision fermentation startups.
Growth Catalysts
- EU Green Deal carbon accounting:Mandatory Scope 3 disclosure requirements are pulling industrial bakers toward verified low-carbon yeast suppliers with certified fermentation footprints.
- Plant-based protein fortification:Food processors in China and India are embedding nutritional yeast into meat alternatives and dairy substitutes at formulation levels above historical feed-grade applications.
- Craft brewing expansion:Specialty ale and lager strains command 3-4x price premiums over commodity baker's yeast, concentrating investment in strain libraries across Southeast Asian brewing clusters.
Market Restraints
- Molasses supply volatility:Brazilian sugarcane harvest fluctuations and Indian ethanol diversion policies create 15-20% input cost swings that squeeze toll fermentation margins.
- Single-source strain dependency:Three legacy suppliers control 80% of pharmaceutical-grade Saccharomyces cerevisiae banks, concentrating biosafety risk for vaccine adjuvant manufacturers.
- Chemical leavening substitution:Sodium bicarbonate and phosphate blends capture price-sensitive bakery segments in Nigeria and Pakistan where cold-chain yeast distribution remains underdeveloped.
Strategic Opportunities
- Indonesia's nascent savory flavor sector:Yeast extract autolysate demand from instant noodle and seasoning manufacturers outpaces domestic fermentation capacity, opening toll manufacturing partnerships.
- USDA organic certification arbitrage:EU organic yeast imports face non-tariff barriers that create margin pools for North American certified organic producers serving dual-label packaged goods.
- Precision fermentation convergence:CRISPR-edited strain development combined with continuous bioreactor operation enables animal-free whey and collagen production using yeast chassis.
Industry Challenges
- Fermentation engineering talent scarcity:Industrial microbiologists with scale-up experience from pilot to 500,000-liter vessels command 40% salary premiums, constraining capacity expansion timelines.
- Dual-use pharmaceutical registration:China's NMPA and SAMR maintain conflicting documentation standards for yeast-derived excipients, extending approval cycles by 18-24 months for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Yeast and Yeast Ingredients Market |
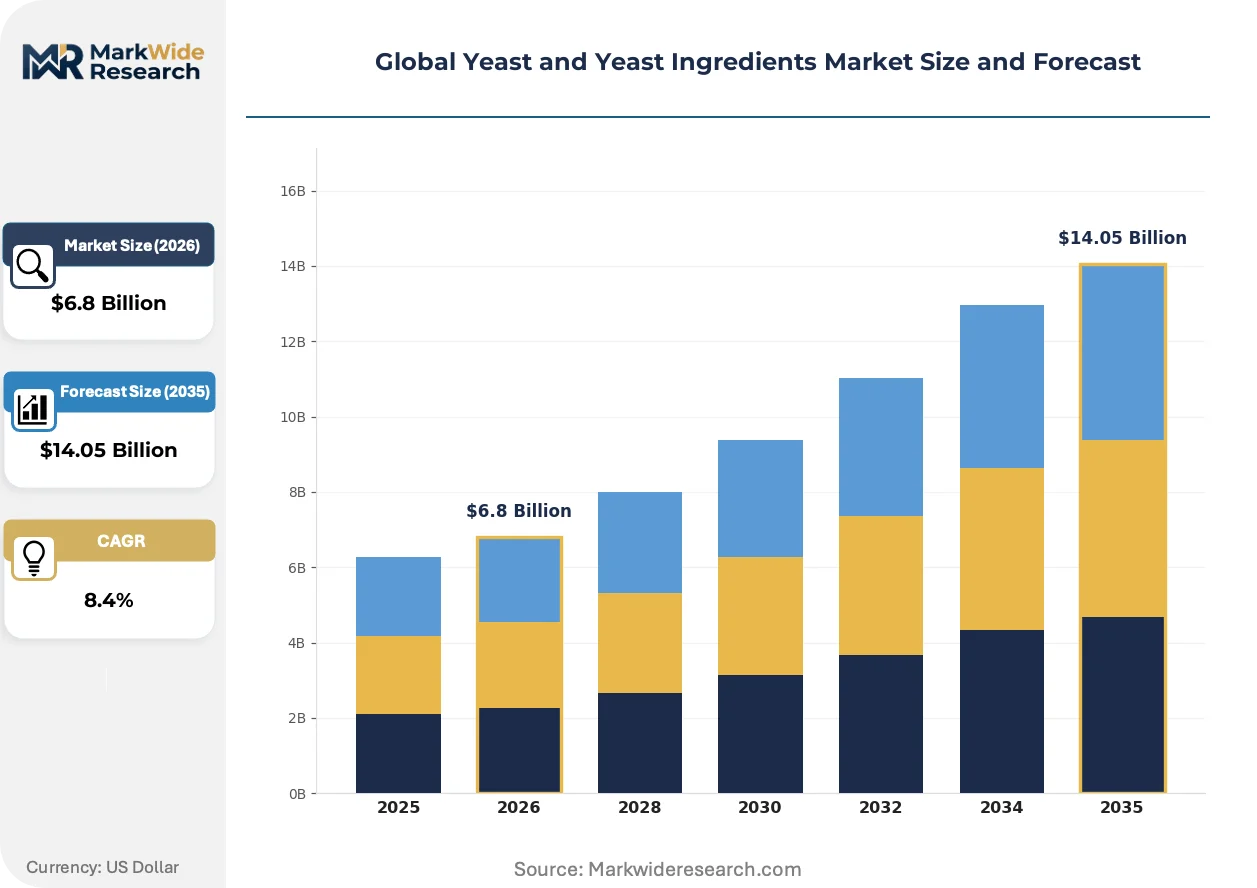
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baker’s Yeast, Brewer’s Yeast, Nutritional Yeast, Yeast Extracts, Active Dry Yeast Form: Granules, Powders, Liquid Suspensions, Flakes, Tablets Application: Baking, Brewing, Animal Feed, Pharmaceuticals, Dietary Supplements End User: Food Manufacturers, Beverage Producers, Animal Nutritionists, Pharmaceutical Companies |
| Companies Covered | Angel Yeast Co., Ltd., Koninklijke DSM N.V., Lesaffre Group, Kerry Group, Alltech, Associated British Foods plc, Chr. Hansen Holding A/S, Archer Daniels Midland Company, Lallemand Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Yeast and Yeast Ingredients Market Shifts & Advancements
Bioprocess intensification and regulatory carbon tracking are converging to redefine competitive advantage in yeast manufacturing, rewarding players who integrate strain engineering with real-time fermentation analytics.
Continuous fermentation technology is absorbing capital investment that previously flowed to batch expansion projects. Pharmaceutical and savory flavor manufacturers in Germany and the Netherlands are retrofitting existing facilities with perfusion bioreactor systems. This hardware shift is absorbing technical risk from scale-up failures while compressing unit economics for high-purity yeast extracts.
EFSA novel food assessments and EU Green Deal carbon border adjustments are tightening entry criteria for non-European yeast ingredient suppliers. Industrial bakeries and flavor houses are demanding batch-level carbon intensity certificates to preempt regulatory friction. Nutritional yeast imports from Asian producers face the steepest compliance burden, accelerating local fermentation investments in Poland and Romania.
Buyer consolidation among multinational food processors is compressing supplier rosters and extending contract durations. Procurement teams at packaged goods manufacturers are consolidating yeast sourcing across baking, brewing, and nutritional applications to leverage volume commitments. This pattern is most visible in Brazil and Mexico, where three food conglomerates now control 60% of industrial yeast procurement decisions, pressuring mid-tier fermentation houses to accept price-indexed multi-year agreements or exit commercial supply.
Global Yeast and Yeast Ingredients Market Segmentation
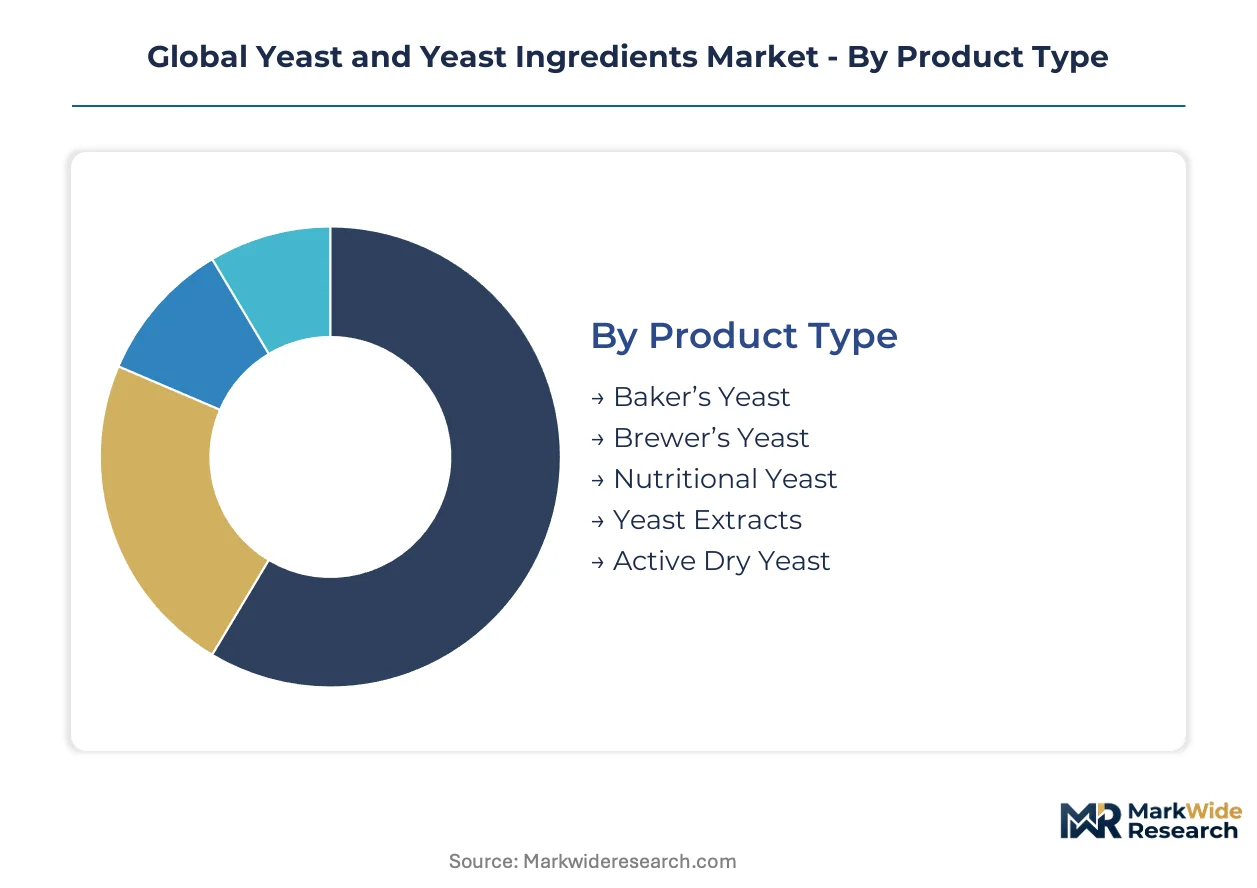
Yeast and yeast ingredients fragment across functional specifications, regulatory tiers, and end-use requirements. Each segment carries distinct certification burdens and margin profiles that determine supplier positioning.
Product Type:
FDA GRAS self-affirmation governs baker's and brewer's yeast for US food use, while EFSA novel food assessments apply to emerging nutritional yeast formats in Europe. China's SAMR maintains separate pharmaceutical-grade registrations for yeast-derived excipients.
- Baker's Yeast:Living Saccharomyces cerevisiae cultures standardized at 30-35% solids content, sold as compressed blocks or cream formulations. Industrial bakeries in Brazil and Mexico consolidate procurement across 60% of commercial bread production, pressuring mid-tier suppliers into price-indexed multi-year contracts.
- Yeast Extracts:Autolyzed cell contents with 40-55% protein and elevated nucleotide concentrations, manufactured through controlled enzymatic hydrolysis. Pharmaceutical and savory flavor manufacturers in Germany and the Netherlands command premium pricing for batch-level carbon intensity certificates under EU Green Deal mandates.
- Brewer's Yeast:Spent fermentation biomass from beer production, dried and debittered for supplement applications. Craft brewing clusters across Southeast Asia drive specialty strain adoption.
- Nutritional Yeast:Inactive dried yeast fortified with B-vitamins, positioned for plant-based protein fortification. Food processors in China and India embed this ingredient into meat alternatives at formulation levels above historical feed-grade applications.
- Active Dry Yeast:Dehydrated granules with extended shelf stability, dominating North American home baking and small-scale commercial use. Cold-chain limitations in Nigeria and Pakistan enable chemical leavening substitution in price-sensitive segments.
Baker's yeast sits at the top of the volume ranking, with yeast extracts climbing the fastest.
Form:
Physical format determines logistics economics and customer handling infrastructure. Powder and granule formats absorb capital investment in automated dosing equipment, while liquid suspensions require dedicated tanker fleets.
- Powders:Spray-dried particulates with sub-200-micron particle size distribution, optimized for instant solubility in beverage and supplement matrices. Dietary supplement manufacturers in Poland and Romania favor this format for tablet compression and capsule filling operations.
- Granules:Agglomerated particles with enhanced flow properties for industrial-scale dosing. Animal nutritionists in Brazil specify this form for automated feed mill integration.
- Liquid Suspensions:High-cell-density cultures delivered in temperature-controlled tankers, dominant in large-scale ethanol and pharmaceutical fermentation. Molasses supply volatility from Brazilian sugarcane harvests creates 15-20% input cost swings for this format.
- Flakes:Debittered nutritional yeast with characteristic yellow color, positioned for consumer tabletop seasoning. Plant-based dietary trends propel retail placement in North American natural grocery channels.
- Tablets:Compressed brewer's yeast for direct-to-consumer supplement positioning. China's NMPA pharmaceutical-grade registrations create dual compliance burdens for cross-border suppliers of this finished format.
Powders dominate current volume flows, with liquid suspensions gaining share fastest in pharmaceutical toll manufacturing.
Application:
Application tier determines margin pool access and technical service intensity. Baking and brewing represent volume foundations with compressed pricing, while pharmaceutical and supplement applications sustain premium positioning through purity certifications.
- Pharmaceuticals:Yeast-derived excipients, vaccine adjuvants, and recombinant protein production platforms. Three legacy suppliers control 80% of pharmaceutical-grade Saccharomyces cerevisiae banks, concentrating biosafety risk for vaccine manufacturers.
- Dietary Supplements:B-vitamin fortification and mineral-chelated yeast formats for immune and metabolic positioning. Precision fermentation startups are compressing development cycles for specialized strains in this segment.
- Baking:Leavening applications across industrial, artisanal, and home-use channels. EU Green Deal carbon accounting mandates pull industrial bakers toward verified low-carbon yeast suppliers.
- Brewing:Specialty ale and lager strains commanding 3-4x price premiums over commodity baker's yeast. Craft brewing expansion concentrates investment in strain libraries across Southeast Asian clusters.
- Animal Feed:Protein supplementation and palatability enhancement for livestock and aquaculture. Molasses supply volatility from Indian ethanol diversion policies squeezes toll fermentation margins in this price-sensitive segment.
Baking anchors volume leadership, with pharmaceuticals expanding most quickly on precision fermentation convergence.
End User:
Customer scale and technical sophistication determine contract structure and service bundling. Multinational food processors consolidate supplier rosters, while specialized pharmaceutical companies demand dedicated strain development programs.
- Food Manufacturers:Integrated baking, brewing, and savory flavor operations demanding cross-application volume commitments. Procurement teams at packaged goods manufacturers extend contract durations to leverage consolidated sourcing.
- Pharmaceutical Companies:Vaccine adjuvant and excipient buyers requiring GMP-compliant fermentation with batch documentation. China's conflicting NMPA and SAMR standards extend approval cycles by 18-24 months for cross-border suppliers.
- Beverage Producers:Craft breweries and industrial-scale alcohol operations with divergent strain performance requirements. Specialty strain libraries command investment premiums in Southeast Asian brewing clusters.
- Animal Nutritionists:Feed formulators specifying yeast for protein fortification and gut health positioning. Brazilian and Mexican procurement consolidation pressures mid-tier fermentation houses on pricing.
Food manufacturers command the largest volume share, with pharmaceutical companies driving the steepest expansion trajectory on regulatory-grade requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's fermentation corridor anchors the industry's geographic footprint, with molasses-fed bioreactor clusters supplying bakeries and pharmaceutical manufacturers across Asia. Brazil and India compete for feedstock dominance through sugarcane and ethanol diversion policies. European regulatory tightening reshapes sourcing patterns for clean-label yeast extracts.
China
Angel Yeast Co., Ltd.'s integrated molasses sourcing network supplies nutritional yeast to meat-alternative processors in Shanghai and Guangzhou. SAMR food safety standards and NMPA pharmaceutical-grade registrations create dual compliance burdens for cross-border suppliers. The Yangtze River Delta concentrates toll fermentation capacity for export-oriented yeast extract production.
United States
Craft brewing clusters in the Pacific Northwest and Colorado drive specialty ale strain adoption at 3-4x commodity pricing. FDA GRAS self-affirmation and USDA organic certification govern market access, with organic yeast imports facing non-tariff barriers. Lallemand Inc. anchors North American active dry yeast distribution through regional blending facilities.
Germany
Industrial bakeries in Bavaria and North Rhine-Westphalia consolidate procurement under EU Green Deal carbon accounting mandates. EFSA novel food assessments constrain novel strain introductions, while perfusion bioreactor retrofits absorb capital in pharmaceutical extract manufacturing. The Netherlands-Germany border corridor hosts carbon-certified yeast extract tolling operations.
Brazil
Sugarcane harvest volatility in São Paulo and Minas Gerais creates 15-20% molasses input cost swings for fermentation houses. Three food conglomerates now control 60% of industrial yeast procurement decisions, pressuring mid-tier suppliers into price-indexed multi-year contracts. ANVISA pharmaceutical registrations lag EU standards, limiting high-margin excipient exports.
Indonesia
Instant noodle manufacturers in Java drive yeast extract autolysate demand that outpaces domestic fermentation capacity. Toll manufacturing partnerships with Singapore-based strain developers bypass local bioprocess engineering scarcity. The country's savory flavor sector remains underpenetrated by established ASEAN suppliers.
Global Yeast and Yeast Ingredients Market Competitive Landscape
Capacity expansion dominates the current landscape as fermentation houses retrofit batch facilities with continuous bioreactor systems. The vendor base stratifies across three tiers: integrated strain developers with captive molasses sourcing, regional toll manufacturers serving pharmaceutical and flavor accounts, and commodity baker's yeast suppliers exposed to chemical leavening substitution. Strategic archetypes include backward-integrated Asian giants, European carbon-certified specialists, and North American craft-brewing focused portfolios. M&A activity concentrates on strain library acquisitions and precision fermentation technology licensing.
Within the integrated tier, Angel Yeast Co., Ltd. exemplifies backward integration into agricultural feedstocks, while Lesaffre Group occupies a position bridging European baking supply chains with pharmaceutical-grade fermentation. Lallemand Inc. anchors the North American specialist archetype. These three represent distinct competitive positioning vectors: captive raw material security, regulatory-grade certification depth, and regional application focus respectively.
| Leading Market Players |
|---|
| Angel Yeast Co., Ltd. |
| Koninklijke DSM N.V. |
| Lesaffre Group |
| Kerry Group |
| Alltech |
| Associated British Foods plc |
| Chr. Hansen Holding A/S |
| Archer Daniels Midland Company |
| Lallemand Inc. |
| Others |
Supply & Pricing Matrix
Family-owned fermentation specialists across Europe and Asia anchor supply discipline through captive molasses sourcing networks, translating agricultural feedstock security into pricing power that resists spot-market volatility in downstream baking and brewing contracts.
Pricing Analysis
Molasses cost pass-through dominates pricing structures, with Brazilian sugarcane harvest fluctuations and Indian ethanol diversion policies creating input cost swings that compress toll fermentation margins. Pricing stratifies across pharmaceutical-grade, food-grade, and feed-grade tiers, with EU Green Deal carbon certification commanding premiums from industrial bakeries in Germany and the Netherlands. Cost compression in commodity baker's yeast is intensifying because chemical leavening substitutes capture price-sensitive segments in Nigeria and Pakistan. Food manufacturers consolidating procurement across baking, brewing, and nutritional applications exhibit lowest price sensitivity, while animal feed formulators remain most exposed to margin pressure.
Supply Chain Analysis
Temperature-controlled liquid yeast tanker logistics absorb 12-18% of delivered cost for large-scale ethanol and pharmaceutical fermentation, constraining viable supply radii around molasses-fed bioreactor clusters in China, Brazil, and India. Raw material dependencies center on sugarcane molasses, corn steep liquor, and nitrogen supplements for aerobic culture propagation. Single-source strain vulnerability concentrates biosafety risk, with three legacy suppliers controlling pharmaceutical-grade Saccharomyces cerevisiae banks. Distribution runs through regional blending facilities and direct tanker delivery to industrial bakeries and brewing operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with EU Green Deal carbon accounting mandates and FDA pharmaceutical-grade registration requirements filtering demand toward certified suppliers with verified fermentation footprints and strain documentation capabilities.
For Market Incumbents: Cement leadership by deepening backward integration into molasses sourcing networks in São Paulo and Yangtze River Delta corridors, while accelerating perfusion bioreactor retrofits to capture pharmaceutical extract premiums. Precision fermentation startups threaten high-margin nutritional applications through compressed development cycles; defend by locking industrial bakeries into multi-year carbon-certified supply agreements with batch-level traceability. For New Entrants and Emerging Players: Toll manufacturers in Singapore and Indonesia offer the most penetrable channel partnership route, given Java's instant noodle-driven yeast extract autolysate demand that outpaces domestic fermentation capacity. Target USDA organic certification arbitrage opportunities serving North American packaged goods manufacturers facing EU non-tariff barriers. A precision fermentation licensing play combined with continuous bioreactor engineering expertise enables animal-free protein production without legacy strain library investments. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier toll fermentation houses exposed to Brazilian procurement consolidation and molasses price volatility. Long-term viability hinges on regulatory-grade certification depth and carbon accounting infrastructure across the analysis window. Acquire strain library assets with pharmaceutical-grade documentation and GMP-compliant scale-up capabilities. The signal to watch is EFSA novel food assessment timelines for CRISPR-edited yeast chassis, which would accelerate precision fermentation convergence and reshape competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Molasses Sourcing | Captive agricultural feedstock supply in São Paulo and Minas Gerais insulates margin volatility from Brazilian sugarcane harvest swings. |
| Perfusion Bioreactor Retrofit | German and Dutch pharmaceutical extract manufacturers absorb technical risk while compressing unit economics for high-purity yeast autolysates. |
| Carbon Certification Investment | Batch-level carbon intensity certificates preempt EU Green Deal friction for industrial bakeries in Bavaria and North Rhine-Westphalia. |
| Strain Library Acquisition | Pharmaceutical-grade Saccharomyces cerevisiae banks with GMP documentation address biosafety concentration risk for vaccine adjuvant manufacturers. |
| Toll Manufacturing Partnership | Singapore-based strain developers bypass Indonesia's bioprocess engineering scarcity to serve Java's instant noodle seasoning manufacturers. |
Research Methodology
Direct dialogue with fermentation plant managers, procurement leads at multinational food processors, pharmaceutical excipient buyers, and craft brewing operations directors grounded qualitative insights, validated against customs and trade data, SEC filings from listed ingredient suppliers, EFSA novel food assessment registers, and SAMR pharmaceutical registration databases. Bottom-up capacity modeling across molasses-fed bioreactor installations and top-down demand triangulation from bakery, brewing, and supplement consumption patterns converged on volume estimates.
Bottom-up strain production capacity by facility combined with top-down end-use consumption surveys across baking, brewing, pharmaceutical, and animal feed applications. Segmentation dimensions spanned product type, physical form, application tier, and customer scale. CAGRs derived from facility expansion announcements, regulatory approval timelines, and procurement contract duration shifts. Molasses supply elasticity and carbon border adjustment implementation schedules served as industry-specific forecast inputs across the modeling period.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal carbon accounting enforcement, precision fermentation regulatory clarity, and Brazilian ethanol diversion policy shifts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
United Kingdom Food Preservatives Market
Food Additives and Ingredients
Ammonia Caramel Market
Food Additives and Ingredients
China Food Preservatives Market
Food Additives and Ingredients
Food Enzymes Market
Food Additives and Ingredients
United States Food Acidulants Market
Food Additives and Ingredients
Food Glazing Agents Market
Food Additives and Ingredients
Germany Food Additives Market
Food Additives and Ingredients
Meat Stabilizers Blends Market
Food Additives and Ingredients
Food Antifoaming Agents Market
Food Additives and Ingredients
Hydrocolloids Market
Food Additives and Ingredients
Italy Food Emulsifier Market
Food Additives and Ingredients
Biscuit Shortening Flakes Market
Food Additives and Ingredients
Feed Anti-Caking Agents Market
Food Additives and Ingredients
Russia Food Acidulants Market
Food Additives and Ingredients
Monostarch Phosphate Market
Food Additives and Ingredients
Food Binders Market