
 Titanium-Free Food Color Alternatives Market | 2026-2036
Titanium-Free Food Color Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
Titanium-Free Food Color Alternatives Market Analytics
Plant-derived extraction and fermentation-based pigment synthesis is tilting formulation pipelines away from mineral opacity agents. Sensient Technologies Corporation leverages its botanical extraction infrastructure to supply spirulina and butterfly pea-derived blue alternatives at commercial scale. Chr. Hansen Holding A/S anchors its position through fermentation-derived carmine and lutein platforms that bypass titanium dioxide entirely in confectionery coatings. Archer Daniels Midland Company competes across the natural color spectrum with vertically integrated agricultural sourcing from annatto and turmeric cultivars.
Titanium-free food color alternatives comprise pigments, opacifiers, and whitening agents formulated without titanium dioxide (E171), typically employing calcium carbonate, starch-based complexes, or algae-derived phycocyanin to achieve comparable opacity and hue stability in pH ranges of 3.0 to 8.0. These substitutes serve food manufacturers seeking to maintain visual shelf appeal while eliminating nanoparticle whitening agents from ingredient declarations. Natural dyes now lead product type demand as beverage producers and confectionery houses face retailer mandates for simplified labels, though synthetic dye alternatives retain share in cost-sensitive sauce applications where heat stability requirements exceed plant-derived performance thresholds. Powdered and liquid forms dominate the channel, with gel formats gaining traction in artisan bakery segments where precise viscosity control matters.
EFSA's 2021 reclassification of E171 as a food additive no longer considered safe, REACH compliance obligations for nanoparticle characterization, and FDA guidance on color additive petition pathways collectively reshape product development timelines and market access requirements for titanium-free alternatives. The EU Green Deal chemical sustainability targets further pressure manufacturers to validate biodegradability and sourcing transparency across natural dye supply chains. Stakeholders must monitor pending FDA decisions on titanium dioxide petition withdrawals and align R&D portfolios with emerging state-level labeling requirements that could fragment North American formulation standards.
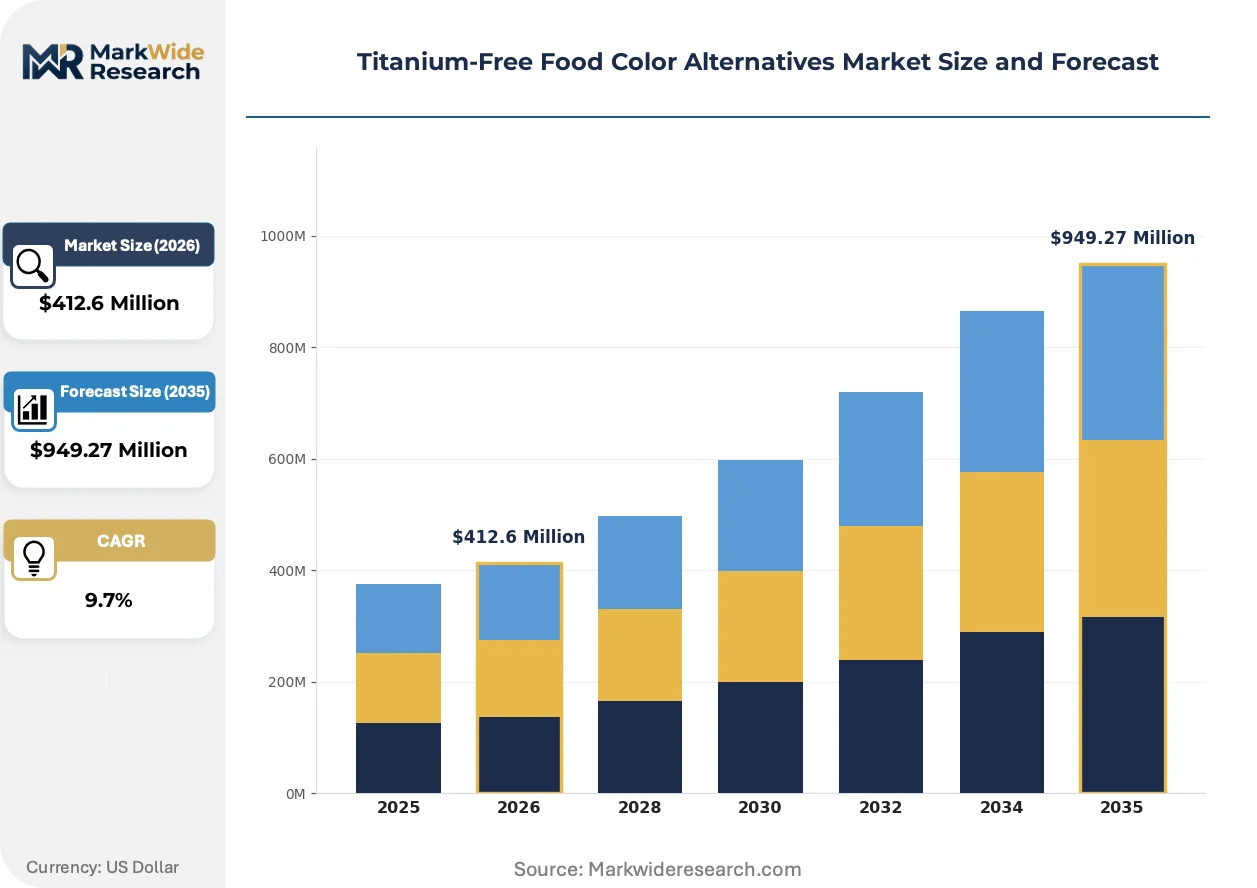
Market Dynamics
EFSA's 2021 E171 safety reclassification has forced immediate reformulation across European confectionery and beverage manufacturing, compressing development timelines from years to months as brands race to maintain shelf appeal without titanium dioxide whitening agents.
Growth Catalysts
- Retailer-Led Ingredient Bans:Carrefour and E.Leclerc in France now mandate titanium-free formulations across private-label confectionery, creating procurement pull-through that extends to branded suppliers.
- EU Green Deal Chemical Targets:Biodegradability validation requirements under the EU's chemical sustainability framework favor plant-derived pigments over synthetic mineral alternatives in public procurement.
- Fermentation-Based Pigment Synthesis:Precision fermentation platforms for carmine and lutein production achieve cost parity with extraction methods while eliminating agricultural weather risk.
Market Restraints
- Spirulina Supply Concentration:Over 70% of food-grade phycocyanin originates from Chinese and Indian algae cultivation facilities, creating single-source vulnerability for blue pigment formulations.
- Heat Stability Limitations:Plant-derived anthocyanins degrade above 85°C, excluding them from UHT-processed dairy applications where synthetic alternatives retain performance.
- REACH Nanoparticle Characterization:Compliance costs for particle-size distribution testing of alternative opacifiers add 15-20% to raw material qualification expenses.
Strategic Opportunities
- Butterfly Pea Flower Expansion:Thai and Vietnamese agricultural cooperatives are scaling cultivation of Clitoria ternatea for pH-responsive blue pigments in functional beverages.
- State-Level US Labeling Momentum:California's pending titanium dioxide disclosure requirements create first-mover advantage for reformulated products entering West Coast retail channels.
- 3D Food Printing Integration:Gel-based natural color systems enable precise deposition control in additive manufacturing of customized confectionery shapes.
Industry Challenges
- Color Matching Expertise Gap:Formulation chemists trained on mineral opacifiers lack experience balancing opacity, pH stability, and lightfastness in plant-derived systems.
- Clean-Label Certification Timelines:Non-GMO Project and EU organic verification for new algae-sourced pigments extends go-to-market schedules by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Titanium-Free Food Color Alternatives Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $949.27 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Dyes, Synthetic Dyes, Concentrates, Powders End User: Food Manufacturers, Beverage Producers, Confectionery, Bakery Application: Desserts, Sauces, Snacks, Dairy Products Form: Liquid, Powdered, Gel, Granulated |
| Companies Covered | Sensient Technologies Corporation, Chr. Hansen Holding A/S, Archer Daniels Midland Company, Royal DSM, GNT Group, Döhler Group, BASF, Kerry Group, IFC Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Titanium-Free Food Color Alternatives Market Evolving Landscape
Digital color formulation platforms are compressing the traditional trial-and-error development cycle, enabling rapid matching of titanium dioxide opacity profiles using predictive spectral modeling rather than iterative bench testing.
Microencapsulation technology is virtualizing pigment protection. Lipid-shell encapsulation of beet-derived betalains extends heat stability from 30 minutes to 4 hours at 90°C. Bakery manufacturers in Germany and the Netherlands are adopting these systems for fruit-filled pastries. This virtualization is collapsing the performance gap between natural and synthetic colorants in thermally stressed applications.
REACH Annex XVII restrictions on microplastics are accelerating starch-based opacifier development. The European Chemicals Agency's 2023 guidance on biodegradable alternatives mandates water dispersibility standards that exclude conventional polymer carriers. Coating manufacturers for chewing gum and pan-coated confectionery are reformulating around modified rice starch complexes to maintain opacity while meeting biodegradability thresholds.
Direct-to-manufacturer pigment sourcing is fragmenting traditional distribution channels. Mid-sized confectionery houses in Belgium and Switzerland now contract directly with Peruvian turmeric extractors and Indian annatto processors, bypassing European color houses. This disintermediation compresses margin structures for distributors while rewarding agricultural traceability investments with price premiums from clean-label buyers.
Titanium-Free Food Color Alternatives Market Segmentation
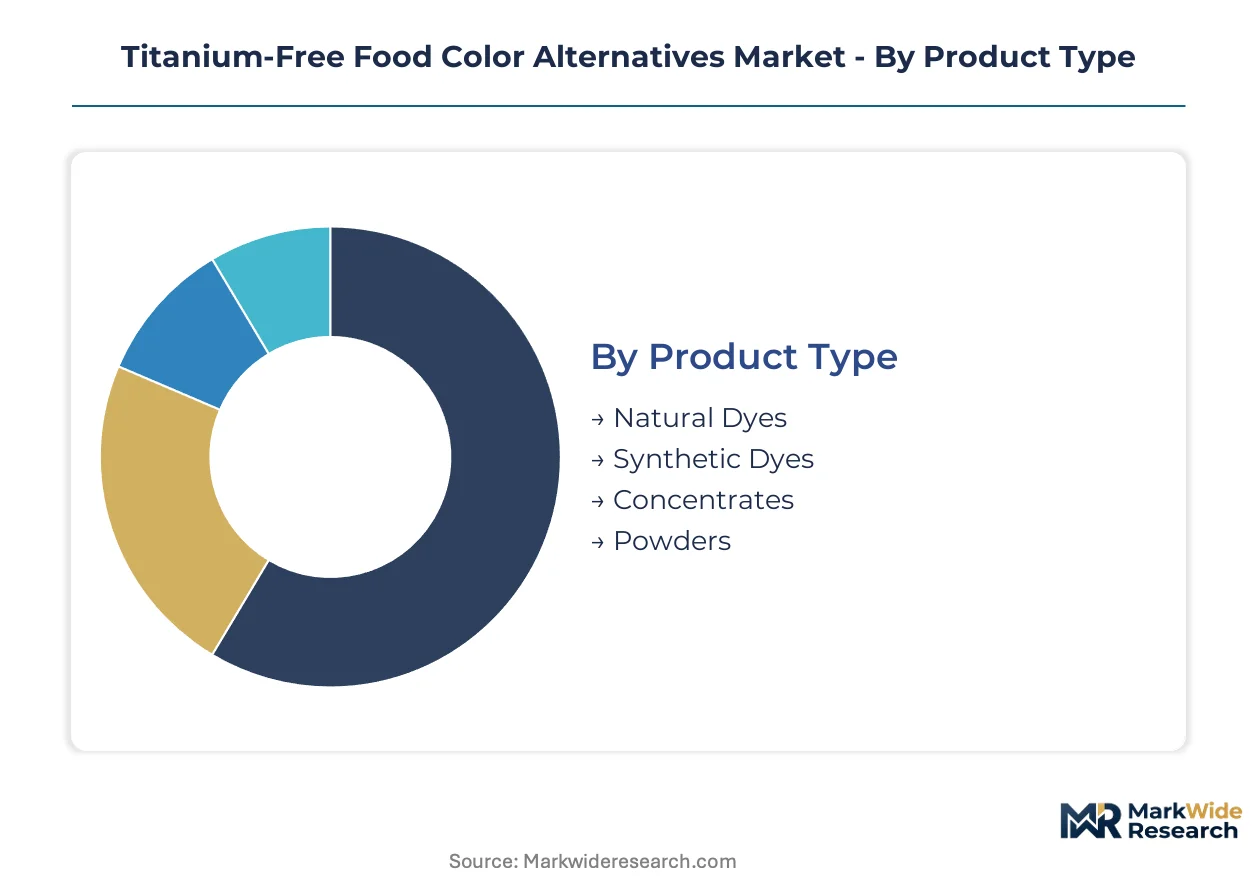
Segmentation in titanium-free food color alternatives reveals how reformulation pressures fragment across product formats and processing requirements. Manufacturers must match pigment stability profiles to specific thermal and pH conditions while navigating retailer clean-label mandates.
Product Type:
Mature extraction platforms dominate volume, while fermentation-based synthesis emerges as the cost-competitive frontier for carmine and lutein alternatives.
- Natural Dyes:Spirulina-derived phycocyanin and butterfly pea flower extracts provide pH-responsive blue hues with opacity comparable to mineral whiteners at neutral pH ranges. German and French confectionery houses now specify these for E171-compliant coatings under EFSA guidance, though spirulina supply concentration in Chinese cultivation facilities creates procurement vulnerability.
- Synthetic Dyes:Heat-stable azo and triarylmethane compounds retain formulation share in cost-sensitive sauce applications where UHT processing exceeds 120°C. These formulations face declining retailer acceptance as clean-label mandates tighten across Western European retail channels.
- Concentrates:High-solid pigment suspensions reduce transportation costs for beverage producers seeking volumetric efficiency.
- Powders:Spray-dried formulations serve dry-mix manufacturers requiring extended shelf stability without refrigeration.
Natural dyes handle the majority of throughput; concentrates are expanding most quickly as beverage brands consolidate supplier relationships.
End User:
Customer scale determines formulation service intensity, from multinational procurement teams to artisan bakery operators.
- Food Manufacturers:Industrial sauce and ready-meal producers balance heat stability requirements against clean-label positioning, often defaulting to synthetic alternatives where thermal processing demands exceed natural pigment thresholds. EFSA's E171 reclassification has accelerated RFP activity for titanium-free opacifiers across frozen dessert and prepared sauce categories.
- Beverage Producers:Functional drink brands in Germany and France drive demand for pH-responsive anthocyanin systems that shift color with acidity changes, creating visual differentiation in premium positioning. These formulations require microencapsulation to prevent degradation during pasteurization.
- Confectionery:Pan-coating and shellac applications demand high-opacity alternatives to titanium dioxide whitening in chewing gum and chocolate dragée production.
- Bakery:Artisan and industrial bakers seek heat-stable betalain systems for fruit fillings and decorative icings.
Food manufacturers represent the largest procurement volume; beverage producers are climbing the fastest on share as functional drink launches multiply.
Application:
Thermal stress tolerance creates a performance hierarchy that filters pigment selection by processing intensity.
- Desserts:Frozen and refrigerated applications favor anthocyanin and carmine systems where heat exposure remains minimal. German retail chains now mandate titanium-free formulations across private-label ice cream and mousse products.
- Sauces:Ketchup and dressing manufacturers face the steepest technical barriers, as tomato-based acidity and retort processing degrade most natural pigments within minutes.
- Snacks:Seasoning and coating applications for extruded products require lipid-dispersible pigments that survive spray-drying and oil contact.
- Dairy Products:Yogurt and fresh cheese applications leverage spirulina and butterfly pea for visual appeal without thermal degradation concerns.
Desserts absorb the highest pigment volume; dairy products are gaining share fastest as clean-label positioning penetrates fermented categories.
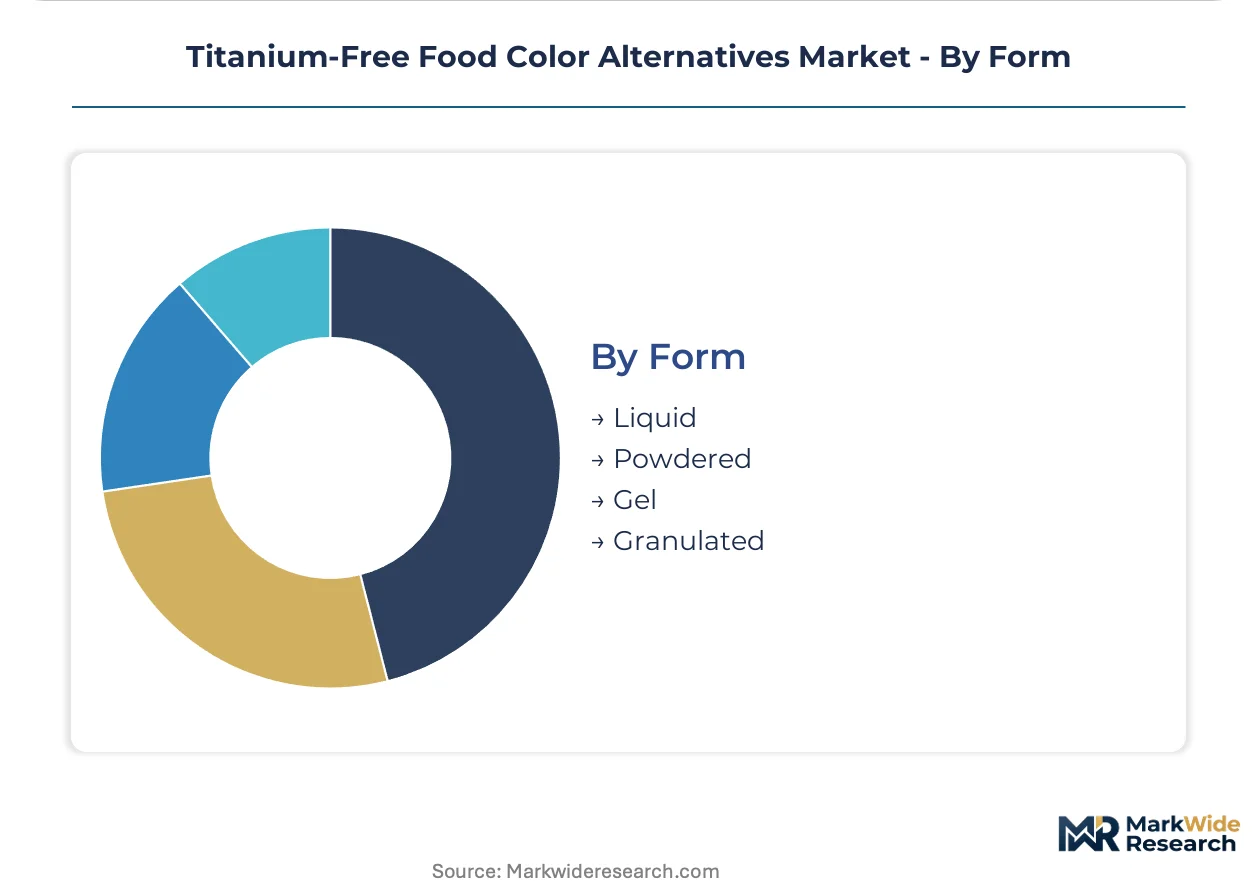
Form:
Physical state determines dosing precision, shelf stability, and compatibility with existing manufacturing infrastructure.
- Liquid:Pumpable suspensions integrate directly into continuous processing lines for beverage and sauce manufacturing, eliminating dust exposure and hydration steps. These formats dominate high-volume procurement contracts with multinational food manufacturers.
- Powdered:Spray-dried and agglomerated pigments serve dry-blend applications where water activity control prevents caking, particularly in seasoning and bakery premix segments.
- Gel:Viscous concentrates enable precise deposition control in 3D food printing and artisan decoration where droplet definition matters.
- Granulated:Free-flowing particles reduce dusting in industrial handling environments for large-scale confectionery operations.
Liquid forms carry the bulk of commercial volume; gel formats are expanding most rapidly as additive manufacturing applications develop.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Private-label confectionery buyers in Germany and France dominate procurement volumes, while beverage reformulation in the United States and dairy innovation in Japan create secondary demand centers for titanium-free pigment systems.
Germany
Retail chains Rewe and Aldi Süd enforce titanium-free private-label standards across confectionery and frozen dessert portfolios. EFSA's E171 reclassification under EU regulation 2022/63 mandates immediate reformulation for products entering German distribution. The Cologne-Düsseldorf corridor hosts reformulation service labs where Sensient Technologies and Döhler Group support mid-sized chocolate manufacturers migrating from mineral opacifiers to calcium carbonate and spirulina-based alternatives.
France
Carrefour and E.Leclerc procurement teams require E171-free declarations across chewing gum and dragée categories, compressing supplier qualification timelines. ANSM enforces nanoparticle characterization standards for alternative opacifiers under REACH Annex XVII microplastic restrictions. The Lyon-Grenoble cluster concentrates fermentation-based pigment R&D where Chr. Hansen Holding A/S operates carmine production facilities serving pan-coating applications.
United States
Functional beverage brands in California and New York Metro drive demand for pH-responsive anthocyanin systems that shift color with acidity changes. FDA guidance on color additive petition pathways delays market entry for novel algae-derived pigments, though state-level disclosure requirements in California accelerate reformulation planning. Chicago-area flavor houses now integrate titanium-free whitening specifications into national account contracts for carbonated soft drink manufacturers.
Japan
Premium yogurt and fresh cheese producers leverage spirulina and butterfly pea extracts for visual differentiation in fermented dairy. METI's Food Labeling Standards require additive transparency that disadvantages synthetic mineral opacifiers against plant-derived alternatives. The Kansai region around Osaka hosts ingredient trading houses that import Thai butterfly pea flower extracts for pH-responsive beverage applications targeting health-conscious urban consumers.
Netherlands
Amsterdam-Rotterdam logistics hubs distribute titanium-free color systems to Benelux confectionery exporters serving UK and Scandinavian markets. ECHA's 2023 guidance on biodegradable alternatives mandates water dispersibility standards that exclude conventional polymer carriers. Wageningen University research partnerships accelerate starch-based opacifier development for chewing gum manufacturers reformulating around modified rice starch complexes.
Titanium-Free Food Color Alternatives Market Competitive Landscape
Channel-controlling players compete with product-specialist players across formulation service tiers. The market structures around three archetypes: multinational ingredient houses with botanical extraction infrastructure, fermentation-based pigment specialists with precision biology platforms, and regional color houses with direct agricultural sourcing relationships. Consolidation pressure intensifies as retailer mandates compress qualification timelines, favoring players with integrated regulatory affairs capabilities. Strategic moves concentrate on backward integration into algae cultivation and partnerships with agricultural cooperatives in Southeast Asia.
Within the multinational tier, Sensient Technologies Corporation and Chr. Hansen Holding A/S exemplify divergent technology bets—botanical extraction versus fermentation biology—while Archer Daniels Midland Company occupies a position anchored in vertically integrated agricultural sourcing from turmeric and annatto cultivars.
| Leading Market Players |
|---|
| Sensient Technologies Corporation |
| Chr. Hansen Holding A/S |
| Archer Daniels Midland Company |
| Royal DSM |
| GNT Group |
| Döhler Group |
| BASF |
| Kerry Group |
| IFC Solutions |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese spirulina cultivation facilities is compressing phycocyanin spot prices while tightening margins for European extraction houses, forcing reformulation service providers to absorb qualification costs or shift toward long-term offtake contracts with Indian algae cooperatives.
Pricing Analysis
Cost-plus contracts indexed to agricultural commodity benchmarks dominate natural dye procurement, with turmeric and annatto formulations tracking Indian spot markets and spirulina derivatives pegged to Chinese biomass futures. Price differentiation rests on organic certification tier and cold-chain logistics requirements, with EU organic-compliant spirulina commanding premiums over conventional grades. Pricing pressure stems from retailer consolidation in Germany and France, where Carrefour and Aldi Süd squeeze supplier margins through volume concentration. Mid-sized confectionery houses exhibit highest price sensitivity due to limited reformulation budgets, while multinational beverage producers absorb premiums for pH-responsive anthocyanin systems.
Supply Chain Analysis
Export-control restrictions on biotechnology equipment under EU dual-use regulations are constraining precision fermentation capacity expansion for carmine and lutein platforms, fragmenting supply chain development across jurisdictions. Geographic concentration centers on China for spirulina biomass, India for annatto and turmeric extracts, and Peru for betalain-rich beet varieties. Raw material dependencies include food-grade algae cultivation media, organic solvent extraction systems, and modified starch carriers for opacifier applications. Single-source vulnerability in Chinese phycocyanin supply creates structural risk for blue pigment formulations. Distribution runs through Rotterdam and Hamburg logistics hubs serving Benelux and German confectionery exporters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against mineral opacifier re-entry if EFSA reverses E171 guidance, requiring incumbents to lock in formulation partnerships before regulatory uncertainty resolves.
For Market Incumbents: Build regulatory affairs capabilities as the primary moat. Secure early-mover certification under EU organic and Non-GMO Project standards to extend qualification timelines for challengers. Anchor long-term supply contracts with Thai butterfly pea cooperatives before agricultural traceability premiums inflate. Fermentation-based pigment specialists threaten botanical extraction margins through cost parity achievement. For New Entrants and Emerging Players: Artisan bakery gel formats in the Netherlands and Belgium represent the most penetrable entry point, bypassing multinational procurement gatekeepers. California functional beverage reformulation creates West Coast beachhead demand for pH-responsive anthocyanin systems. Direct-to-manufacturer sourcing relationships with Peruvian turmeric extractors enable margin capture disintermediating European color houses. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across fermentation-based pigment synthesis as precision biology platforms achieve scale economies. Five-to-ten year viability favors specialists with integrated regulatory affairs and agricultural traceability capabilities. Acquisition targets should demonstrate captive cultivation relationships or patented encapsulation technology. Monitor FDA petition withdrawal timelines as inflection signal for North American market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Algae Cultivation | Captive spirulina supply insulates against Chinese concentration risk for phycocyanin-dependent formulations. |
| Precision Fermentation Scale-Up | Chr. Hansen's carmine platforms demonstrate cost parity potential eliminating agricultural weather exposure. |
| Microencapsulation Technology Licensing | Lipid-shell betalain protection extends heat stability for bakery applications previously excluded from natural dye conversion. |
| Direct Agricultural Sourcing Partnerships | Belgian confectionery houses bypass distributor margins through Peruvian turmeric and Indian annatto contracts. |
| Regulatory Pre-Qualification Investment | Early EU organic and REACH Annex XVII compliance accelerates procurement pull-through from retailer mandates. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with formulation chemists at German and French confectionery houses, procurement leads at Carrefour and Aldi Süd, technical directors at Sensient Technologies and Döhler Group, and regulatory affairs specialists navigating EFSA and FDA petition pathways. Secondary validation drew from EFSA scientific opinions, REACH Annex XVII guidance documents, EU customs trade data for natural dye imports, and SEC filings of publicly traded ingredient houses. Bottom-up pigment volume estimates by application were triangulated against top-down market size calculations from reformulation service provider contract values.
Calibration against historical E171 displacement rates in Germany and France informed adoption curve assumptions across the projection horizon. Segmentation modeling incorporated product type, end-user scale, thermal processing intensity, and physical form dimensions. CAGRs were derived from logistic diffusion curves fitted to retailer mandate implementation timelines. Industry-specific inputs included spirulina cultivation capacity expansion announcements, fermentation platform yield improvements, and microencapsulation patent filings.
Macroeconomic conditions sit as an overlay; deviation in euro-dollar exchange rates or agricultural commodity price volatility would shift the trajectory of cross-border sourcing economics. Forecasts reflect documented assumptions regarding EFSA regulatory stability and FDA petition processing timelines. Cross-checking against EU organic certification database growth rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Russia Food Acidulants Market
Food Additives and Ingredients
Locust Bean Gum Market
Food Additives and Ingredients
India Food Colorants Market
Food Additives and Ingredients
DATEM Replacement Market
Food Additives and Ingredients
Spain Food Additives Market
Food Additives and Ingredients
Oleic Acid Market
Food Additives and Ingredients
PVPP Beer Stabilizer Market
Food Additives and Ingredients
China Food Additives Market
Food Additives and Ingredients
Food Glazing Agents Market
Food Additives and Ingredients
Africa Feed Additives Market
Food Additives and Ingredients
Africa Food Stabilizers Market
Food Additives and Ingredients
Edible and Soluble Films Market
Food Additives and Ingredients
Europe Clean Label Ingredient Market
Food Additives and Ingredients
Food and Beverages Color Fixing Agents Market
Food Additives and Ingredients
Xanthan Gum Market
Food Additives and Ingredients
Distilled Monoglycerides Market