
 Extended Wear Contact Lens Market | 2026-2036
Extended Wear Contact Lens Market Size, Share, and Industry Trends Forecast 2026-2036
Extended Wear Contact Lens Market Analytics
Young professional demand for overnight-capable vision correction is hardening as work-from-anywhere lifestyles normalize extended wear patterns. Johnson & Johnson Vision Care leverages its silicone hydrogel R&D pipeline to sustain premium positioning in North American retail channels. CooperVision anchors European distribution through optometrist partnerships, while Bausch + Lomb competes on price-accessible daily disposable alternatives that pressure extended wear margin pools.
Extended wear contact lenses are soft hydrogel or silicone hydrogel devices engineered for continuous corneal oxygen transmission exceeding 80 Dk/t, permitting overnight retention without removal for seven to thirty days depending on material specification and regulatory clearance. Their primary commercial purpose is reducing handling frequency for users seeking convenience while maintaining corneal health through high-permeability polymer matrices. Silicone hydrogel dominates product type value pools due to superior oxygen permeability that commands price premiums over conventional hydrogel formulations, while multifocal configurations capture margin expansion from aging presbyopic populations. Online platforms represent the fastest-growing end user channel as direct-to-consumer lens subscription models displace traditional optical retail.
FDA 510(k) clearance pathways govern overnight wear claims in the United States, while CE marking under the EU MDR and Japan's PMDA pharmaceutical affairs standards shape market access across their respective jurisdictions. These frameworks enforce clinical trial thresholds for hypoxia-related adverse events that filter out lower-permeability competitors. Stakeholders must monitor how FDA draft guidance on continuous wear labeling evolves against emerging water gradient technologies that blur traditional category boundaries.
Market Dynamics
Silicone hydrogel oxygen permeability thresholds are compressing the competitive set as FDA 510(k) clearance pathways filter out lower-performance materials, concentrating commercial viability among polymer innovators with clinical trial capabilities.
Growth Catalysts
- Overnight Wear Normalization:Young professionals adopting work-from-anywhere lifestyles are expanding addressable demand for multi-day continuous use lenses, particularly in urban United States corridors where convenience premiums sustain.
- FDA 510(k) Pathway Clarity:Established regulatory frameworks for hypoxia-related adverse event thresholds provide predictable market access timelines for silicone hydrogel formulations meeting 80+ Dk/t specifications.
- Presbyopic Population Expansion:Multifocal extended wear configurations capture margin expansion from aging demographics seeking single-solution vision correction without reading glasses supplementation.
Market Restraints
- Silicone Monomer Supply Concentration:Specialty polymer feedstock production clusters in select East Asian chemical manufacturing hubs, creating input cost volatility exposure for Western lens fabricators.
- Corneal Infection Liability Thresholds:Overnight wear claims trigger elevated clinical trial requirements and post-market surveillance obligations that extend time-to-revenue for new entrants.
- Daily Disposable Substitution:Price-accessible single-use alternatives compete for convenience-oriented segments, pressuring extended wear margin pools in price-sensitive distribution channels.
Strategic Opportunities
- Direct-to-Consumer Subscription Models:Online platform distribution is consolidating purchasing power away from traditional optical retail, enabling margin capture through recurring revenue structures.
- EU MDR CE Marking Expansion:Harmonized European regulatory pathways offer streamlined multi-country market access for silicone hydrogel innovations meeting biocompatibility standards.
- Water Gradient Technology Convergence:Hybrid material architectures combining silicone hydrogel cores with surface hydration layers blur traditional category boundaries and open premium positioning.
Industry Challenges
- Optometrist Channel Dependence:Fitting and prescription workflows require professional intermediation, complicating pure direct-to-consumer scaling and increasing customer acquisition costs.
- ISO 18369-3 Compliance Timelines:International standardization for contact lens physical properties extends certification cycles, delaying product launches and compressing effective patent windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Extended Wear Contact Lens Market |
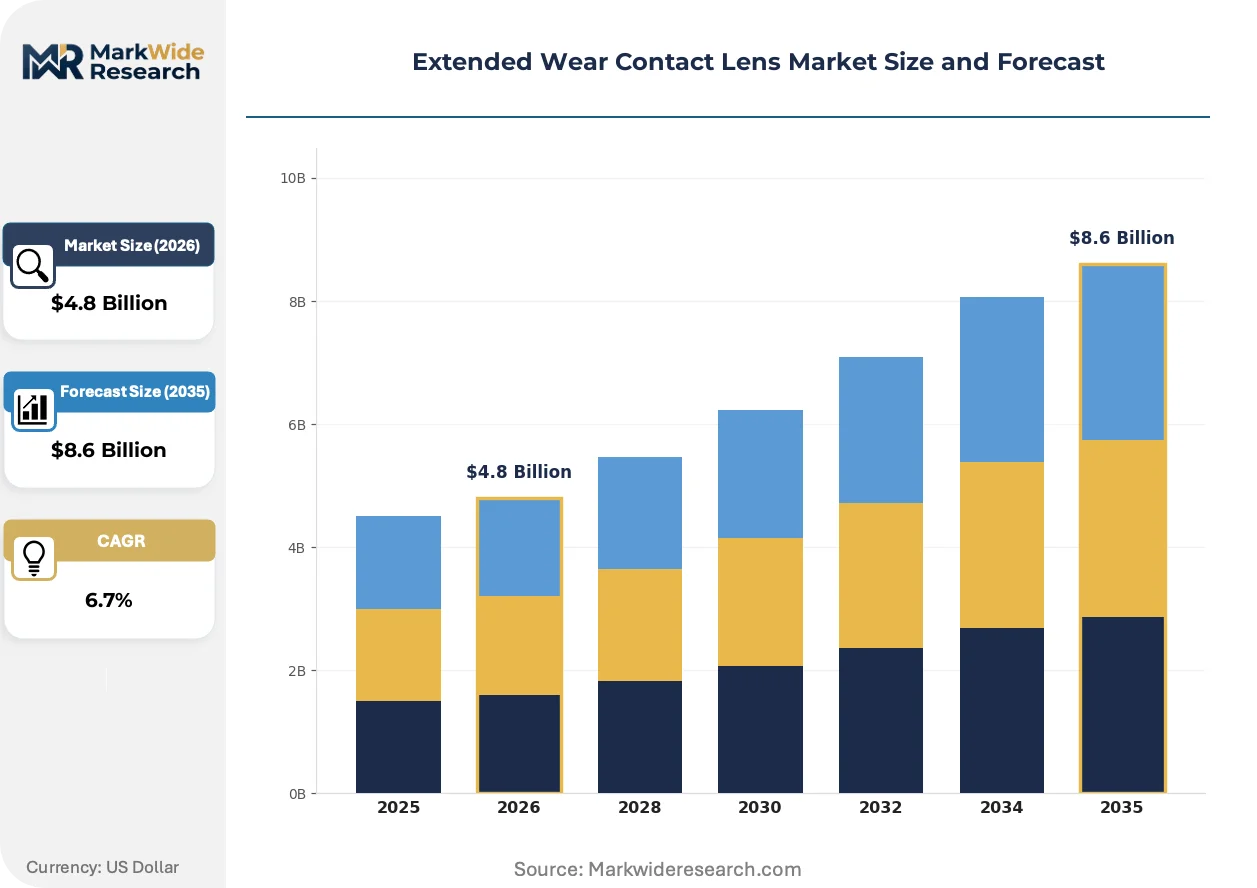
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Hydrogel, Daily Disposable, Extended Wear, Multifocal Application: Astigmatism, Presbyopia, Myopia, Hyperopia End User: Retail Chains, Online Platforms, Hospitals, Clinics Technology: Wettable Surface, Oxygen Permeability, UV Blocking, Water Gradient |
| Companies Covered | Johnson & Johnson Vision Care, Novartis (Alcon), CooperVision, Bausch + Lomb, Menicon, NEO Vision, Weicon Group, St. Shine Optical, Bescon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Extended Wear Contact Lens Market Evolving Landscape
Material science convergence with digital distribution infrastructure is restructuring how extended wear lenses reach end users, compressing traditional optical retail intermediation while elevating clinical performance thresholds.
Silicone hydrogel formulations are consolidating market viability as the dominant substrate for overnight-capable lenses, with oxygen permeability exceeding 80 Dk/t now table stakes for FDA clearance. Urban professional segments in the United States are adopting these materials fastest, driving manufacturers to prioritize high-Dk/t R&D pipelines over conventional hydrogel legacy lines. This technical consolidation is compressing viable competition to polymer specialists with clinical trial infrastructure.
EU MDR implementation is tightening biocompatibility documentation requirements for continuous wear claims, extending technical file preparation timelines and elevating notified body scrutiny levels. Manufacturers targeting European distribution must now demonstrate enhanced post-market surveillance capabilities alongside pre-market clinical evidence. Silicone hydrogel innovators with established quality management systems are capturing disproportionate access as smaller competitors face compliance resource constraints.
Subscription-based replenishment models are displacing episodic optical retail purchasing, particularly among digitally native demographics seeking automated lens delivery. E-commerce platforms and telehealth-integrated prescription services are capturing this behavioral shift, while traditional optometrist partnerships face margin compression from disintermediation. This channel rotation is most visible in United States metropolitan markets where convenience premiums justify premium pricing for automated fulfillment.
Extended Wear Contact Lens Market Segmentation
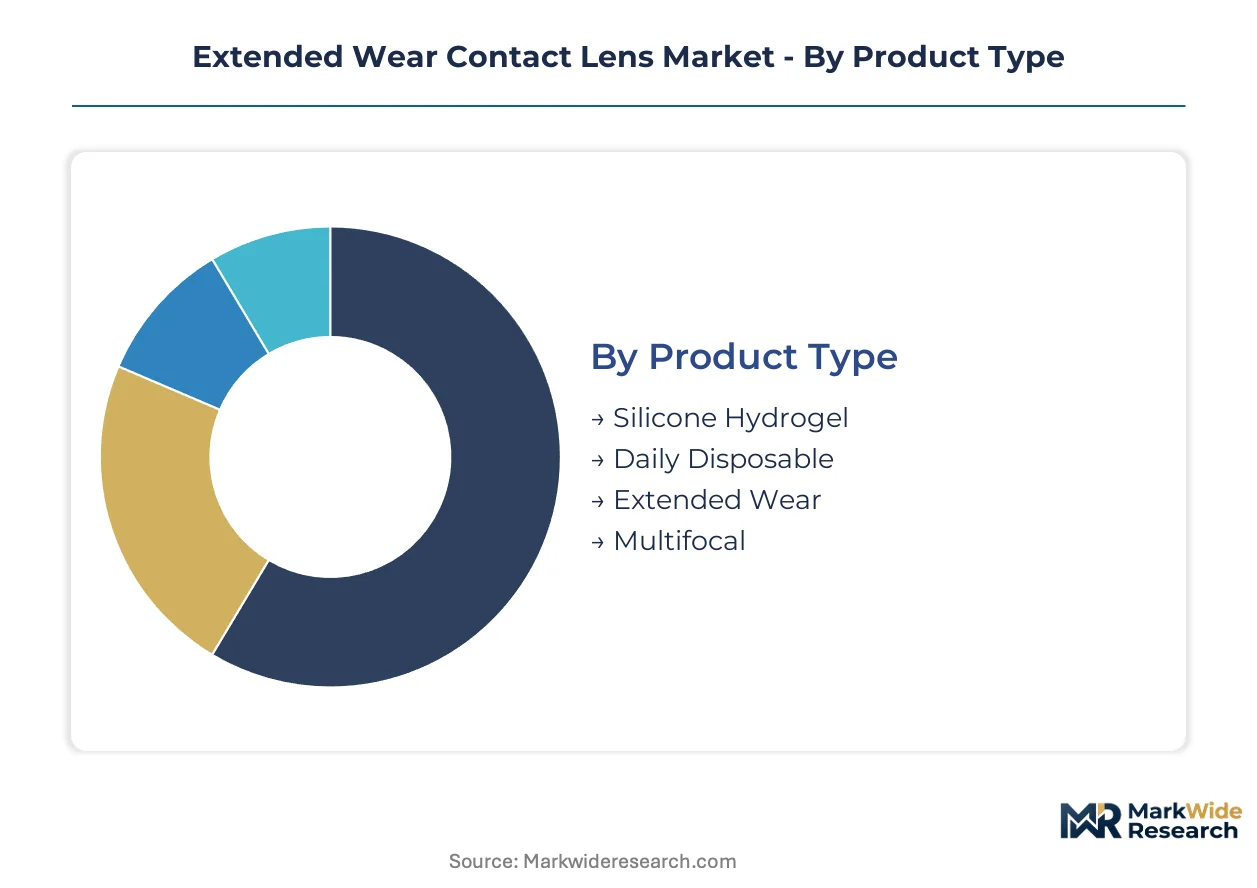
Extended wear contact lenses fragment across material chemistry, vision correction needs, distribution channels, and surface engineering specifications. Understanding these partitions reveals where oxygen permeability premiums concentrate and which patient populations drive replacement-cycle economics.
Product Type:
Replacement cycles in extended wear vary dramatically by material chemistry, with silicone hydrogel formulations commanding multi-week continuous wear versus daily disposables requiring daily disposal economics.
- Silicone Hydrogel:Polymer matrices incorporating siloxane groups achieve oxygen permeability exceeding 80 Dk/t, enabling FDA-cleared overnight retention for seven to thirty days. Urban professionals in United States metropolitan corridors pay convenience premiums for these formulations, particularly those with work-from-anywhere lifestyles normalizing multi-day continuous use.
- Daily Disposable:Single-use lenses eliminate cleaning regimens and storage solutions, capturing price-sensitive convenience seekers who prioritize hygiene simplicity over extended wear economics. These products compete aggressively on unit cost in retail chain channels, pressuring margin pools for multi-day alternatives in price-conscious segments.
- Extended Wear:Conventional hydrogel formulations permit shorter continuous wear periods than silicone hydrogel variants, typically cleared for overnight use up to seven days depending on regional regulatory thresholds.
- Multifocal:Zone-optimized optics address presbyopic vision correction within extended wear parameters, combining distance and near correction in single-lens solutions for aging demographics.
Silicone hydrogel sits at the top of the volume ranking, with multifocal configurations climbing the fastest as presbyopic populations expand.
Application:
Vision correction requirements determine fitting complexity and prescription renewal frequency, with astigmatism and presbyopia applications demanding more specialized clinical workflows than spherical corrections.
- Astigmatism:Toric lens designs stabilize on-eye orientation through prism ballast or thin-zone technologies, requiring precise axis alignment during fitting. These prescriptions concentrate among younger active demographics in United States urban markets, where extended wear convenience offsets handling complexity.
- Presbyopia:Simultaneous vision or segmented optical designs enable near and distance correction without reading glasses supplementation. Aging professional populations in metropolitan corridors drive fastest adoption, particularly those seeking single-solution vision correction for multi-day travel or remote work patterns.
- Myopia:Spherical correction for nearsightedness represents the foundational extended wear application, with straightforward fitting protocols supporting high-volume distribution.
- Hyperopia:Farsightedness correction in extended wear formats serves smaller patient populations, with lens thickness profiles varying significantly across power ranges.
Myopia maintains the largest installed base, though presbyopia applications are expanding most quickly as demographic shifts reshape demand composition.
End User:
Channel economics diverge sharply between professional-intermediated fitting workflows and direct-to-consumer replenishment models, with online platforms capturing growing share of recurring revenue streams.
- Online Platforms:Subscription-based replenishment models displace episodic optical retail purchasing among digitally native demographics, with telehealth-integrated prescription services reducing friction. United States metropolitan markets show strongest platform adoption, where automated fulfillment justifies premium positioning.
- Retail Chains:Mass-market optical retailers compete on price accessibility and immediate availability, though they face margin compression from disintermediation.
- Hospitals:Institutional procurement channels serve post-surgical and specialty vision correction cases requiring clinical oversight.
- Clinics:Independent optometrist practices retain fitting and prescription authority, complicating pure direct-to-consumer scaling despite channel rotation pressures.
Online platforms are gaining share fastest, while retail chains retain volume leadership in suburban and secondary markets.
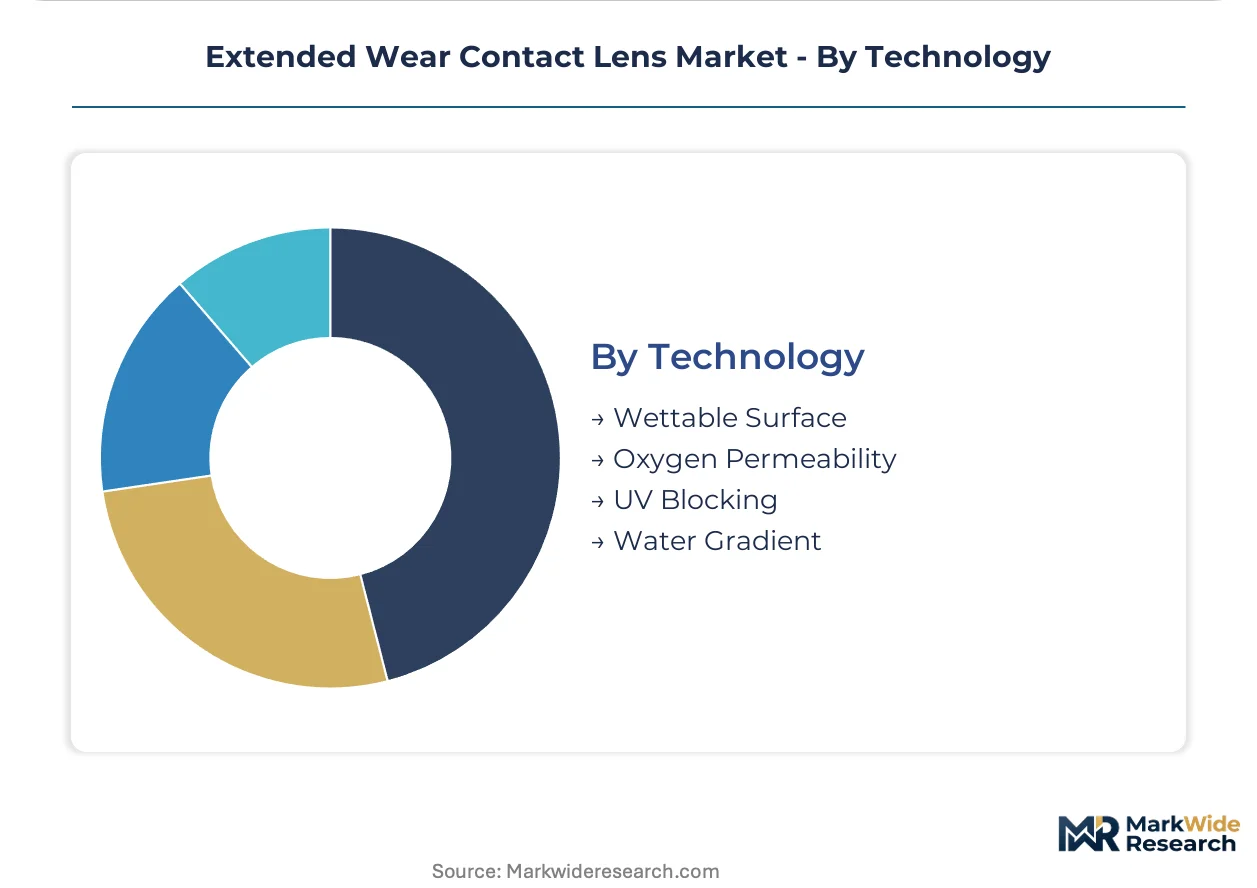
Technology:
Surface engineering and bulk material properties determine clinical performance thresholds, with oxygen permeability and wettability specifications filtering competitive viability through regulatory clearance pathways.
- Oxygen Permeability:Dk/t measurements above 80 define table stakes for overnight wear claims, with silicone hydrogel formulations dominating this specification tier. FDA 510(k) clearance pathways enforce these thresholds, filtering out lower-performance materials and concentrating viability among polymer specialists.
- Water Gradient:Hybrid architectures combining silicone hydrogel cores with surface hydration layers blur traditional category boundaries, enabling premium positioning through enhanced comfort profiles.
- Wettable Surface:Surface treatments reduce tear film disruption and improve on-eye comfort during extended wear periods.
- UV Blocking:Ultraviolet absorption additives address ocular health concerns for outdoor-active extended wear users.
Oxygen permeability commands the highest specification priority, while water gradient technology shows the steepest expansion trajectory as manufacturers pursue differentiated comfort positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States metropolitan corridors anchor demand concentration for silicone hydrogel formulations, with urban professional populations normalizing multi-day continuous wear patterns. Regulatory clarity from FDA 510(k) pathways and direct-to-consumer platform penetration are compressing traditional optical retail intermediation across major vision correction markets.
United States
Young professionals in New York, Los Angeles, and Chicago metro areas drive fastest adoption of seven-to-thirty-day continuous wear lenses as remote work patterns normalize overnight retention. FDA 510(k) clearance pathways provide predictable market access for formulations exceeding 80 Dk/t oxygen permeability. Johnson & Johnson Vision Care and CooperVision maintain concentrated R&D operations in California and New York state corridors.
Germany
EU MDR implementation is elevating biocompatibility documentation requirements for continuous wear claims, extending technical file preparation timelines for notified body submissions. CE marking under harmonized European regulatory pathways streamlines multi-country distribution for silicone hydrogel innovations. Alcon and Menicon leverage established quality management systems to capture disproportionate access across German-speaking markets.
Japan
PMDA pharmaceutical affairs standards enforce clinical trial thresholds for hypoxia-related adverse events that filter lower-permeability competitors from overnight wear segments. Aging presbyopic populations in Tokyo and Osaka metropolitan areas drive multifocal extended wear demand. Menicon anchors domestic manufacturing and distribution networks through optometrist partnership channels.
China
NMPA medical device registration pathways are tightening clinical evidence requirements for extended wear indications, concentrating viability among polymer specialists with trial infrastructure. Manufacturing clusters in Jiangsu and Zhejiang provinces supply silicone monomer feedstock to regional fabricators. Weicon Group and St. Shine Optical occupy positions within domestic production and distribution tiers.
United Kingdom
Post-Brexit regulatory divergence from EU MDR frameworks is creating parallel conformity assessment requirements for continuous wear lens manufacturers. London and Southeast England concentrate private optometry practice networks prescribing premium silicone hydrogel formulations. CooperVision leverages established European distribution infrastructure to serve UK demand through professional-intermediated channels.
Extended Wear Contact Lens Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbent players extend silicone hydrogel R&D pipelines across multifocal and toric configurations. The vendor base concentrates among four multinational ophthalmic care groups with established clinical trial infrastructure and regulatory affairs capabilities. Two strategic archetypes define competitive positioning: polymer innovation specialists with captive material science capabilities, and diversified vision care platforms leveraging optical retail channel control. M&A activity and technology licensing agreements represent the dominant competitive moves, with smaller regional fabricators seeking access to high-Dk/t formulation IP.
Among diversified vision care platforms, Johnson & Johnson Vision Care, Alcon, and CooperVision exemplify the scale-driven archetype through established North American and European distribution networks. These entities occupy positions spanning silicone hydrogel material development, regulatory clearance navigation, and professional channel penetration. Regional specialists including Menicon, NEO Vision, and St. Shine Optical represent alternative competitive positions anchored in Asia-Pacific manufacturing clusters and domestic market access. Bausch + Lomb sits within a hybrid tier competing on price-accessible alternatives that pressure extended wear margin pools in cost-sensitive channels.
| Leading Market Players |
|---|
| Johnson & Johnson Vision Care |
| Novartis (Alcon) |
| CooperVision |
| Bausch + Lomb |
| Menicon |
| NEO Vision |
| Weicon Group |
| St. Shine Optical |
| Bescon |
| Others |
Value Network & Pricing Analysis
Silicone hydrogel premiumization versus conventional hydrogel commoditization bifurcates value capture across the extended wear contact lens market, with oxygen permeability thresholds above 80 Dk/t anchoring subscription pricing power while lower-specification products compete on unit cost in retail chain channels. This performance ladder concentrates polymer R&D investment among FDA 510(k) clearance holders while forcing price-sensitive fabricators toward daily disposable alternatives that bypass overnight wear liability premiums.
Pricing Analysis
Silicone monomer cost pass-through from East Asian chemical manufacturing hubs directly pressures margin structures for Western lens fabricators lacking captive polymer supply. Three-tier pricing structure across premium silicone hydrogel, standard conventional hydrogel, and economy daily disposable levels separates convenience-oriented urban professionals from price-sensitive suburban consumers. Pricing pressure stems from daily disposable substitution in retail chains, where unit economics favor single-use hygiene simplicity over extended wear handling reduction. Price sensitivity concentrates among younger myopia-correcting users in secondary markets, while presbyopic multifocal adopters in metropolitan corridors exhibit lowest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with East Asian silicone monomer production clusters, where specialty polymer feedstock manufacturing concentrates in Jiangsu and Zhejiang provinces. Raw material dependencies span siloxane-based silicone monomers, hydrogel base polymers, and precision molding equipment for lens fabrication. Supply chain risk manifests through tariff exposure on optical-grade polymer imports into North American and European fabrication facilities. Distribution runs through dual-channel structures combining professional-intermediated optometrist fitting workflows with direct-to-consumer subscription fulfillment platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between United States premium pricing corridors and Asian manufacturing cost bases, with FDA 510(k) clearance timelines creating regulatory rent extraction potential for domestic innovators versus import-dependent competitors.
For Market Incumbents: Deepen backward integration into silicone hydrogel polymer production to offset East Asian feedstock volatility exposure. Secure optometrist channel control through exclusive fitting software partnerships that complicate direct-to-consumer disintermediation. Prioritize multifocal R&D pipelines targeting presbyopic urban professionals least susceptible to daily disposable price competition.
For New Entrants and Emerging Players: Begin with water gradient technology white-space positioning that blurs silicone hydrogel versus conventional hydrogel category boundaries for premium comfort claims. Target EU MDR CE marking pathways where notified body concentration filters incumbent-dominated competition. Deploy telehealth-integrated prescription services to reduce customer acquisition friction in online platform channels.
For Investors and Strategic Acquirers: Consolidation pressure builds where clinical trial infrastructure scarcity meets silicone hydrogel IP concentration among polymer specialists. Long-term viability favors acquisition targets with established FDA 510(k) clearance track records and quality management systems transferable across jurisdictions. Monitor FDA draft guidance evolution on continuous wear labeling as inflection indicator for water gradient technology premiumization potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Hydrogel R&D Pipeline Expansion | Johnson & Johnson Vision Care leverages polymer innovation to sustain premium positioning in North American retail channels. |
| Direct-to-Consumer Subscription Launch | Online platform distribution captures recurring revenue from digitally native urban professionals seeking automated lens replenishment. |
| EU MDR CE Marking Pathway Investment | Harmonized European regulatory access streamlines multi-country distribution for silicone hydrogel formulations meeting biocompatibility standards. |
| Optometrist Partnership Network Expansion | Professional-intermediated fitting workflows defend against margin compression from telehealth-integrated prescription disintermediation. |
| Water Gradient Technology Licensing | Hybrid material architectures enable premium positioning through surface hydration layer differentiation from conventional silicone hydrogel cores. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each regional cluster combining structured interviews with polymer R&D directors, regulatory affairs specialists at notified bodies, optometrist practice owners, and hospital procurement managers with secondary validation. Secondary sources include FDA 510(k) clearance databases, EU MDR technical file submissions, PMDA pharmaceutical affairs standards documentation, and trade flow data from optical polymer customs classifications. Bottom-up lens shipment modeling triangulates against top-down vision correction demographic projections and regional regulatory pathway timelines.
Rate-of-change decomposition separates volume expansion from value-per-unit evolution across the projection horizon, with segmentation dimensions spanning material chemistry tiers, vision correction applications, distribution channel structures, and surface engineering specifications. CAGRs derive from fitted trend extrapolation against historical regulatory approval velocity and demographic shift patterns. Industry-specific forecast inputs incorporate silicone monomer price indices and optometrist channel penetration rates by metropolitan market density.
Several conditions sit outside the modeled scope, including unforeseen regulatory reclassification of water gradient technologies, abrupt silicone monomer supply disruptions from geopolitical events, and pandemic-scale demand shocks to professional fitting workflows. Forecasts reflect documented assumptions regarding FDA 510(k) pathway stability and EU MDR implementation consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
High Frequency Ventilators Market
Medical Devices
Europe Otoscope Market
Medical Devices
GCC and UAE Diabetes Devices Market
Medical Devices
Alpha Emitter Market
Medical Devices
Global Skin Grafting Device Market
Medical Devices
Asia-Pacific Nerve Repair and Regeneration Market
Medical Devices
Inhaled Nitric Oxide (NO) Delivery Systems Market
Medical Devices
United States Drug Delivery Devices Market
Medical Devices
Nerve Monitoring Devices Market
Medical Devices
Intravenous Access Devices Market
Medical Devices
Artificial Eye Market
Medical Devices
Cardiac Catheters and Guidewires Market
Medical Devices
Bunion Correction Systems Market
Medical Devices
Electronic Skin Patch Market
Medical Devices
Cranial Orthoses Market
Medical Devices
Cyberknife Technology Market