
 Medical Walker Market | 2026-2036
Medical Walker Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Walker Market Intelligence
Production expansion in Southeast Asian countries like Vietnam and Malaysia is fragmenting the traditional manufacturing base for medical walkers. Established players like Drive DeVilbiss Healthcare leverage extensive global distribution networks to maintain market share. Invacare Corporation specializes in a comprehensive portfolio of durable medical equipment for the home care setting. Medline Industries sustains its position through strong ties with large healthcare systems and institutional buyers.
A medical walker is a mobility aid frame designed to provide stability and support for individuals with balance or strength impairments. These devices are typically constructed from lightweight aluminum or steel tubing and feature adjustable height mechanisms to accommodate different users. Their primary function is to assist with ambulation, reduce the risk of falls, and enable greater independence. Four-wheel walkers, also known as rollators, represent the fastest-growing product type, often displacing standard walkers due to added features like seats and brakes. The elderly care and post-surgery rehabilitation applications continue to be the largest sources of demand.
The market operates under strict regulatory oversight to ensure user safety and product quality. The U.S. Food and Drug Administration (FDA) classifies most walkers as Class I medical devices, while the European Union's Medical Device Regulation (MDR) requires CE marking for market access. Compliance with ISO 13485 for quality management systems is a standard requirement for manufacturers. The critical decision for manufacturers now revolves around balancing cost-effective material sourcing with the integration of advanced features like smart sensors for fall detection.
Market Dynamics
The central force shaping the medical walker market is the demographic imperative in aging societies, particularly in developed nations, which necessitates greater availability of mobility support devices for home care and independent living settings.
Growth Catalysts
- Aging Global Population:Countries with rapidly aging demographics, such as Japan, create sustained demand for mobility aids, often supported by national healthcare policies aimed at promoting senior independence and reducing institutional care costs.
- Post-Surgical Rehabilitation:An increasing volume of orthopedic surgeries, including hip and knee replacements, drives requirements for walkers during the recovery phase, making the post-operative care segment a consistent source of demand.
- Lightweight Materials:The use of lightweight yet durable materials like aluminum tubing enhances user comfort and portability, broadening the appeal of modern walkers over heavier, traditional steel models and encouraging upgrades.
Market Restraints
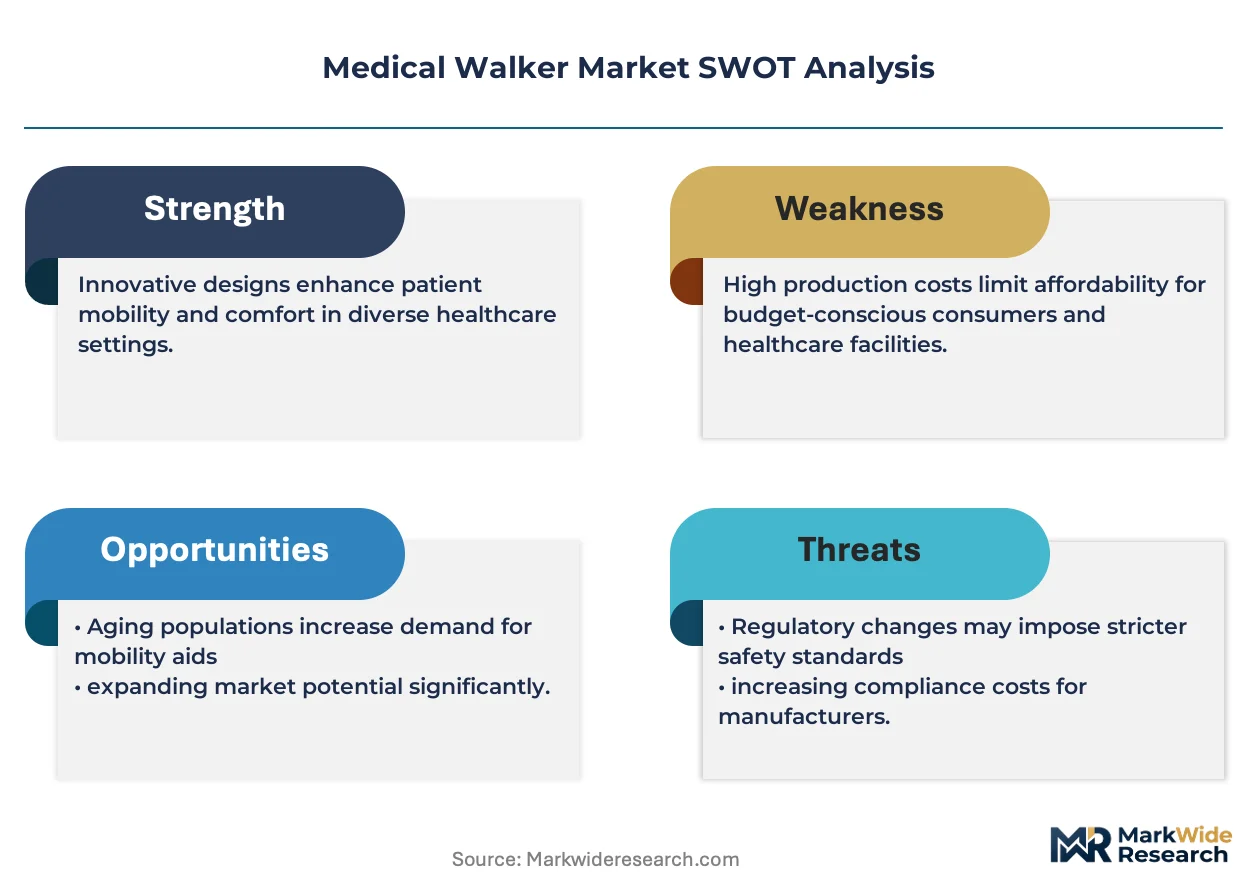
- Reimbursement Rate Pressure:In healthcare systems with public or private insurance reimbursement, downward pressure on payment rates for durable medical equipment can squeeze manufacturer margins and limit investment in premium features.
- Substitution by Rollators:Standard walkers face a significant substitution threat from four-wheel rollators, which offer superior mobility and integrated features like seats and brakes, capturing a growing share of the user base.
- Regulatory Compliance Costs:Adhering to stringent regulatory frameworks, such as the EU's Medical Device Regulation (MDR) for CE marking, imposes significant costs and administrative burdens on manufacturers, acting as a barrier to entry.
Strategic Opportunities
- Smart Walker Technology:Integrating smart sensors for fall detection, gait analysis, and GPS tracking presents a major opportunity to add value, creating a new premium product tier that connects to telehealth and remote monitoring ecosystems.
- Emerging Market Penetration:Expanding distribution into Southeast Asian markets like Vietnam and Malaysia, where aging populations are growing and healthcare spending is rising, offers new avenues for volume growth outside of saturated markets.
- Direct-to-Consumer Channels:Developing e-commerce platforms and direct-to-consumer sales models allows manufacturers to bypass traditional durable medical equipment suppliers, capture higher margins, and build direct relationships with end-users.
Industry Challenges
- Supply Chain Management:Managing quality control and ensuring consistent component supply across a geographically fragmented manufacturing base, including new facilities in Southeast Asia, presents a significant operational challenge.
- Feature-Cost Balancing Act:Manufacturers face the challenge of balancing consumer demand for advanced features and improved aesthetics against the need to maintain affordable price points, especially for out-of-pocket buyers.
- Certification Timelines:Achieving and maintaining necessary quality management certifications, such as ISO 13485, is a time-consuming and resource-intensive process that can delay the market entry of new products or new manufacturing sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Walker Market |
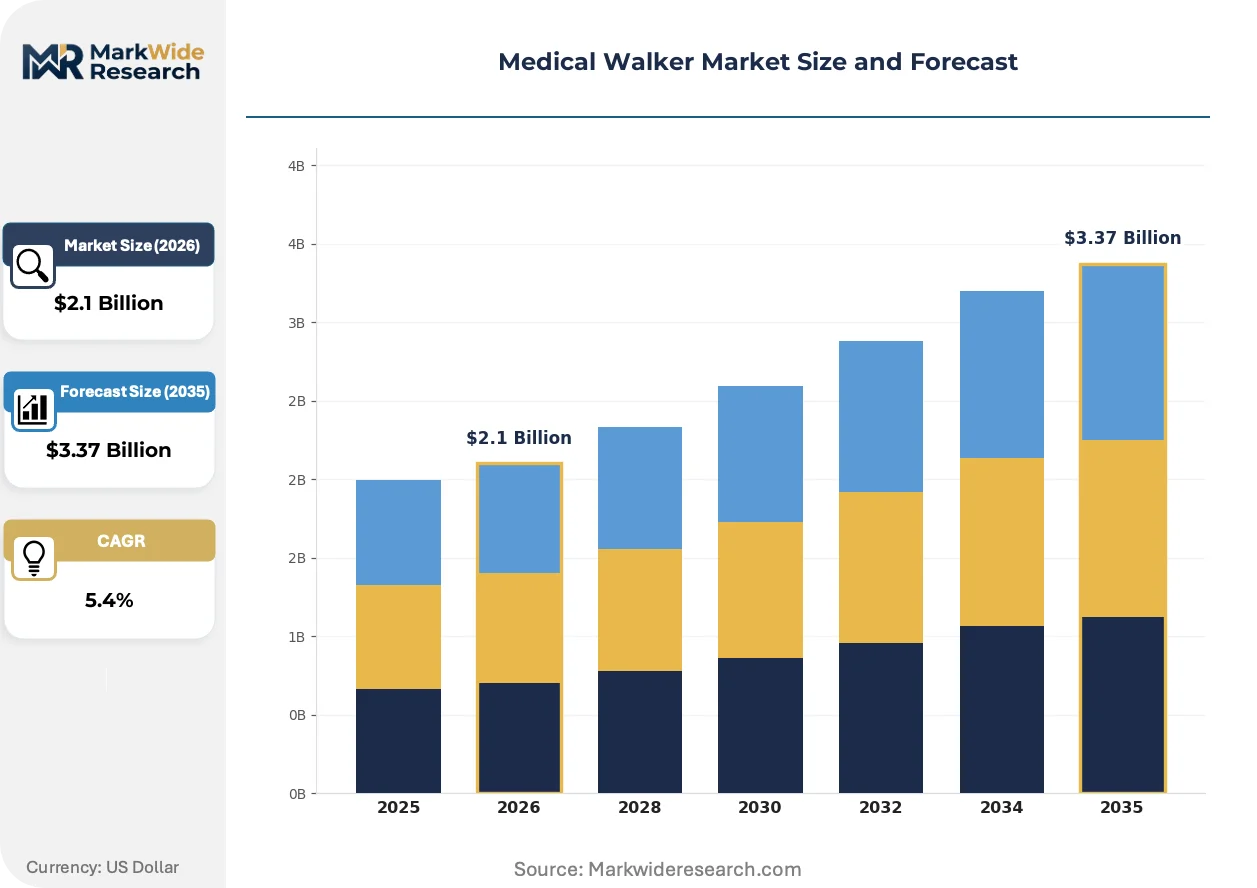
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Walkers, Two-Wheel Walkers, Four-Wheel Walkers, Folding Walkers, Knee Walkers Application: Post-Surgery Rehabilitation, Mobility Assistance, Fall Prevention, Elderly Care, Injury Recovery End User: Geriatric Patients, Physical Therapy Centers, Rehabilitation Clinics, Home Care Providers, Orthopedic Patients Material: Aluminum, Steel, Carbon Fiber, Plastic Composites, Stainless Steel |
| Companies Covered | Invacare Corporation, Drive DeVilbiss Healthcare, Medline Industries, GF Health Products, Karman Healthcare, Carex Health Brands, Nova Medical Products, Sunrise Medical, Human Care HC AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Walker Market Strategic Shifts & Innovations
Blurring the lines between medical devices and consumer electronics, product evolution now centers on embedding digital connectivity and data-gathering capabilities into traditional walker frames to enhance user safety and provide caregiver insights.
Smart sensors embedded in walker frames provide real-time fall detection and GPS location tracking. The home care provider segment and individual consumers are adopting these features to improve safety for elderly users. This integration of digital services is collapsing the traditional boundary between a simple mobility aid and a comprehensive personal emergency response system.
The European Union's Medical Device Regulation (MDR) elevates the compliance burden for manufacturers. It mandates more rigorous clinical evidence, post-market surveillance, and traceability throughout the supply chain compared to its predecessor. Four-wheel rollators with electronic features are most impacted, requiring extensive technical documentation and risk management files to secure or maintain CE marking.
Consumer purchasing behavior is moving towards direct-to-consumer models via online platforms, bypassing traditional procurement. This disintermediates durable medical equipment suppliers, giving consumers control over product selection based on aesthetics and features. The shift is most apparent in North America and Western Europe, where e-commerce infrastructure supports direct sales.
Medical Walker Market Segmentation
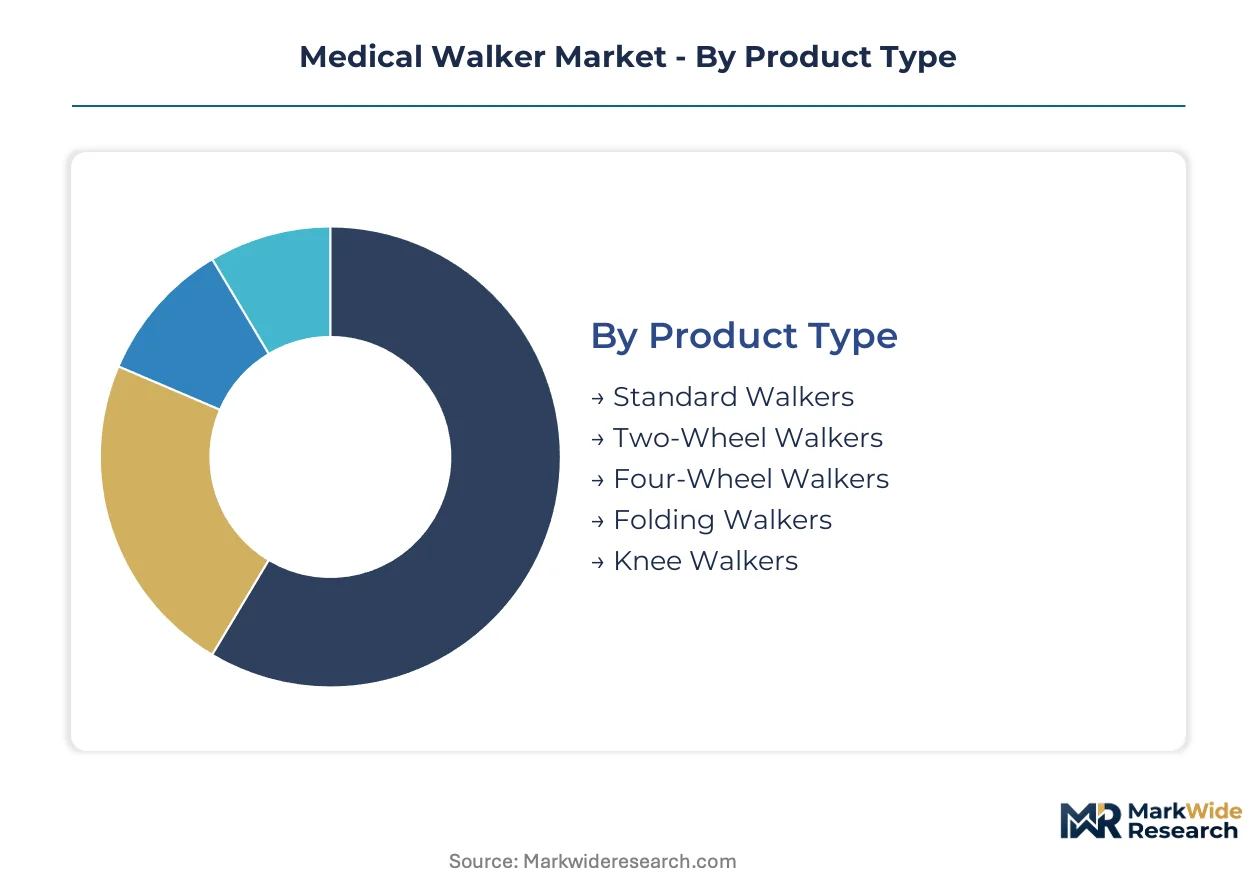
The medical walker market's segmentation provides a granular understanding of product evolution, user requirements, and material science advancements. Analyzing these distinct categories illuminates specific demand drivers and strategic opportunities for manufacturers within this expanding mobility aid sector.
Product Type:
Product type distinctions delineate the functional capabilities and design innovations within the medical walker market.
- Four-Wheel Walkers:Known as rollators, these devices feature four wheels, hand brakes, and often a built-in seat, providing enhanced mobility and resting options. Demand concentrates in developed nations like Japan, driven by an aging population seeking greater independence and comfort.
- Standard Walkers:These traditional mobility aids typically have two fixed front wheels and glides or rubber tips on the rear legs, requiring users to lift the device for forward movement. Post-surgical rehabilitation applications consistently drive demand for these stable, foundational support systems.
- Two-Wheel Walkers:Equipped with wheels on the front legs and glides on the rear, these walkers offer a balance between stability and ease of movement.
- Folding Walkers:Designed for portability and convenient storage, these models collapse into a compact form, appealing to users with active lifestyles or limited space.
- Knee Walkers:These specialized devices support one leg on a padded platform, allowing users with lower leg injuries to maintain mobility without bearing weight.
Standard Walkers hold significant installed capacity. Four-Wheel Walkers are rotating up the share rankings.
Application:
The application landscape for medical walkers reflects diverse patient needs and clinical requirements.
- Elderly Care:This application focuses on providing continuous support for older adults experiencing age-related mobility decline, enabling independent living within home settings. Countries with high proportions of seniors, such as Japan and Germany, show sustained demand for these devices.
- Post-Surgery Rehabilitation:Walkers are essential tools for patients recovering from orthopedic procedures like hip and knee replacements, facilitating early ambulation and muscle strengthening. Clinical guidelines in the US and Europe often mandate their use during the initial recovery phases.
- Mobility Assistance:This broad application addresses general difficulties in walking due to various chronic conditions or temporary impairments, enhancing user independence.
- Fall Prevention:Medical walkers significantly reduce the risk of accidental falls by providing a stable base of support, particularly for individuals with balance disorders.
- Injury Recovery:These devices aid individuals recuperating from injuries that temporarily compromise lower limb strength or stability, supporting gradual weight-bearing.
Elderly Care applications maintain the largest demand volume. Post-Surgery Rehabilitation applications represent a consistently expanding segment.
End User:
Understanding end-user segments is crucial for tailoring product features and distribution strategies.
- Home Care Providers:These entities supply mobility aids directly to individuals receiving care in their residences, facilitating independent living and reducing institutionalization. The segment's expansion in countries like the US and UK reflects a shift towards community-based healthcare.
- Geriatric Patients:This primary user group comprises elderly individuals who require assistance with ambulation due to age-related frailty, neurological conditions, or reduced muscle strength. Their needs drive innovation in lightweight and user-friendly designs for daily use.
- Physical Therapy Centers:These facilities utilize walkers as essential tools for gait training and balance exercises during patient rehabilitation programs.
- Rehabilitation Clinics:Specialized clinics employ a range of walkers to support patients recovering from severe injuries, strokes, or chronic conditions, focusing on functional recovery.
- Orthopedic Patients:Individuals undergoing orthopedic surgeries, such as joint replacements, rely on walkers for initial post-operative mobility and support.
Geriatric Patients form the largest end-user demographic. Home Care Providers are gaining market influence through direct supply channels.
Material:
Material choices significantly impact a walker's weight, durability, and cost profile.
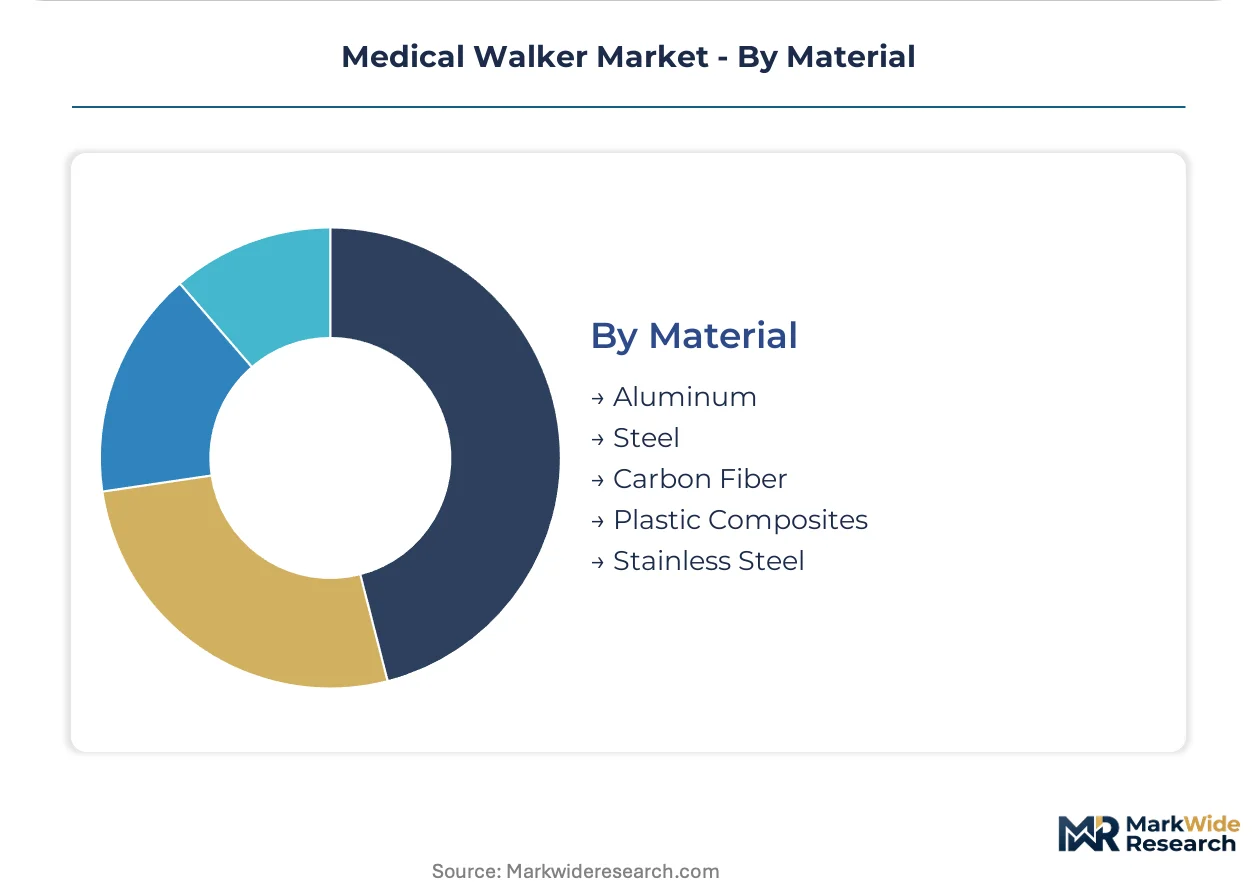
- Aluminum:This lightweight metal is widely favored for walker construction due to its high strength-to-weight ratio, making devices easier for users to maneuver and transport. Its adoption is widespread across global markets where portability is a key consumer preference.
- Steel:Traditional walkers often utilize steel for its superior strength and lower cost, providing robust support for heavier individuals or those requiring maximum stability. Manufacturing in Southeast Asian countries like Vietnam benefits from its cost-effectiveness.
- Carbon Fiber:Offering exceptional strength and minimal weight, carbon fiber is a premium material used in high-end walkers, providing advanced durability and portability.
- Plastic Composites:These materials are increasingly integrated into walker components for ergonomic design, reduced weight, and aesthetic appeal, complementing metal frames.
- Stainless Steel:Known for its corrosion resistance and strength, stainless steel is used in specific walker designs requiring enhanced hygiene and durability, often for institutional settings.
Aluminum remains the predominant material choice. Steel maintains a strong position in cost-sensitive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global medical walker market is significantly influenced by established healthcare infrastructure and public health policies that prioritize senior care. Robust distribution networks, often centered around major port cities, facilitate the movement of mobility aids. This ensures widespread availability of essential devices for aging populations worldwide.
Japan
Demand for medical walkers in Japan is sustained by its rapidly aging population and a strong cultural emphasis on elder independence. The Ministry of Health, Labour and Welfare (MHLW) actively promotes home care support programs to reduce institutionalization. Tokyo's dense urban areas and surrounding prefectures demonstrate high adoption rates for advanced mobility solutions.
United States
The United States experiences consistent demand for walkers driven by post-surgical rehabilitation needs and an expanding home care provider segment. The U.S. Food and Drug Administration (FDA) classifies most walkers as Class I medical devices, ensuring product safety. Major medical device manufacturing hubs in states like California and Florida are innovating new walker designs.
Germany
Germany's aging demographic and comprehensive social security system generate stable demand for medical walkers, especially in elderly care applications. The European Union's Medical Device Regulation (MDR) requires CE marking for market access, impacting all devices sold. Cities such as Munich and Hamburg serve as key distribution points for medical equipment across Europe.
Vietnam
Production expansion in Vietnam is fragmenting the traditional manufacturing base for medical walkers, attracting foreign investment. The Vietnamese Ministry of Health provides guidelines for medical device manufacturing and quality control. Industrial zones near Ho Chi Minh City are becoming significant centers for cost-effective walker production.
United Kingdom
Demand in the United Kingdom is shaped by its growing elderly population and a strong focus on community-based care, supported by the NHS. The Medicines and Healthcare products Regulatory Agency (MHRA) oversees medical device compliance within the UK market. London and Birmingham serve as key logistical hubs for distributing medical aids to home care providers.
Medical Walker Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical elements for medical walkers. The market exhibits a tiered structure, with established global brands alongside regional manufacturers and emerging producers. Strategic archetypes include diversified medical equipment giants, specialized mobility aid providers, and cost-focused original equipment manufacturers. Key competitive moves involve geographic expansion into developing economies and continuous product portfolio diversification to capture new user segments.
Within the specialized mobility aid provider archetype, Invacare Corporation exemplifies a comprehensive portfolio approach, serving diverse home care needs across numerous product categories. This global entity focuses on durable medical equipment for independent living. Drive DeVilbiss Healthcare, another prominent player, occupies a position leveraging extensive distribution networks to maintain market presence and reach a broad consumer base. Medline Industries, Inc., a large healthcare supplier, anchors its market share through strong ties with institutional buyers and large healthcare systems, consistently reinforcing its position in the segment by offering a wide array of medical supplies.
| Leading Market Players |
|---|
| Invacare Corporation |
| Drive DeVilbiss Healthcare |
| Medline Industries |
| GF Health Products |
| Karman Healthcare |
| Carex Health Brands |
| Nova Medical Products |
| Sunrise Medical |
| Human Care HC AB |
| Others |
Cost & Logistics Intelligence
Overcapacity in Southeast Asian manufacturing facilities drives competitive supplier behavior, directly influencing global pricing posture for medical walkers.
Pricing Analysis
The European Union's Medical Device Regulation (MDR) dictates the pricing tier structure for medical walkers, especially for advanced rollators requiring CE marking. Pricing primarily operates on a per-unit transactional model, with differentiation stemming from certification level and brand premium. Reimbursement rate pressure in public healthcare systems exerts downward pressure on margins. Home care providers often exhibit high price sensitivity, while physical therapy centers prioritize durability and after-sales service.
Supply Chain Analysis
Contract manufacturing capacity in Vietnam and Malaysia holds significant production volume for medical walkers, complementing established facilities in China. The supply chain draws heavily from lightweight aluminum tubing, plastic composites for ergonomic designs, and specialized smart sensors. A key structural risk involves managing quality control across this geographically fragmented manufacturing base. Distribution runs through extensive global networks, connecting manufacturers to institutional buyers and home care providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical walker market is undergoing a platform-economics inflection, driven by the integration of smart sensors into telehealth and remote monitoring ecosystems. This shift transforms devices from simple aids into connected health solutions.
For Market Incumbents: Harden existing distribution networks and institutional relationships to counter substitution by advanced rollators. Invest in R&D for smart features like fall detection, leveraging ISO 13485 certification to maintain quality. Deepen integration with large healthcare systems to secure long-term procurement contracts. This approach mitigates margin pressure from reimbursement rate changes.
For New Entrants and Emerging Players: Build out direct-to-consumer e-commerce platforms to bypass traditional distribution channels. Target underpenetrated emerging markets in Southeast Asia, focusing on the premium smart walker segment. Offer products with integrated fall detection and gait analysis, appealing to tech-savvy consumers seeking enhanced safety. This strategy allows for higher margins and direct user feedback.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across the smart walker sub-segment, driven by R&D in advanced sensors. Long-term viability remains strong due to global aging demographics and sustained demand for independence. Identify acquisition targets specializing in embedded digital connectivity or telehealth integration. Watch for increasing adoption rates of smart walker features within the home care provider segment as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: Smart Walker Series | Introduces premium products with integrated digital features for user safety. |
| CE Marking Pathway | Ensures market access and regulatory compliance for advanced devices in European markets. |
| Hospital System Partnership | Secures procurement contracts and expands reach within post-surgical rehabilitation. |
| Direct-to-Consumer Channel Expansion | Captures higher margins and builds direct relationships with end-users. |
| Supply Chain Diversification | Mitigates risks associated with manufacturing concentration in Asian countries. |
Research Approach
Desk research of regulatory filings, trade association reports, and national health statistics preceded structured interviews with clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers. This approach combined primary insights with secondary validation to ensure data accuracy. Bottom-up data collection from manufacturers was triangulated with top-down market sizing estimates. The analysis covered both established and emerging market dynamics.
Assumptions regarding stable regulatory frameworks and consistent healthcare expenditure were held fixed, while demographic shifts and technological integration were varied across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end-user, material, and regional adoption patterns. Compound annual growth rates were derived from historical data analysis and projected growth drivers. Key inputs included aging population demographics and orthopedic surgery volumes.
Stress conditions across reimbursement policies and raw material costs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions, but rapid material innovation or significant regulatory shifts could revise projections. Quarterly review of national health statistics and technology adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Furniture
Global Automated Hospital Beds Market
Medical Furniture
Europe Hospital Furniture Market
Medical Furniture
North America Hospital Furniture Market
Medical Furniture
Asia-Pacific Hospital Furniture Market
Medical Furniture
Hospital Beds Market
Medical Furniture
Global Stretcher Chairs Market
Medical Furniture
Clinical Chairs Market
Medical Furniture
Medical Commodes Market
Medical Furniture
Global Smart Hospital Bed Market
Medical Furniture
Healthcare Smart Beds Market
Medical Furniture
Electrical Hospital Beds Market
Medical Furniture
Healthcare Flooring Market
Medical Furniture
Global Medical Furniture Market
Medical Furniture
Infusion Chair Market
Medical Furniture
Hospital Bed Management Systems Market
Medical Furniture
Intensive Care Beds Market