
 Hospital Bed Management Systems Market | 2026-2036
Hospital Bed Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Hospital Bed Management Systems Market Analytics
The FDA's 21st Century Cures Act enforcement is recalibrating the cost-of-entry calculus for digital health vendors serving hospital capacity management. Epic Systems Corporation leverages its dominance in electronic health record integration to embed bed management within broader clinical workflows. Cerner anchors its position through deep interoperability with existing health system infrastructure. Philips competes by extending its acute care monitoring portfolio into real-time capacity analytics.
Hospital bed management systems coordinate the allocation, tracking, and turnover of inpatient beds through software platforms that integrate electronic health records, admission-discharge-transfer protocols, and real-time location services. These systems typically process bed status updates at intervals under sixty seconds to support operational decision-making in high-throughput clinical environments. Software solutions command the most attractive margin pools due to recurring subscription revenue and lower incremental delivery costs, while automated systems represent the fastest-growing product category as health systems replace manual whiteboard processes. Cloud-based deployment leads technology adoption, though on-premise installations persist in facilities with stringent data residency requirements.
The US FDA regulates software-as-medical-device functionality under its digital health pre-certification pathway, while HIPAA mandates govern patient data flows across bed management networks. The EU MDR and GDPR jointly shape product standards for European deployments, requiring clinical evidence and data protection by design. Stakeholders must monitor evolving interoperability mandates from ONC and determine capital allocation between cloud migration and legacy system augmentation.
Market Dynamics
Health system consolidation across the United States is compressing procurement timelines and forcing enterprise-wide standardization of bed management platforms, eliminating point solutions from departmental budgets.
Growth Catalysts
- 21st Century Cures Act enforcement:The FDA's digital health pre-certification pathway creates regulatory clarity that accelerates hospital IT investment cycles.
- Real-time location services:RFID and Bluetooth Low Energy integration enables sub-sixty-second bed status updates that acute care hospitals now require.
- Cloud migration mandates:Health system CFOs prioritize subscription-based SaaS models that convert capital expenditure to operational budgets.
Market Restraints
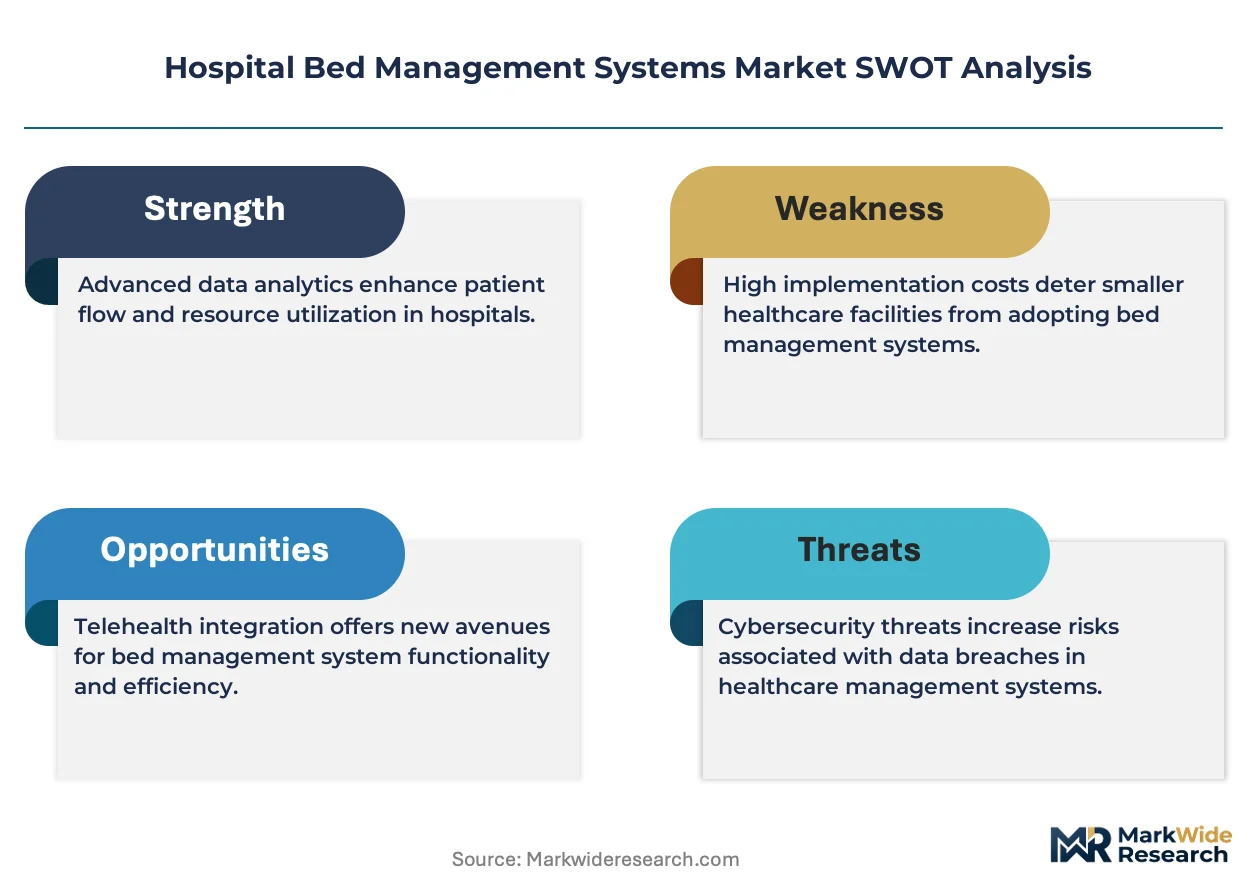
- EHR vendor lock-in:Epic Systems and Cerner control dominant market positions that fragment interoperability and raise switching costs.
- HIPAA compliance complexity:Patient data residency requirements perpetuate on-premise installations that constrain cloud adoption velocity.
- Legacy infrastructure debt:Manual whiteboard processes and aging admission-discharge-transfer protocols resist automation in underfunded community hospitals.
Strategic Opportunities
- Skilled nursing facility integration:Post-acute care networks seek unified capacity platforms that coordinate patient flow across care continuums.
- EU MDR harmonization:The Medical Device Regulation creates a single compliance pathway for vendors targeting European hospital groups.
- AI-driven predictive analytics:Machine learning models that forecast discharge timing and bed demand are attracting venture investment.
Industry Challenges
- Interoperability engineering talent:Health systems struggle to hire HL7 FHIR specialists capable of integrating bed management with existing clinical workflows.
- ONC certification timelines:The Office of the National Coordinator's evolving interoperability mandates delay product roadmaps and inflate compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospital Bed Management Systems Market |
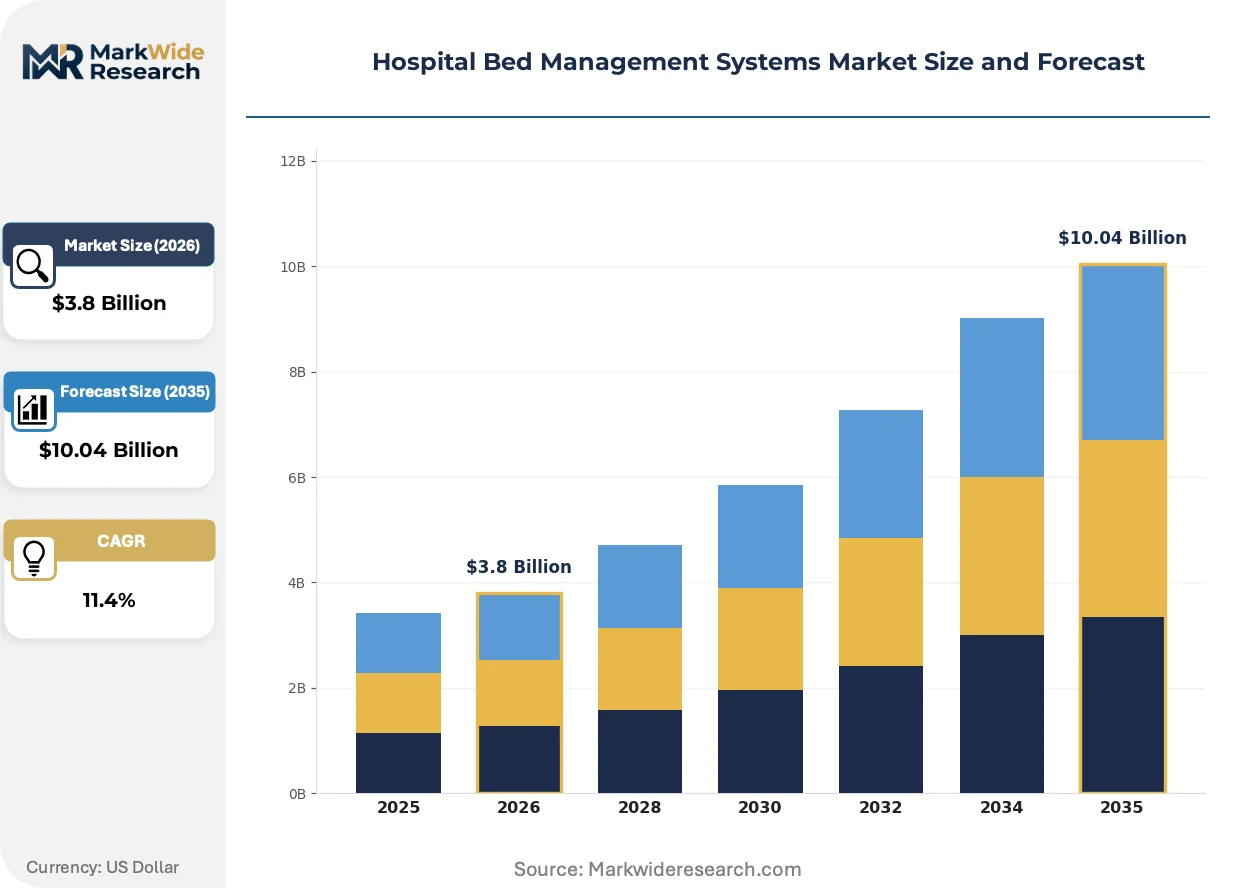
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Systems, Automated Systems, Hybrid Systems, Software Solutions Application: Acute Care, Extended Care, Emergency Services, Ambulatory Care End User: Hospitals, Outpatient Clinics, Long-Term Care Facilities, Rehabilitation Centers Technology: Cloud-Based, On-Premise, Mobile Solutions, Analytics Tools |
| Companies Covered | TeleTracking Technologies, Oracle, Epic Systems Corporation, GE Healthcare, Veradigm, Philips, Siemens Healthineers, Cerner, CentralSquare Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospital Bed Management Systems Market Evolving Landscape
Hospital bed management is transitioning from operational utility to strategic clinical infrastructure, with real-time data streams now feeding enterprise-wide decision support systems.
Cloud-native architecture is overtaking legacy client-server deployments as health systems prioritize elastic scalability and remote accessibility. Acute care hospitals in the United States are migrating core bed management workloads to AWS and Azure environments within eighteen-month implementation windows. This shift compresses total cost of ownership and forces on-premise vendors toward hybrid delivery models.
The EU MDR's software-as-medical-device classification is recalibrating vendor compliance strategies across European deployments. Clinical evidence requirements now govern algorithmic bed allocation tools that previously escaped scrutiny. German hospital groups are consolidating procurement around MDR-certified platforms that preempt national regulator divergence.
Subscription pricing models are displacing perpetual license structures as health system finance committees demand predictable operational expenditure profiles. Value analysis committees now evaluate bed management vendors on annual recurring revenue metrics rather than upfront capital recovery. This pattern concentrates most visibly in United States integrated delivery networks with centralized procurement authority.
Hospital Bed Management Systems Market Segmentation
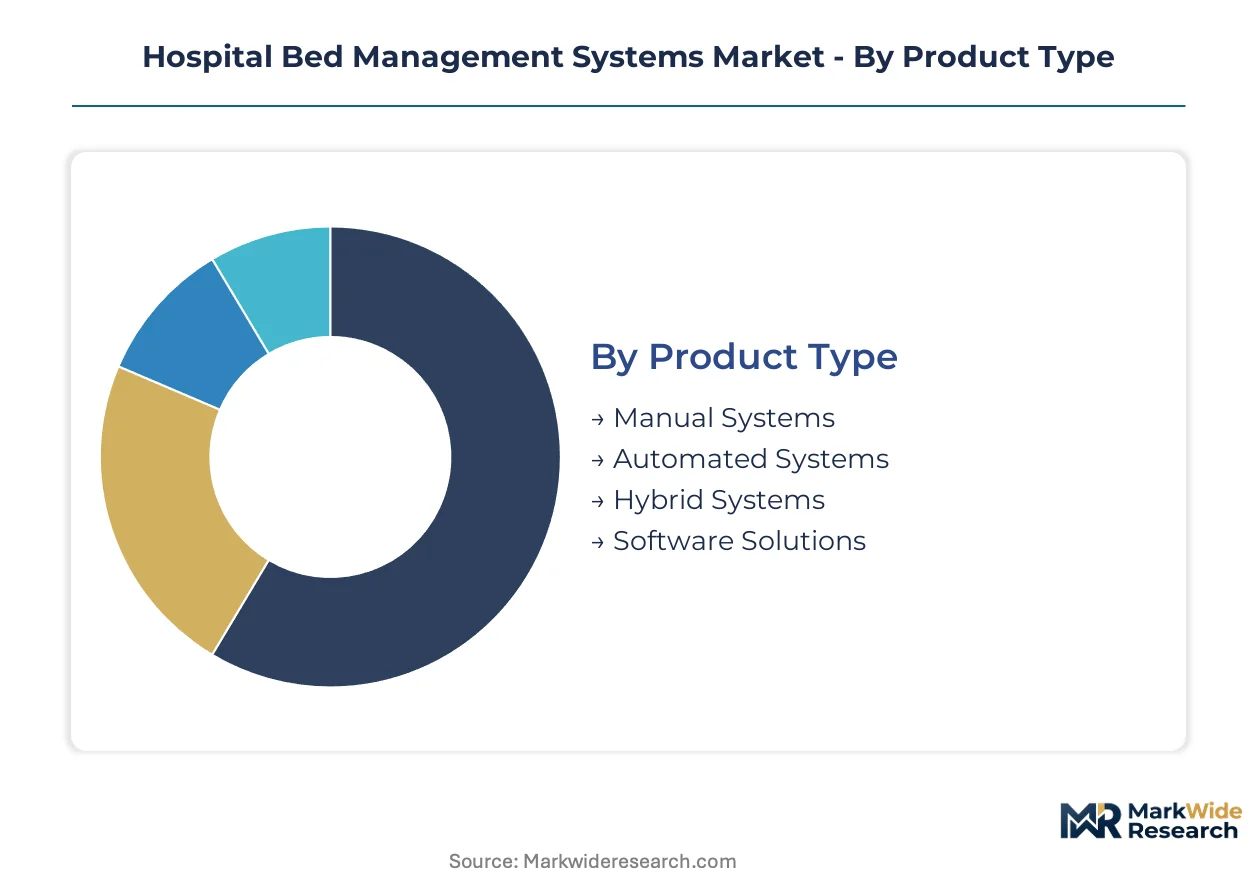
Hospital bed management systems fragment across four distinct axes that determine procurement priorities and vendor competitive positioning. Product architecture dictates margin structures and implementation complexity. Application context shapes real-time performance requirements and integration depth.
Product Type:
Technology sophistication defines the product hierarchy, with automation intensity separating capital-intensive hardware from recurring-revenue software platforms.
- Manual Systems:Whiteboard-based tracking and paper admission-discharge-transfer protocols persist in underfunded community hospitals. Budget constraints in rural United States facilities perpetuate these legacy workflows despite known inefficiencies.
- Automated Systems:RFID-enabled bed boards and electronic status displays eliminate transcription errors in high-throughput acute care environments. United States health system consolidation is forcing enterprise-wide deployment of these platforms to standardize capacity visibility.
- Hybrid Systems:Bridge configurations combining partial automation with retained manual checkpoints serve mid-tier hospitals navigating phased digital transformation.
- Software Solutions:Pure-play platforms delivering bed management through EHR-integrated modules command the most attractive margin pools via subscription pricing.
Software solutions lead on scale; automated systems lead on momentum.
Application:
Clinical velocity determines system specifications, with patient turnover frequency dictating update latency tolerances and alert sophistication.
- Acute Care:Sub-sixty-second bed status refresh rates support surgical scheduling and emergency admission routing in tertiary hospitals. FDA digital health oversight tightens validation requirements for these high-stakes deployments.
- Emergency Services:Real-time capacity dashboards integrate with ambulance dispatch systems to optimize patient routing during surge events. United States trauma centers prioritize these integrations for level-one certification maintenance.
- Extended Care:Lower-frequency updates accommodate longer length-of-stay patients in skilled nursing and post-acute settings.
- Ambulatory Care:Same-day procedure centers require lightweight bed tracking for pre- and post-operative holding areas.
Acute care dominates procurement volume; emergency services climbs fastest on regulatory pressure.
End User:
Organizational scale and reimbursement structure shape technology investment capacity and platform complexity requirements.
- Hospitals:Enterprise-wide capacity management platforms integrate admission-discharge-transfer protocols with real-time location services across multi-campus systems. United States integrated delivery networks consolidate procurement around vendors with proven Epic and Cerner interoperability.
- Long-Term Care Facilities:Post-acute networks seek unified platforms coordinating patient flow across hospital-to-skilled-nursing continuums. Medicare reimbursement changes are accelerating these integration investments.
- Outpatient Clinics:Limited scope implementations focus on procedure room turnover rather than overnight bed allocation.
- Rehabilitation Centers:Specialized workflows for therapy scheduling and discharge planning require customized configuration.
Hospitals anchor absolute demand; long-term care facilities expand most quickly on care continuum integration mandates.
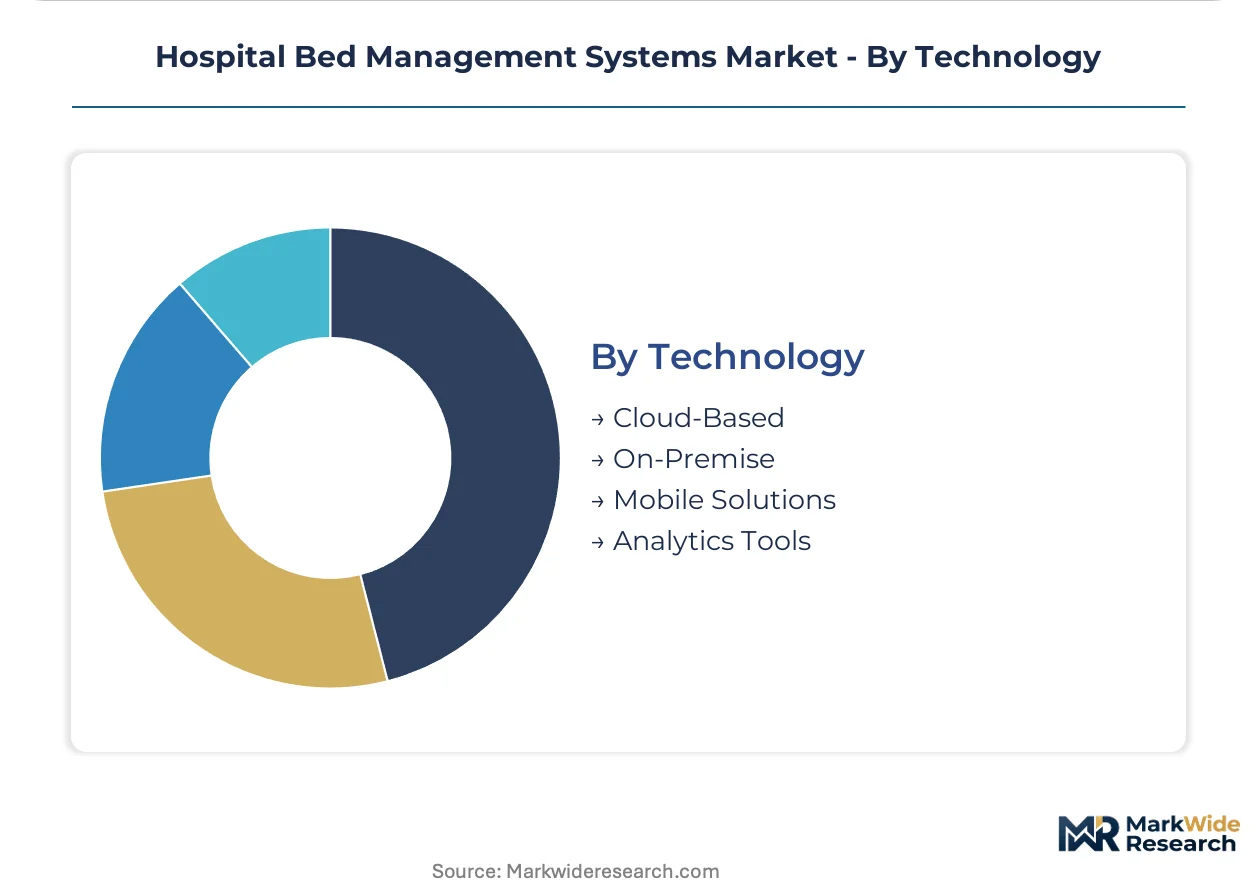
Technology:
Deployment architecture determines total cost of ownership trajectories and data residency compliance pathways.
- Cloud-Based:AWS and Azure-hosted platforms deliver elastic scalability and remote accessibility for distributed health systems. HIPAA business associate agreements and encryption standards govern these deployments.
- Mobile Solutions:Smartphone and tablet interfaces extend bed status visibility to charge nurses and house supervisors beyond fixed workstation locations.
- On-Premise:Client-server installations persist where state-level data residency statutes or institutional risk tolerance block external hosting.
- Analytics Tools:Machine learning modules forecasting discharge timing and demand patterns attract venture investment but face FDA scrutiny under software-as-medical-device pathways.
Cloud-based deployments capture the largest installed base; analytics tools gain share fastest on predictive operational planning demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health informatics specialists cluster in metropolitan medical technology corridors where academic medical centers and enterprise software vendors co-locate. These talent pools anchor regional deployment capacity for real-time capacity management platforms.
United States
Integrated delivery networks in the Northeast Corridor and California consolidate procurement around cloud-native bed management platforms. FDA digital health pre-certification pathways accelerate validation timelines for vendors targeting acute care hospitals. The Greater Boston cluster houses multiple health IT vendors developing real-time location service integrations for tertiary medical centers.
Germany
University hospital groups in Bavaria and North Rhine-Westphalia drive demand for MDR-certified capacity management software. EU MDR software-as-medical-device classification tightens clinical evidence requirements for algorithmic bed allocation tools. The Berlin-Brandenburg health technology corridor attracts vendors seeking harmonized European compliance pathways.
United Kingdom
NHS Trust consolidation in London and the Midlands creates enterprise-scale procurement opportunities for integrated patient flow platforms. NHS England's digital transformation mandates prioritize interoperability with existing electronic health record infrastructure. The Cambridge-Oxford-London triangle concentrates health informatics research translating into commercial bed management applications.
Japan
Super-aging prefectures in Kanto and Kansai regions invest in automated bed turnover systems to manage chronic care capacity constraints. PMDA software guidance shapes validation requirements for predictive analytics modules forecasting discharge timing. The Tokyo metropolitan medical cluster leads adoption of RFID-enabled real-time location services in university hospitals.
Australia
State health departments in New South Wales and Victoria fund centralized capacity management platforms across public hospital networks. TGA software regulation governs clinical decision support functionality in bed allocation algorithms. The Melbourne biomedical precinct hosts vendors developing cloud-based interoperability solutions for multi-site health services.
Hospital Bed Management Systems Market Competitive Landscape
The competitive structure tilts toward electronic health record incumbents with embedded workflow integration. Three to five integrated platforms capture the majority of acute care hospital procurement in consolidated health systems. Strategic archetypes include EHR-native suite providers, standalone capacity management specialists, and industrial conglomerates with acute care monitoring portfolios. Dominant competitive moves encompass API-based interoperability partnerships and cloud infrastructure migration programs that convert perpetual licenses to recurring revenue streams.
Within the EHR-native tier, Epic Systems Corporation and Cerner occupy positions exemplifying deep clinical workflow integration. Epic leverages its dominance in United States academic medical centers to embed bed management within comprehensive electronic health record deployments. Cerner anchors enterprise-wide capacity visibility through interoperability protocols connecting disparate health system infrastructure. Among standalone specialists, TeleTracking Technologies represents the focused application archetype, building market presence through dedicated patient flow optimization without broader clinical system dependencies.
| Leading Market Players |
|---|
| TeleTracking Technologies |
| Oracle |
| Epic Systems Corporation |
| GE Healthcare |
| Veradigm |
| Philips |
| Siemens Healthineers |
| Cerner |
| CentralSquare Technologies |
| Others |
Value Network & Pricing Analysis
Software development labor costs in India and Eastern Europe cascade through SaaS pricing tiers, with United States health system procurement committees capturing margin compression through multi-year subscription negotiations while rural community hospitals absorb residual on-premise hardware premiums.
Pricing Analysis
Bundled EHR-integrated bed management modules command premium positioning against standalone capacity platforms that unbundle workflow functionality. Three-tier pricing structure across premium, standard, and economy levels segments by interoperability depth and real-time update latency. Cost compression in the standard tier is intensifying because Epic Systems and Cerner leverage captive EHR installed bases to absorb pricing pressure. Rural community hospitals exhibit highest price sensitivity, while integrated delivery networks with centralized procurement authority demonstrate lowest sensitivity due to total cost of ownership framing.
Supply Chain Analysis
Domestic-content mandates in Germany's EU MDR implementation and India's Make in India procurement preferences are reshaping sourcing patterns for hardware components and cloud infrastructure localization. Supply concentrates in the United States for software development, Taiwan for RFID sensor manufacturing, and Ireland for European data residency-compliant hosting. Raw material dependencies span semiconductor chips for location sensors, medical-grade displays for bed boards, and lithium batteries for mobile tracking devices. Single-source vulnerability concentrates in AWS and Azure hyperscaler dominance for cloud deployments. Distribution runs through direct enterprise sales teams targeting health system CIOs and value analysis committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription revenue conversion and cloud infrastructure cost curves are expanding margin pools for vendors with established EHR interoperability, while on-premise legacy providers face structural compression.
For Market Incumbents: Deploy API-first interoperability architectures to neutralize emerging standalone analytics vendors threatening EHR-embedded bed management modules. Deepen certification investments in FDA digital health pre-certification pathways to raise rival compliance costs. Consolidate channel control through exclusive partnerships with major group purchasing organizations to lock out point-solution competitors. For New Entrants and Emerging Players: Launch via targeted post-acute care network deployments where EHR vendor lock-in remains weakest and Medicare reimbursement changes create procurement urgency. Skilled nursing facility integration represents the most penetrable white-space segment, with unified capacity platforms coordinating hospital-to-skilled-nursing continuums commanding premium positioning. Pursue white-label partnerships with regional health information exchanges as the primary go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where standalone capacity management specialists lack Epic or Cerner interoperability depth and face margin compression from EHR-native suite expansion. Long-term viability favors vendors with cloud-native architecture and recurring revenue concentration above seventy percent. Acquisition target archetype: mid-tier automated systems providers with installed base in community hospitals ripe for SaaS conversion. Watch FDA enforcement patterns on software-as-medical-device classification as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Epic Systems leverages EHR dominance to embed bed management within comprehensive clinical workflows. |
| Regulatory Certification Pathway | EU MDR software-as-medical-device classification tightens clinical evidence requirements for algorithmic tools. |
| Strategic Partnership | TeleTracking Technologies builds hospital system partnerships through dedicated patient flow optimization. |
| Geographic Expansion | German hospital groups consolidate procurement around MDR-certified platforms for harmonized compliance. |
| Acquisition of Specialist Firm | Industrial conglomerates extend acute care monitoring portfolios into real-time capacity analytics. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital CIOs, health system value analysis committee chairs, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, CMS Medicare cost reports, hospital procurement databases, and hyperscaler healthcare vertical disclosures. Bottom-up installed base modeling triangulated against top-down health system IT spending benchmarks.
Comparable-period anchoring linked historical EHR adoption curves and cloud migration trajectories to projection assumptions across the analysis window. Segmentation dimensions modeled include product architecture intensity, clinical velocity tier, organizational scale, and deployment topology. CAGRs derived from logistic diffusion curves fitted to health system consolidation patterns and regulatory enforcement timelines. Forecast inputs incorporated real-time location service penetration rates and subscription pricing conversion velocity.
Several conditions sit outside the modeled scope, including pandemic-era emergency capacity waivers and speculative AI diagnostic modules not yet subject to FDA software-as-medical-device pathways. Forecasts reflect documented assumptions about health system consolidation velocity and interoperability mandate enforcement intensity. Cybersecurity incidents affecting cloud-hosted patient data and unexpected ONC certification timeline extensions represent specific risk factors that could revise projections. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Furniture
Europe Hospital Furniture Market
Medical Furniture
Healthcare Smart Beds Market
Medical Furniture
Intensive Care Beds Market
Medical Furniture
Medical Bed Market
Medical Furniture
Global Chemotherapy Chairs Market
Medical Furniture
Global Smart Hospital Bed Market
Medical Furniture
North America Hospital Furniture Market
Medical Furniture
Medical Commodes Market
Medical Furniture
Global Medical Furniture Market
Medical Furniture
Infusion Chair Market
Medical Furniture
Clinical Chairs Market
Medical Furniture
Hospital Furniture Market
Medical Furniture
Asia-Pacific Hospital Bed Market
Medical Furniture
Global Stretcher Chairs Market
Medical Furniture
Global Automated Hospital Beds Market
Medical Furniture
Medical Mattress Market