
 North America Hospital Furniture Market | 2026-2036
North America Hospital Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hospital Furniture Market Analytics
Aftermarket service revenue is tilting toward predictive maintenance contracts and fleet refurbishment programs as acute care systems extend capital cycles. Stryker leverages its installed base of powered beds to capture recurring service income across integrated delivery networks. Hill-Rom Services anchors its competitive position through comprehensive asset management programs that reduce total cost of ownership for hospital clients.
North America hospital furniture encompasses beds, chairs, carts, and tables engineered to support patient care, clinical workflow, and infection control in acute and post-acute settings. Products must meet load-bearing specifications for bariatric patients, incorporate antimicrobial surface treatments, and enable rapid sterilization compatibility. Patient beds command the largest margin pool due to electromechanical complexity and long replacement cycles, while carts represent the fastest-growing category as point-of-care mobility and medication delivery workflows expand. Steel-framed products dominate volume, though plastic and fabric components are gaining share in surfaces requiring frequent replacement and enhanced cleanability.
The FDA enforces medical device quality system regulations that govern design controls and post-market surveillance for powered hospital furniture, while the EPA regulates antimicrobial coating claims and volatile organic compound emissions from finishes and adhesives. These frameworks elevate compliance costs but create barriers that favor established manufacturers with dedicated regulatory affairs infrastructure. Procurement teams must weigh total cost of ownership against upfront capital outlays as reimbursement pressure intensifies and equipment lifecycles compress.
Market Dynamics
Electromechanical bed platforms are forcing capital allocation toward predictive service architectures as acute care systems extend replacement cycles beyond traditional seven-year windows. Ambulatory surgical centers now demand procedure-specific furniture configurations that compress procurement timelines.
Growth Catalysts
- FDA Quality System Regulation updates:Enhanced traceability mandates are accelerating hospital replacement of legacy furniture lacking material validation documentation. Manufacturers with established regulatory affairs infrastructure capture displaced volume.
- Sun Belt hospital construction:Facility renovation cycles in Texas, Florida, and Arizona are compressing replacement schedules for aging patient beds and procedure chairs.
- Antimicrobial surface treatments:EPA-registered coating claims are becoming a non-negotiable specification in infection control procurement, pulling demand toward validated suppliers.
Market Restraints
- Steel input cost volatility:Frame manufacturing faces margin pressure from fluctuating commodity prices, constraining pricing flexibility for mid-tier product lines.
- Powered bed supply concentration:Electromechanical platform assembly concentrates among a limited supplier base in the Midwest, creating delivery timeline risk for integrated delivery networks.
- Antimicrobial coating regulatory friction:EPA pesticide registration requirements for surface treatments extend product development cycles and elevate compliance costs for new entrants.
Strategic Opportunities
- Mexico manufacturing expansion:Nearshoring of frame fabrication and final assembly offers tariff-advantaged supply positioning for US hospital procurement.
- Fleet refurbishment programs:Service-based revenue models for bed platform overhaul and component replacement capture extended capital cycles.
- IRA healthcare facility incentives:Energy-efficient powered bed and lighting integration qualifies for federal tax credits, accelerating replacement demand.
Industry Challenges
- Biomedical technician shortage:Electromechanical bed maintenance requires specialized training that acute care systems struggle to staff, elevating service contract dependency.
- Legacy system integration:New powered platforms must interface with existing nurse call and EMR infrastructure, complicating deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hospital Furniture Market |
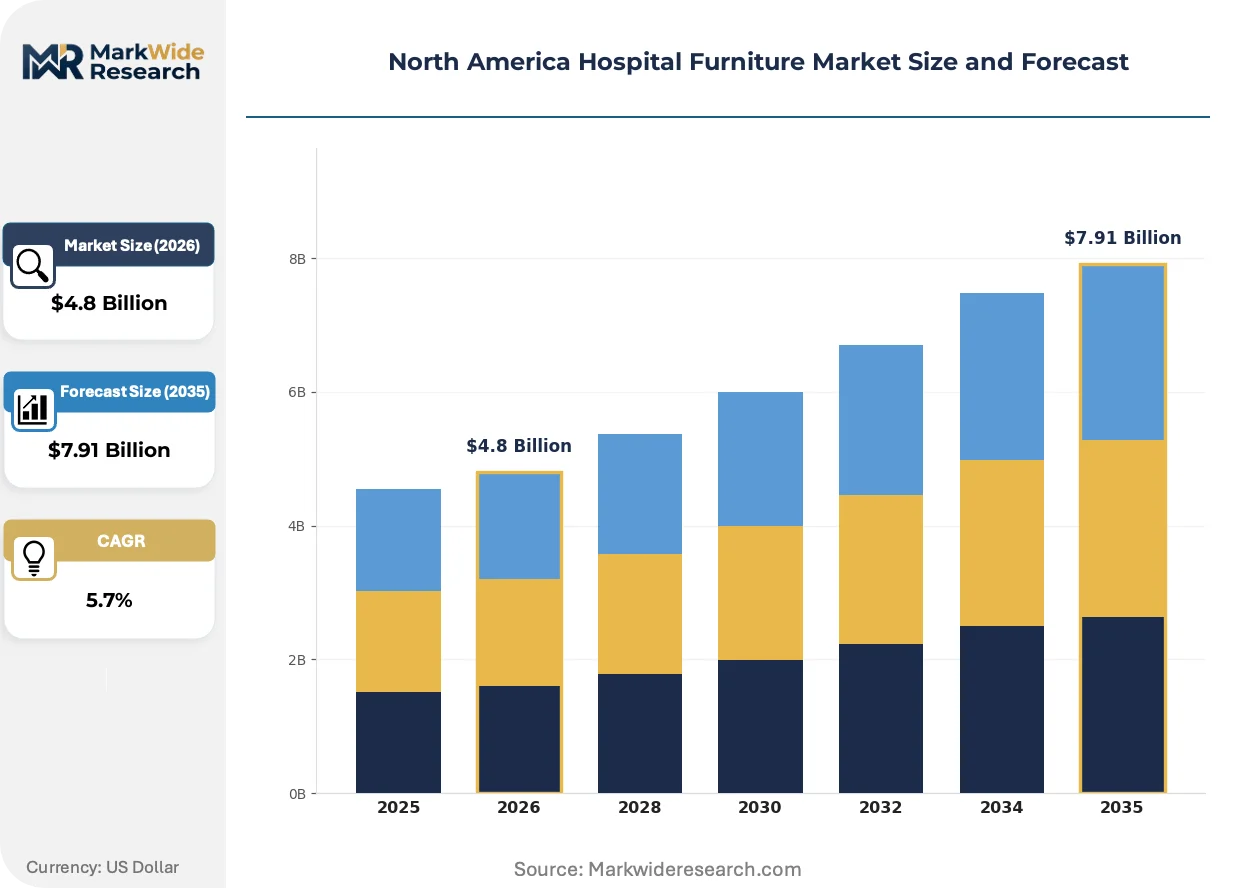
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patient Beds, Chairs, Carts, Tables Material: Steel, Wood, Plastic, Fabric End User: Hospitals, Clinics, Emergency Rooms, Rehabilitation Centers Application: Inpatient Care, Outpatient Care, Surgery, Diagnostic Procedures |
| Companies Covered | Stryker, Hill-Rom Services, STERIS, GPC Medical, Invacare Corporation, Herman Miller, Sunrise Medical, LINET, The Brewer Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hospital Furniture Market Evolving Landscape
Connected sensor architectures are embedding into hospital furniture, generating real-time patient data streams that reshape clinical workflow and asset utilization models. This convergence of physical infrastructure and digital capability is redefining competitive differentiation.
Capacitive patient monitoring systems integrated into bed platforms is collapsing the distinction between furniture and diagnostic equipment. Acute care systems in the US Northeast are piloting these configurations for fall prevention and pressure injury alerts. The technology is collapsing traditional procurement categories that previously separated capital equipment from room infrastructure.
EPA antimicrobial coating validation protocols are tightening claims substantiation requirements for surface treatments marketed to healthcare facilities. Manufacturers must now demonstrate sustained efficacy against specified pathogens under clinical use conditions. Powered bed suppliers with in-house coating capabilities are accelerating third-party testing investments to maintain specification eligibility.
Consolidated procurement through integrated delivery networks is compressing vendor relationships toward sole-source or dual-source arrangements. Group purchasing organizations are unbundling after-sales service from capital purchase, forcing manufacturers to compete on transparent lifecycle cost models. This concentration is most visible in the US Southeast, where hospital system mergers have reduced qualified supplier pools by half in select metropolitan markets.
North America Hospital Furniture Market Segmentation
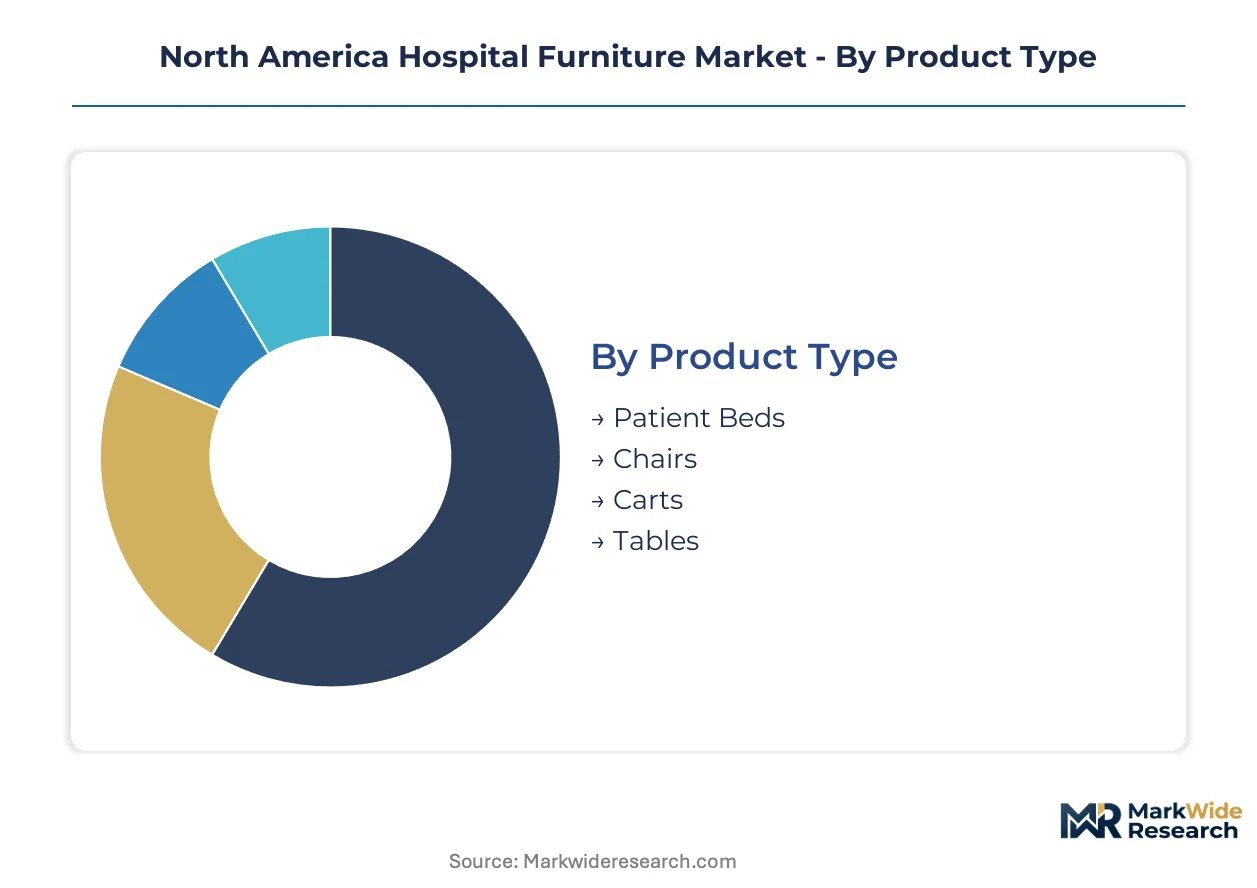
Hospital furniture procurement in North America stratifies across clinical workflow requirements, infection control specifications, and capital cycle timing. Understanding these segment boundaries enables manufacturers to align R&D investment with replacement demand concentration and regulatory compliance thresholds.
Product Type:
Cost tier differentiation separates electromechanical platforms from manual alternatives, with service revenue potential varying dramatically across the spectrum.
- Patient Beds:Electromechanical platforms with motorized height adjustment, Trendelenburg positioning, and integrated scale systems command premium pricing. Demand concentrates in Texas and Florida hospital construction, where bariatric load ratings and antimicrobial surface validation are mandatory specifications.
- Carts:Mobile medication delivery, emergency crash, and procedure-specific configurations incorporate polymer construction for cleanability. Ambulatory surgical centers in Arizona and Georgia are expanding fleet procurement as point-of-care workflows extend beyond traditional nursing stations.
- Chairs:Dialysis recliners, bariatric seating, and procedure chairs with pressure redistribution surfaces serve extended treatment protocols.
- Tables:Surgical, examination, and over-bed configurations span manual and powered actuation for specialty procedures.
Patient beds hold installed capacity. Carts are rotating up the share rankings.
Material:
Application environment dictates material selection, with sterilization compatibility and durability requirements driving specification divergence.
- Steel:Cold-rolled and stainless formulations dominate bed frame and cart chassis construction for load-bearing applications. Sun Belt facility renovations are accelerating replacement of carbon steel frames with corrosion-resistant alloys in high-humidity climates.
- Plastic:High-density polyethylene and thermoplastic polymers replace metal in surfaces requiring frequent replacement and enhanced cleanability. EPA-registered antimicrobial additives are becoming standard in injection-molded components for infection control procurement.
- Wood:Laminate and solid surface options persist in administrative and behavioral health settings where residential aesthetics reduce institutional stigma.
- Fabric:Vinyl-coated textiles and fluid-barrier upholstery serve seating applications with disposable cover protocols.
Steel maintains production dominance. Plastic is climbing the fastest specification rankings.
End User:
Customer type determines procurement authority, with integrated delivery networks consolidating vendor relationships differently than independent facilities.
- Hospitals:Acute care systems with centralized biomedical engineering departments prioritize predictive service contracts and EMR-integrated platforms. FDA quality system documentation requirements are displacing legacy suppliers lacking material traceability infrastructure.
- Clinics:Federally qualified health centers and specialty practices seek modular configurations supporting multi-purpose room utilization. IRA facility incentives are accelerating energy-efficient powered furniture adoption in nonprofit community health settings.
- Emergency Rooms:Rapid-turnover trauma bays demand corrosion-resistant finishes and rapid-decontamination surface protocols.
- Rehabilitation Centers:Long-term post-acute facilities prioritize bariatric capacity and pressure injury prevention in extended-stay configurations.
Hospitals command specification authority. Clinics are rotating up the procurement volume rankings.
Application:
Workflow intensity separates segments, with surgical and diagnostic applications demanding precision positioning versus inpatient comfort prioritization.
- Inpatient Care:Med-surg, ICU, and step-down units require beds with integrated nurse call connectivity and fall prevention sensor architectures. Northeast health systems are piloting capacitive monitoring platforms that collapse furniture and diagnostic equipment categories.
- Surgery:Operating tables and procedure chairs demand radiolucent surfaces, C-arm compatibility, and sterile field maintenance. Ambulatory surgical centers are compressing procurement timelines for specialty-configured platforms.
- Outpatient Care:Examination and infusion settings balance patient comfort with rapid room turnover efficiency.
- Diagnostic Procedures:Imaging-compatible and bariatric-rated configurations serve radiology and endoscopy suites.
Inpatient care holds replacement cycle concentration. Surgery is rotating up the technology investment rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electromechanical bed assembly concentrates in the US Midwest industrial corridor, while frame fabrication migrates toward tariff-advantaged Mexican border states. Canadian health system procurement maintains distinct specification requirements through Health Canada oversight.
United States
Texas, Florida, and Arizona hospital construction cycles are compressing replacement schedules for aging patient beds and procedure chairs. FDA quality system regulation updates are displacing legacy suppliers lacking material traceability infrastructure. The Midwest manufacturing belt around Chicago and Cleveland anchors powered platform assembly for integrated delivery networks.
Canada
Provincial health authorities in Ontario and Quebec are consolidating procurement through shared service organizations. Health Canada medical device regulations enforce bilingual labeling and documentation requirements that elevate compliance costs for foreign suppliers. The Greater Toronto Area hosts distribution hubs serving Atlantic and Prairie province hospital systems.
Mexico
Nearshoring of steel frame fabrication and final assembly accelerates in Nuevo León and Baja California to serve US hospital procurement. Mexican manufacturing offers tariff positioning under USMCA provisions for North American content requirements. Tijuana and Monterrey industrial parks are adding cleanroom finishing capacity for infection-control-compliant surfaces.
North America Hospital Furniture Market Competitive Landscape
Full-line systems integrators and specialized component fabricators split the market between comprehensive service contracts and focused manufacturing efficiency. The vendor base stratifies into three tiers: multinational healthcare conglomerates with predictive service architectures, mid-cap specialists in electromechanical platforms, and regional metalworkers supplying standard frames. Consolidation through integrated delivery network procurement is compressing qualified supplier pools, while Mexico manufacturing partnerships are emerging as a defensive move against steel input volatility.
Among US-based healthcare equipment conglomerates, Stryker and Hill-Rom Services occupy positions anchored by installed base service revenue. Stryker exemplifies the full-line integrator archetype through its powered bed platform and recurring maintenance contracts. Hill-Rom Services represents the predictive service model, capturing extended capital cycles through comprehensive asset management programs. European specialists LINET and STERIS sit within the premium-tier electromechanical segment, differentiated by regulatory affairs infrastructure for FDA and EPA compliance.
| Leading Market Players |
|---|
| Stryker |
| Hill-Rom Services |
| STERIS |
| GPC Medical |
| Invacare Corporation |
| Herman Miller |
| Sunrise Medical |
| LINET |
| The Brewer Company |
| Others |
Value Network & Pricing Analysis
Chicago's electromechanical bed manufacturing cluster concentrates powered platform assembly capacity, and its output constraints translate directly into pricing leverage for integrated delivery networks facing compressed procurement timelines. FDA quality system documentation requirements and EPA antimicrobial coating validation protocols elevate compliance costs that filter through to hospital capital budgets, particularly for mid-tier suppliers lacking in-house regulatory infrastructure.
Pricing Analysis
FDA Quality System Regulation updates dictate the pricing tier structure across the North America hospital furniture landscape. Three-tier pricing stratifies across premium electromechanical platforms with predictive service architectures, standard manual configurations, and economy frame-only alternatives. Price differentiation hinges on antimicrobial coating certification tier and after-sales service bundling. Cost compression in mid-tier steel-framed products is intensifying because of volatile commodity inputs. Federally qualified health centers exhibit highest price sensitivity, while academic medical centers prioritize total cost of ownership over upfront capital outlays.
Supply Chain Analysis
Export-control restrictions on advanced sensor components and semiconductor chips for capacitive patient monitoring systems limit technology transfer into bed platform manufacturing. Electromechanical assembly draws from the United States, Mexico, and Canada under USMCA provisions. Steel frame fabrication, polymer injection molding, and EPA-registered coating application constitute critical input dependencies. Single-source vulnerability concentrates in Midwest powered platform assembly for integrated delivery networks. Distribution runs through group purchasing organization contracts and direct hospital system agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across ambulatory surgical center procurement creates niche opportunities for specialized procedure chair configurations and rapid-turnover mobile carts. The collapse of traditional furniture and diagnostic equipment categories opens white-space for sensor-integrated platform developers.
For Market Incumbents:Pre-empt displacement from connected sensor architectures by accelerating predictive maintenance contract penetration across installed bed bases. Captive supply of antimicrobial coating capabilities defends margin position against EPA validation cost escalation. Stryker and Hill-Rom Services demonstrate the defensive value of comprehensive asset management programs that extend replacement cycle capture.
For New Entrants and Emerging Players:Pursue fleet refurbishment service contracts as acute care systems extend capital cycles beyond traditional replacement windows. Arizona and Georgia ambulatory surgical centers represent the most penetrable geography for procedure-specific chair configurations. Direct contracting with integrated delivery network biomedical engineering departments offers the clearest go-to-market path bypassing consolidated GPO channels.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors electromechanical platform specialists with EPA-registered coating capabilities and FDA quality system infrastructure. Long-term viability across the analysis window rests on recurring service revenue attachment rather than transactional equipment sales. Acquisition targets should demonstrate nurse call and EMR integration expertise. The signal to watch is capacitive monitoring pilot expansion beyond Northeast health systems into Sun Belt construction markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Contract Expansion | Stryker leverages installed base to capture recurring revenue across integrated delivery networks. |
| Antimicrobial Coating In-House Certification | EPA-registered surface treatment capabilities defend specification eligibility in infection control procurement. |
| Mexico Manufacturing Footprint Addition | Nuevo León and Baja California assembly offers tariff-advantaged supply positioning under USMCA. |
| Capacitive Sensor Platform Development | Northeast health system pilots for fall prevention collapse furniture and diagnostic equipment categories. |
| Integrated Delivery Network Direct Contracting | Bypassing GPO consolidation captures sole-source arrangements in Southeast metropolitan markets. |
Research Methodology
Operator-level perspectives from hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and ambulatory surgical center administrators anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, hospital procurement databases, CMS Medicare cost report data, and EPA antimicrobial product registration records. Bottom-up segment sizing triangulated against top-down macroeconomic healthcare expenditure trends.
Scenario-bracketing around steel input cost volatility, FDA enforcement intensity, and integrated delivery network consolidation pace shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material composition, end-user facility category, and clinical application workflow. CAGRs derived from replacement cycle timing, construction pipeline data, and reimbursement pressure indices. Electromechanical platform adoption curves and antimicrobial coating specification penetration served as industry-specific forecast inputs.
Sensitivities concentrate around steel commodity price spikes, EPA coating claim enforcement actions, and Sun Belt hospital construction delays. Forecasts reflect documented assumptions on replacement cycle extension limits and predictive service contract attach rates. Material shifts in FDA quality system regulation scope or USMCA tariff provisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Furniture
Medical Mattress Market
Medical Furniture
Global Chemotherapy Chairs Market
Medical Furniture
Infusion Chair Market
Medical Furniture
Hospital Beds Market
Medical Furniture
Global Medical Furniture Market
Medical Furniture
Medical Walker Market
Medical Furniture
Hospital Bed Management Systems Market
Medical Furniture
Healthcare Smart Beds Market
Medical Furniture
Asia-Pacific Hospital Bed Market
Medical Furniture
Clinical Chairs Market
Medical Furniture
Hospital Furniture Market
Medical Furniture
Europe Hospital Furniture Market
Medical Furniture
Global Smart Hospital Bed Market
Medical Furniture
Global Stretcher Chairs Market
Medical Furniture
Asia-Pacific Hospital Furniture Market
Medical Furniture
Global Automated Hospital Beds Market