
 Hospital Furniture Market | 2026-2036
Hospital Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Hospital Furniture Market Analysis
Preventive maintenance contracts and software-defined bed positioning systems is consolidating recurring revenue streams alongside hardware sales. Stryker leverages its service infrastructure to lock in multi-year hospital contracts. Hill-Rom Holdings, Inc. anchors North American acute care demand through integrated bed-surface-air-mattress systems. Getinge AB competes in Europe with sterilization-compatible furniture lines that reduce cross-contamination risk.
Hospital furniture encompasses beds, stretchers, examination tables, and ancillary equipment engineered to IEC 60601 electrical safety standards and ISO 13485 quality management protocols, primarily serving patient positioning, mobility assistance, and clinical workflow optimization in acute and post-acute settings. Patient beds command the largest revenue pool due to electrification and pressure-injury prevention features, while stretchers represent the fastest-growing category as emergency department throughput demands rise. Stainless steel dominates material selection for infection control compliance, though antimicrobial plastic coatings are gaining share in outpatient clinic environments where weight reduction and cleaning frequency matter most.
The FDA's 510(k) premarket notification and the EU MDR's post-market surveillance requirements are forcing manufacturers to maintain clinical evidence portfolios for powered furniture, directly shaping R&D allocation and market access timelines. Japan's PMDA and METI enforce JIS T 0601 electromagnetic compatibility standards that create additional certification barriers for imported hospital beds. Stakeholders must monitor how reimbursement policy shifts in Medicare and national health systems alter capital equipment purchasing cycles independent of clinical need signals.
Market Dynamics
Powered patient beds with integrated pressure-mapping surfaces are compressing replacement cycles in acute care facilities, forcing manufacturers to reallocate R&D toward software-defined positioning systems and predictive maintenance algorithms.
Growth Catalysts
- EU Medical Device Regulation (MDR):Post-market surveillance mandates for powered beds are elevating clinical evidence requirements, creating competitive moats for manufacturers with robust documentation infrastructure.
- Aging demographics in Germany and Japan:Hospital modernization programs in these markets are accelerating procurement of bariatric-capable beds and mobility-assist furniture.
- IEC 60601 electrical safety standards:Harmonized international certification protocols are reducing redundant testing costs for multi-regional suppliers.
Market Restraints
- Stainless steel price volatility:Infection-control-grade alloys constitute 35-45% of bed frame production costs, exposing margins to commodity swings.
- 510(k) clearance timelines:FDA premarket notification processes for powered medical beds extend 12-18 months, delaying revenue recognition on new electrification features.
- Antimicrobial plastic coatings:Lighter-weight polymer alternatives are gaining traction in outpatient clinics, threatening stainless steel's dominant position in non-acute settings.
Strategic Opportunities
- India's hospital infrastructure expansion:Government-funded district hospital upgrades present entry points for mid-tier bed manufacturers with localized assembly.
- Preventive maintenance contracts:Multi-year service agreements bundling software updates and component replacement are capturing recurring revenue streams alongside hardware sales.
- Pressure-injury prevention mandates:Medicare reimbursement policies penalizing hospital-acquired pressure ulcers are driving demand for integrated air-mattress systems.
Industry Challenges
- Electromagnetic compatibility certification:Japan's JIS T 0601 standards create additional testing barriers for imported powered beds, fragmenting product development roadmaps.
- Legacy hospital IT integration:Bed-positioning software must interface with disparate nurse-call and electronic health record systems, extending deployment timelines.
- Clinical evidence portfolio maintenance:Post-market surveillance requirements under EU MDR demand continuous adverse-event tracking, consuming regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospital Furniture Market |
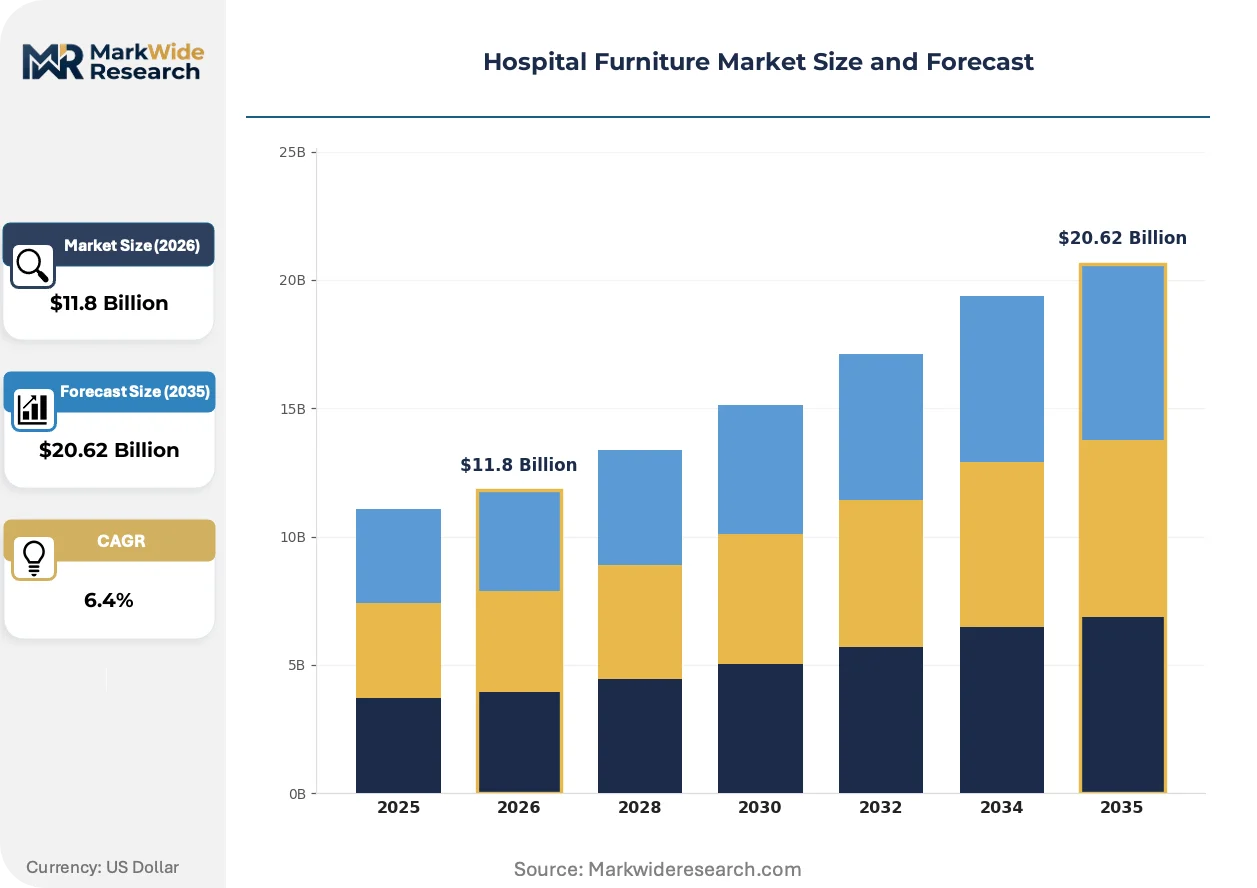
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patient Beds, Examination Tables, Stretchers, Overbed Tables Material: Stainless Steel, Plastic, Wood, Upholstery End User: Hospitals, Clinics, Rehabilitation Centers, Long-term Care Facilities Functionality: Adjustable, Fixed, Mobile, Multi-functional |
| Companies Covered | Stryker, Hill-Rom Holdings, Inc., Invacare Corporation, ARJO AB, Steris Plc., Medline Industries, Inc., Getinge AB, Drive DeVilbiss Healthcare, GF Health Products, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospital Furniture Market Emerging Trajectories
Software-defined functionality is displacing mechanical differentiation in patient beds, while regulatory pressure and procurement centralization are compressing vendor margins and consolidating buyer power.
Sensor-embedded mattress surfaces are converging with real-time pressure-mapping algorithms to enable automated repositioning protocols. Acute care hospitals in the United States are piloting these systems to reduce nursing labor associated with turn schedules. The technology is converging with predictive analytics platforms that flag pressure-injury risk before tissue damage manifests, compressing liability exposure for facilities.
Japan's PMDA and METI are tightening electromagnetic compatibility enforcement for powered beds under revised JIS T 0601 interpretations. Domestic manufacturers with pre-certified component libraries are capturing share from importers facing extended retesting cycles. Pediatric and neonatal intensive care units face the steepest compliance burdens due to sensitivity requirements for low-power medical devices.
Group purchasing organizations are consolidating procurement authority for hospital furniture across multi-hospital systems in the United States. Independent acute care facilities are losing negotiating leverage as contract volumes concentrate with three dominant GPOs. This concentration is most visible in the Southeast and Midwest, where hospital system mergers have reduced the number of independent purchasing decision-makers by half over the past decade.
Hospital Furniture Market Segmentation
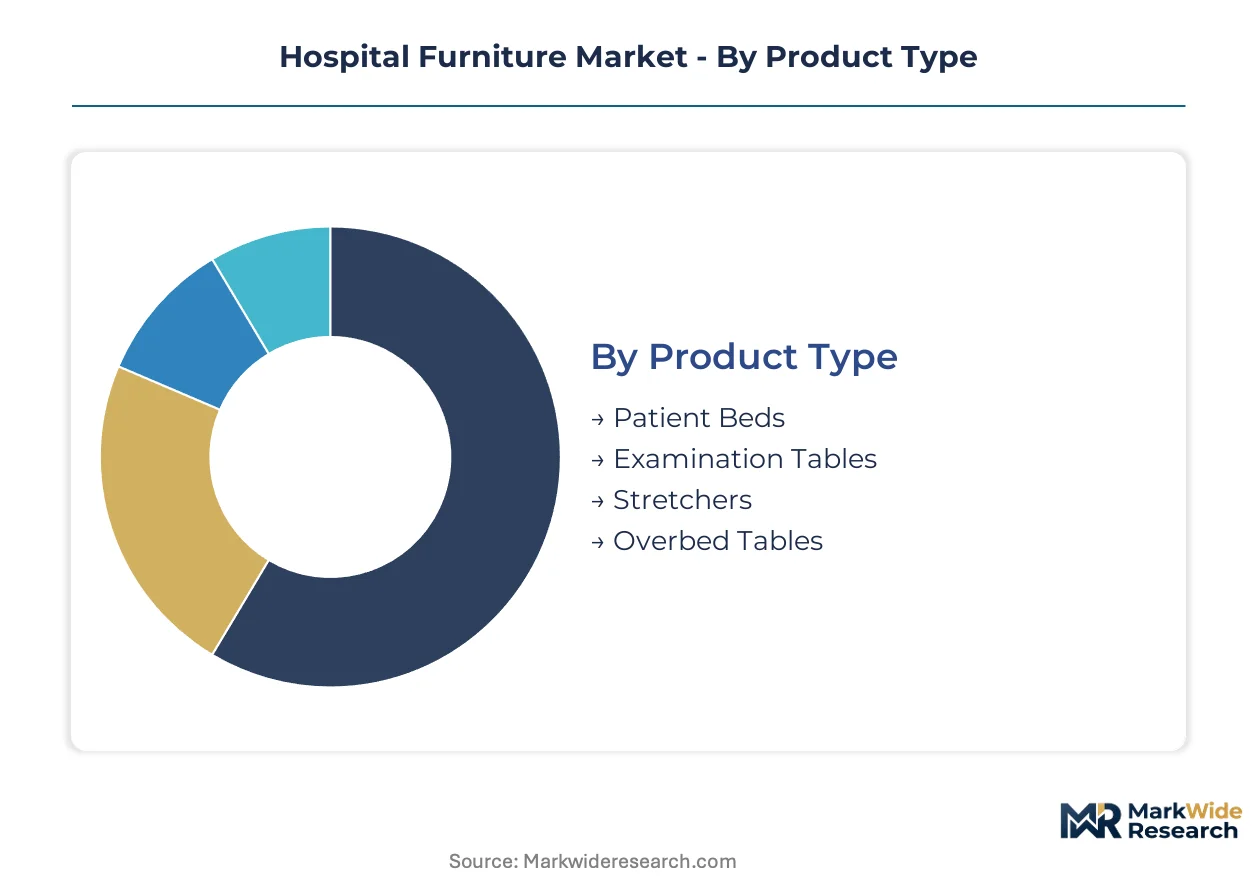
Hospital furniture procurement decisions cluster around electrification thresholds and infection-control mandates, with replacement cycles varying dramatically across acute versus ambulatory settings. Segment boundaries are blurring as powered beds absorb monitoring functions and outpatient clinics demand lighter, reconfigurable equipment.
Product Type:
Upgrade cycles diverge sharply between acute care electrification and clinic-level refresh programs, with powered functionality commanding premium replacement timelines.
- Patient Beds:Electrified frames with integrated pressure-mapping surfaces and software-defined positioning dominate capital allocation in acute care facilities. Demand concentrates in Germany and the United States where Medicare reimbursement penalties for hospital-acquired pressure ulcers accelerate procurement of air-mattress systems.
- Stretchers:Emergency department throughput requirements are driving demand for bariatric-capable, radiolucent designs with integrated oxygen and IV mounting. Japan's hospital modernization programs are expanding fastest here as aging demographics strain ED capacity.
- Examination Tables:Powered height-adjustment and stirrup positioning serve outpatient clinic workflows where patient transfer safety regulations are tightening.
- Overbed Tables:Height-adjustable polymer designs with integrated device mounts support bedside computing and meal delivery in med-surg units.
Patient beds sit at the top of the volume ranking, with stretchers climbing the fastest as emergency department capacity expansion outpaces other infrastructure investments.
Material:
Cost tier separation between infection-control-grade alloys and lightweight polymers determines margin structure and procurement channel access.
- Stainless Steel:Infection-control-grade 304 and 316 alloys constitute the structural backbone of acute care beds and surgical tables, with surface finishes specified to IEC 60601 electrical safety protocols. German and Japanese hospitals maintain strict procurement preferences here despite commodity price volatility.
- Plastic:Antimicrobial polymer formulations with embedded silver-ion or copper additives are displacing metal in outpatient clinics where cleaning frequency and weight reduction outweigh durability requirements. India's district hospital expansion programs are sourcing heavily from this tier.
- Wood:Veneered hardwoods and laminate finishes persist in long-term care and psychiatric settings where residential aesthetics reduce institutional stigma.
- Upholstery:Fluid-resistant vinyl and polyurethane-coated fabrics with welded seams prevent moisture ingress in pressure-redistribution mattress systems.
Stainless steel dominates absolute volume, though plastic is expanding most quickly as ambulatory clinic construction accelerates globally.
End User:
Customer type dictates specification intensity, with acute care hospitals demanding full electrification while long-term care prioritizes durability and transfer assistance.
- Hospitals:Acute care facilities in the United States and Germany are consolidating procurement through group purchasing organizations, bundling powered beds with preventive maintenance contracts and software update subscriptions.
- Clinics:Outpatient diagnostic and surgical centers in Japan are driving demand for space-efficient, multi-purpose examination furniture with rapid reconfiguration capabilities.
- Rehabilitation Centers:Bariatric-capable equipment with integrated lift assistance and parallel bar systems serves stroke and orthopedic recovery protocols.
- Long-term Care Facilities:Pressure-injury prevention surfaces and low-height bed designs address fall-risk management in skilled nursing environments.
Hospitals command the largest revenue pool, with clinics gaining share fastest as care migration to ambulatory settings deepens.
Functionality:
Technology maturity separates established mechanical segments from software-defined positioning systems capturing premium margins.
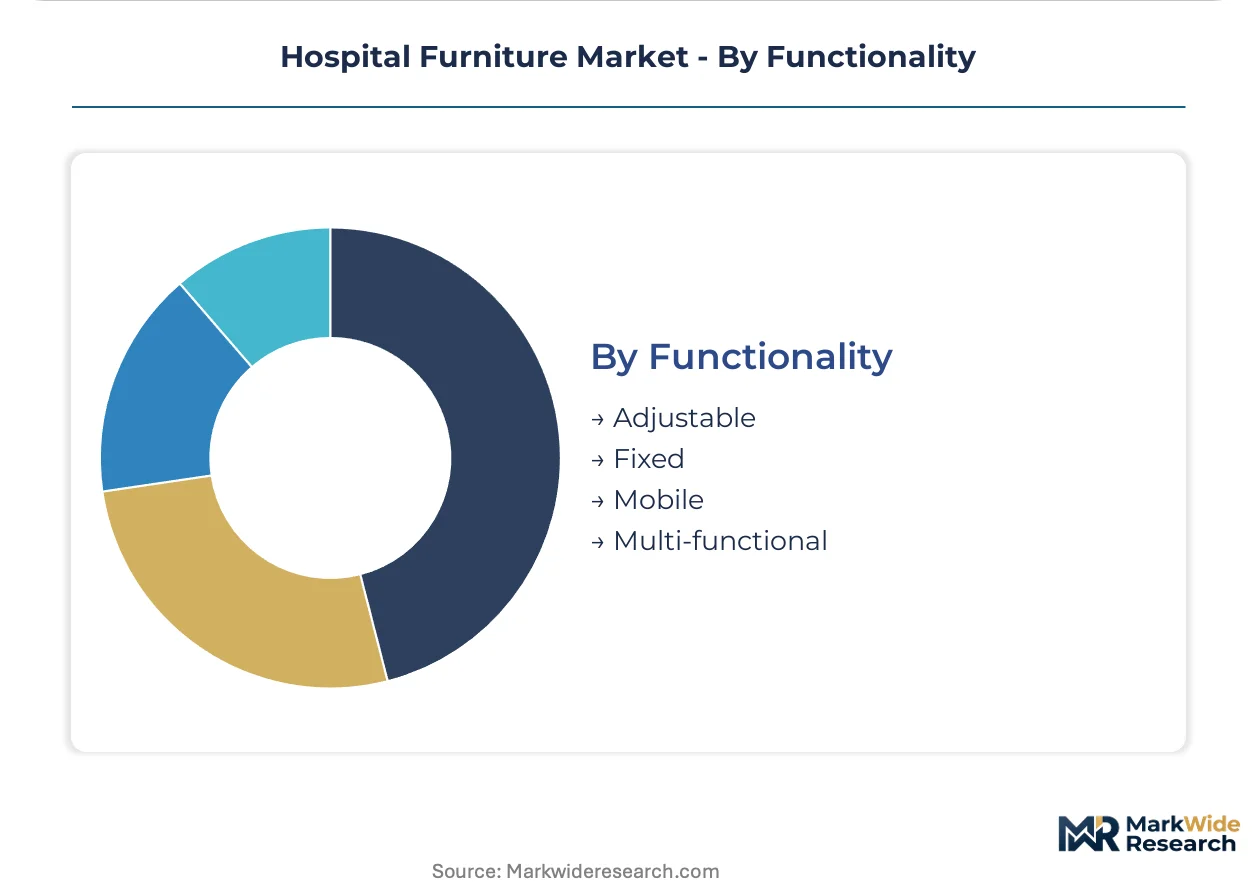
- Adjustable:Powered height, trendelenburg, and cardiac chair positioning with programmable memory settings serve ICU and step-down unit workflows. FDA 510(k) clearance requirements for new motor configurations extend development timelines.
- Mobile:Fifth-wheel steering and central brake systems enable intra-hospital transport without patient transfer, critical for surgical services and imaging departments.
- Fixed:Non-powered designs persist in budget-constrained markets and psychiatric settings where mechanical simplicity reduces maintenance burden and ligature risk.
- Multi-functional:Convertible stretcher-chair configurations and procedure-table hybrids maximize equipment utilization in space-constrained emergency departments.
Adjustable functionality leads volume, with mobile designs showing the steepest expansion trajectory as hospital footprint optimization intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's hospital modernization programs outpace Japan's procurement velocity, though both markets prioritize bariatric-capable electrified beds. The United States concentrates the highest absolute spending on powered patient positioning systems. India's district hospital expansion and Brazil's private healthcare infrastructure investments round out the five-country demand matrix.
United States
Medicare reimbursement penalties for hospital-acquired pressure ulcers accelerate procurement of integrated air-mattress systems. The FDA's 510(k) premarket notification requirements extend clearance timelines for new electrification features. Texas Medical Center and Cleveland Clinic anchor multi-hospital system contracts that bundle preventive maintenance with hardware purchases.
Germany
Aging demographics and hospital consolidation drive replacement cycles for bariatric-capable beds with software-defined positioning. The EU Medical Device Regulation's post-market surveillance mandates elevate clinical evidence requirements for powered furniture manufacturers. Baden-Württemberg's medical technology cluster around Tuttlingen supplies sterilization-compatible furniture lines to acute care facilities.
Japan
Emergency department capacity expansion strains stretcher availability as aging demographics intensify patient throughput demands. METI and PMDA enforce JIS T 0601 electromagnetic compatibility standards that fragment product development roadmaps for imported powered beds. Tokyo's university hospitals pilot sensor-embedded mattress surfaces with predictive analytics platforms.
India
Government-funded district hospital upgrades present entry points for mid-tier bed manufacturers with localized assembly capabilities. CDSCO medical device registration requirements shape import substitution strategies for foreign suppliers. Gujarat's medical device manufacturing zones concentrate plastic-frame production for outpatient clinic environments.
Brazil
Private healthcare infrastructure investments outpace public sector procurement for powered examination tables and mobility-assist furniture. ANVISA's medical device regulatory pathways determine market access timelines for imported hospital beds. São Paulo's hospital networks consolidate purchasing authority through group contracting arrangements.
Hospital Furniture Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with acute care electrification favoring integrated solution providers while outpatient clinics source from regional fabricators. The vendor base organizes into three tiers: multi-regional specialists with service infrastructure, mid-cap manufacturers with localized assembly, and commodity producers competing on stainless steel frame pricing. Strategic moves concentrate on preventive maintenance contract bundling and software update subscriptions that capture recurring revenue alongside hardware sales.
Among North American integrated system providers, Stryker and Hill-Rom Holdings, Inc. exemplify the service-anchored competitive archetype. Getinge AB represents European sterilization-compatible specialization. These three occupy positions where regulatory documentation infrastructure and multi-year hospital contracts create defensive moats against price-based competition.
| Leading Market Players |
|---|
| Stryker |
| Hill-Rom Holdings, Inc. |
| Invacare Corporation |
| ARJO AB |
| Steris Plc. |
| Medline Industries, Inc. |
| Getinge AB |
| Drive DeVilbiss Healthcare |
| GF Health Products, Inc. |
| Others |
Supply Flow & Price Mechanics
Group purchasing organizations in the United States are consolidating procurement authority across multi-hospital systems, compressing vendor margins and shifting pricing power toward volume-based contract structures with bundled preventive maintenance terms.
Pricing Analysis
Capacity additions in China's medical device manufacturing zones are reshaping price floors for mid-tier hospital beds, particularly plastic-frame designs targeting outpatient clinic expansion. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared powered systems with software subscriptions from basic mechanical frames and localized assembly models. Cost compression in the economy tier is intensifying because India's district hospital programs prioritize procurement volume over electrification features. Government procurement committees exhibit the highest price sensitivity, while integrated delivery networks in Germany and Japan accept premium positioning for MDR-compliant documentation and predictive maintenance capabilities.
Supply Chain Analysis
Stainless steel supply rests on German specialty alloy producers, Chinese commodity mills, and Japanese precision metalworkers for infection-control-grade 304 and 316 specifications. Electrification components including linear actuators, pressure sensors, and embedded software modules draw from South Korean and Taiwanese electronics manufacturing. Single-source vulnerability concentrates in medical-grade motor assemblies certified to IEC 60601 electrical safety standards, where qualified supplier pools remain narrow. Distribution runs through group purchasing organizations and regional medical device distributors serving hospital systems, with direct manufacturer relationships reserved for large integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital furniture procurement has entered a late-cycle quality phase where Medicare pressure-injury penalties and EU MDR surveillance mandates favor manufacturers with clinical evidence infrastructure over commodity frame producers.
For Market Incumbents: Anchor multi-year hospital contracts through preventive maintenance bundling and software update subscriptions that lock in recurring revenue alongside hardware replacement cycles. Invest in backward integration into pressure-sensor manufacturing to defend margins against component cost volatility from qualified electronics suppliers. Counter antimicrobial plastic coating substitutes by emphasizing stainless steel's durability credentials in acute care settings where replacement cycle compression threatens long-term contract value. For New Entrants and Emerging Players: Sensor-embedded mattress surfaces with predictive analytics integration offer the most penetrable wedge for technology-first challengers targeting pilot programs at Tokyo university hospitals and Texas Medical Center affiliates. India's government-funded district hospital expansion presents the lowest barrier to entry for mid-tier manufacturers with localized assembly capabilities and CDSCO registration pathways. Pursue direct procurement relationships with state-level health departments rather than competing for GPO contract slots dominated by established incumbents. For Investors and Strategic Acquirers: Medical device conglomerates with existing service infrastructure are the most active acquirer in this space, seeking software-defined positioning capabilities to complement hardware portfolios. Five-to-ten year viability favors targets with robust EU MDR technical documentation and installed base density in Germany or Japan enabling preventive maintenance contract conversion. Watch for inflection when Medicare expands pressure-injury penalty categories or when Japan's METI tightens JIS T 0601 electromagnetic compatibility enforcement beyond current pediatric and neonatal ICU scopes.| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | Predictive analytics platforms for pressure-injury prevention differentiate powered beds in Medicare penalty environments. |
| CE Marking Pathway | EU MDR technical documentation investment creates competitive moats against importers lacking clinical evidence portfolios. |
| Hospital System Partnership | Multi-year preventive maintenance contracts with Cleveland Clinic or Texas Medical Center anchor recurring revenue streams. |
| Backward Integration | In-house production of pressure-mapping sensors reduces dependency on Taiwanese electronics supply chains. |
| Reimbursement Strategy | FDA 510(k) clearance for automated repositioning protocols supports premium pricing against mechanical alternatives. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement managers, biomedical engineers, GPO contracts managers, and regulatory affairs leads at powered bed manufacturers with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement policy updates, and hospital capital equipment procurement records. Bottom-up demand modeling across acute care facilities, outpatient clinics, and long-term care settings triangulated against top-down spending estimates from national health system budget disclosures.
Segment-weighting approaches distributed value across product type, material grade, end-user facility category, and functionality tier, with electrification thresholds and infection-control mandates serving as cross-cutting analytical dimensions. CAGRs were derived from replacement cycle compression rates in acute care versus ambulatory settings, regulatory compliance cost trajectories, and demographic-driven capacity expansion in Germany, Japan, and India. Forecast inputs incorporated Medicare penalty schedule evolution, stainless steel commodity price bands, and software subscription attach rate assumptions for predictive maintenance platforms.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR enforcement consistency, Japan's JIS T 0601 interpretation revisions, and Medicare pressure-injury penalty expansion beyond current hospital-acquired conditions. Material deviation in these regulatory triggers or abrupt stainless steel supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Furniture
Intensive Care Beds Market
Medical Furniture
Asia-Pacific Hospital Bed Market
Medical Furniture
Infusion Chair Market
Medical Furniture
Hospital Bed Management Systems Market
Medical Furniture
Medicine Cabinets Market
Medical Furniture
Global Automated Hospital Beds Market
Medical Furniture
Medical Bed Market
Medical Furniture
Global Medical Furniture Market
Medical Furniture
Asia-Pacific Hospital Furniture Market
Medical Furniture
Clinical Chairs Market
Medical Furniture
Medical Commodes Market
Medical Furniture
Global Smart Hospital Bed Market
Medical Furniture
Hospital Beds Market
Medical Furniture
Electrical Hospital Beds Market
Medical Furniture
Healthcare Smart Beds Market
Medical Furniture
Medical Walker Market