
 Healthcare Flooring Market | 2026-2036
Healthcare Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Flooring Market Analysis
Germany is tilting toward expanded resilient flooring production to serve Central European hospital renovation pipelines. Tarkett leverages integrated polymer compounding operations to shorten lead times for antimicrobial sheet vinyl. Gerflor anchors its position through dedicated healthcare R&D centers focused on slip-resistant surface engineering. Mohawk Group competes via broadloom carpet tile systems engineered for operating theater static control.
Healthcare flooring comprises engineered resilient and textile surfaces designed for clinical environments, typically incorporating antimicrobial additives, welded seam construction, and static-dissipative properties to maintain sterile conditions under heavy rolling loads. Vinyl sheet products dominate hospital installations due to seamless welding and chemical resistance, while rubber flooring captures premium pediatric and imaging suite applications where ergonomics and radiation shielding intersect. Long-term care facilities represent the fastest-growing end user segment as aging-in-place policies extend skilled nursing capacity, with glue-down installations retaining share despite loose-lay advances in rapid-turnover clinic settings.
FDA Center for Devices and Radiological Health oversees antimicrobial coating claims in clinical surface materials, while EPA regulates volatile organic compound emissions from installed flooring through FloorScore and GREENGUARD certification pathways. The EU Medical Device Regulation and REACH chemical restrictions jointly constrain phthalate plasticizer formulations, pushing manufacturers toward bio-based plasticizer alternatives. Stakeholders must weigh regulatory compliance costs against the premium pricing power of certified low-emission systems as procurement standards tighten across acute and post-acute care networks.
Market Dynamics
Rising resident acuity in long-term care facilities is compressing floor replacement cycles and elevating antimicrobial performance requirements across post-acute care networks. This structural pressure reshapes specification standards and procurement priorities simultaneously.
Growth Catalysts
- CMS infection control mandates:US Centers for Medicare & Medicaid Services now require documented floor hygiene compliance in skilled nursing settings, creating enforceable demand for welded-seam vinyl systems.
- Hospital modernization pipelines:Central European renovation programs prioritize antimicrobial sheet vinyl, with Germany anchoring regional specification upgrades.
- Aging-in-place policy expansion:Extended skilled nursing capacity under demographic transition programs drives glue-down installation volumes in long-term care environments.
Market Restraints
- Phthalate plasticizer restrictions:EU REACH chemical constraints and MDR compliance requirements force costly reformulation toward bio-based alternatives.
- Raw material concentration:Specialty polymer compounding capacity clusters in Western Europe, exposing supply chains to regional logistics disruptions.
- Seamless welding skill scarcity:Certified installer availability limits rapid deployment of sheet vinyl systems despite specification demand.
Strategic Opportunities
- Rapid-turnover clinic formats:Loose-lay installation systems penetrate outpatient diagnostic centers and ambulatory surgical facilities where downtime minimization dominates.
- Pediatric and imaging suite specialization:Rubber flooring with radiation shielding properties captures premium positioning in MRI and proton therapy environments.
- GREENGUARD and FloorScore certification leverage:EPA-aligned low-emission standards unlock premium pricing in acute care procurement networks prioritizing indoor air quality.
Industry Challenges
- Antimicrobial claim validation:FDA Center for Devices and Radiological Health oversight of clinical surface coating assertions extends product development timelines and documentation burdens.
- Multi-standard compliance stacking:Simultaneous satisfaction of EU MDR, REACH, and US EPA emission protocols strains quality assurance resources and certification costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Flooring Market |
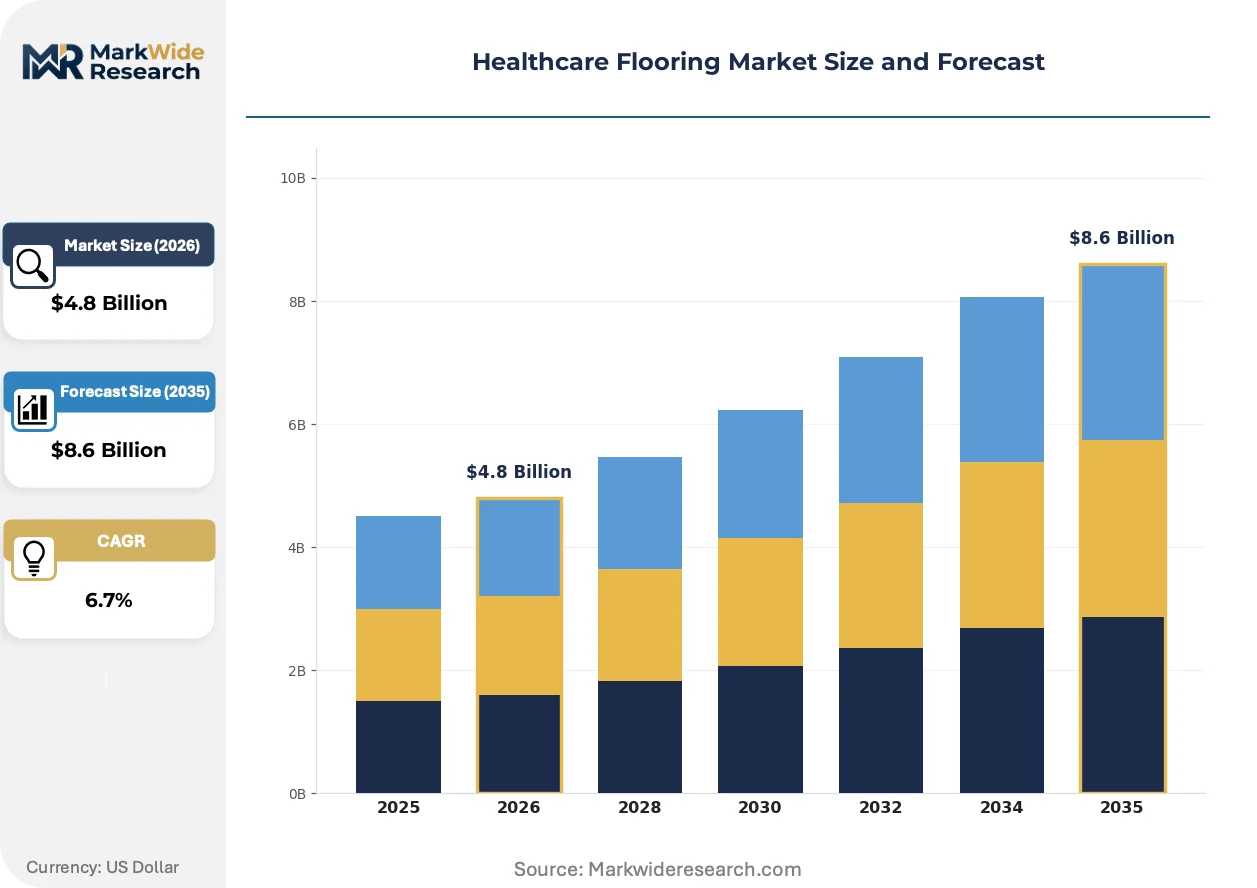
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl, Carpet, Linoleum, Rubber End User: Hospitals, Clinics, Long-term Care Facilities, Medical Offices Installation Type: Glue Down, Loose Lay, Interlocking, Tile Material: Polyvinyl Chloride, Natural Rubber, Glass Fiber, Epoxy |
| Companies Covered | Gerflor, Mohawk Group, Tarkett, Interface, Mannington, Armstrong Flooring, Shaw Industries, Nora Systems, Forbo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Flooring Market Emerging Trajectories
Material science convergence with infection control engineering is redefining performance benchmarks across clinical surface categories. Specification priorities now integrate static dissipation, chemical resistance, and ergonomic properties into unified product platforms.
Welded-seam vinyl sheet technology dominates hospital installations through seamless construction and chemical resistance properties. Acute care facilities specify these systems for operating theaters and intensive care units where sterility maintenance under rolling loads is non-negotiable. The technology is migrating from traditional acute care anchors into outpatient surgery centers and dialysis clinics seeking equivalent performance at compressed project timelines.
EU Medical Device Regulation and REACH chemical restrictions jointly constrain legacy plasticizer formulations. Manufacturers reformulate around bio-based alternatives to maintain market access. German hospital procurement networks exhibit strongest response intensity, prioritizing certified low-emission systems in public tender specifications.
Long-term care operators now specify flooring through lifecycle cost frameworks rather than first-cost minimization. Skilled nursing facilities evaluate total cost of ownership across extended replacement cycles. This behavioral pivot is most pronounced in US post-acute networks where CMS reimbursement pressures elevate maintenance efficiency in capital planning decisions.
Healthcare Flooring Market Segmentation
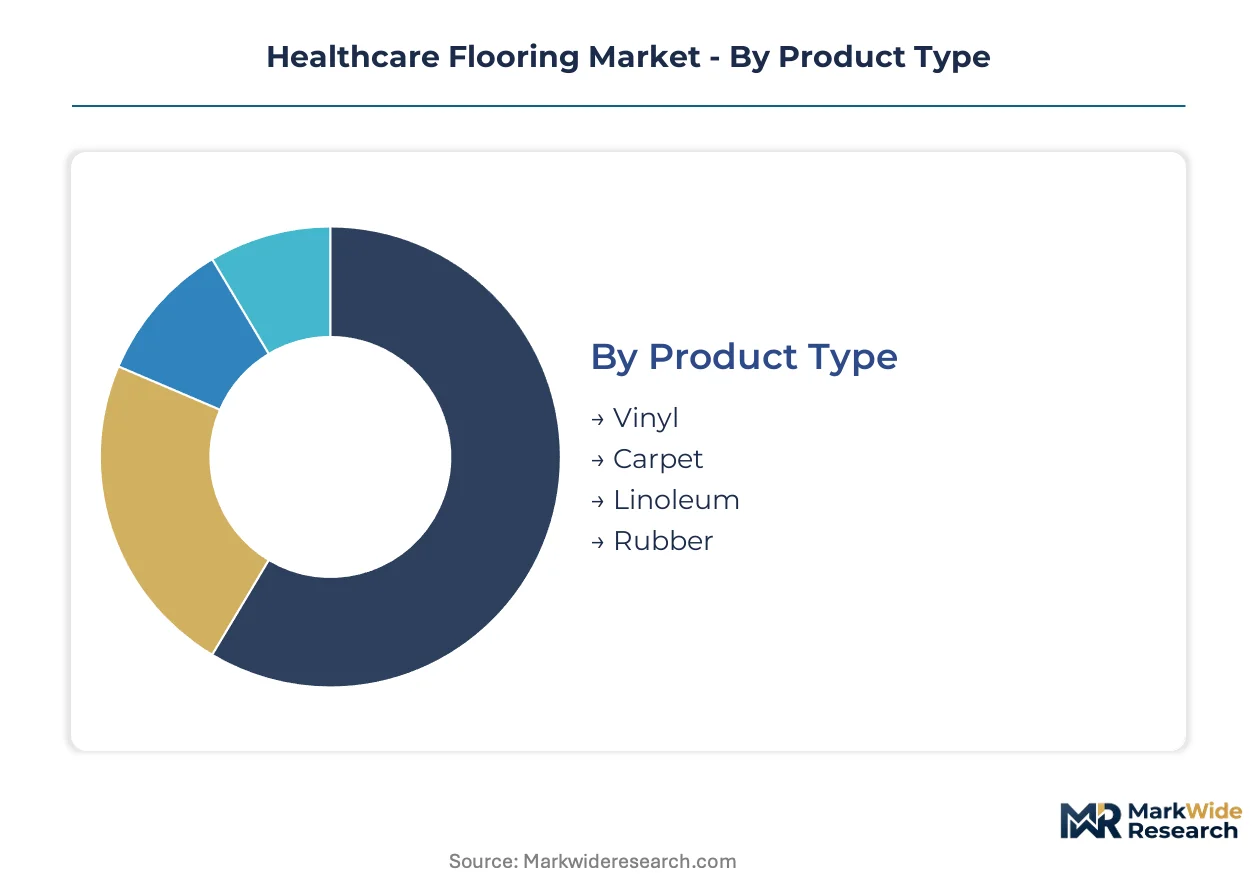
Segmentation in healthcare flooring reveals how clinical environments impose distinct technical demands across surface categories. Specification patterns diverge sharply between acute care sterility requirements and long-term care durability priorities. Understanding these divides illuminates where procurement budgets concentrate and where technology investments yield competitive separation.
Product Type:
Cost tier differentiation separates commodity sheet goods from premium specialty surfaces in clinical procurement networks.
- Vinyl:Homogeneous and heterogeneous sheet products incorporate welded seams and antimicrobial additives for sterile field maintenance. Hospital procurement in Germany prioritizes certified low-emission vinyl systems under public tender modernization programs. PVC formulations face REACH plasticizer constraints, accelerating bio-based alternative adoption.
- Rubber:Natural and synthetic rubber compounds deliver ergonomic cushioning and radiation attenuation properties for MRI and proton therapy suites. Premium positioning in pediatric and imaging environments commands specification priority where staff fatigue reduction intersects with equipment protection. German hospital clusters anchor European demand concentration.
- Carpet:Broadloom and tile systems engineered for static dissipation in operating theaters and administrative zones.
- Linoleum:Bio-based composition with natural antimicrobial properties serving sustainability-focused renovation projects.
Vinyl holds installed capacity. Rubber is rotating up the share rankings.
End User:
Application severity dictates surface performance specifications across the care continuum from sterile surgical fields to residential-scale long-term care environments.
- Hospitals:Acute care facilities specify welded-seam sheet vinyl for operating theaters and intensive care units where rolling load tolerance and chemical resistance are mandatory. Central European renovation pipelines concentrate demand in Germany, with antimicrobial certification requirements tightening specification thresholds. FDA and EPA compliance documentation extends procurement cycles.
- Long-term Care Facilities:Skilled nursing and assisted living operators prioritize lifecycle cost frameworks over first-cost minimization as resident acuity rises and replacement cycles compress. CMS infection control mandates now enforce documented floor hygiene compliance, elevating welded-seam systems in US post-acute networks. Aging-in-place policy expansion extends capacity requirements.
- Clinics:Outpatient diagnostic and ambulatory surgical centers balance performance with rapid installation turnaround.
- Medical Offices:Administrative and examination room environments where aesthetic flexibility competes with cleanability requirements.
Hospitals command specification authority. Long-term Care Facilities are climbing the fastest expansion trajectory.
Installation Type:
Volume throughput and downtime sensitivity determine whether permanent adhesion or rapid deployment systems prevail in project specifications.
- Glue Down:Permanent adhesive installation delivers maximum stability under heavy rolling loads and maintains seam integrity for welded vinyl systems in sterile fields. Long-term care facilities retain dominant share despite labor intensity, as extended service life justifies upfront investment. Certified installer scarcity constrains rapid deployment capacity.
- Loose Lay:Adhesive-free systems with friction-backed or weighted construction enable rapid installation and future reconfiguration. Outpatient diagnostic centers and ambulatory surgical facilities specify these formats where downtime minimization dominates project economics. The format is gaining traction in rapid-turnover clinic settings.
- Interlocking:Mechanical connection systems for modular reconfiguration in temporary or expanding clinical spaces.
- Tile:Modular plank and tile formats balancing installation speed with replacement granularity for high-wear zones.
Glue Down retains specification dominance. Loose Lay is gaining share fastest in outpatient segments.
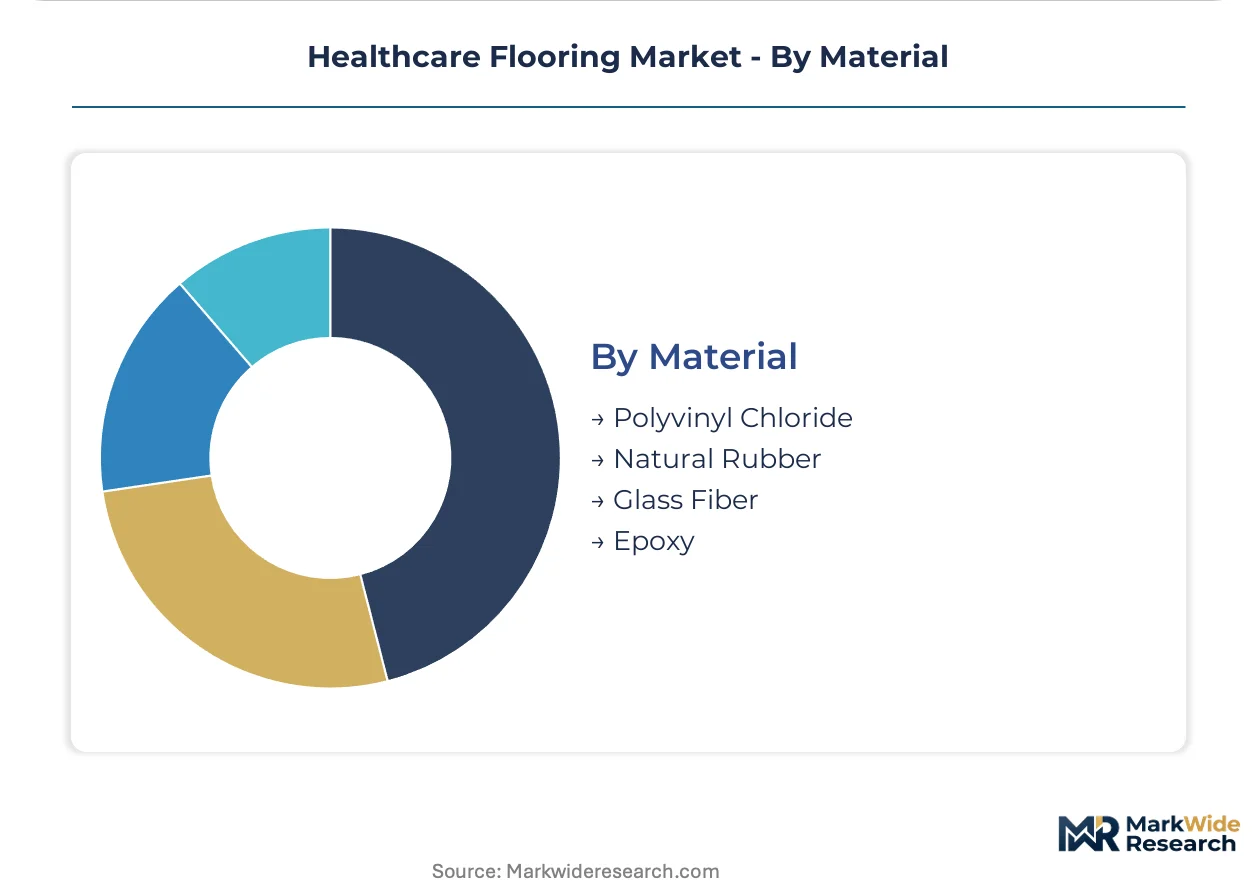
Material:
Supply concentration in polymer compounding and chemical feedstocks shapes regional production advantages and regulatory exposure profiles.
- Polyvinyl Chloride:Chlorinated polymer formulations dominate hospital sheet vinyl through cost efficiency, chemical resistance, and seamless welding compatibility. Western European compounding capacity clusters expose supply chains to regional logistics disruptions. REACH phthalate restrictions force continuous reformulation investment.
- Natural Rubber:Hevea-derived elastomers provide superior ergonomic properties and radiation shielding for specialized imaging and pediatric environments. Premium sourcing from Southeast Asian plantations intersects with sustainability certification demands in German and Nordic procurement networks.
- Glass Fiber:Reinforcement layer for dimensional stability in heterogeneous vinyl constructions.
- Epoxy:Thermoset resin systems for seamless poured applications in wet environments and pharmaceutical manufacturing adjacencies.
Polyvinyl Chloride anchors production volume. Natural Rubber is ascending the value chain in premium segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CMS infection control mandates and hospital modernization programs are concentrating procurement activity in the United States and Germany. These regulatory frameworks are reshaping specification standards across acute and post-acute care networks.
United States
Skilled nursing facilities are extending floor replacement cycles as resident acuity rises under aging-in-place policies. The Centers for Medicare & Medicaid Services now enforce documented floor hygiene compliance, elevating welded-seam vinyl specifications. The Southeast corridor from Florida to Georgia anchors post-acute construction pipelines.
Germany
Public hospital renovation programs prioritize antimicrobial sheet vinyl systems in Central European procurement networks. The EU Medical Device Regulation and REACH chemical restrictions jointly constrain phthalate plasticizer formulations, accelerating bio-based alternatives. The Rhine-Ruhr metropolitan cluster concentrates resilient flooring manufacturing capacity.
United Kingdom
NHS estate modernization is driving specification upgrades across acute care trusts and mental health facilities. National Health Service procurement frameworks increasingly weight indoor air quality certifications in tender evaluations. Greater London and the Midlands concentrate renovation contract awards.
Japan
Super-aging demographics are expanding long-term care facility construction under national capacity targets. The Ministry of Economy, Trade and Industry promotes low-emission building materials through JIS standards alignment. The Kanto region around Tokyo anchors hospital and geriatric care facility development.
France
Regional hospital group consolidation is standardizing flooring specifications across public healthcare networks. ANSM oversight of clinical surface materials extends documentation requirements for antimicrobial claims. The Île-de-France region concentrates acute care renovation activity.
Healthcare Flooring Market Vendor Landscape
Integrated polymer compounders and specialized surface engineers split the market between scale-driven sheet vinyl production and premium rubber system development. The vendor base concentrates in Western European manufacturing clusters with secondary capacity in North American textile regions. Three archetypes dominate: vertically integrated resilient flooring producers, healthcare-dedicated R&D specialists, and broadloom carpet tile manufacturers. Capacity expansion in antimicrobial compounding and strategic partnerships for installer certification networks represent the dominant competitive vectors.
Among Western European integrated producers, Tarkett and Gerflor exemplify the compounder archetype with captive polymer operations. Mohawk Group represents the North American textile-engineering approach to clinical static control. These three anchors occupy distinct positioning vectors within specification networks.
| Leading Market Players |
|---|
| Gerflor |
| Mohawk Group |
| Tarkett |
| Interface |
| Mannington |
| Armstrong Flooring |
| Shaw Industries |
| Nora Systems |
| Forbo |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Western European polymer compounding is forcing sheet vinyl producers into aggressive contract renegotiations while compressing margins for antimicrobial additive suppliers. This utilization imbalance simultaneously elevates pricing power for certified installer networks and intensifies cost scrutiny among German hospital procurement consortiums.
Pricing Analysis
German public tender prices for welded-seam vinyl systems command premiums of 15-25% above comparable Italian and Spanish contract awards, reflecting REACH compliance certification costs and localized logistics. Pricing stratifies across premium certified-low-emission tiers, standard antimicrobial grades, and economy bulk-purchase categories, with FloorScore and GREENGUARD Gold tiers capturing measurable premiums. Cost compression in standard-grade sheet vinyl is intensifying because bio-based plasticizer reformulations have not yet achieved scale economies. Long-term care facility groups exhibit highest price sensitivity due to CMS reimbursement constraints, while proton therapy suite operators show least sensitivity given radiation shielding performance requirements.
Supply Chain Analysis
Contract manufacturing for healthcare flooring concentrates with Tarkett's integrated compounding operations in France, Gerflor's captive polymer facilities in Germany, and specialized antimicrobial additive blending houses in Belgium and the Netherlands. Raw material flows draw from chlorinated PVC resin production in Germany and France, phthalate-free plasticizer development in Scandinavian chemical clusters, and natural rubber sourcing from Southeast Asian plantations. Single-source vulnerability around certified welding equipment and skilled installer training programs constrains rapid deployment capacity for sheet vinyl systems. Distribution runs through specification-influencer networks where architects and infection control consultants channel hospital procurement decisions toward pre-approved manufacturer lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare flooring is approaching a platform-economics inflection where antimicrobial certification interoperability between EU MDR and US FDA pathways will determine which compounders capture cross-Atlantic specification authority. The emergence of unified digital documentation systems for floor hygiene compliance is restructuring procurement committee influence.
For Market Incumbents: Harden specification defenses by deepening captive control over bio-based plasticizer supply chains and accelerating installer certification network expansion in US Southeast corridors. The threat of loose-lay modular systems displacing welded-seam vinyl in rapid-turnover clinics demands preemptive lifecycle cost demonstration tools. Certification investment in dual FDA-EMA antimicrobial claim documentation represents the critical defensive lever. For New Entrants and Emerging Players: US post-acute networks in Florida and Georgia present the most penetrable white-space opportunity, where CMS compliance mandates have outpaced incumbent installer capacity deployment. Pediatric imaging suite rubber flooring offers secondary entry point given radiation shielding specialization barriers. A go-to-market angle anchored in guaranteed installation speed with certified subcontractor partnerships bypasses incumbent specification lock-in. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated compounders with captive antimicrobial additive blending and established German hospital procurement relationships. The five-to-ten year viability window favors manufacturers who have secured bio-based plasticizer scale pathways ahead of REACH enforcement intensification. The signal to watch is consolidation velocity among mid-tier sheet vinyl producers unable to absorb dual-standard compliance costs.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Certification Dual-Track Investment | Simultaneous FDA and EMA claim documentation unlocks cross-Atlantic hospital procurement access. |
| Installer Certification Network Expansion | Captive welding technician training in US Southeast corridors secures rapid deployment capacity for CMS-mandated upgrades. |
| Bio-Based Plasticizer Backward Integration | In-house production of REACH-compliant alternatives insulates margin structure from chemical feedstock volatility. |
| Loose-Lay System Development for Outpatient Segments | Adhesive-free formats penetrate ambulatory surgical centers where downtime minimization dominates capital planning. |
| Radiation Shielding Rubber Specialization | Pediatric and proton therapy suite positioning commands premium pricing in German and US academic medical center procurement. |
Methodological Framework
The analysis maps vinyl sheet systems, rubber specialty surfaces, carpet tile static-control products, and linoleum bio-based alternatives, each validated through hospital procurement managers, infection control officers, flooring contractor estimators, and resilient flooring R&D directors. Primary fieldwork combined structured interviews with specification architects and GPO contract administrators, cross-referenced against secondary validation from CMS Medicare cost reports, EU MDR technical documentation filings, hospital construction pipeline databases, and FloorScore certification registries. Bottom-up project pipeline enumeration and top-down manufacturer shipment analysis were triangulated to establish volume baselines.
Assumptions held fixed include REACH phthalate restriction enforcement timelines and CMS infection control mandate scope, while variables tested included bio-based plasticizer cost curves and loose-lay technology penetration rates across outpatient segments. The projection horizon incorporates product type segmentation by material chemistry and installation format, end-user segmentation by acuity level and regulatory jurisdiction, and geographic segmentation by hospital modernization program intensity. CAGRs were derived from replacement cycle compression modeling and demographic capacity expansion targets, with antimicrobial performance premium elasticity and certified installer supply constraints as key sensitivity inputs.
Practitioners should monitor REACH enforcement intensity, CMS reimbursement rate adjustments, and bio-based plasticizer scale-up milestones for early signals of forecast revision. Quarterly review of German public tender award patterns and US skilled nursing construction permit issuance is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Furniture
Medicine Cabinets Market
Medical Furniture
Global Automated Hospital Beds Market
Medical Furniture
Global Stretcher Chairs Market
Medical Furniture
Electrical Hospital Beds Market
Medical Furniture
Healthcare Smart Beds Market
Medical Furniture
Hospital Furniture Market
Medical Furniture
Asia-Pacific Hospital Furniture Market
Medical Furniture
Global Smart Hospital Bed Market
Medical Furniture
Infusion Chair Market
Medical Furniture
Medical Mattress Market
Medical Furniture
Europe Hospital Furniture Market
Medical Furniture
Hospital Bed Management Systems Market
Medical Furniture
Hospital Beds Market
Medical Furniture
Medical Commodes Market
Medical Furniture
Global Chemotherapy Chairs Market
Medical Furniture
Medical Walker Market