
 Medical Mattress Market | 2026-2036
Medical Mattress Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Mattress Market Analysis
North American foam producers is realigning capacity toward medical-grade viscoelastic formulations to serve hospital group purchasing organizations. Stryker Corporation leverages its integrated stretcher and surface ecosystem to control premium account access across integrated delivery networks. Medline Industries anchors its position through private-label manufacturing scale and direct-to-facility distribution density. Hill-Rom Holdings competes on technology leadership in microclimate management and continuous lateral rotation systems.
A medical mattress is a specialized sleep surface engineered with density-calibrated foam cores, multi-zone air cell arrays, or gel-infused viscoelastic layers to redistribute interface pressure, manage skin microclimate, and support wound healing protocols in clinical and post-acute environments. Foam mattresses dominate hospital procurement volumes due to cost efficiency and durability, while smart mattresses with embedded pressure mapping sensors represent the fastest-expanding margin pool as facilities pursue predictive skin integrity protocols. Air mattresses sustain premium positioning in intensive care and bariatric applications where dynamic pressure modulation is clinically mandated.
The FDA's medical device quality system regulation and the EU MDR's reclassification of powered active surfaces are elevating validation costs and compressing time-to-market for new entrants. ISO 10993 biocompatibility testing and EN 60601-1-2 electromagnetic compatibility standards now gate commercial access across North American and European procurement channels. Stakeholders must monitor how CMS reimbursement adjustments for hospital-acquired pressure injuries reshape capital allocation between preventive surfaces and therapeutic interventions.
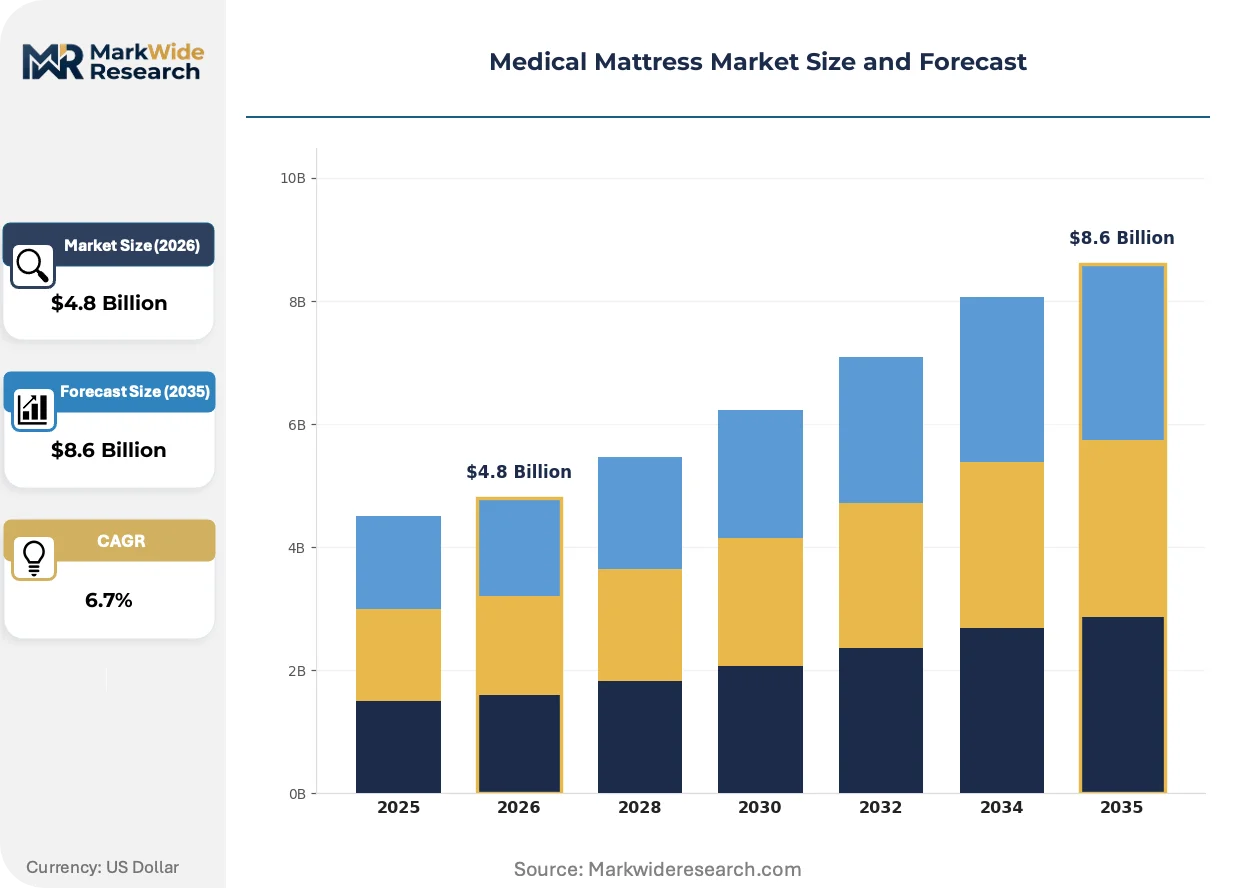
Market Dynamics
Hospital group purchasing organizations are consolidating supplier rosters around integrated surface-stretcher ecosystems, compressing vendor access points and elevating scale requirements for mattress manufacturers seeking acute care contracts.
Growth Catalysts
- EU MDR reclassification:Powered active surfaces now face Class IIa device requirements, accelerating hospital replacement cycles for legacy equipment ahead of compliance deadlines.
- Viscoelastic foam formulations:Medical-grade density calibrations enable pressure redistribution protocols that reduce Stage III-IV pressure injury incidence in long-term care facilities.
- German hospital infrastructure modernization:Federal state-level procurement programs prioritize bariatric and critical care bedding upgrades, concentrating demand among specialized manufacturers.
Market Restraints
- Polyether polyol input volatility:Foam core production depends on petrochemical feedstocks subject to refining capacity constraints and energy price fluctuations.
- ISO 10993 biocompatibility testing:Extended validation timelines for skin-contact materials delay product launches by 8-14 months.
- Air mattress compressor reliability:Electromechanical failure rates in high-utilization ICU environments sustain skepticism among risk-averse procurement committees.
Strategic Opportunities
- Post-acute and home care channels:Discharge planning protocols are extending pressure-relief surface requirements into residential settings, opening direct-to-patient distribution models.
- Predictive sensor integration:Convergence of pressure mapping arrays with electronic health record systems enables real-time skin integrity alerts.
- CMS reimbursement adjustments:Non-payment policies for hospital-acquired pressure injuries create capital allocation priority for preventive surface technologies.
Industry Challenges
- Electromagnetic compatibility certification:EN 60601-1-2 testing for powered mattresses requires specialized laboratory access and iterative design revisions.
- Legacy stretcher integration:New surface technologies must interface with installed bed frames across heterogeneous hospital fleets, complicating installation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Mattress Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam, Air, Gel, Spring End User: Hospitals, Home Care, Nursing Facilities, Rehabilitation Centers Technology: Pressure Relief, Temperature Control, Smart Mattresses, Adjustable Application: Preventive Care, Therapeutic Use, Postoperative Recovery, Chronic Care |
| Companies Covered | Stryker Corporation, Medline Industries, Arjo, Joerns Healthcare, GF Health Products, Invacare Corporation, Drive DeVilbiss Healthcare, Acelity, Hill-Rom Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Mattress Market Emerging Trajectories
Embedded sensing architectures and material science advances are redefining clinical surface functionality, shifting competitive advantage from passive pressure redistribution toward predictive intervention capabilities.
Multi-zone air cell arrays with algorithmic pressure modulation is unifying dynamic support surface design with continuous patient position monitoring. Intensive care units in tertiary hospitals are adopting these systems at accelerated rates. The technology is unifying previously separate capital equipment categories into single-platform procurement decisions.
REACH restrictions on flame retardant chemistries are forcing reformulation of foam core compositions across European manufacturing facilities. Suppliers are migrating to phosphorus-based alternatives ahead of substance authorization deadlines. Powered mattress segments face disproportionate impact due to electrical component density and accompanying fire safety requirements.
Consolidated contracting through integrated delivery networks is compressing vendor negotiation cycles from annual to multi-year frameworks. Regional health systems are displacing individual hospital purchasing autonomy with centralized surface standardization mandates. This pattern is most visible in United States metropolitan markets where IDN penetration exceeds sixty percent of acute care beds.
Medical Mattress Market Segmentation
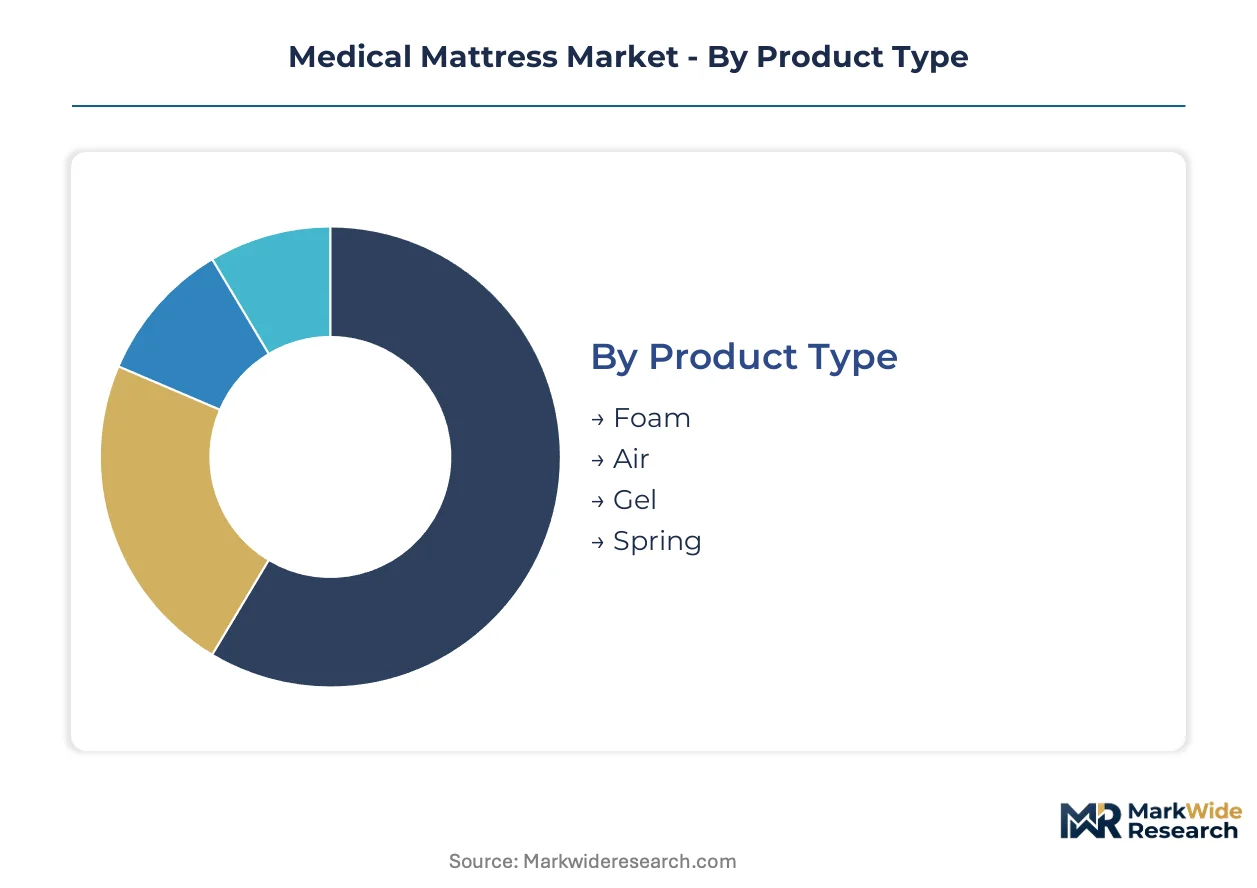
Medical mattress procurement patterns diverge sharply across care settings and clinical protocols. Hospital capital committees weight total cost of ownership against pressure injury prevention outcomes, while post-acute buyers prioritize portability and reimbursement alignment.
Product Type:
Cost tier separates institutional buyers from residential purchasers, with capital availability dictating material selection and replacement cycles.
- Foam:Multi-density polyurethane and viscoelastic cores calibrated for interface pressure redistribution dominate hospital bulk purchasing. German federal procurement programs and US group purchasing organizations concentrate demand for medical-grade density formulations that meet ISO 10993 biocompatibility requirements.
- Air:Alternating pressure and low-air-loss systems utilize electromechanical compressors with algorithmic cell inflation cycles. Intensive care units in tertiary hospitals drive premium positioning where dynamic pressure modulation addresses Stage III-IV wound protocols, though compressor reliability concerns sustain procurement committee scrutiny.
- Gel:Viscoelastic polymer matrices with thermal conductivity properties manage skin microclimate in bariatric applications.
- Spring:Traditional coil constructions persist in budget-constrained long-term care conversions and legacy facility upgrades.
Volume sits with Foam; growth tilts toward Air.
End User:
Application acuity determines performance specifications and regulatory compliance burdens across purchaser categories.
- Hospitals:Integrated delivery networks consolidate surface standardization mandates across metropolitan systems, compressing vendor rosters toward suppliers with stretcher ecosystem compatibility and FDA Class II device clearances.
- Home Care:Discharge planning protocols extending pressure-relief requirements into residential settings open direct-to-patient distribution models with reimbursement-dependent price sensitivity.
- Nursing Facilities:Medicaid reimbursement rates constrain capital budgets toward foam-dominant procurement with extended warranty requirements.
- Rehabilitation Centers:Transitional care settings balance pressure redistribution with patient mobility protocols during recovery timelines.
Procurement volume concentrates in Hospitals; expansion trajectory steepest in Home Care.
Technology:
Margin structure separates passive materials from embedded sensor architectures with predictive capabilities.
- Pressure Relief:Static and dynamic surface engineering redistributes body weight across calibrated support zones, forming the baseline specification for Medicare reimbursement eligibility.
- Temperature Control:Microclimate management systems with moisture-wicking covers and conductive gel layers address perspiration-related skin breakdown in extended immobility cases.
- Smart Mattresses:Pressure mapping arrays integrated with electronic health record systems enable real-time skin integrity alerts. EU MDR Class IIa reclassification elevates validation costs while accelerating hospital replacement cycles for legacy equipment.
- Adjustable:Motorized positioning functions for head-of-bed elevation and Trendelenburg requirements interface with ICU workflow protocols.
Revenue pools concentrate in Pressure Relief; technology investment flows toward Smart Mattresses.
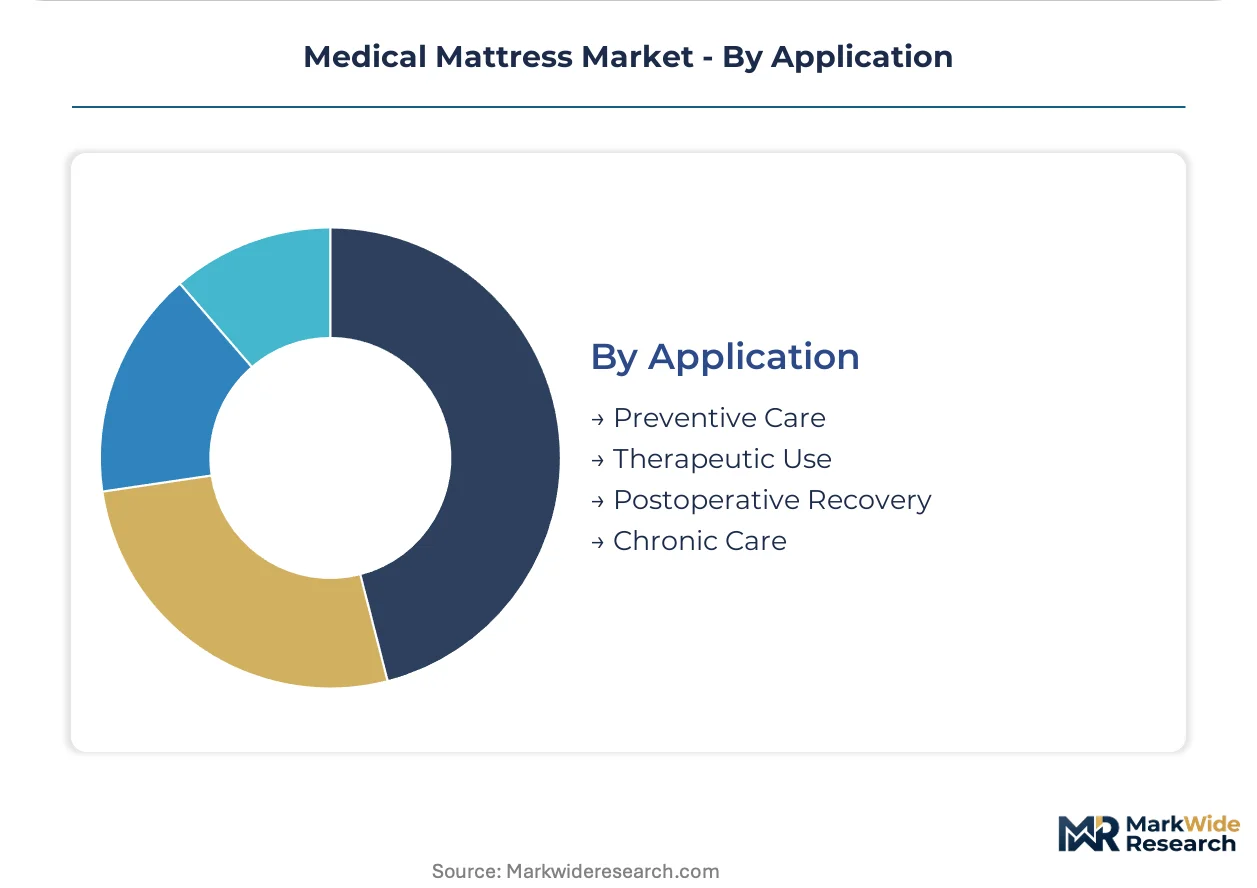
Application:
Clinical outcome metrics and reimbursement risk allocation shape capital allocation priorities between preventive and therapeutic surface categories.
- Preventive Care:Surfaces engineered for pressure injury avoidance in at-risk populations align with CMS non-payment policies for hospital-acquired conditions, prioritizing capital deployment ahead of incidence.
- Therapeutic Use:Advanced support surfaces for existing Stage II-IV wounds require documentation of clinical progression for continued reimbursement authorization.
- Postoperative Recovery:Surgical service line specifications dictate surface selection for orthopedic and cardiovascular procedure protocols.
- Chronic Care:Long-duration immobility management in neurological and palliative settings emphasizes durability and caregiver handling efficiency.
Spend concentrates in Preventive Care; fastest share gains in Therapeutic Use.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyether polyol refining capacity in the US Gulf Coast and petrochemical corridors of Germany anchors foam core supply chains for medical mattress manufacturing. Hospital infrastructure modernization programs and regulatory compliance deadlines are redistributing demand across mature healthcare systems. Procurement concentration follows integrated delivery network consolidation and federal state-level capital allocation priorities.
United States
Integrated delivery networks in metropolitan markets control over sixty percent of acute care bed procurement, compressing vendor rosters toward suppliers with stretcher ecosystem compatibility. FDA medical device quality system regulation elevates validation costs for powered pressure-redistribution surfaces. The US Gulf Coast polyether polyol corridor supplies foam core feedstocks to domestic converters serving hospital group purchasing organizations.
Germany
Federal state-level hospital infrastructure modernization programs prioritize bariatric and critical care bedding upgrades, concentrating demand among specialized manufacturers. EU MDR reclassification of powered active surfaces to Class IIa device requirements accelerates replacement cycles for legacy equipment ahead of compliance deadlines. The Rhine-Ruhr industrial cluster hosts polyurethane formulation facilities supplying medical-grade density calibrations for pressure redistribution protocols.
Japan
Aging demographic expansion drives acute care admission growth and pressure-relief surface procurement in tertiary hospitals. METI industrial standards and PMDA device classification frameworks govern powered mattress commercialization timelines. The Kanto region around Tokyo concentrates hospital capital equipment procurement authority and medical device distribution infrastructure.
China
Hospital infrastructure expansion in provincial capitals creates demand for cost-efficient foam mattresses alongside premium air systems in tier-one cities. NMPA medical device registration requirements and GB standards for electromagnetic compatibility shape market access protocols. The Yangtze River Delta manufacturing corridor supplies polyurethane foam cores and electromechanical components for domestic and export markets.
United Kingdom
NHS procurement frameworks standardize pressure-relief surface specifications across trust-level purchasing, favoring suppliers with national distribution density. MHRA post-Brexit device regulation alignment with EU MDR maintains compliance continuity for powered active surfaces. The Midlands manufacturing belt hosts foam conversion facilities serving hospital and post-acute care channels.
Medical Mattress Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue sensor-embedded smart mattress architectures and direct-to-patient home care distribution. Market structure consolidates around three to five integrated surface-stretcher ecosystems controlling premium account access, while mid-scale foam specialists compete on private-label manufacturing scale. Two strategic archetypes dominate: integrated medical device conglomerates leveraging hospital capital equipment relationships, and focused surface specialists competing on material science differentiation. Competitive moves center on multi-year integrated delivery network contracting and predictive sensor integration with electronic health record systems.
Among US-based medical device conglomerates, Stryker Corporation and Hill-Rom Holdings exemplify the integrated ecosystem archetype, anchoring positions through stretcher-surface compatibility and technology leadership in microclimate management. Medline Industries occupies a scale-driven position within private-label manufacturing and direct-to-facility distribution density. These three entities represent the competitive tension between capital equipment integration and supply chain scale in hospital procurement channels.
| Leading Market Players |
|---|
| Stryker Corporation |
| Medline Industries |
| Arjo |
| Joerns Healthcare |
| GF Health Products |
| Invacare Corporation |
| Drive DeVilbiss Healthcare |
| Acelity |
| Hill-Rom Holdings |
| Others |
Supply Flow & Price Mechanics
Integrated delivery networks in US metropolitan markets control over sixty percent of acute care bed procurement, concentrating purchasing power around multi-year contracting frameworks that compress vendor margins while demanding extended warranty and service bundling. This buyer concentration forces manufacturers to absorb ISO 10993 validation costs and compressor reliability guarantees into upfront pricing.
Pricing Analysis
Extended warranty and preventive maintenance bundling separates premium-tier suppliers from unbundled economy competitors in hospital procurement channels. Three-tier pricing structure across premium, standard, and economy levels reflects FDA Class II device clearance status, ISO 10993 biocompatibility certification tier, and stretcher ecosystem compatibility depth. Cost compression in foam core segments is intensifying because polyether polyol feedstock volatility and REACH flame retardant reformulation expenses are squeezing converter margins. Nursing facilities operating under Medicaid reimbursement constraints exhibit the highest price sensitivity, while tertiary ICU procurement committees prioritize compressor reliability and predictive sensor integration over unit cost.
Supply Chain Analysis
Regional distribution centers in the US Gulf Coast, Germany's Rhine-Ruhr corridor, and China's Yangtze River Delta form a hub-and-spoke pattern feeding hospital group purchasing organizations and direct-to-facility channels. Polyether polyol refining capacity in Texas and Louisiana, polyurethane formulation expertise in North Rhine-Westphalia, and electromechanical component manufacturing in Jiangsu Province anchor global production. Medical-grade foam core production rests on petrochemical feedstock availability, specialized blowing agent chemistries, and REACH-compliant flame retardant alternatives. Single-source vulnerability in polyether polyol supply creates exposure to energy price shocks and refining capacity constraints. Distribution runs through IDN-centralized warehousing with direct-to-bed delivery protocols replacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical mattress sector is becoming a vertical-integration race as manufacturers pursue captive control over polyurethane formulation and sensor-embedded software stacks to defend margin structure against consolidated hospital procurement.
For Market Incumbents: Cement stretcher ecosystem lock-in by acquiring complementary surface technology specialists and deepening backward integration into medical-grade foam formulation. Threats from algorithmic pressure-modulation entrants and EU MDR compliance cost escalation demand defensive certification investment and multi-year IDN contracting ahead of legacy equipment replacement cycles. For New Entrants and Emerging Players: The price-point gap between premium air-mattress systems and economy foam replacements creates white-space opportunity in mid-tier smart surfaces with modular sensor retrofit capability. Post-acute home care channels show the most penetrable demand profile, with direct-to-patient distribution and reimbursement-aligned rental models offering viable go-to-market positioning outside IDN vendor rosters. For Investors and Strategic Acquirers: The window for entry favors specialized sensor-embedded surface developers with FDA Class II clearance pathways and EHR integration capabilities. Long-term viability hinges on predictive skin integrity protocol adoption across accountable care organizations. Watch CMS reimbursement adjustments for hospital-acquired pressure injuries as the inflection signal for preventive surface capital allocation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Class II Device Clearance | Unlocks powered pressure-redistribution mattress sales to integrated delivery networks under quality system regulation. |
| EU MDR Class IIa Certification | Enables continued commercialization of active surfaces in German hospital modernization programs ahead of compliance deadlines. |
| Hospital System Partnership | Secures multi-year surface standardization mandates across metropolitan IDNs controlling sixty percent of acute care beds. |
| Software Companion Development | Integrates pressure mapping arrays with Epic and Cerner EHR systems for real-time skin integrity alerts. |
| Reimbursement Strategy | Aligns preventive surface positioning with CMS non-payment policies for hospital-acquired pressure injuries. |
Methodological Framework
Document review covered FDA 510(k) filings, EU MDR technical documentation, hospital GPO contract databases, and CMS Medicare cost report data, complemented by interviews with hospital biomedical engineers, GPO contracts managers, foam conversion plant managers, and regulatory affairs specialists at powered surface manufacturers. Secondary validation drew from ISO 10993 biocompatibility test reports, EN 60601-1-2 electromagnetic compatibility filings, and polyether polyol trade flow data. Bottom-up hospital procurement volume estimates and top-down medical device market sizing were triangulated to establish baseline demand figures.
Historical shipment data was cross-referenced against panel input from procurement executives at tertiary hospital systems and post-acute care operators. The analytical framework modeled demand across product type, end user, technology tier, and application acuity throughout the forecast period. CAGRs were derived from segment-level volume projections calibrated to federal hospital infrastructure spending patterns and EU MDR replacement cycle timing. Industry-specific inputs included REACH flame retardant substance authorization timelines and CMS reimbursement policy adjustment probabilities.
Inputs from FDA registration databases and German federal state procurement portals were available through the study window; gaps in real-time hospital capital budget allocation data introduce uncertainty bands around near-term volume projections. Forecasts reflect documented assumptions regarding IDN consolidation velocity and sensor-embedded surface adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Furniture
Medicine Cabinets Market
Medical Furniture
Asia-Pacific Hospital Bed Market
Medical Furniture
Global Smart Hospital Bed Market
Medical Furniture
Medical Bed Market
Medical Furniture
Hospital Bed Management Systems Market
Medical Furniture
Medical Walker Market
Medical Furniture
Global Chemotherapy Chairs Market
Medical Furniture
North America Hospital Furniture Market
Medical Furniture
Electrical Hospital Beds Market
Medical Furniture
Hospital Furniture Market
Medical Furniture
Medical Commodes Market
Medical Furniture
Clinical Chairs Market
Medical Furniture
Intensive Care Beds Market
Medical Furniture
Global Medical Furniture Market
Medical Furniture
Healthcare Smart Beds Market
Medical Furniture
Europe Hospital Furniture Market