
 Asia-Pacific Hospital Bed Market | 2026-2036
Asia-Pacific Hospital Bed Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Hospital Bed Market Analysis
Leasing and rental-based asset-light models is fragmenting competitive dynamics across the Asia-Pacific hospital bed landscape. Paramount Bed Holdings Co., Ltd. anchors its position through deep vertical integration across Japanese manufacturing and regional distribution networks. Hill-Rom Holdings Inc. differentiates through intensive R&D investment in smart-bed sensor technology for intensive care applications. Jiangsu Aegean Technology Co. Ltd. competes aggressively on cost-optimized electric bed configurations for China's provincial hospital procurement tenders.
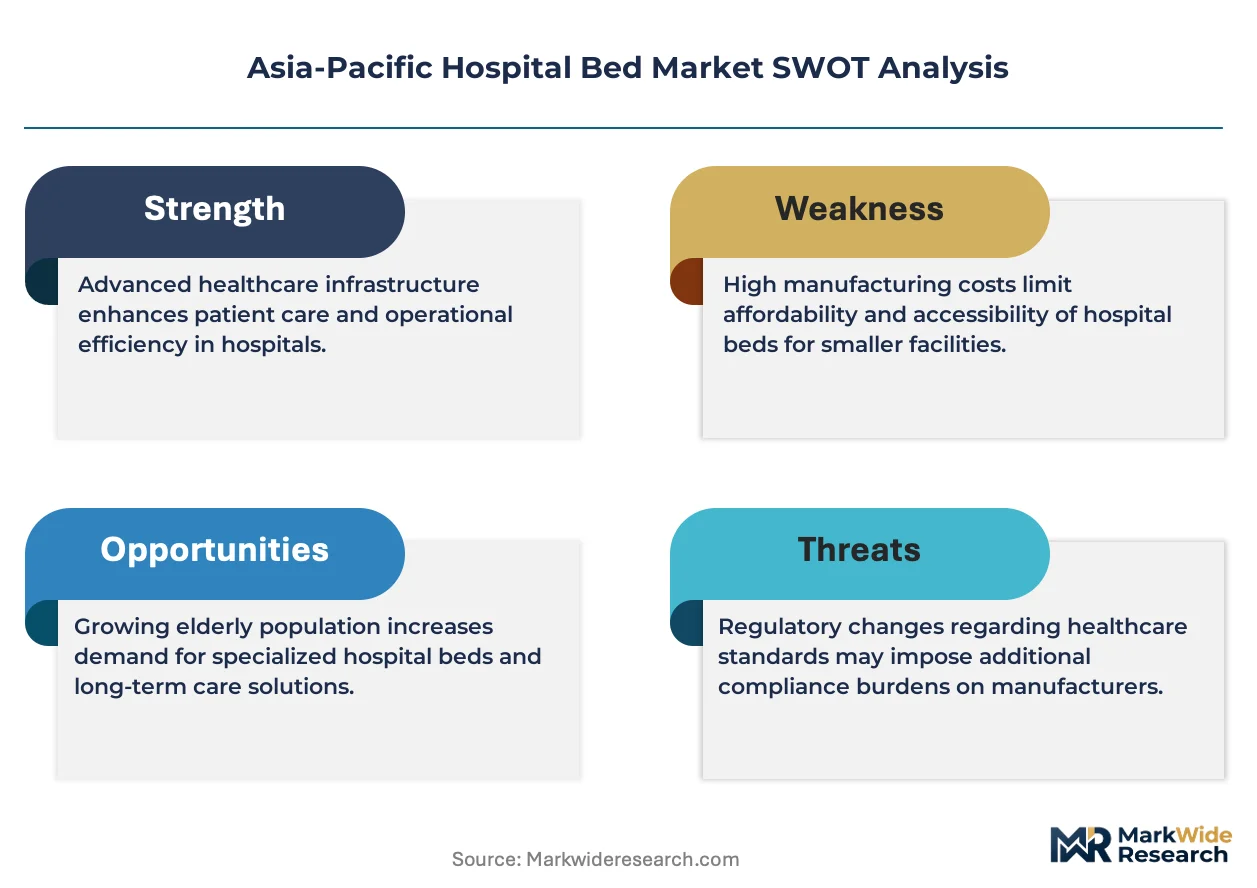
Hospital beds are height-adjustable platforms engineered with steel or composite frames, motorized actuators, and load-bearing capacities typically exceeding 250 kilograms, designed to position patients for clinical procedures and recovery. Electric beds command expanding share as Chinese and Indian hospitals replace manual systems to reduce nursing strain and improve patient turnover efficiency. Bariatric beds represent a concentrated margin pool given specialized engineering requirements and limited supplier bases across the region. Metal-frame construction dominates procurement volumes, though composite materials gain traction in pediatric and long-term care settings where weight reduction and cleaning protocols matter.
Japan's Ministry of Economy, Trade and Industry (METI) enforces JIS standards for medical electrical equipment, while China's National Medical Products Administration (NMPA) certifies bed-mounted electronic systems under revised GB standards. India's Central Drugs Standard Control Organization (CDSCO) now requires bed-side rail strength testing for all imported and domestically manufactured hospital beds. Stakeholders must monitor how divergent national certification timelines affect cross-border product rollout strategies and localized assembly investments.
Market Dynamics
Leasing models are fragmenting competitive dynamics across the Asia-Pacific hospital bed landscape, forcing manufacturers to choose between asset-heavy manufacturing scale and service-based recurring revenue streams.
Growth Catalysts
- India's PLI scheme:The production-linked incentive framework accelerates domestic electric bed manufacturing, reducing import dependency for motorized systems across tier-two and tier-three hospital networks.
- China's NMPA GB standards revision:Updated certification requirements for bed-mounted electronics create compliance-driven replacement cycles in provincial hospital procurement.
- Long-term care expansion:Southeast Asian governments are expanding bed capacity in aged care facilities, generating sustained demand for bariatric and pressure-relief configurations.
Market Restraints
- Steel and actuator cost volatility:Input price swings for high-grade steel and German-sourced linear actuators compress margins on mid-range electric bed configurations.
- Supplier concentration in Japan:Critical sensor and control module production clusters around Osaka and Nagoya, creating single-source vulnerability for regional assemblers.
- Manual bed substitution ceiling:Rural clinics in Indonesia and Vietnam retain manual systems due to unreliable electricity infrastructure, capping electrification penetration.
Strategic Opportunities
- Vietnam's underpenetrated provincial hospitals:Northern and central provinces lack motorized bed density, presenting first-mover advantage for cost-optimized electric configurations.
- Sensor-telemetry convergence:Integration of load cells and patient monitoring modules enables ICU-grade functionality in general ward beds.
- Rental channel innovation:Third-party medical equipment lessors in Thailand and Malaysia are building captive bed fleets, bypassing traditional distributor networks.
Industry Challenges
- Biomedical technician scarcity:Maintenance and calibration of electric actuators and control systems outpaces trained workforce supply across Philippine and Indonesian hospital networks.
- CDSCO certification timelines:India's bed-side rail strength testing requirements extend product approval cycles, delaying market entry for new configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Hospital Bed Market |
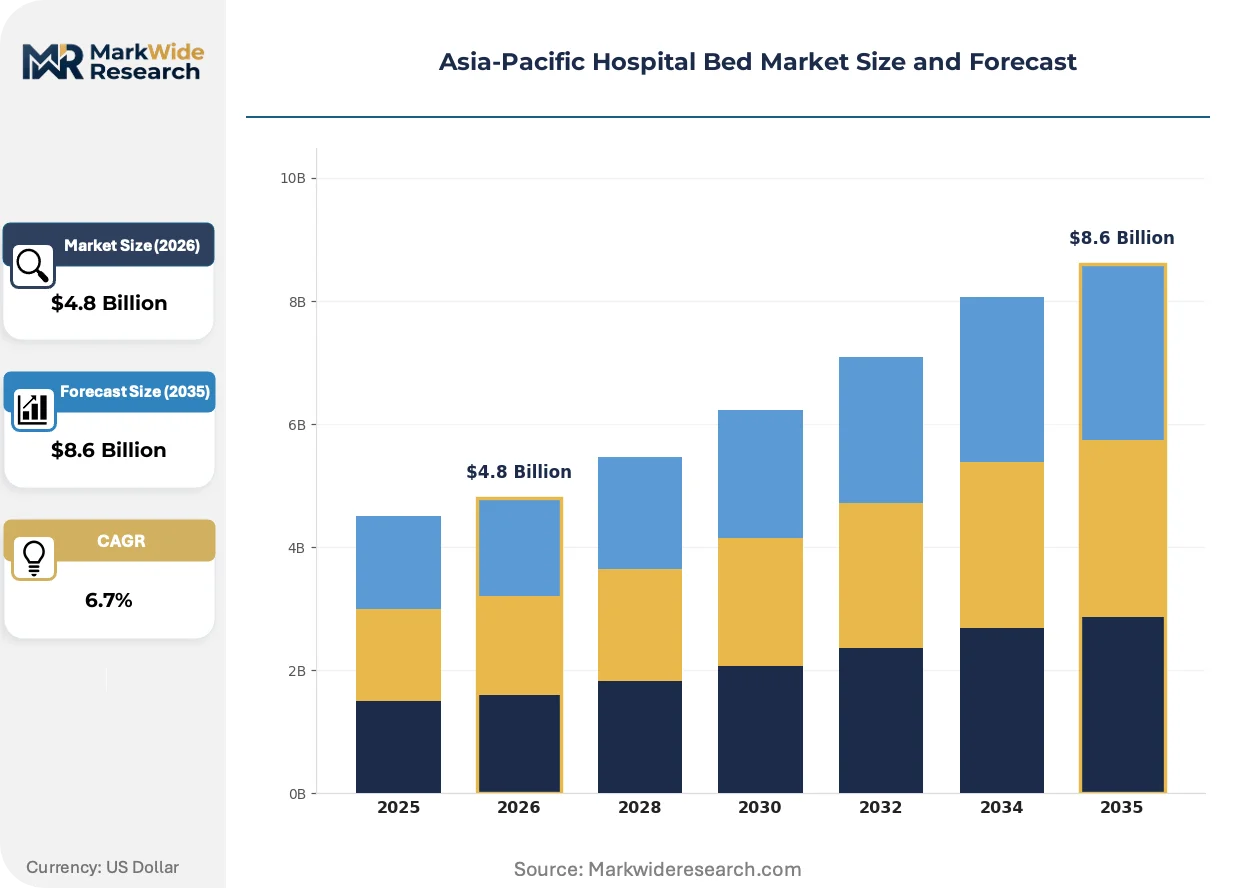
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Beds, Electric Beds, Semi-Electric Beds, Bariatric Beds End User: Hospitals, Clinics, Home Care, Long-Term Care Facilities Material: Metal, Plastic, Composite, Wood Design: Standard, Trendelenburg, Pediatric, Adjustable |
| Companies Covered | Invacare Corporation, Funtech, Paramount Bed Holdings Co., Ltd., Getinge AB, Guangdong Kareway Medical Technology Co. Ltd., Hill-Rom Holdings Inc., Jiangsu Aegean Technology Co. Ltd., Mindray, Stryker Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Hospital Bed Market Emerging Trajectories
Smart-bed sensor technology is actively reshaping product architecture, while regulatory divergence and procurement model fragmentation are forcing manufacturers to build modular platforms capable of rapid market-specific adaptation.
Composite frame materials are hybridizing traditional steel construction in pediatric and long-term care segments. Japanese manufacturers are integrating carbon-fiber reinforced polymers to reduce bed weight by thirty to forty percent without sacrificing load capacity. This material shift is hybridizing supply chains, as metal stamping specialists partner with aerospace composite processors to meet JIS standards for medical electrical equipment.
Japan's METI is enforcing stricter electromagnetic compatibility testing under revised JIS T 0601-1 standards for bed-mounted electronics. The regulation mandates shielding protocols for motors and control systems, adding engineering cost but creating competitive moats for compliant suppliers. Intensive care units in Tokyo and Osaka hospitals are prioritizing certified configurations, displacing uncertified imports from secondary suppliers.
Asset-light rental models are compressing ownership cycles across Southeast Asian hospital networks. Third-party lessors in Bangkok and Kuala Lumpur are unbundling maintenance from capital expenditure, allowing provincial hospitals to access electric beds without balance-sheet commitment. This behavioral shift is most visible in Thailand's private hospital chains, where operating lease penetration now exceeds direct purchase for non-ICU bed categories.
Asia-Pacific Hospital Bed Market Segmentation
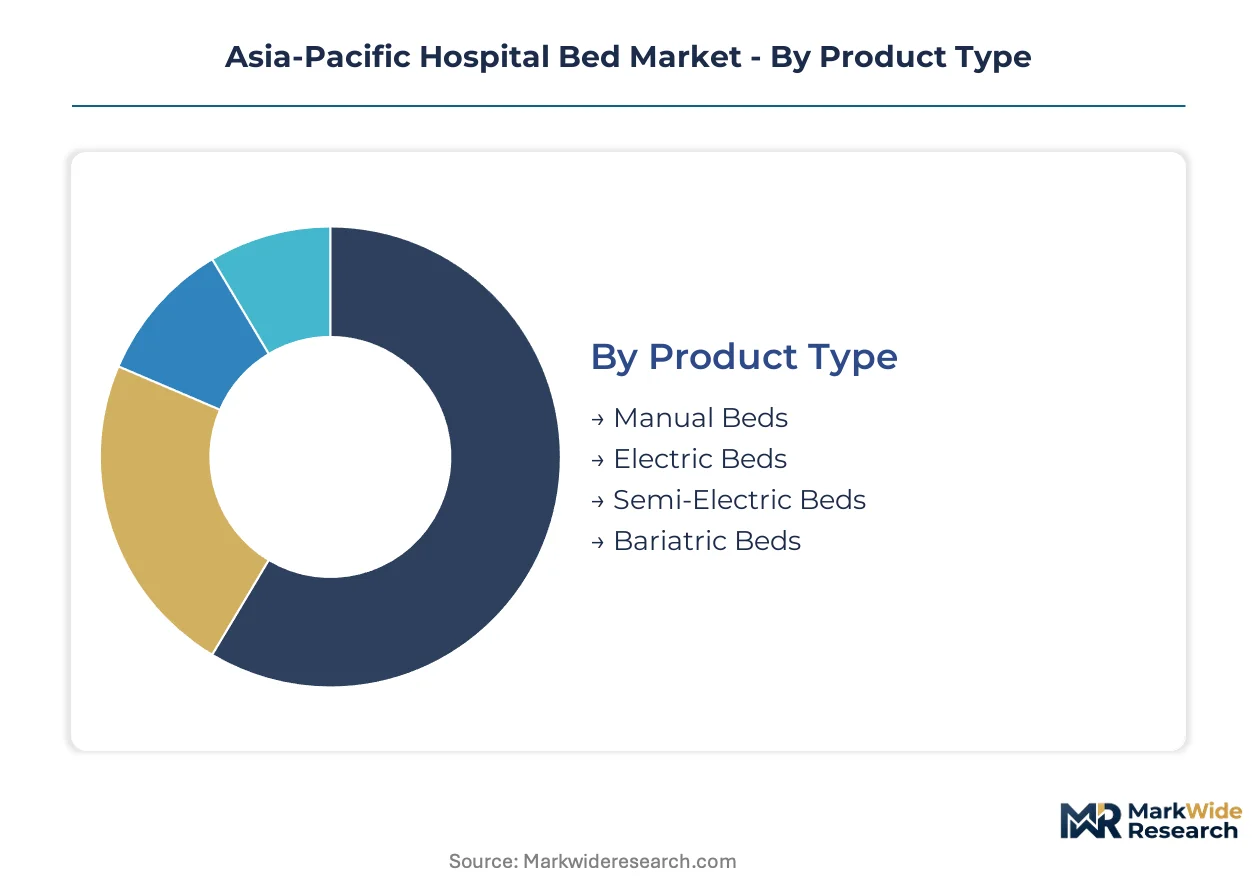
Segmentation in the Asia-Pacific hospital bed market reveals distinct procurement rhythms across product tiers and care settings. Replacement cycles vary from five-year intervals for basic manual units to accelerated two-year refresh rates for sensor-equipped ICU configurations.
Product Type:
Cycle times compress sharply as electrification intensifies, with motorized systems turning over faster than mechanical platforms due to software obsolescence and sensor integration demands.
- Manual Beds:Steel-frame platforms with hand-crank height and section adjustment, lacking motorized actuators. Rural Indonesian and Vietnamese clinics retain these systems where grid reliability remains problematic, capping electrification penetration in archipelago geographies.
- Electric Beds:Fully motorized platforms with handset-controlled height, Trendelenburg, and cardiac chair positioning. China's tier-two city hospital upgrades are replacing manual fleets with these systems to reduce nursing strain and accelerate patient turnover efficiency.
- Semi-Electric Beds:Hybrid configurations with electric height adjustment and manual head/foot section control. India's PLI scheme is accelerating domestic assembly of these mid-tier units for provincial hospital procurement tenders.
- Bariatric Beds:Reinforced frames with load capacities exceeding 450 kilograms and expanded mattress platforms. Specialized engineering requirements and limited supplier bases across Southeast Asia concentrate margins in this configuration.
Manual beds dominate installed base across rural archipelago geographies. Electric beds are where expansion concentrates as Chinese provincial hospitals modernize infrastructure.
End User:
Procurement authority fragments across capital expenditure committees, with acute care facilities prioritizing technology integration while long-term care operators emphasize durability and cleaning protocols.
- Hospitals:Tertiary and secondary acute care facilities with ICU, general ward, and surgical recovery requirements. China's NMPA GB standards revision for bed-mounted electronics is driving compliance-driven replacement cycles in provincial procurement.
- Long-Term Care Facilities:Aged care institutions with pressure-relief mattress compatibility and fall-prevention rail requirements. Southeast Asian governments are expanding bed capacity in these facilities to serve aging demographics.
- Clinics:Primary care and outpatient surgical centers with limited procedure recovery needs. Manual bed retention rates remain highest in this channel due to capital constraints.
- Home Care:Residential settings with rental-based delivery models and caregiver-operated controls. Third-party lessors in Bangkok and Kuala Lumpur are building captive fleets for this emerging channel.
Hospitals command technology premium pricing. Long-term care facilities are climbing the fastest as demographic shifts reshape regional healthcare infrastructure.
Material:
Weight reduction imperatives in pediatric and mobile care segments are hybridizing traditional metal supply chains with aerospace composite processors.
- Metal:High-grade steel and aluminum alloys with powder-coated finishes for infection control. Dominates procurement volumes across Chinese and Indian hospital networks due to cost efficiency and established fabrication infrastructure.
- Composite:Carbon-fiber reinforced polymers reducing bed weight by thirty to forty percent without load capacity sacrifice. Japanese manufacturers are integrating these materials to meet METI JIS standards for medical electrical equipment.
- Plastic:Molded polymer components for railings, headboards, and control housings. Common in pediatric configurations where impact resistance and color customization matter.
- Wood:Laminated timber frames with antimicrobial finishes for hospice and residential aesthetics. Niche presence in Japan's premium home care segment.
Metal construction anchors volume production. Composite materials are gaining share fastest in pediatric and long-term care segments where cleaning protocols and weight reduction converge.
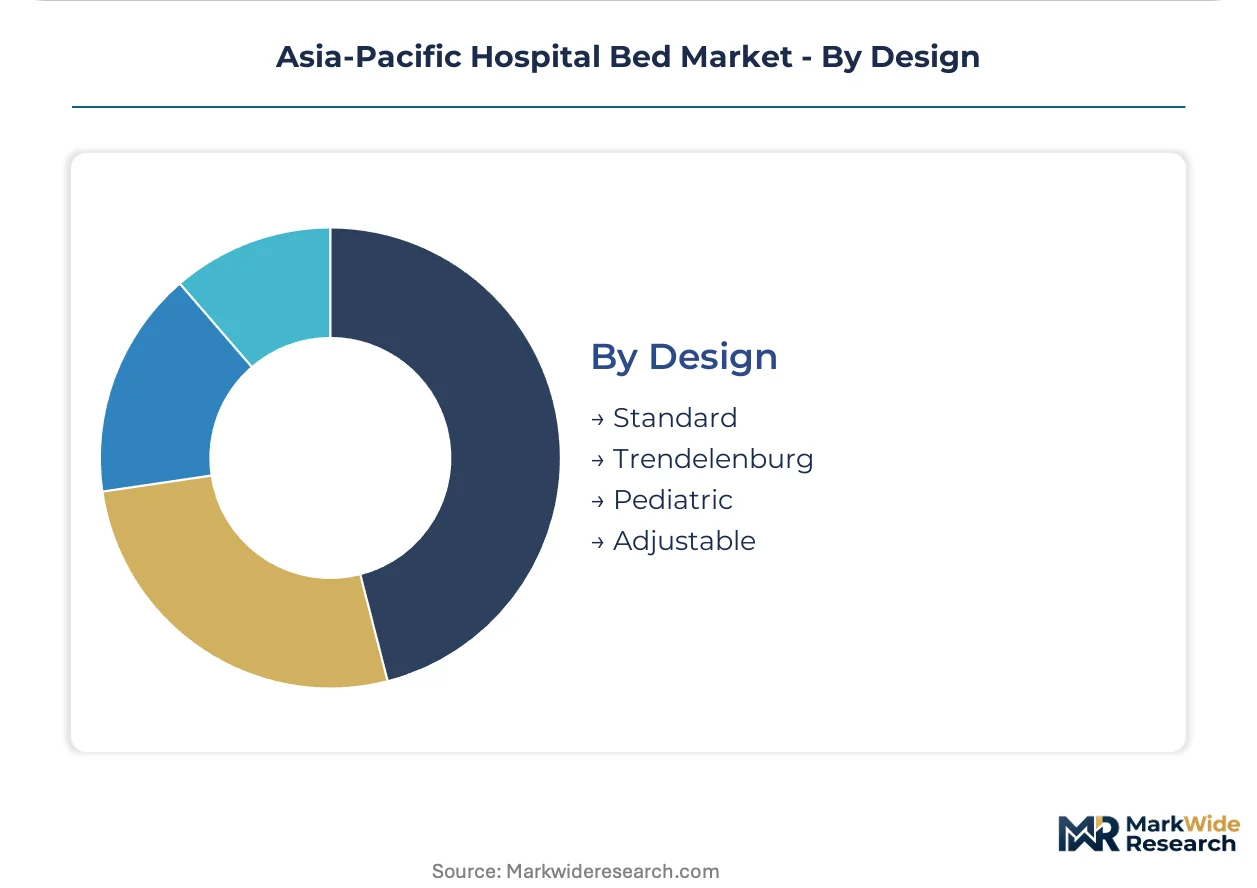
Design:
Functional specialization intensifies as care protocols differentiate positioning requirements across surgical, respiratory, and mobility-limited patient populations.
- Standard:Flat platform with basic height adjustment and fixed rail configurations. Baseline specification for general ward procurement in cost-constrained Indian and Indonesian facilities.
- Trendelenburg:Tilt-capable frames enabling head-down positioning for shock management and abdominal surgery. ICU-grade functionality now penetrating general ward specifications in Chinese tertiary hospitals.
- Pediatric:Scaled-down dimensions with side rail gaps meeting child safety standards and colorful composite finishes. Weight reduction priorities drive composite material adoption in this configuration.
- Adjustable:Multi-section articulation for cardiac chair, Fowler's, and lateral rotation positioning. Sensor-telemetry convergence is embedding load cells and patient monitoring modules into these platforms.
Standard designs retain volume dominance in emerging market procurement. Trendelenburg and adjustable configurations are expanding most quickly as ICU functionality migrates to general ward settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances across the Asia-Pacific hospital bed market are reshaping manufacturing footprints, with deficit economies accelerating domestic assembly while surplus markets consolidate sensor and actuator production clusters.
China
Tier-two city hospital infrastructure upgrades are replacing manual bed fleets with motorized systems to reduce nursing strain. NMPA certification under revised GB standards for bed-mounted electronics is driving compliance-driven procurement cycles. Jiangsu province hosts concentrated electric bed assembly operations serving provincial hospital tenders.
Japan
Domestic demand concentrates in ICU-grade smart-bed configurations with integrated sensor telemetry. METI enforces JIS T 0601-1 electromagnetic compatibility standards for medical electrical equipment. Osaka and Nagoya industrial clusters anchor critical sensor and control module production for regional supply.
India
PLI scheme incentives are accelerating domestic manufacturing of electric and semi-electric beds for tier-two and tier-three hospital networks. CDSCO mandates bed-side rail strength testing for all imported and domestically manufactured units. Gujarat and Maharashtra are emerging as assembly hubs for cost-optimized configurations.
Vietnam
Provincial hospitals in northern and central regions lack motorized bed density, creating first-mover opportunities for cost-optimized electric configurations. National infrastructure investment programs prioritize healthcare facility modernization. Ho Chi Minh City and Hanoi concentrate distributor networks and maintenance service capacity.
Thailand
Private hospital chains are adopting operating lease models for non-ICU bed categories, compressing ownership cycles. Third-party medical equipment lessors in Bangkok are building captive bed fleets. Bangkok metropolitan area dominates rental channel innovation and service infrastructure deployment.
Asia-Pacific Hospital Bed Market Vendor Landscape
On the supply side, the industry is bifurcating between asset-heavy integrated manufacturers and asset-light service providers. Japanese and European-origin players anchor premium-tier positioning through captive technology development. Chinese and Indian fabricators compete on cost-optimized electric configurations for provincial procurement. Strategic moves concentrate on backward integration into actuator supply and regional distribution network capture.
Among Japan-based manufacturers, Paramount Bed Holdings Co., Ltd. exemplifies deep vertical integration across manufacturing and regional distribution. Hill-Rom Holdings Inc. occupies a position within the premium-tier sensor-technology segment. Jiangsu Aegean Technology Co. Ltd. represents the cost-optimized electric configuration archetype competing for China's provincial tenders.
| Leading Market Players |
|---|
| Invacare Corporation |
| Funtech |
| Paramount Bed Holdings Co., Ltd. |
| Getinge AB |
| Guangdong Kareway Medical Technology Co. Ltd. |
| Hill-Rom Holdings Inc. |
| Jiangsu Aegean Technology Co. Ltd. |
| Mindray |
| Stryker Corporation |
| Others |
Supply Flow & Price Mechanics
Osaka and Nagoya industrial clusters anchor sensor and control module production for the Asia-Pacific hospital bed market, concentrating upstream pricing power among Japanese component suppliers while downstream assemblers in China and India face margin compression from actuator cost volatility.
Pricing Analysis
Provincial hospital procurement committees anchor pricing stratification across premium, standard, and economy tiers in the Asia-Pacific hospital bed market. Price differentiation hinges on NMPA certification grade for bed-mounted electronics and volume scale in tender participation, with CDSCO-mandated rail strength testing adding compliance premiums to Indian-bound configurations. Cost compression in mid-range electric beds intensifies as Jiangsu and Gujarat assembly operations expand domestic capacity. Rural clinic networks in Indonesia and Vietnam exhibit highest price sensitivity due to manual bed retention, while Tokyo and Osaka ICU-grade smart-bed buyers prioritize METI JIS T 0601-1 electromagnetic compatibility certification over unit cost.
Supply Chain Analysis
Contract manufacturing capacity concentrates in Jiangsu province electric bed assembly operations and Gujarat domestic manufacturing hubs serving PLI scheme incentives. Raw material dependencies draw from German-sourced linear actuators, high-grade steel from Chinese mills, and carbon-fiber reinforced polymers from Japanese aerospace composite processors. Single-source vulnerability clusters around Osaka-Nagoya sensor production, creating regional assembler exposure to JIS standard revision delays. Distribution runs through third-party medical equipment lessors in Bangkok and Kuala Lumpur building captive fleets, bypassing traditional distributor networks for provincial hospital access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific hospital bed market rewards players who control scarce biomedical technician training pipelines and captive actuator supply, as maintenance capacity constraints and component single-source vulnerability create defensive moats for integrated operators.
For Market Incumbents: Entrench position through backward integration into linear actuator supply and regional distribution network capture, countering emerging cost-optimized electric bed assemblers from Jiangsu and Gujarat. Prioritize METI JIS T 0601-1 electromagnetic compatibility certification investment to displace uncertified imports in Tokyo-Osaka ICU procurement. Expand captive biomedical technician training programs across Philippine and Indonesian hospital networks to lock in aftermarket service revenue. For New Entrants and Emerging Players: Northern and central Vietnam provincial hospitals present first-mover white-space for cost-optimized electric configurations, as motorized bed density remains below regional averages despite national infrastructure investment programs. Target Thailand's rental channel innovation through operating lease model partnerships with Bangkok-based third-party lessors, bypassing capital expenditure committee resistance in private hospital chains. Lead with sensor-telemetry convergence offerings that embed ICU-grade functionality into general ward specifications. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated manufacturers with captive component supply and regional distribution control over pure-play assemblers. Long-term viability across the projection horizon rests on backward integration depth and certification moat sustainability. Monitor CDSCO certification timeline compression and NMPA GB standards enforcement intensity as inflection indicators for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Actuator Supply | Captive linear actuator production reduces German-sourced component exposure and margin volatility. |
| METI JIS T 0601-1 Certification Investment | Electromagnetic compatibility shielding protocols create competitive moats in Tokyo-Osaka ICU procurement. |
| Biomedical Technician Training Programs | Maintenance capacity scarcity in Philippine and Indonesian networks locks in recurring service revenue streams. |
| Third-Party Lessor Partnership Development | Bangkok and Kuala Lumpur rental channel innovation bypasses traditional distributor networks for provincial access. |
| Sensor-Telemetry Platform Integration | Load cell and patient monitoring module embedding enables ICU-grade functionality migration to general ward settings. |
Methodological Framework
A standing panel of hospital procurement committee directors, biomedical engineers, GPO contracts managers, and third-party medical equipment lessors provided ongoing calibration across the study period. Primary interview inputs combined with secondary validation from NMPA certification databases, CDSCO approval records, METI JIS standard documentation, and hospital procurement tender archives. Bottom-up assembly capacity estimates from Jiangsu and Gujarat manufacturing hubs triangulated against top-down demand projections from Southeast Asian long-term care expansion programs and China's tier-two city infrastructure upgrade commitments.
Scenario-bracketing framed volume and value outputs across the projection horizon, modeling patient bed type, care setting intensity, material construction, and functional design specialization as core segmentation dimensions. CAGRs derived from replacement cycle compression analysis for sensor-equipped configurations versus manual bed retention patterns in archipelago geographies. Forecast inputs incorporated PLI scheme incentive intensity, NMPA GB standards revision compliance-driven procurement timing, and rental channel penetration rates in Thailand's private hospital sector.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Jiangsu cost-optimized assemblers or accelerated CDSCO certification timeline compression would shift outcomes beyond modeled ranges. Quarterly review of NMPA enforcement intensity, PLI scheme disbursement velocity, and Bangkok lessor fleet build rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Furniture
Hospital Beds Market
Medical Furniture
Global Chemotherapy Chairs Market
Medical Furniture
Healthcare Smart Beds Market
Medical Furniture
Electrical Hospital Beds Market
Medical Furniture
Europe Hospital Furniture Market
Medical Furniture
Hospital Furniture Market
Medical Furniture
Medical Bed Market
Medical Furniture
Global Stretcher Chairs Market
Medical Furniture
Asia-Pacific Hospital Furniture Market
Medical Furniture
Global Medical Furniture Market
Medical Furniture
Clinical Chairs Market
Medical Furniture
Global Automated Hospital Beds Market
Medical Furniture
Medical Walker Market
Medical Furniture
Medical Mattress Market
Medical Furniture
Medical Commodes Market
Medical Furniture
Medicine Cabinets Market