
 Electrical Hospital Beds Market | 2026-2036
Electrical Hospital Beds Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical Hospital Beds Market Analysis
Modular bed-platform configurations is hardening as the dominant procurement pattern, with buyers bundling mattress surfaces, side-rail systems, and nurse-call integration into single capital outlays. Stryker leverages its integrated operating-room ecosystem to cross-sell powered bed platforms into IDN consolidation deals. Linet Group anchors Central European tenders through localized assembly and rapid service response networks. Joerns Healthcare specializes in bariatric and wound-care configurations that differentiate its portfolio in post-acute channels.
An electrical hospital bed is a motorized patient support platform employing actuator-driven height adjustment, Trendelenburg positioning, and backrest articulation to enable clinical access and pressure redistribution. Units typically integrate DC motor arrays, control handsets, and optional scale systems for continuous patient weighing. Full electric models now lead replacement cycles in acute settings as labor-cost arithmetic favors powered adjustment over manual crank operations. Homecare demand for semi-electric configurations is expanding fastest among aging-in-place populations, though margin pools remain concentrated in specialty beds with integrated IT systems for fall-risk alerting and EMR connectivity.
The FDA enforces 510(k) premarket notification for powered hospital beds, while the EU Medical Device Regulation imposes stricter clinical evidence and post-market surveillance obligations than its predecessor directive. IEC 60601-2-52 establishes international safety benchmarks for bed rail entrapment and electrical isolation that manufacturers must satisfy for CE marking and FDA equivalence claims. Stakeholders should monitor how cybersecurity annexes to medical device standards reshape software update obligations and liability exposure for connected bed platforms.
Market Dynamics
Modular bed-platform configurations are hardening as the dominant procurement pattern, with buyers bundling mattress surfaces, side-rail systems, and nurse-call integration into single capital outlays. This shift compresses vendor margins while rewarding integrated-system suppliers capable of delivering unified platforms.
Growth Catalysts
- EU Medical Device Regulation:Tightened electrical safety and software validation requirements for powered patient support equipment are accelerating replacement cycles among risk-averse procurement committees.
- Japan's aging-population ward expansion:Hospital infrastructure modernization programs are creating concentrated demand for full-electric configurations with integrated fall-risk alerting systems.
- Actuator miniaturization:DC motor array density improvements are enabling lighter bed-platform designs that reduce shipping costs and installation labor for long-term care facilities.
Market Restraints
- Steel and copper input volatility:Bed-frame materials and motor windings face commodity price swings that compress manufacturing margins without corresponding pricing power.
- Control handset supplier concentration:Specialized electronics for medical-grade handsets concentrate among a limited set of qualified vendors, creating single-source vulnerabilities.
- IEC 60601-2-52 entrapment testing:Extended validation timelines for bed rail safety compliance delay product launches and freeze R&D budgets for 18-24 month cycles.
Strategic Opportunities
- Germany's hospital infrastructure modernization:Federal ward expansion programs are creating tender windows for EMR-integrated beds with continuous patient weighing capabilities.
- Homecare semi-electric configurations:Aging-in-place populations represent underpenetrated demand for powered height adjustment without full articulation features.
- Cybersecurity annex convergence:Software update obligations under evolving medical device standards are creating service-contract attach opportunities for connected bed platforms.
Industry Challenges
- Embedded systems engineering talent:Shortages of firmware developers with IEC 62304 medical software lifecycle experience delay control system upgrades.
- Legacy nurse-call protocol integration:Proprietary communication standards in installed hospital infrastructure force costly adapter development for new bed platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical Hospital Beds Market |
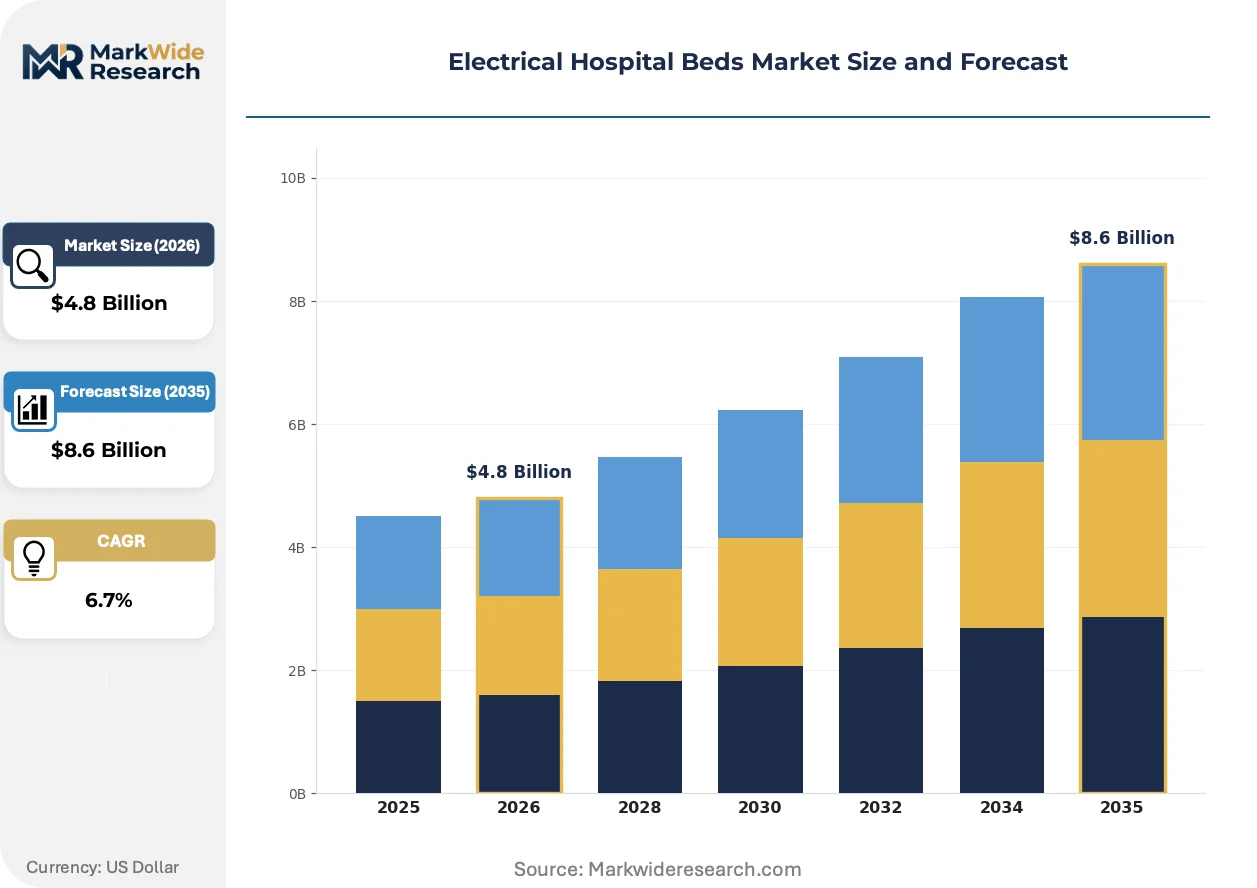
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Semi-Electric, Full Electric, Specialty End User: Hospitals, Homecare, Rehabilitation Centers, Long-Term Care Facilities Usage Type: Acute Care, Postoperative Care, Geriatric Care, Palliative Care Features: Adjustable Height, Trendelenburg Position, Pressure Relief, Integrated IT Systems |
| Companies Covered | Baxter (Hill-Rom), Stryker, Invacare, Arjo, Linet Group, Joerns Healthcare, GF Health Products, Medline, Span America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical Hospital Beds Market Emerging Trajectories
Software-defined functionality is displacing hardware-differentiated bed platforms across acute and post-acute settings. Vendors now compete through firmware update cadence and API ecosystem breadth rather than mechanical feature counts alone.
Sensor-integrated mattress surfaces are expanding into continuous pressure mapping and early-stage pressure injury detection. Long-term care facilities in Japan are adopting these systems at twice the rate of US counterparts. The technology is expanding into reimbursement-adjacent value propositions that justify premium procurement.
FDA 510(k) premarket notification pathways are tightening for powered hospital beds with software-controlled positioning algorithms. The industrial consequence is extended documentation requirements for clinical equivalence claims. Acute care segments in the United States are responding by front-loading regulatory consulting into product development budgets.
Integrated service contracts are displacing transactional equipment sales in integrated delivery network procurement. Capital-constrained hospitals in Germany are favoring multi-year agreements bundling hardware, maintenance, and software updates. This pattern is most visible among tertiary care centers consolidating vendor relationships under framework agreements.
Electrical Hospital Beds Market Segmentation
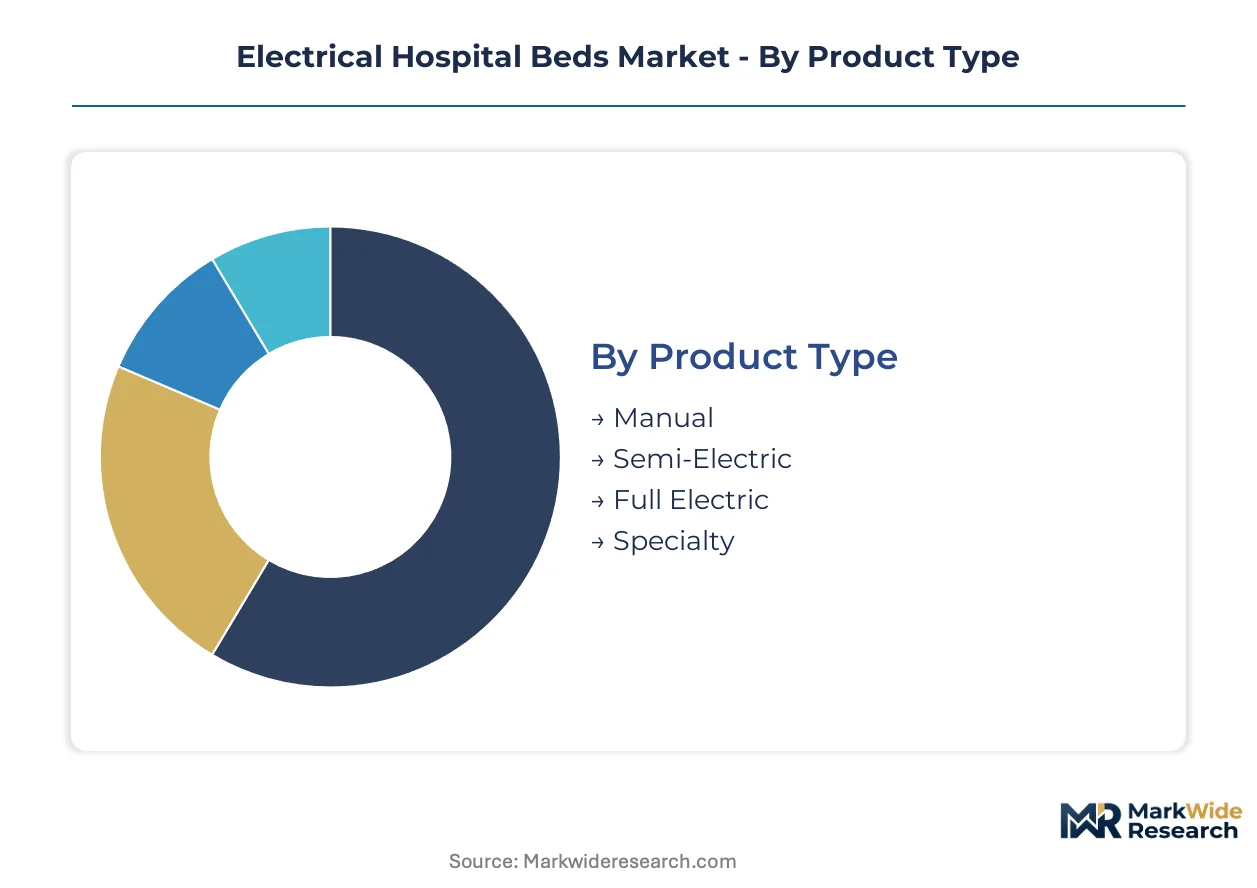
Electrical hospital bed procurement varies sharply by care setting and technical specification. Buyers evaluate motor configuration, integration depth, and feature bundles against labor-cost arithmetic and reimbursement frameworks. Segmentation reveals where margin pools concentrate versus where volume expansion occurs.
Product Type:
Standalone powered beds dominate acute settings where full articulation justifies capital outlay, while embedded configurations with modular add-ons expand in cost-constrained channels.
- Manual:Crank-operated height adjustment persists in budget-constrained long-term care facilities and emerging-market procurement. Demand concentrates in India and Southeast Asia where capital budgets limit electrification.
- Semi-Electric:Powered height adjustment with manual backrest and leg articulation. Homecare demand for this configuration is expanding fastest among aging-in-place populations in Germany and Japan, balancing functionality against caregiver assistance requirements.
- Full Electric:Complete DC motor arrays enabling height, backrest, leg, and Trendelenburg positioning through handset control. Acute care wards in the United States and Japan are replacing manual inventories with full-electric platforms to reduce nursing labor strain and satisfy IEC 60601-2-52 safety mandates.
- Specialty:Bariatric load ratings, integrated scale systems, and wound-care surfaces for specific clinical populations. Post-acute channels in the United States are driving procurement of bariatric configurations as obesity prevalence reshapes patient demographics.
Full Electric leads volumes today; Semi-Electric is gaining share fastest.
End User:
Procurement authority and reimbursement pathways determine feature bundling and service contract structures across customer types.
- Hospitals:Integrated delivery networks negotiate multi-year framework agreements bundling hardware, software, and maintenance. Tertiary centers in Germany and the United States are consolidating vendor relationships under EMR-integrated procurement specifications.
- Homecare:Semi-electric configurations with transport casters and battery backup. Japan's long-term care insurance expansion is accelerating homecare bed deployment faster than any other end-user channel.
- Rehabilitation Centers:Height-adjustable platforms with standing-assist compatibility and therapy rail configurations. Demand concentrates in post-stroke and orthopedic recovery protocols.
- Long-Term Care Facilities:Pressure-relief surfaces and fall-risk alerting systems bundled into capital cycles. EU Medical Device Regulation compliance is extending replacement timelines for these risk-averse buyers.
Hospitals command the largest revenue pool; Homecare exhibits the steepest expansion trajectory.
Usage Type:
Clinical workflow intensity dictates motor duty cycles, control system complexity, and IT integration requirements.
- Acute Care:High-frequency positioning demands with continuous patient weighing and nurse-call integration. ICU and step-down units in the United States require FDA 510(k) cleared platforms with software validation documentation.
- Postoperative Care:Trendelenburg and reverse-Trendelenburg positioning for cardiac and abdominal recovery. German hospital infrastructure modernization programs are specifying these capabilities in federal tender documents.
- Geriatric Care:Low-height positioning for fall prevention and easy patient egress. Japan's aging-population ward expansion is creating concentrated demand for beds with floor-level height ranges.
- Palliative Care:Quiet motor operation and pressure redistribution surfaces for comfort-focused protocols. Hospice facilities prioritize mattress integration over advanced positioning features.
Acute Care dominates installed base value; Geriatric Care is climbing the fastest.
Features:
Software-defined functionality is displacing hardware differentiation as vendors compete through firmware capabilities and API ecosystems.
- Adjustable Height:DC actuator arrays enabling vertical travel from floor-level to caregiver ergonomic access. This capability now serves as baseline specification rather than premium feature across all product tiers.
- Trendelenburg Position:Motorized tilt for hemodynamic management and surgical access. Cardiac care units in Germany and the United States require precise angle calibration with position feedback systems.
- Pressure Relief:Alternating air mattress surfaces and continuous pressure mapping sensors. Japanese long-term care facilities are adopting sensor-integrated surfaces at twice the rate of US counterparts.
- Integrated IT Systems:EMR connectivity, fall-risk alerting, and remote diagnostics through embedded cellular or Wi-Fi modules. Cybersecurity annexes to IEC 60601 standards are reshaping software update obligations for connected platforms.
Adjustable Height is universal baseline; Integrated IT Systems is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The electrical hospital bed industry traces its modern scale to post-war hospital construction programs in Germany and the United States, where powered patient platforms first displaced manual crank systems in acute care wards. Today procurement concentrates in aging economies with federal infrastructure commitments.
United States
Integrated delivery networks are consolidating vendor relationships under multi-year framework agreements bundling hardware and software maintenance. The FDA enforces 510(k) premarket notification for powered beds with software-controlled positioning algorithms. Tertiary care centers in Texas and California are specifying EMR-integrated platforms with continuous patient weighing capabilities.
Germany
Federal ward expansion programs are creating tender windows for full-electric configurations with Trendelenburg positioning and nurse-call integration. The EU Medical Device Regulation imposes stricter clinical evidence requirements than its predecessor directive. Manufacturing clusters in North Rhine-Westphalia are supplying Central European markets through localized assembly networks.
Japan
Long-term care insurance expansion is accelerating homecare bed deployment faster than any other end-user channel. METI hospital infrastructure modernization programs specify floor-level height ranges for fall prevention in geriatric wards. Medical device manufacturers in the Kanto region are shipping sensor-integrated mattress surfaces to domestic long-term care facilities.
United Kingdom
NHS capital budgets are favoring modular bed-platform configurations that bundle mattress surfaces and side-rail systems into single procurement outlays. The Medicines and Healthcare products Regulatory Agency enforces CE marking alignment with IEC 60601-2-52 safety benchmarks. Hospital trusts in Greater London are piloting connected bed platforms with remote diagnostics capabilities.
China
Provincial hospital construction programs are expanding demand for semi-electric configurations in secondary care facilities. NMPA medical device registration requirements are tightening for powered patient support equipment with embedded software. Domestic manufacturers in the Yangtze River Delta are scaling production of DC motor arrays for export markets.
Electrical Hospital Beds Market Vendor Landscape
Premium-margin players sit above commodity-margin players across integration depth and service contract attach rates. The vendor base organizes into three tiers: integrated-system suppliers capable of unified platform delivery, regional assemblers with rapid service response networks, and specialists in bariatric and wound-care configurations. Dominant competitive moves include framework agreement consolidation under integrated delivery networks and firmware update cadence differentiation for software-defined functionality.
Within the integrated-system tier, Stryker and Baxter (Hill-Rom) exemplify vendors leveraging cross-selling relationships into IDN consolidation deals. Linet Group occupies a position among Central European assemblers with localized production footprints. Joerns Healthcare represents the specialist archetype focused on post-acute channel differentiation.
| Leading Market Players |
|---|
| Baxter (Hill-Rom) |
| Stryker |
| Invacare |
| Arjo |
| Linet Group |
| Joerns Healthcare |
| GF Health Products |
| Medline |
| Span America |
| Others |
Supply Flow & Price Mechanics
EU Medical Device Regulation compliance mandates are forcing procurement committees toward pre-qualified integrated-system suppliers, compressing vendor margins while rewarding scale players capable of absorbing extended validation timelines and software documentation costs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with premium tiers commanded by FDA 510(k) cleared platforms with EMR connectivity, standard tiers populated by CE-marked full-electric configurations, and economy tiers served by semi-electric units for homecare. Price differentiation rests on certification grade and after-sales service bundling, with integrated delivery networks extracting volume discounts through multi-year framework agreements. Cost compression in the economy tier is intensifying because domestic manufacturers in China are scaling DC motor production for export markets. Long-term care facilities exhibit the highest price sensitivity due to capital budget constraints, while tertiary care centers in Germany and the United States demonstrate lowest sensitivity when EMR integration justifies premium outlays.
Supply Chain Analysis
Dual-sourcing requirements from risk-averse hospital procurement committees are fragmenting component orders across qualified vendors, particularly for control handset electronics and medical-grade actuators. Manufacturing concentrates in Germany, China, and the United States, with steel frame fabrication anchored in North Rhine-Westphalia, DC motor assembly scaling in the Yangtze River Delta, and final system integration distributed across Midwestern US industrial corridors. Raw material dependencies include cold-rolled steel for bed frames, copper windings for motor arrays, and specialized polymers for handset housings. Single-source vulnerability concentrates in medical-grade handset electronics, where qualified vendor pools remain narrow. Distribution runs through group purchasing organizations in the United States and federal tender frameworks in Germany, with direct-to-hospital contracts gaining share among integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electrical hospital bed market functions as a regulatory compounder, where EU Medical Device Regulation enforcement and FDA 510(k) pathway tightening continuously elevate compliance barriers that favor incumbents with established clinical evidence dossiers.
For Market Incumbents: Extend firmware update cadence as a competitive differentiator, leveraging software-defined functionality to lock in integrated delivery network relationships through recurring service revenue. Consolidate position by acquiring regional assemblers with localized CE marking expertise and rapid service networks in Central Europe. Vertical integration into DC motor production mitigates copper and steel input volatility threatening manufacturing margins.
For New Entrants and Emerging Players: Begin with homecare semi-electric configurations in Japan, where long-term care insurance expansion outpaces supplier capacity and procurement committees prioritize functionality over EMR integration. Target Germany's rehabilitation center segment, where standing-assist compatibility specifications remain underspecified in federal tenders. A direct-to-consumer channel with rental-subscription hybrid models bypasses GPO concentration in acute care.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing IEC 62304 compliant software stacks and established nurse-call protocol adapters. Long-term viability over a multi-year horizon favors vendors with recurring service contract attach rates above transactional equipment sales. Monitor FDA 510(k) clearance timelines for software-controlled positioning algorithms as an inflection indicator for competitive moat durability.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR compliance accelerates replacement cycles among risk-averse procurement committees in Germany. |
| Hospital System Partnership | Framework agreements with integrated delivery networks lock in multi-year revenue visibility in the United States. |
| Software Companion Development | API ecosystems for EMR connectivity differentiate platforms beyond mechanical feature specifications. |
| Reimbursement Strategy | Pressure injury prevention sensor integration unlocks value-based procurement in Japanese long-term care. |
| Backward Integration into Actuators | In-house DC motor production insulates margins from copper and steel commodity volatility. |
Methodological Framework
Direct dialogue with hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and long-term care facility administrators grounded this analysis, cross-referenced against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement registries, and CMS Medicare durable medical equipment claims data. Bottom-up triangulation validated manufacturer shipment data against top-down spending estimates from federal health infrastructure programs.
Bottom-up modeling of unit shipments across product type, end user, usage type, and feature configuration dimensions generated volume foundations, while top-down spending analysis from hospital capital budget disclosures anchored value estimates across the projection horizon. CAGRs derived from regression analysis of historical replacement cycle data and infrastructure modernization program announcements, with sensitivity testing against steel price indices and regulatory timeline scenarios.
Several conditions sit outside the modeled scope, including pandemic-era emergency procurement distortions, trade policy shifts affecting motor component tariffs, and cybersecurity incident impacts on connected bed platform adoption. Deviation in EU MDR enforcement intensity or FDA software validation guidance would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Furniture
Asia-Pacific Hospital Furniture Market
Medical Furniture
Medical Bed Market
Medical Furniture
Medical Walker Market
Medical Furniture
Clinical Chairs Market
Medical Furniture
Intensive Care Beds Market
Medical Furniture
Medical Mattress Market
Medical Furniture
Infusion Chair Market
Medical Furniture
Healthcare Smart Beds Market
Medical Furniture
Asia-Pacific Hospital Bed Market
Medical Furniture
Global Stretcher Chairs Market
Medical Furniture
Healthcare Flooring Market
Medical Furniture
Global Automated Hospital Beds Market
Medical Furniture
Hospital Bed Management Systems Market
Medical Furniture
Global Medical Furniture Market
Medical Furniture
Hospital Beds Market
Medical Furniture
Global Smart Hospital Bed Market