
 Global Medical Furniture Market | 2026-2036
Global Medical Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Furniture Market Foresight
Preventive maintenance subscriptions is realigning how hospitals evaluate total cost of ownership on capital equipment. Stryker leverages its service network to extend equipment lifecycle revenue beyond initial sales. Hill-Rom Holdings anchors its North American position through intensive R&D spending on sensor-integrated surfaces. Getinge competes in Europe by specializing in infection-control-compliant furnishings for surgical environments.
Medical furniture encompasses beds, tables, carts, cabinets, chairs, and trolleys engineered to specific load ratings, surface antimicrobial treatments, and ergonomic adjustability for clinical workflows. Stainless steel and high-density plastic compositions dominate where sterilization cycles and chemical resistance are mandatory. Patient beds command the largest revenue pool due to extended replacement cycles and integrated electronics, while treatment chairs represent the fastest-expanding category driven by ambulatory surgical center construction. Application demand tilts toward hospitals for volume but shifts toward elderly care facilities for growth as residential care models expand.
FDA device classification rules and the EU Medical Device Regulation (MDR) impose biocompatibility, electrical safety, and cybersecurity standards that filter market access and elevate compliance costs for entrants. ISO 13485 quality management certification functions as a baseline procurement filter across OECD healthcare systems. Stakeholders must monitor how CMS reimbursement shifts and EU Green Deal procurement criteria reshape specification priorities before committing to manufacturing footprints or distribution partnerships.
Market Dynamics
Hospital procurement departments are redefining vendor relationships through lifecycle cost models that embed predictive maintenance and remote diagnostics into furniture acquisition decisions.
Growth Catalysts
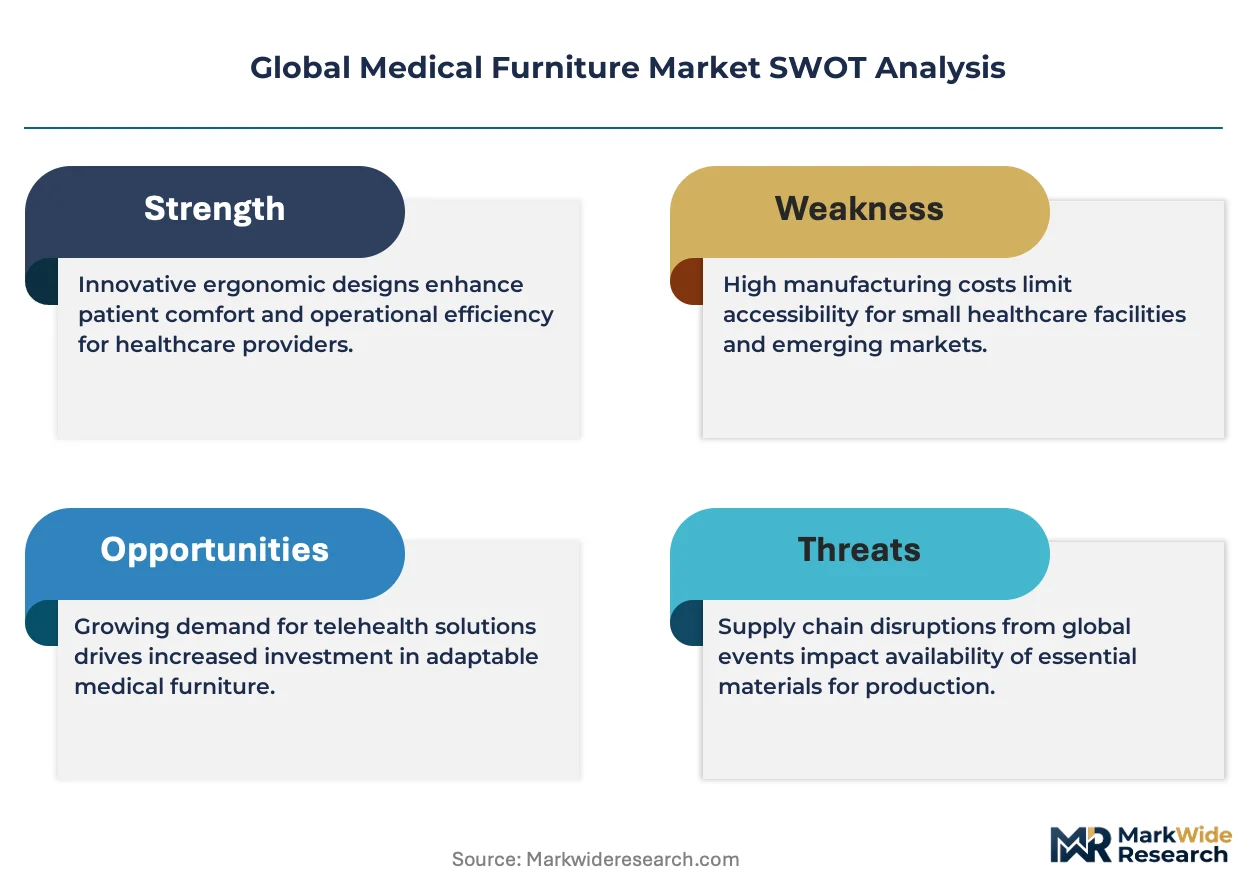
- EU Medical Device Regulation (MDR) compliance mandates:Biocompatibility and electrical safety certifications are filtering out low-cost competitors and elevating certified manufacturers' contract win rates in European tenders.
- Stainless steel sterilization compatibility:Surgical suites in tertiary hospitals are mandating corrosion-resistant surfaces that withstand accelerated autoclave cycles without degradation.
- Germany's hospital modernization programs:Federal infrastructure investments are replacing aging bed fleets with sensor-integrated platforms across university medical centers.
Market Restraints
- Chip and sensor supply concentration:Semiconductor shortages for pressure-sensing arrays are extending lead times for smart bed manufacturers dependent on East Asian foundries.
- EU Green Deal procurement criteria:Embodied carbon disclosure requirements are raising documentation burdens and disqualifying suppliers lacking verified lifecycle assessments.
- Antimicrobial coating raw material volatility:Silver nanoparticle and copper alloy prices fluctuate with mining output, compressing margins on infection-control surfaces.
Strategic Opportunities
- India's PLI scheme for medical devices:Production-linked incentives are attracting contract manufacturers to establish domestic assembly for export to Southeast Asian markets.
- Home-based elderly care transition:Japan's community-based long-term care insurance is funding residential-grade adjustable beds with clinical monitoring capabilities.
- AI-powered predictive maintenance convergence:Machine learning algorithms analyzing bed sensor data are enabling subscription-based uptime guarantees that displace traditional warranty models.
Industry Challenges
- Cybersecurity engineering talent scarcity:FDA's updated medical device cybersecurity guidance demands embedded security architects that furniture manufacturers struggle to recruit.
- ISO 13485 certification timeline compression:Quality management system audits are backlogged at notified bodies, delaying market entry for new product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Furniture Market |
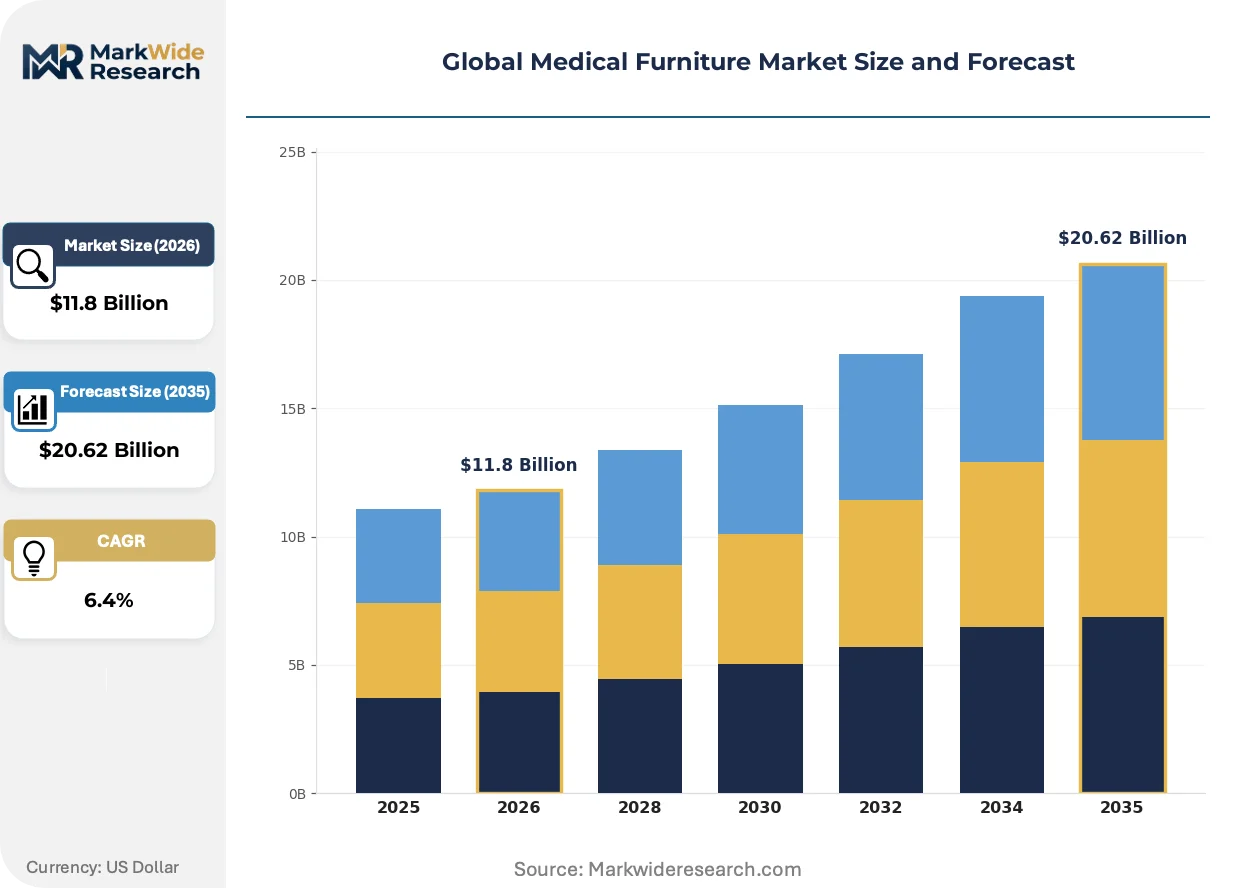
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patient Beds, Examination Tables, Surgical Carts, Medical Cabinets, Treatment Chairs, Instrument Trolleys Material: Stainless Steel, Aluminum, Wood, High-Density Plastic, Carbon Fiber, Composite Materials Application: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Rehabilitation Centers, Elderly Care Facilities, Specialty Clinics End User: Healthcare Providers, Nursing Homes, Research Institutes, Clinics, Outpatient Centers, Government Facilities |
| Companies Covered | Arjo, Invacare Corporation, Stryker, LINET Group SE, Baxter, Hill-Rom Holdings, Paramount Bed, Steris Corporation, Getinge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Furniture Market Shifts & Advancements
Sensor fusion and connectivity protocols are transforming static furniture into data infrastructure that feeds clinical decision support systems and operational dashboards.
Capacitive pressure mapping arrays are consolidating multiple discrete sensors into unified surface layers that detect patient position, movement, and pressure ulcer risk in real time. Acute care hospitals in the United States are adopting these platforms to reduce nursing documentation burden and automate turn protocols. The technology is consolidating previously separate monitoring devices into bed-integrated systems that compress capital expenditure and floor space requirements.
REACH chemical restrictions and RoHS substance limits are compelling manufacturers to reformulate surface coatings and electronic assemblies around halogen-free flame retardants and bisphenol-A-free plastics. Industrial consequence includes accelerated R&D cycles and supplier qualification costs that favor scaled producers with dedicated compliance teams. Surgical furniture categories face the steepest reformulation timelines as European tenders now mandate full material disclosure.
Subscription-based service agreements are displacing traditional capital purchase and break-fix maintenance models across North American health systems. Integrated delivery networks are consolidating vendor relationships into multi-year performance contracts that bundle equipment, software, and uptime guarantees. Kaiser Permanente and similar systems are piloting these arrangements for bed fleets, transferring obsolescence risk to manufacturers in exchange for guaranteed availability metrics.
Global Medical Furniture Market Segmentation
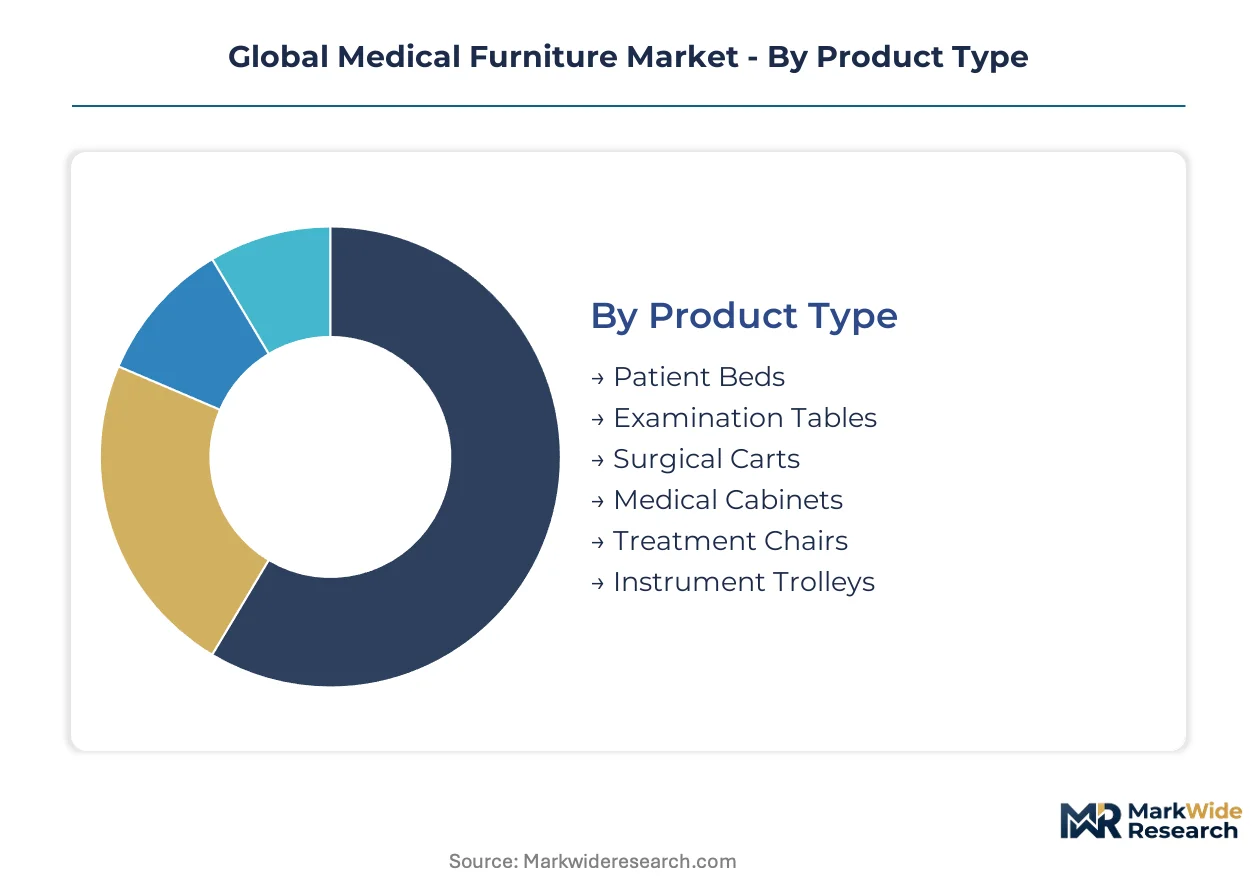
Medical furniture segmentation reveals how procurement priorities diverge across care settings, with integrated sensor platforms commanding premium positioning while basic furnishings compete on lifecycle cost. Understanding these tiered demand patterns enables manufacturers to align R&D investment and distribution channels with specific customer workflows.
Product Type:
Integration depth separates standalone furniture from platforms embedded with clinical monitoring infrastructure, reshaping how hospitals evaluate capital deployment.
- Patient Beds:These platforms integrate capacitive pressure mapping arrays, motorized articulation, and connectivity protocols that feed electronic health records. Demand concentrates in German university medical centers where federal modernization programs mandate sensor-integrated replacements. FDA cybersecurity guidance is forcing embedded security architectures that extend development cycles.
- Treatment Chairs:Motorized recline systems with bariatric load ratings and antimicrobial upholstery dominate ambulatory surgical center construction in the United States. The fastest expansion trajectory belongs to this segment as outpatient procedural volume shifts away from inpatient settings.
- Examination Tables:Fixed-height and adjustable models with paper roll dispensers and stirrup attachments serve primary care workflows.
- Surgical Carts:Stainless steel construction with corrosion-resistant casters supports sterile supply transport in tertiary operating suites.
- Medical Cabinets:Lockable storage with controlled substance compliance features anchors pharmacy and nursing station layouts.
- Instrument Trolleys:Lightweight aluminum frames with removable trays facilitate procedural equipment staging.
Volume placements concentrate in Patient Beds; the faster expansion belongs to Treatment Chairs.
Material:
Cost tier stratification separates premium corrosion-resistant alloys from commodity compositions, with sterilization cycle requirements dictating specification floors.
- Stainless Steel:Austenitic grades 304 and 316 withstand accelerated autoclave cycles and chemical disinfectants without surface degradation. German surgical suites mandate this specification for infection control compliance, while REACH substance restrictions are compelling European manufacturers to document alloy provenance.
- High-Density Plastic:Polypropylene and polyethylene formulations offer chemical resistance and reduced weight for mobile equipment categories. Demand is climbing fastest in Japanese elderly care facilities where residential-grade aesthetics must coexist with clinical cleanability.
- Aluminum:Anodized extrusions provide structural rigidity at reduced weight for transportable applications.
- Wood:Sealed hardwoods with antimicrobial finishes serve behavioral health and residential care environments.
- Carbon Fiber:Composite radiolucent structures enable imaging compatibility in orthopedic and interventional suites.
- Composite Materials:Glass-reinforced polymers balance durability with design flexibility for custom casework.
Specification floors rise fastest in Stainless Steel; cost-sensitive procurement favors High-Density Plastic.
Application:
Customer type segmentation maps how reimbursement structures and regulatory oversight intensity shape furniture performance requirements.
- Hospitals:Acute care facilities demand ISO 13485-certified platforms with predictive maintenance connectivity and cybersecurity hardening. CMS reimbursement shifts in the United States are pressuring capital committees to prioritize total cost of ownership over acquisition price.
- Elderly Care Facilities:Residential-grade adjustable beds with fall-risk monitoring and nurse call integration are expanding most quickly as Japan's community-based long-term care insurance funds home-equivalent environments.
- Ambulatory Surgical Centers:Same-day discharge protocols require rapid room turnover furniture with integrated equipment mounting.
- Diagnostic Laboratories:Chemical-resistant surfaces and ergonomic reach zones support high-volume specimen processing.
- Rehabilitation Centers:Bariatric-rated equipment with progressive mobility assistance features serves recovery protocols.
- Specialty Clinics:Procedure-specific configurations align with ophthalmology, dentistry, and dermatology workflows.
Contract value concentrates in Hospitals; the steepest volume climb occurs in Elderly Care Facilities.
End User:
Procurement authority segmentation distinguishes centralized health system purchasing from decentralized facility-level decision-making.
- Healthcare Providers:Integrated delivery networks in the United States are consolidating vendor relationships into multi-year performance contracts bundling equipment, software, and uptime guarantees. Kaiser Permanente pilots subscription models that transfer obsolescence risk to manufacturers.
- Government Facilities:Federal and state procurement in Germany follows EU Green Deal criteria requiring embodied carbon disclosure and verified lifecycle assessments, filtering supplier pools.
- Nursing Homes:Private and nonprofit operators balance regulatory compliance with resident dignity preferences.
- Research Institutes:Protocol-specific modifications and data integration requirements drive custom fabrication.
- Clinics:Independent practitioners prioritize rapid delivery and flexible financing over advanced feature sets.
- Outpatient Centers:Corporate ownership structures enable standardized fleet purchasing across multi-site networks.
Contract sophistication concentrates in Healthcare Providers; compliance burden intensity peaks in Government Facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European medical furniture manufacturing through its dense cluster of precision engineering firms supplying sensor-integrated bed platforms to university medical centers across Germany.
United States
Integrated delivery networks in California and Texas are consolidating vendor relationships into multi-year performance contracts bundling equipment, software, and uptime guarantees. FDA cybersecurity guidance for connected medical devices is forcing embedded security architectures that extend development cycles for domestic manufacturers. Kaiser Permanente pilots subscription-based bed fleet arrangements in the San Francisco Bay Area, transferring obsolescence risk to manufacturers in exchange for guaranteed availability metrics.
Germany
Federal hospital modernization programs are replacing aging bed fleets with sensor-integrated platforms across university medical centers in Berlin, Munich, and Hamburg. EU Medical Device Regulation compliance mandates are filtering out low-cost competitors and elevating certified manufacturers' contract win rates in European tenders. The Baden-Württemberg industrial corridor concentrates stainless steel surgical furniture production serving tertiary operating suites with corrosion-resistant specifications.
Japan
Community-based long-term care insurance is funding residential-grade adjustable beds with clinical monitoring capabilities for elderly care facilities in Tokyo, Osaka, and Nagoya. METI standards for connected healthcare devices are shaping procurement specifications for domestic manufacturers. The Kanto region around Tokyo hosts the densest concentration of treatment chair production serving ambulatory surgical center construction.
India
Production-linked incentive schemes for medical devices are attracting contract manufacturers to establish domestic assembly in Gujarat and Maharashtra for export to Southeast Asian markets. CDSCO quality management requirements are filtering supplier pools for government hospital tenders. The Pune industrial cluster is emerging as a hub for high-density plastic medical furniture serving cost-sensitive procurement segments.
China
NMPA medical device classification rules are elevating compliance costs for domestic and foreign manufacturers seeking market access. The Yangtze River Delta around Shanghai concentrates the largest assembly capacity for export-oriented medical furniture production. Dual carbon goals are pressuring manufacturers in Jiangsu and Zhejiang provinces to document embodied carbon for EU-bound shipments facing Green Deal procurement criteria.
Global Medical Furniture Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a tiered market structure where scale economies separate premium integrated platform vendors from commodity furniture fabricators. The vendor base stratifies into three archetypes: diversified healthcare conglomerates with full lifecycle service networks, specialized surgical environment specialists with infection-control expertise, and regional contract manufacturers competing on cost and customization velocity. Dominant competitive moves include vertical integration into sensor and connectivity component supply, and geographic expansion through production-linked incentive schemes in emerging manufacturing hubs.
Among diversified healthcare conglomerates, Stryker and Baxter exemplify the integrated service network archetype, anchoring premium positioning through lifecycle revenue models that extend beyond initial equipment sales. Hill-Rom Holdings occupies a position within the North American sensor-integrated surface segment, while Getinge sits within the European surgical environment specialization tier. LINET Group SE represents the mid-scale integrated platform vendor archetype competing across multiple regional markets.
| Leading Market Players |
|---|
| Arjo |
| Invacare Corporation |
| Stryker |
| LINET Group SE |
| Baxter |
| Hill-Rom Holdings |
| Paramount Bed |
| Steris Corporation |
| Getinge |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between ISO 13485-certified smart platforms and uncertified commodity furnishings splits pricing power and sourcing geography simultaneously. Premium sensor-integrated beds command lifecycle service bundles while basic stainless steel cabinets compete on landed cost from contract manufacturers.
Pricing Analysis
Margin tightening in commodity-grade furnishings reflects raw material volatility and REACH compliance documentation burdens. Three-tier pricing structure across premium, standard, and economy levels differentiates by cybersecurity hardening depth and predictive maintenance bundling. Price differentiation hinges on FDA cybersecurity tier certification and geographic delivery cost from East Asian foundries. Ambulatory surgical centers exhibit highest price sensitivity; integrated delivery networks prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
India's PLI scheme and China's dual carbon goals are reshaping component sourcing toward Gujarat and Maharashtra assembly hubs. Semiconductor pressure-sensing arrays draw from Taiwan and South Korea; stainless steel feedstock rests on German and Chinese mill capacity. Single-source vulnerability concentrates in East Asian foundry supply for capacitive sensor arrays. Distribution runs through regional GPO contracts and direct hospital system partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 13485 audit backlogs at notified bodies constrain certified manufacturing capacity, propping pricing for qualified suppliers across European tenders.
For Market Incumbents: To counter cybersecurity engineering talent scarcity, Stryker and Baxter should deepen captive supply of embedded security architectures through targeted R&D hiring in Berlin and Boston clusters. Backward integration into pressure-sensor component supply secures allocation priority during semiconductor shortages. For New Entrants and Emerging Players: Launch via India's PLI scheme contract manufacturing model to serve Southeast Asian export demand with cost-advantaged high-density plastic furnishings. White-space targets include Japan's community-based long-term care insurance-funded residential beds and German university medical center modernization tenders requiring EU MDR certification. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale integrated platform vendors given federal hospital modernization program acceleration across Germany and the United States. Long-term viability favors archetypes with established ISO 13485 certification and predictive maintenance subscription revenue. Monitor FDA cybersecurity guidance enforcement intensity as inflection signal for compliance cost barriers.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance unlocks German federal modernization program contract access. |
| Hospital System Partnership | Kaiser Permanente-style performance contracts transfer obsolescence risk to manufacturers. |
| Software Companion Development | AI-powered predictive maintenance algorithms enable subscription-based uptime guarantees. |
| Backward Integration | Captive pressure-sensor production insulates against East Asian foundry allocation constraints. |
| Reimbursement Strategy | CMS total cost of ownership alignment secures integrated delivery network vendor consolidation. |
Research Methodology
Independent corroboration across hospital procurement committee interviews, biomedical engineer surveys, and GPO contracts database analysis underwrites the qualitative findings. Primary fieldwork engaged hospital purchasing directors, biomedical engineering leads, GPO contracts managers, and regulatory affairs specialists at FDA-registered manufacturers. Secondary validation drew from FDA 510(k) filings, EU MDR notified body audit records, CMS Medicare cost report data, and German federal hospital modernization program tender documents. Bottom-up equipment shipment modeling triangulates against top-down healthcare capital expenditure estimates.
Rate-of-change decomposition across product type, material specification, application setting, and procurement authority dimensions structures the analytical framework. Volume and value outputs anchor in shipment data, tender award tracking, and installed base replacement cycle analysis across the projection horizon. CAGRs derive from segment-level growth rate reconciliation against macro healthcare expenditure trends. Industry-specific forecast inputs include semiconductor lead time indices and EU Green Deal embodied carbon disclosure adoption curves.
Semiconductor supply disruption, EU MDR audit backlog extension, and CMS reimbursement policy recalibration are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about hospital modernization program continuity and cybersecurity regulatory enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Furniture
Medical Walker Market
Medical Furniture
Global Automated Hospital Beds Market
Medical Furniture
Infusion Chair Market
Medical Furniture
Asia-Pacific Hospital Bed Market
Medical Furniture
Hospital Bed Management Systems Market
Medical Furniture
North America Hospital Furniture Market
Medical Furniture
Europe Hospital Furniture Market
Medical Furniture
Global Smart Hospital Bed Market
Medical Furniture
Global Chemotherapy Chairs Market
Medical Furniture
Electrical Hospital Beds Market
Medical Furniture
Medical Bed Market
Medical Furniture
Healthcare Flooring Market
Medical Furniture
Medical Mattress Market
Medical Furniture
Intensive Care Beds Market
Medical Furniture
Asia-Pacific Hospital Furniture Market
Medical Furniture
Hospital Beds Market