
 Hospital Beds Market | 2026-2036
Hospital Beds Market Size, Share, and Industry Trends Forecast 2026-2036
Hospital Beds Market Intelligence
European medical device manufacturers are shifting production capacity toward electrically actuated platforms. Stryker Corporation leverages its integrated stretcher-to-bed workflow systems to sustain premium positioning in North American acute care networks. LINET Group SE anchors Central European supply through vertically controlled actuator manufacturing in the Czech Republic. Paramount Bed Co. Ltd. dominates Japanese domestic procurement via JIS-certified long-term care configurations.
A hospital bed is a height-adjustable patient support platform incorporating electric or manual actuation, side rails, and castor-based mobility, typically engineered with steel or aluminum frames and antimicrobial-coated surfaces to enable therapeutic positioning and infection control. Fully electric beds command the highest value per unit due to embedded motor systems and programmable Trendelenburg functions, while bariatric segments extract premium pricing from reinforced frame specifications. Critical care applications drive replacement cycles fastest because ICU protocols mandate continuous cardiac positioning capabilities and integrated weighing systems.
FDA 510(k) premarket notification governs powered bed safety interlocks and entrapment prevention in the United States, while the EU Medical Device Regulation mandates clinical evaluation and post-market surveillance for CE-marked beds sold across member states. Japan's PMDA enforces electrical safety testing under METI-administered standards for hospital-grade equipment. Stakeholders must monitor evolving entrapment zone guidelines and battery backup requirements as regulators tighten patient safety specifications without grandfathering existing installed bases.
Market Dynamics
Electrification of patient support platforms is compressing replacement cycles across acute care networks as hospitals prioritize programmable positioning and integrated weighing capabilities over legacy manual frames.
Growth Catalysts
- EU Medical Device Regulation (MDR):CE-marking requirements for clinical evaluation and post-market surveillance are accelerating hospital fleet upgrades to compliant electric platforms across member states.
- Long-term care facilities:Aging demographics in Japan and Germany are expanding bed procurement for JIS-certified and DIN-standard configurations respectively.
- Powered adjustable actuation:Embedded motor systems with Trendelenburg positioning are displacing semi-electric units in critical care protocols.
Market Restraints
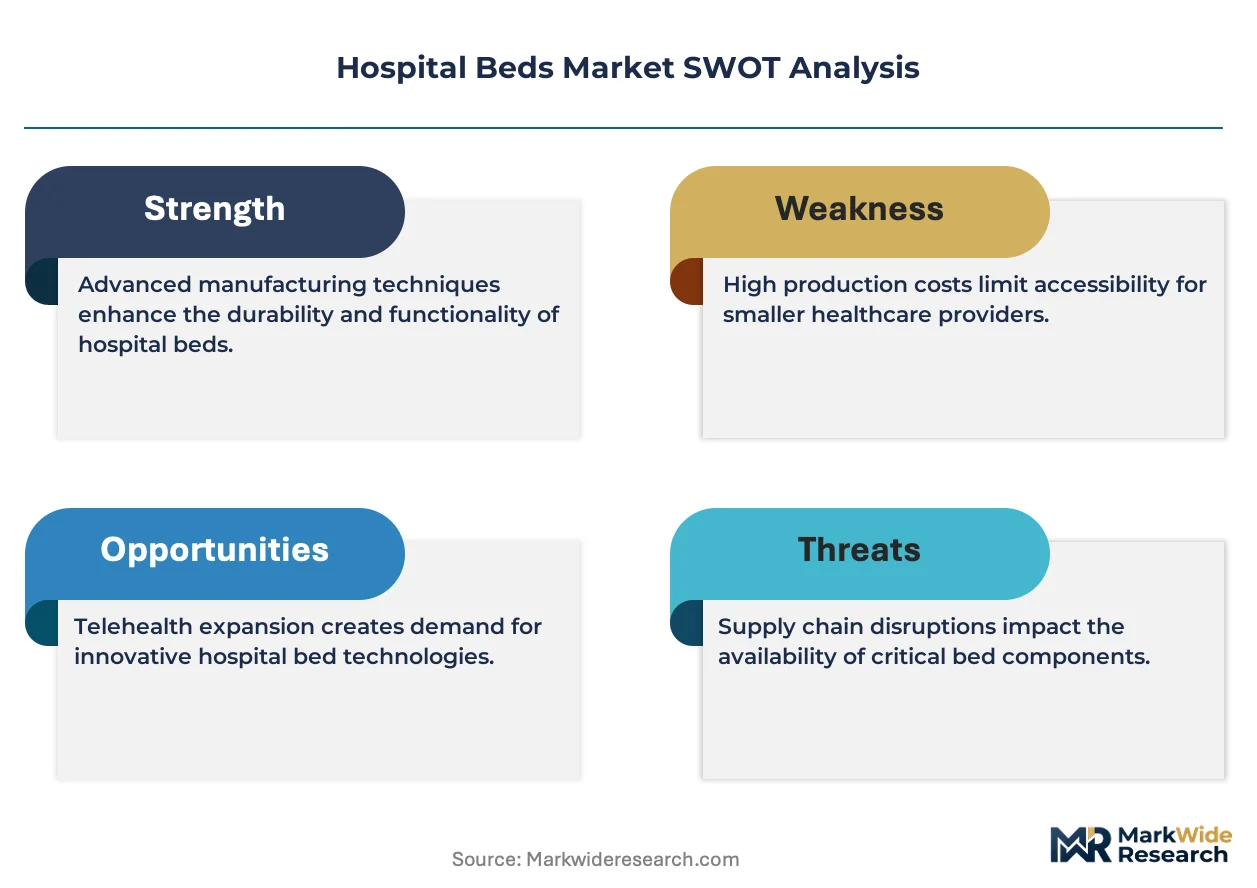
- Steel and aluminum input volatility:Frame material costs fluctuate with commodity indexes, pressuring margin structures for mid-tier manufacturers without captive metal sourcing.
- Actuator supply concentration:Central European component manufacturing creates geographic dependency for electric bed assembly operations.
- Antimicrobial coating technical limitations:Surface treatment durability under repeated disinfection cycles constrains product lifecycle claims.
Strategic Opportunities
- Home-based acute care:Post-discharge monitoring protocols in the United States are creating demand for residential-grade electric beds with hospital-equivalent positioning.
- FDA 510(k) pathway acceleration:Streamlined premarket notification for powered safety interlocks enables faster product introductions versus full PMA routes.
- Battery backup convergence:Integration of uninterruptible power systems with wireless connectivity protocols addresses emergency preparedness mandates.
Industry Challenges
- Biomedical technician certification gaps:Electric bed maintenance requires specialized training in motor diagnostics and software calibration that acute care networks struggle to staff.
- Legacy system integration friction:New electric platforms must interface with existing nurse call systems and electronic health record architectures without full infrastructure replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospital Beds Market |
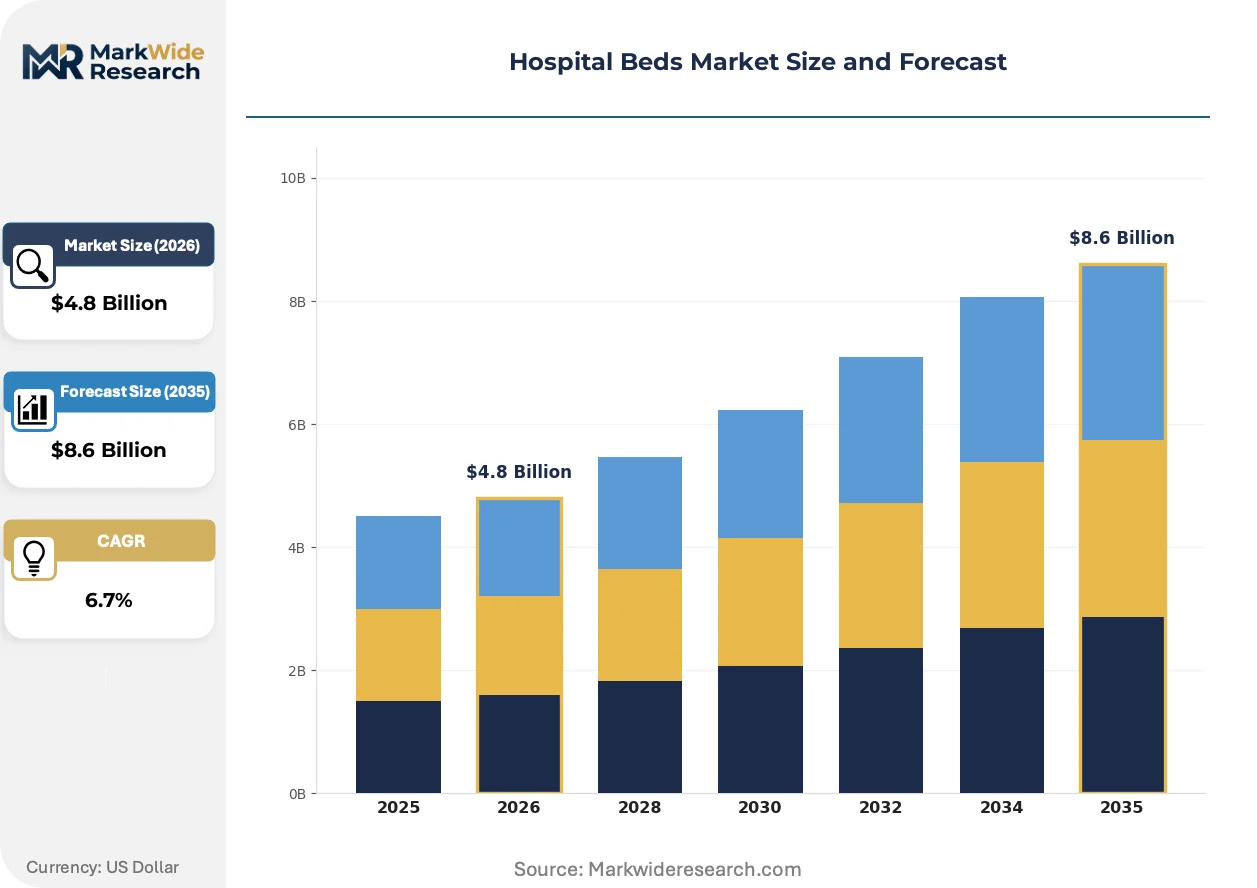
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Beds, Semi-Electric Beds, Fully Electric Beds, Pediatric Beds, Bariatric Beds Application: Critical Care, Maternity, Geriatrics, Surgical, Rehabilitation End User: General Hospitals, Specialty Clinics, Nursing Homes, Diagnostic Centers Distribution Channel: Direct Sales, Medical Equipment Distributors, Online Platforms, Tender Supply |
| Companies Covered | Baxter International, Stryker Corporation, Invacare Corporation, Paramount Bed Co. Ltd., Arjo, LINET Group SE, Medline Industries Inc., Drive DeVilbiss Healthcare, Stiegelmeyer GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospital Beds Market Strategic Shifts & Innovations
Digital connectivity and predictive maintenance capabilities are embedding intelligence directly into bed platforms, transforming capital equipment into data-generating nodes within hospital operational systems.
Wireless patient monitoring integration is expanding into standard bed configurations. ICU departments in German university hospitals are deploying sensor-embedded platforms that transmit continuous weight and position data to central nursing stations. This convergence is expanding into mid-tier acute care units that previously relied on standalone monitoring devices.
Japan's PMDA has tightened electrical safety testing protocols under METI-administered standards for hospital-grade equipment. Manufacturers must now demonstrate compliance with updated grounding and leakage current specifications before market authorization. Domestic producers are responding by vertically controlling testing laboratory relationships to compress certification timelines.
Hospital procurement departments are unbundling after-sales service contracts from initial equipment purchases. Large integrated delivery networks in the United States are negotiating separate multi-year maintenance agreements with third-party biomedical service firms rather than accepting manufacturer-captive service bundles. This shift is most pronounced among nonprofit hospital systems seeking operational expenditure flexibility.
Hospital Beds Market Segmentation
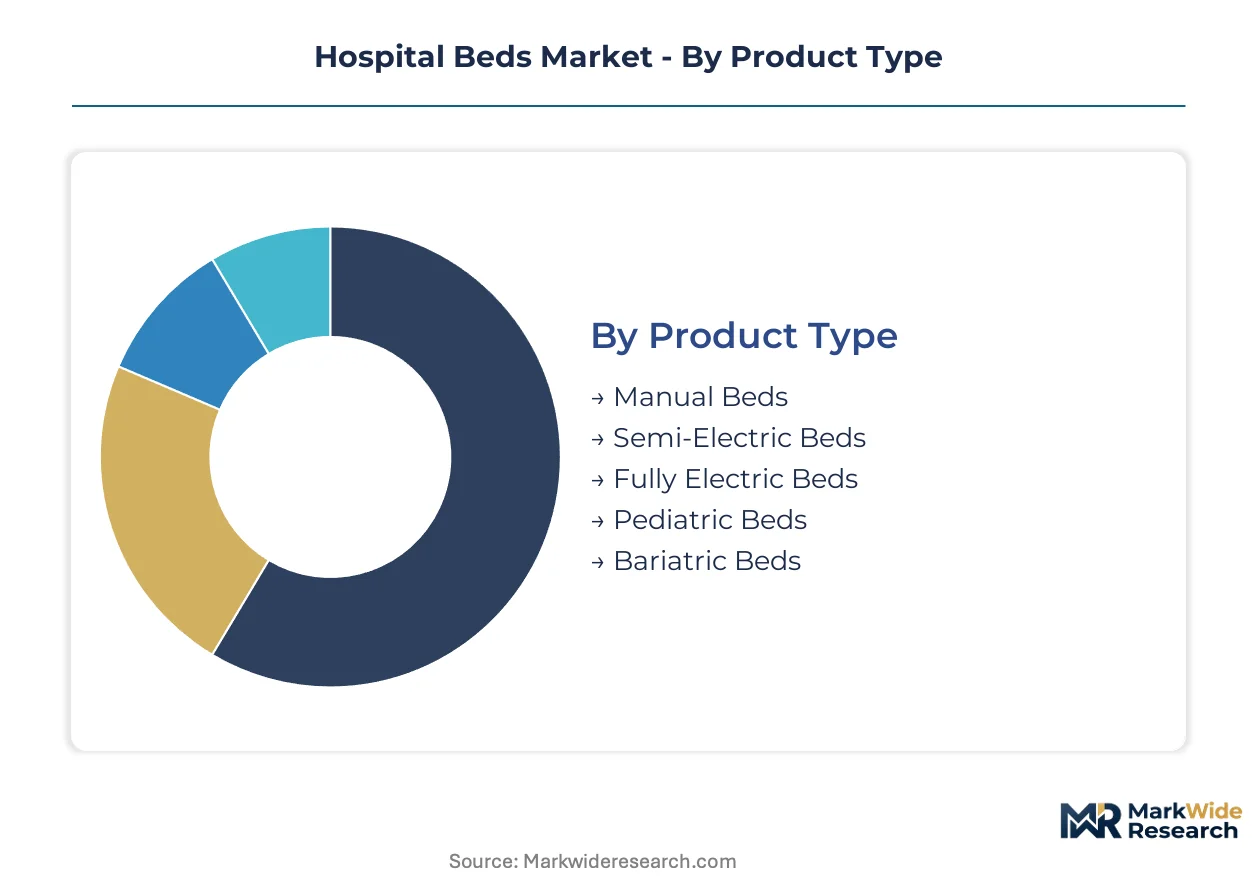
Hospital bed procurement varies sharply by care setting and technical specification, with electric actuation and patient weight capacity driving unit economics. Segmentation reveals how acute care networks prioritize programmable positioning while long-term facilities balance acquisition cost against maintenance burden.
Product Type:
Integration depth separates standalone manual platforms from embedded motor systems with nurse call connectivity and predictive maintenance capability.
- Fully Electric Beds:Embedded motor arrays enable programmable Trendelenburg positioning, integrated weighing scales, and wireless data transmission to central monitoring stations. German university hospitals and Japanese long-term care networks are standardizing on these platforms for ICU protocols and aging population management respectively.
- Bariatric Beds:Reinforced steel or aluminum frames support patient weights exceeding standard specifications, with wider deck surfaces and enhanced caster systems. Demand concentrates in US acute care networks addressing obesity prevalence, with premium pricing reflecting specialized actuator torque requirements and extended warranty terms.
- Semi-Electric Beds:Electric height adjustment paired with manual head and foot section positioning.
- Manual Beds:Hand-crank actuation without motor systems, common in resource-constrained procurement environments.
- Pediatric Beds:Scaled dimensions with side rail configurations optimized for neonatal and adolescent safety standards.
Fully electric beds lead volumes today; bariatric configurations are gaining share fastest.
Application:
Cost tier stratification places cardiac monitoring and surgical positioning at premium price points while rehabilitation applications accept simpler mechanical specifications.
- Critical Care:Continuous cardiac positioning capabilities, integrated weighing systems, and pressure redistribution surfaces define ICU-grade platforms. Replacement cycles compress fastest here as protocols mandate embedded sensor arrays and battery backup systems for emergency preparedness.
- Geriatrics:Low-height positioning for fall prevention and pressure ulcer management dominates long-term care procurement. Japanese JIS-certified configurations and German DIN-standard platforms anchor regional demand as aging demographics expand bed fleet requirements.
- Surgical:Radiolucent deck materials and C-arm compatibility for intraoperative imaging.
- Maternity:Trendelenburg and reverse Trendelenburg positioning for obstetric emergencies.
- Rehabilitation:Simplified electric actuation focused on patient mobility training and early ambulation support.
Critical care commands premium pricing; geriatric applications show steepest expansion trajectory.
End User:
Customer type determines procurement sophistication, with integrated delivery networks negotiating multi-year service unbundling while standalone facilities accept manufacturer-captive bundles.
- General Hospitals:Acute care networks with centralized biomedical engineering departments prioritize electric platforms with predictive maintenance capability and EHR integration. US nonprofit systems and German university hospitals drive fleet standardization around embedded connectivity protocols.
- Nursing Homes:Long-term care operators balance acquisition cost against 10-year operational lifespan, favoring semi-electric units with durable antimicrobial coatings. Japanese domestic producers dominate via JIS-certified configurations tailored to METI-administered electrical safety standards.
- Specialty Clinics:Focused procedure volumes with procedure-specific positioning requirements.
- Diagnostic Centers:Limited bed deployment for patient preparation and recovery.
General hospitals lead absolute volumes; nursing homes are expanding procurement most quickly.
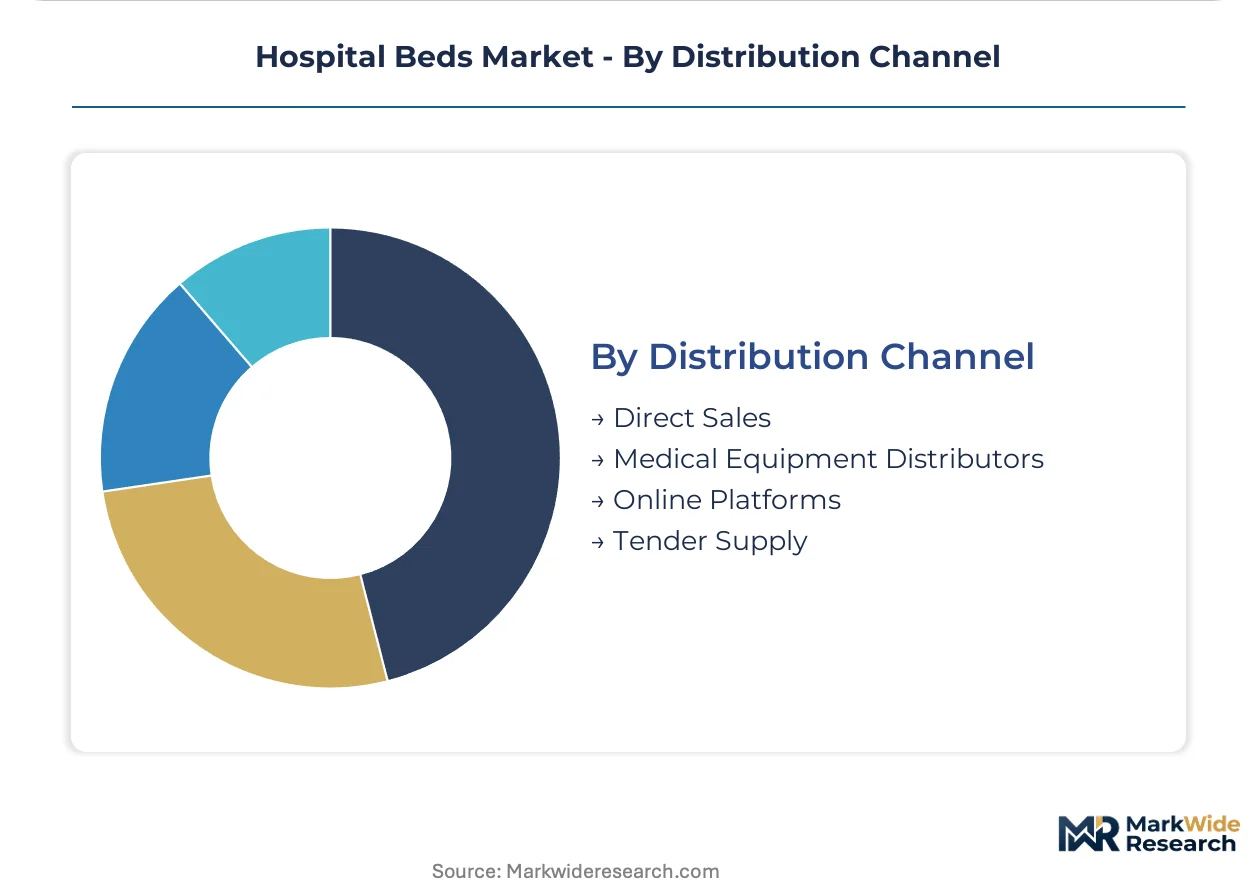
Distribution Channel:
Supply concentration in Central European actuator manufacturing shapes channel economics, with direct sales capturing complex integrated contracts.
- Direct Sales:Manufacturer-led contracting for large integrated delivery networks with customized fleet configurations and unbundled service agreements. Stryker Corporation and LINET Group SE deploy dedicated account teams for North American and Central European hospital systems respectively.
- Medical Equipment Distributors:Regional inventory holding and installation capability for mid-tier acute care and long-term care facilities without specialized procurement staff.
- Tender Supply:Government and nonprofit hospital system competitive bidding with specification compliance weighting.
- Online Platforms:Limited to replacement parts and accessories rather than complete bed systems.
Direct sales leads contract value; medical equipment distributors handle greatest transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting electric bed assembly toward jurisdictions with streamlined premarket pathways. Manufacturers locate certification laboratories and final integration facilities where electrical safety testing costs compress marginally against EU MDR compliance burdens.
United States
Acute care networks in Texas and Florida are standardizing fleet procurement around FDA 510(k)-cleared platforms with embedded connectivity. The FDA's streamlined premarket notification for powered safety interlocks accelerates product introductions versus full PMA routes. Stryker Corporation anchors Michigan-based manufacturing for integrated stretcher-to-bed workflow systems serving nonprofit hospital systems.
Germany
University hospitals in Bavaria and North Rhine-Westphalia prioritize DIN-standard electric configurations with predictive maintenance capability. The EU Medical Device Regulation mandates clinical evaluation and post-market surveillance for CE-marked beds across member states. LINET Group SE controls vertically integrated actuator manufacturing in the Czech Republic to supply Central European demand.
Japan
Long-term care operators in Kanto and Kansai regions are expanding JIS-certified bed fleets for aging population management. METI-administered electrical safety standards enforced by PMDA require updated grounding and leakage current demonstrations. Paramount Bed Co. Ltd. dominates domestic procurement through captive testing laboratory relationships that compress authorization timelines.
China
Hospital infrastructure modernization in Shanghai and Beijing is driving replacement of manual frames with programmable electric platforms. NMPA medical device registration requires electrical safety documentation for powered patient support equipment. Domestic producers are consolidating assembly capacity in Yangtze River Delta clusters to capture public hospital tender volumes.
United Kingdom
Integrated care systems in London and the Midlands are unbundling service contracts from equipment purchases for operational expenditure flexibility. MHRA post-Brexit regulatory alignment with EU MDR technical standards maintains CE-marking equivalence for market access. NHS Supply Chain central procurement is weighting specification compliance over manufacturer-captive maintenance bundles.
Hospital Beds Market Key Industry Players
North American producers anchor one tier; Central European specialists hold differentiated positioning through component manufacturing control. The vendor base concentrates around integrated acute care workflow providers and regional long-term care configurators. Two strategic archetypes dominate: vertically integrated platform manufacturers with captive actuator supply, and service-unbundled distributors targeting mid-tier procurement. Competitive moves center on M&A for connectivity technology access and geographic expansion into home-based acute care segments.
Among US-based fabricators, Stryker Corporation and Invacare Corporation exemplify divergent positioning archetypes. Stryker represents the integrated workflow tier with stretcher-to-bed system continuity, while Invacare occupies a position within residential-grade electric configurations. German GmbH-structured Stiegelmeyer GmbH & Co. KG anchors Central European engineering traditions. These three entities collectively illustrate how geographic origin and corporate structure map to distinct customer segments without overlapping capability claims.
| Leading Market Players |
|---|
| Baxter International |
| Stryker Corporation |
| Invacare Corporation |
| Paramount Bed Co. Ltd. |
| Arjo |
| LINET Group SE |
| Medline Industries Inc. |
| Drive DeVilbiss Healthcare |
| Stiegelmeyer GmbH & Co. KG |
| Others |
Cost & Logistics Intelligence
EU Medical Device Regulation (MDR) compliance gates qualified supply and premium-tier pricing access for electric bed manufacturers serving member states. Hospitals demand CE-marked platforms with embedded actuator systems and predictive maintenance capability, compressing margins for mid-tier producers lacking captive component sourcing.
Pricing Analysis
Distributor margins absorb 15-25 percent of manufacturer list prices for mid-tier acute care facilities without direct procurement teams. Three-tier pricing structure across premium, standard, and economy levels separates fully electric ICU platforms with integrated weighing from semi-electric rehabilitation units and manual frames for resource-constrained settings. Pricing pressure stems from steel and aluminum commodity volatility pressuring frame material costs. Nursing homes exhibit highest price sensitivity due to 10-year operational lifespan planning, while German university hospitals prioritize specification compliance over acquisition cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from integrated delivery networks in Texas, Florida, and Michigan. Electric bed assembly draws from Czech Republic actuator manufacturing, Chinese steel frame fabrication, and German control system engineering. Raw material dependencies center on cold-rolled steel, aluminum extrusions, and precision motor windings. Single-source vulnerability in Central European component manufacturing creates geographic concentration risk. Distribution runs through manufacturer account teams for large hospital systems and regional medical equipment distributors for standalone facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Hospital Beds Market functions as a regulatory compounder where FDA 510(k) clearance acceleration and EU MDR compliance deadlines are compressing replacement cycles and expanding qualified supplier rosters.
For Market Incumbents: Deepen backward integration into actuator manufacturing to defend margin position against commodity volatility and supply concentration risk. Secure captive testing laboratory relationships to compress FDA and PMDA authorization timelines. Prioritize software companion development for predictive maintenance platforms that lock in multi-year service contracts with integrated delivery networks. For New Entrants and Emerging Players: Enter via home-based acute care segments where post-discharge monitoring protocols in the United States are creating demand for residential-grade electric beds with hospital-equivalent positioning. Target third-party biomedical service firms that are capturing unbundled maintenance contracts from nonprofit hospital systems. Deploy direct-to-consumer digital channels to bypass established distributor relationships in long-term care procurement. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier manufacturers with semi-electric product portfolios facing displacement by fully electric platforms. Long-term viability hinges on connectivity technology access and geographic expansion into Japanese JIS-certified or German DIN-standard procurement channels. Monitor battery backup convergence with wireless protocols as the inflection indicator for emergency preparedness mandate compliance.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evaluation requirements accelerate fleet upgrades across member states. |
| Hospital System Partnership | Integrated delivery network standardization locks in multi-year fleet procurement commitments. |
| Software Companion Development | Predictive maintenance platforms transform capital equipment into recurring revenue streams. |
| FDA Submission | 510(k) premarket notification streamlines powered safety interlock introductions versus PMA routes. |
| Reimbursement Strategy | Coding alignment with home-based acute care protocols expands addressable patient populations. |
Research Approach
Bottom-up hospital procurement modeling reconciled against top-down actuator manufacturing tracking forms the analytical core of this study. Primary interviews with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and long-term care procurement officers combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, hospital capital expenditure records, and medical device customs data. Triangulation across these sources ensures segment-level accuracy.
Input-output matrices map electric bed unit economics across product type, application, and end-user dimensions over the projection horizon. Segmentation modeling incorporates fully electric versus semi-electric versus manual platform splits, critical care versus geriatric versus surgical application tiers, and general hospital versus nursing home versus specialty clinic customer archetypes. CAGRs derive from replacement cycle compression rates and infrastructure modernization program commitments. Forecast inputs include aging demographic trajectories and regulatory compliance deadline schedules.
Inputs from hospital procurement databases and GPO contract repositories were available through the study window; gaps in real-time actuator inventory levels introduce uncertainty bands around near-term supply assumptions. Forecasts reflect documented assumptions regarding EU MDR enforcement consistency and FDA review timeline stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Furniture
Healthcare Flooring Market
Medical Furniture
Global Stretcher Chairs Market
Medical Furniture
Medicine Cabinets Market
Medical Furniture
Medical Mattress Market
Medical Furniture
Infusion Chair Market
Medical Furniture
Global Medical Furniture Market
Medical Furniture
Global Automated Hospital Beds Market
Medical Furniture
North America Hospital Furniture Market
Medical Furniture
Asia-Pacific Hospital Bed Market
Medical Furniture
Global Chemotherapy Chairs Market
Medical Furniture
Europe Hospital Furniture Market
Medical Furniture
Asia-Pacific Hospital Furniture Market
Medical Furniture
Medical Walker Market
Medical Furniture
Global Smart Hospital Bed Market
Medical Furniture
Medical Commodes Market
Medical Furniture
Healthcare Smart Beds Market