
 Global Smart Ear Tags Market | 2026-2036
Global Smart Ear Tags Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Ear Tags Market Outlook
The capital-intensity divergence between in-house sensor fabrication and outsourced chipset procurement is rotating competitive dynamics toward vertically integrated manufacturers. Datamars leverages captive semiconductor sourcing to sustain margin control across Australian and Latin American deployments. Allflex anchors its position through dedicated RFID foundry partnerships that dominate European cattle tagging compliance programs. DeLaval competes by extending its milking system installed base into bundled ear tag subscriptions across Nordic dairy cooperatives.
Smart ear tags are wearable identification devices affixed to livestock ears, typically incorporating ISO 11784/11785 compliant transponders, accelerometers, and temperature sensors operating in the 134.2 kHz low-frequency band for short-range reading or ultra-high-frequency RFID for group scanning at distances exceeding three meters. Their primary commercial purpose is to automate individual animal traceability, health anomaly detection, and estrus timing for reproductive management in intensive production systems. Sensor-integrated tags command premium positioning due to real-time biometrics transmission, while passive RFID tags retain volume leadership in cost-sensitive emerging markets where basic identification satisfies regulatory minimums. GPS-enabled active tags represent the fastest-expanding technology segment as ranchers adopt geofencing for extensive grazing operations across semi-arid zones.
The USDA Animal and Plant Health Inspection Service mandates official identification for interstate cattle movement under the Animal Disease Traceability framework, while EID compliance in the European Union is tightening through Commission Implementing Regulation 2021/520 on bovine electronic identifiers. ISO standards 11784 and 11785 shape global interoperability, forcing manufacturers to certify cross-reader compatibility or face market exclusion. Stakeholders must monitor whether Brazil's Ministry of Agriculture will mandate individual cattle traceability ahead of EU export equivalence deadlines, as this would reshape procurement volumes across South American supply chains.
Market Dynamics
EU Green Deal livestock traceability mandates are compressing procurement timelines across European cattle operations while forcing hardware standardization onto a single electronic identification protocol. This regulatory compression is accelerating replacement cycles for legacy passive RFID systems.
Growth Catalysts
- EU Commission Implementing Regulation 2021/520:Mandates individual bovine electronic identification across member states, creating compulsory hardware refresh cycles for dairy and beef operations.
- Accelerometer-integrated estrus detection:Reproductive timing automation is displacing manual heat observation in intensive dairy systems, reducing labor dependency and conception failure rates.
- Brazilian export corridor expansion:Ranching operations in Mato Grosso and Pará are adopting GPS-enabled active tags to satisfy EU equivalence requirements for individual cattle traceability.
Market Restraints
- Semiconductor supply concentration:Captive foundry access limits second-tier manufacturers to spot-market chipset procurement, compressing margins during wafer allocation crunches.
- ISO 11784/11785 certification friction:Cross-reader interoperability testing extends product launch timelines by eight to fourteen months for non-vertically integrated vendors.
- Passive RFID substitution pressure:Basic identification tags retain volume leadership in cost-sensitive emerging markets where regulatory minimums do not mandate sensor integration.
Strategic Opportunities
- Semi-arid grazing digitization:Australian and Argentinian extensive ranching operations present untapped demand for solar-powered GPS geofencing systems with satellite backhaul.
- Blockchain-traceability convergence:Immutable ledger integration with ear tag data streams is creating premium positioning for supply chain transparency in direct-to-retailer beef programs.
- USDA Animal Disease Traceability expansion:Potential interstate movement mandate broadening beyond breeding cattle to feeder stock would reshape North American hardware procurement volumes.
Industry Challenges
- RF engineering talent scarcity:Low-frequency antenna design expertise concentrates among a handful of specialized consultancies, constraining in-house product development velocity.
- Legacy dairy management system integration:Proprietary data formats from incumbent milking equipment vendors create API fragmentation that complicates unified herd analytics deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Ear Tags Market |
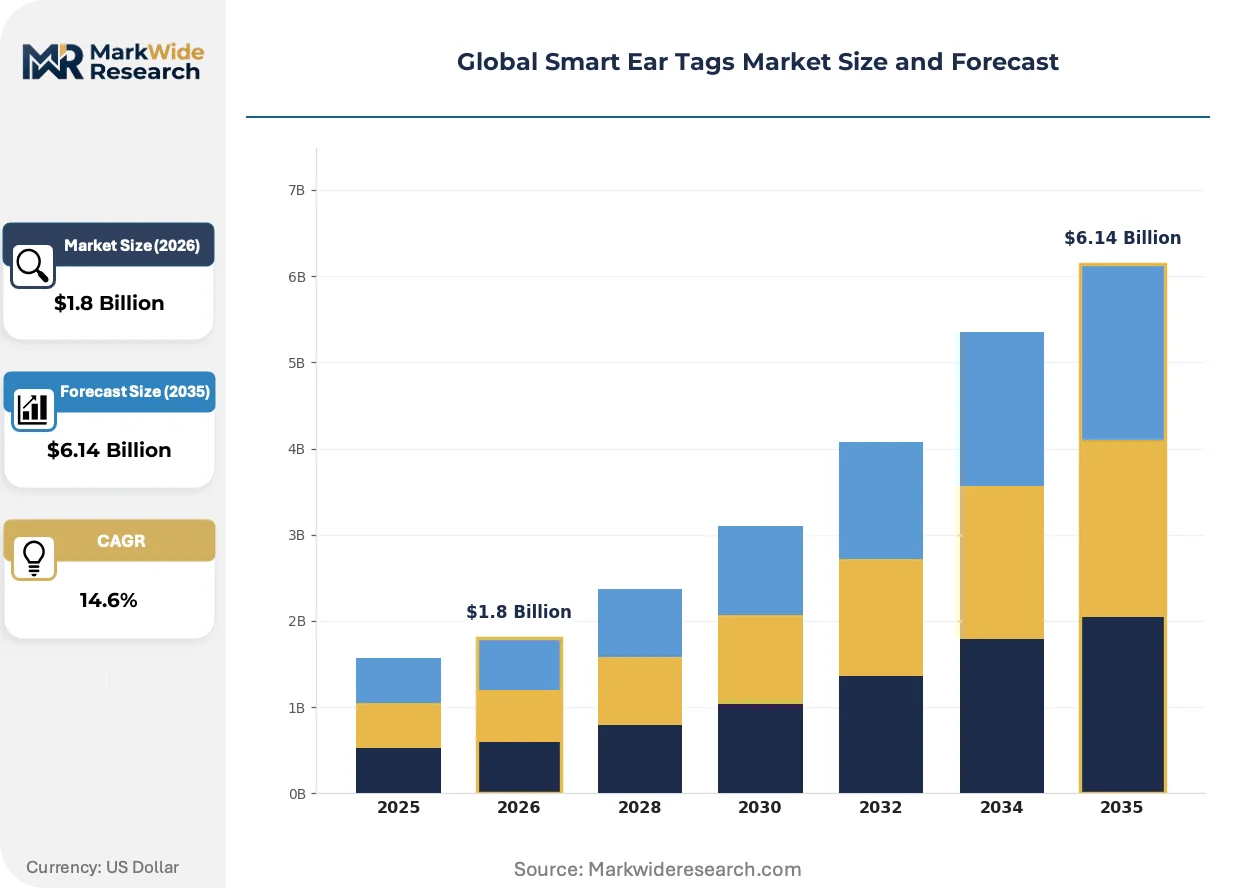
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Tags, Passive Tags, Hybrid Tags, Sensor-Integrated Tags Technology: RFID, GPS, Bluetooth, NFC End User: Agriculture, Livestock Management, Veterinary, Supply Chain Application: Tracking, Monitoring, Health Management, Location Services |
| Companies Covered | HerdDogg, Quantified AG, Allflex, CowManager, Datamars, DeLaval, SMARTBOW, Moocall, Ceres Tag, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Ear Tags Market Strategic Shifts
Sensor miniaturization and energy harvesting advances are collapsing the cost barrier between passive identification and active biometric monitoring. Hardware differentiation is shifting from transponder range to edge-computing inference capability.
Ultra-low-power accelerometers with on-chip machine learning inference are displacing cloud-dependent activity classification in next-generation tags. Nordic dairy cooperatives are piloting these devices for lameness prediction at three-month payback periods. The displacement of cellular backhaul by LoRa mesh networks is reducing subscription costs below satellite telemetry thresholds.
EU AI Act risk classification for biometric monitoring systems is triggering firmware architecture redesigns ahead of enforcement deadlines. Manufacturers must now document algorithmic decision pathways for estrus detection outputs. European tagging compliance programs are absorbing these compliance costs through extended service contract bundling.
Ranch procurement committees are consolidating vendor selection authority away from individual property managers toward centralized cooperative buying desks. Brazilian beef processors are mandating approved-device lists that exclude non-certified hardware. This concentration is visible most acutely in Pará state, where three processor groups control eighty percent of slaughter capacity.
Global Smart Ear Tags Market Segmentation
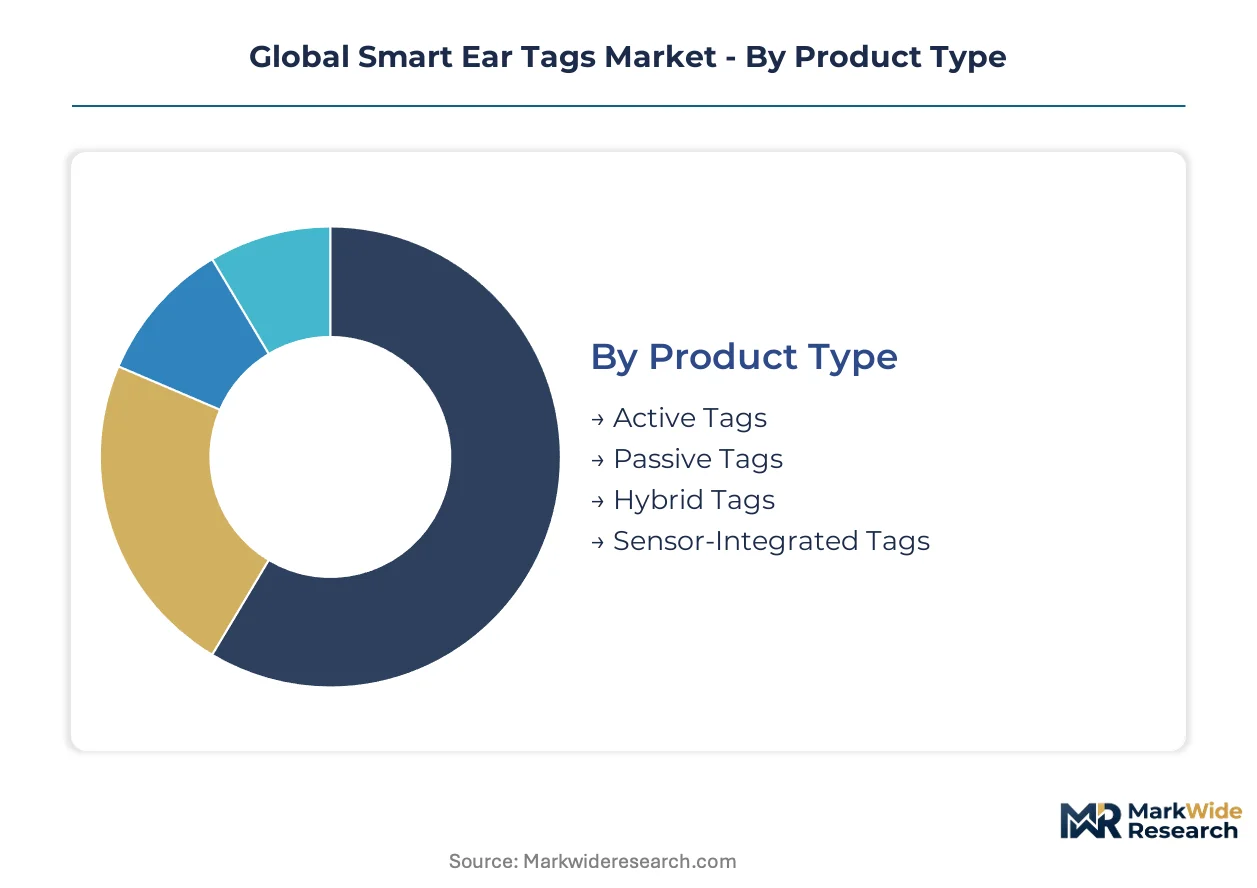
Segmentation in smart ear tags reveals how regulatory mandates reshape procurement across hardware tiers. EU electronic identification requirements and USDA interstate movement rules create divergent compliance pathways that favor specific technology configurations.
Product Type:
EU Commission Implementing Regulation 2021/520 and USDA Animal Disease Traceability framework differentiate hardware refresh cycles across tag categories.
- Active Tags:Battery-powered transponders transmit real-time location and biometric data over extended ranges. Brazilian ranching operations in Mato Grosso and Pará deploy GPS-enabled active tags to satisfy EU export equivalence requirements for individual cattle traceability.
- Passive Tags:ISO 11784/11785 compliant transponders harvest energy from reader electromagnetic fields without onboard power. Cost-sensitive emerging markets retain volume leadership here where regulatory minimums do not mandate sensor integration.
- Hybrid Tags:Dual-mode devices switch between passive identification and active transmission based on proximity to infrastructure.
- Sensor-Integrated Tags:Multi-parameter biometrics including accelerometers and temperature sensors command premium positioning for health anomaly detection.
Established volume favors passive tags; emerging adoption favors sensor-integrated tags.
Technology:
Cost tier stratification separates premium connectivity from basic identification compliance.
- RFID:Operates in 134.2 kHz low-frequency band for short-range reading or ultra-high-frequency for group scanning beyond three meters. European cattle tagging compliance programs standardize on RFID for cross-reader interoperability mandates.
- GPS:Satellite positioning enables geofencing across semi-arid extensive grazing operations. Australian and Argentinian ranching operations present untapped demand for solar-powered GPS systems with satellite backhaul.
- Bluetooth:Short-range wireless supports smartphone-based herd management in intensive dairy systems.
- NFC:Near-field communication facilitates tap-to-read verification at processing facilities.
RFID dominates procurement volumes; GPS climbs the fastest as extensive ranching digitizes.
End User:
Application intensity determines margin structure across customer categories.
- Agriculture:Broad farming operations deploy basic identification for regulatory compliance.
- Livestock Management:Intensive production systems drive accelerometer-integrated estrus detection automation. Nordic dairy cooperatives pilot ultra-low-power devices for lameness prediction at compressed payback periods.
- Veterinary:Clinical diagnostics demand temperature-sensing tags for infectious disease surveillance.
- Supply Chain:Processor-mandated approved-device lists in Brazilian Pará state exclude non-certified hardware.
Livestock management captures premium pricing; supply chain compliance drives volume consolidation.
Application:
Customer maturity separates legacy identification from predictive analytics adoption.
- Tracking:Individual animal traceability satisfies EU Green Deal mandates and USDA interstate movement rules.
- Monitoring:Continuous biometrics transmission requires active tag infrastructure investment.
- Health Management:Edge-computing inference capability for lameness and estrus detection is displacing cloud-dependent classification. EU AI Act risk classification for biometric monitoring triggers firmware architecture redesigns ahead of enforcement deadlines.
- Location Services:Geofencing functionality expands across semi-arid zones with LoRa mesh networks reducing subscription costs below satellite telemetry thresholds.
Tracking commands baseline deployment; health management gains share fastest through predictive analytics bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Australian and Nordic dairy markets where sensor-integrated tags command three-year payback premiums, while Brazilian ranching regions compete on volume procurement with EU export compliance as the threshold condition.
United States
USDA Animal Disease Traceability framework mandates official identification for interstate cattle movement, creating baseline demand across breeding and feeder operations. The USDA APHIS continues evaluating expansion to feeder stock categories. Texas Panhandle feedlots and Nebraska packing corridors drive procurement consolidation toward approved-device vendor lists.
Brazil
Ranching operations in Mato Grosso and Pará deploy GPS-enabled active tags to satisfy EU equivalence requirements for individual cattle traceability. The Ministry of Agriculture evaluates mandatory EID ahead of export deadlines. Three processor groups in Pará control eighty percent of slaughter capacity and mandate certified hardware exclusivity.
Germany
EU Commission Implementing Regulation 2021/520 mandates individual bovine electronic identification, forcing hardware refresh cycles across dairy and beef operations. The EU Green Deal tightens livestock traceability timelines. Bavarian dairy cooperatives pilot ultra-low-power accelerometer tags for lameness prediction at compressed payback periods.
Australia
Extensive grazing operations across Queensland and Western Australia present untapped demand for solar-powered GPS geofencing systems with satellite backhaul. The country's national agricultural regulator maintains biosecurity traceability standards. New South Wales and Victoria dairy regions concentrate sensor-integrated tag adoption for reproductive management automation.
Netherlands
Nordic dairy cooperatives bundle extended service contracts to absorb EU AI Act compliance costs for biometric monitoring firmware. DeLaval extends its milking system installed base into bundled ear tag subscriptions across Dutch and Scandinavian operations. The Randstad corridor hosts RFID foundry partnerships dominating European cattle tagging compliance programs.
Global Smart Ear Tags Market Competitive Environment
Concentration sits with vertically integrated manufacturers controlling captive semiconductor sourcing and dedicated RFID foundry partnerships. Three strategic archetypes dominate: Australian-Latin American deployers with captive supply chains, European compliance specialists with foundry-anchored certification velocity, and dairy system incumbents extending into bundled hardware subscriptions. Competitive moves rotate toward backward integration into chipset procurement and geographic expansion through processor-mandated approved-device lists.
Among vertically integrated specialists, Datamars leverages captive semiconductor sourcing to sustain margin control across Australian and Latin American deployments. Allflex anchors its position through dedicated RFID foundry partnerships that dominate European cattle tagging compliance programs. DeLaval competes by extending its milking system installed base into bundled ear tag subscriptions across Nordic dairy cooperatives.
| Leading Market Players |
|---|
| HerdDogg |
| Quantified AG |
| Allflex |
| CowManager |
| Datamars |
| DeLaval |
| SMARTBOW |
| Moocall |
| Ceres Tag |
| Others |
Value Chain & Pricing Dynamics
Fourteen-month ISO 11784/11785 certification timelines compress pricing power toward vertically integrated manufacturers with captive foundry access, while spot-market semiconductor procurement forces second-tier vendors into margin-sacrifice positioning during wafer allocation crunches.
Pricing Analysis
Configured-to-order premium spreads of 40-60% above standard SKUs separate sensor-integrated active tags from passive identification baseline units. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling, with EU AI Act firmware compliance costs absorbed through extended subscription contracts. Pricing pressure stems from Brazilian processor-mandated approved-device lists that consolidate procurement authority and squeeze non-certified hardware out of volume corridors. Emerging market cattle operations exhibit highest price sensitivity, while Nordic dairy cooperatives accept premium positioning for predictive analytics bundling.
Supply Chain Analysis
Taiwanese foundry capacity allocation serves as the primary chokepoint constraining RFID transponder supply velocity for European compliance program deadlines. Semiconductor fabrication concentrates in Taiwan, South Korea and Germany, while antenna substrate materials draw from Japanese and Chinese specialty polymer suppliers. Single-source vulnerability concentrates in 134.2 kHz low-frequency chipsets where ISO certification requirements tether procurement to qualified vendors. Distribution runs through processor-mandated approved-device lists in Brazilian Pará state and cooperative buying desks across Australian extensive grazing operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware-attach subscription services for estrus detection and lameness prediction are expanding at multiples of tag unit sales, converting capital expenditure into recurring revenue streams across Nordic dairy and Australian beef operations.
For Market Incumbents: Secure captive semiconductor sourcing through foundry partnerships or backward integration into chipset procurement to defend margin control against spot-market volatility. Anchor certification velocity through dedicated ISO 11784/11785 testing relationships that compress fourteen-month interoperability timelines. Threat substitution from LoRa mesh networks displacing cellular backhaul demands firmware architecture investment to maintain subscription pricing power. For New Entrants and Emerging Players: Lead with solar-powered GPS geofencing systems for Australian and Argentinian extensive ranching operations where incumbent coverage remains thin. Target semi-arid grazing digitization as the most penetrable white-space corridor, exploiting satellite backhaul cost thresholds that exclude established cellular-dependent vendors. Go-to-market through processor-approved-device list certification in Brazilian Mato Grosso to bypass cooperative buying desk consolidation. For Investors and Strategic Acquirers: Carve-out targets emerge from agricultural equipment conglomerates with under-optimized livestock identification divisions lacking dedicated RFID foundry relationships. Long-term viability hinges on service revenue attachment ratios exceeding hardware margins across the projection horizon. Signal to monitor: Brazilian Ministry of Agriculture individual traceability mandate timing, which would trigger step-function volume procurement across South American supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| RFID Foundry Partnership | Secures ISO 11784/11785 certification velocity for EU Commission Implementing Regulation 2021/520 compliance windows. |
| Subscription Service Bundling | Converts hardware sales into recurring revenue through estrus detection and lameness prediction analytics. |
| Processor Approved-Device Certification | Unlocks Brazilian Pará state slaughter capacity controlled by three dominant processor groups. |
| Solar GPS Geofencing Development | Captures Australian and Argentinian extensive ranching demand below satellite telemetry cost thresholds. |
| EU AI Act Firmware Redesign | Preempts regulatory exclusion by documenting algorithmic decision pathways for biometric monitoring outputs. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with livestock management directors, veterinary procurement leads, RFID foundry engineering heads, and Brazilian beef processor compliance officers. Secondary validation drew from USDA Animal and Plant Health Inspection Service regulatory filings, EU Commission Implementing Regulation 2021/520 documentation, ISO 11784/11785 certification registries, and Brazilian Ministry of Agriculture export equivalence protocols. Bottom-up tag unit deployment estimates triangulated against top-down cattle population and dairy herd statistics.
Across the analysis window, forecasts model product type segmentation across active, passive, hybrid and sensor-integrated tags; technology tiers spanning RFID, GPS, Bluetooth and NFC; and end-user categories from agriculture through supply chain compliance. CAGRs derive from regression analysis against cattle herd growth, regulatory mandate implementation schedules, and semiconductor foundry capacity expansion trajectories. Industry-specific inputs include EU Green Deal livestock traceability timeline compression and Brazilian export corridor digitization rates.
The analysis sits within stated boundaries; outcomes outside sustained EU electronic identification enforcement or Brazilian individual traceability mandate adoption would require recalibration. Forecasts reflect assumptions regarding ISO certification timeline stability and foundry allocation continuity. Practitioners should keep alternative scenarios live as semiconductor supply concentration and regulatory deadline shifts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Beef Cattle Feed and Additives Market
Livestock Management
Colombia Animal Feed Market
Livestock Management
Poultry Health Market
Livestock Management
Animal Feed Protease Market
Livestock Management
Poultry Concentrate Market
Livestock Management
Equine Artificial Insemination Market
Livestock Management
Europe Ruminant Feed Premix Market
Livestock Management
Hominy Feed Market
Livestock Management
Africa Alfalfa Hay Market
Livestock Management
North America Feed Binders Market
Livestock Management
Cattle Squeeze Market
Livestock Management
Animal Artificial Insemination Market
Livestock Management
Swine Artificial Insemination Market
Livestock Management
China Swine Feed Market
Livestock Management
Animal Identification Market
Livestock Management
North America Ruminant Feed Premix Market