
 Poultry Concentrate Market | 2026-2036
Poultry Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Poultry Concentrate Market Analytics
A capital-intensity divergence between integrated multinationals and regional compounders is reorganizing competitive hierarchy in poultry concentrates. Cargill leverages its oilseed crushing footprint to secure captive protein supplies across multiple continents. CP Group anchors its concentrate strategy through vertically integrated broiler operations in Thailand and China. Nutreco differentiates via precision nutrition platforms that tailor mineral premixes to specific genetic strains.
Poultry concentrate denotes a nutritionally dense, homogenized feed formulation typically containing 18-22% crude protein, supplemented with crystalline amino acids, enzyme complexes, and trace mineral chelates, manufactured through sequential grinding, thermal conditioning, and pelleting or mash blending to deliver metabolizable energy of 2800-3200 kcal/kg for intensive bird rearing. Pelleted feed commands the largest value share due to reduced feed wastage and improved flock uniformity in commercial operations. Mash feed retains dominance among backyard and smallholder systems where capital constraints limit processing infrastructure. Liquid feed concentrates represent the fastest-expanding format, particularly in automated drinking water systems for layer operations.
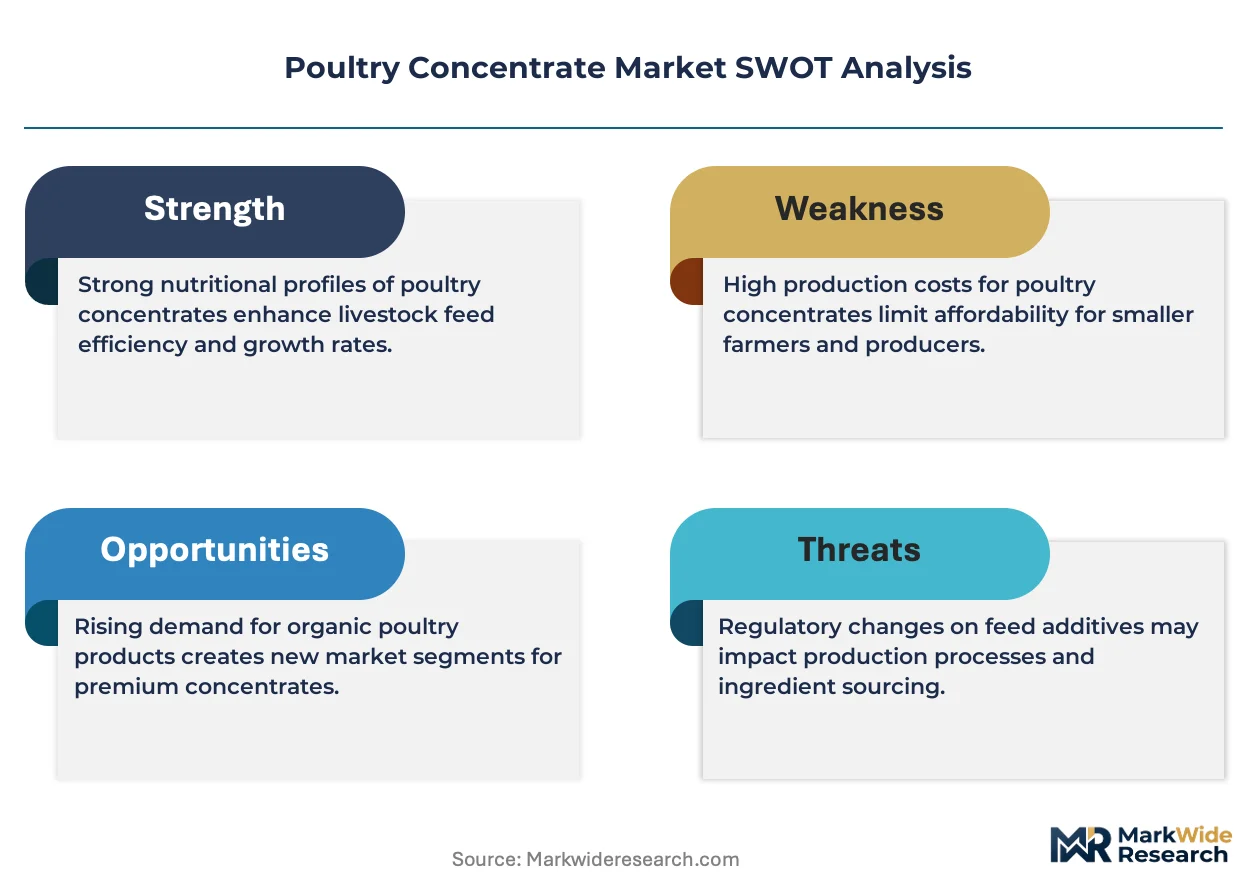
The EU Green Deal and REACH frameworks restrict antibiotic growth promoters and certain pesticide residues in feed crops, compelling reformulation toward enzyme-based digestibility enhancers. The FDA's Veterinary Feed Directive in the United States mandates veterinary oversight for medically important antimicrobials, reshaping concentrate additive portfolios. Stakeholders must monitor evolving maximum residue limits from EFSA and national regulators, as compliance thresholds increasingly determine market access across export-oriented poultry supply chains.
Market Dynamics
Intensifying broiler stocking densities across Southeast Asian farming complexes are compressing feed conversion ratios and forcing concentrate formulators toward precision amino acid balancing and enzyme fortification.
Growth Catalysts
- EU Green Deal feed mandates:Sustainability sourcing requirements across member states are accelerating demand for deforestation-free soy and insect protein alternatives in compound formulations.
- Vietnam's Mekong Delta cluster expansion:Integrated farming complexes in this region are scaling concentrate offtake as contract broiler operations consolidate smallholder output.
- Crystalline amino acid supplementation:Industrial-scale synthesis of lysine, methionine, and threonine is enabling lower crude protein diets without sacrificing bird performance metrics.
Market Restraints
- Soybean meal price volatility:Weather-driven South American harvest variability and biofuel policy competition in the United States are compressing compounder margins.
- Phosphate rock supply concentration:Moroccan and Chinese dominance in feed-grade phosphorus inputs creates geopolitical exposure for mineral premix producers.
- Antibiotic residue thresholds:EFSA maximum residue limits and FDA Veterinary Feed Directive compliance costs are elevating quality assurance expenditure for export-oriented mills.
Strategic Opportunities
- Automated drinking water systems:Liquid concentrate integration into layer house automation is opening format diversification beyond traditional pelleted and mash feeds.
- Enzyme-based digestibility platforms:Phytase and non-starch polysaccharide enzyme cocktails are capturing value from reduced phosphorus excretion regulations in the Netherlands and Denmark.
- Backyard poultry digitization:Mobile-enabled concentrate ordering platforms are penetrating smallholder segments in Indonesia and Bangladesh previously served by informal distribution.
Industry Challenges
- Feed safety certification timelines:FAMI-QS and GMP+ accreditation processes for new manufacturing facilities extend 18-24 months, delaying market entry in regulated export corridors.
- Thermal conditioning energy costs:Pelleting line steam generation requirements are elevating operational expenditure amid natural gas price instability across European compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poultry Concentrate Market |
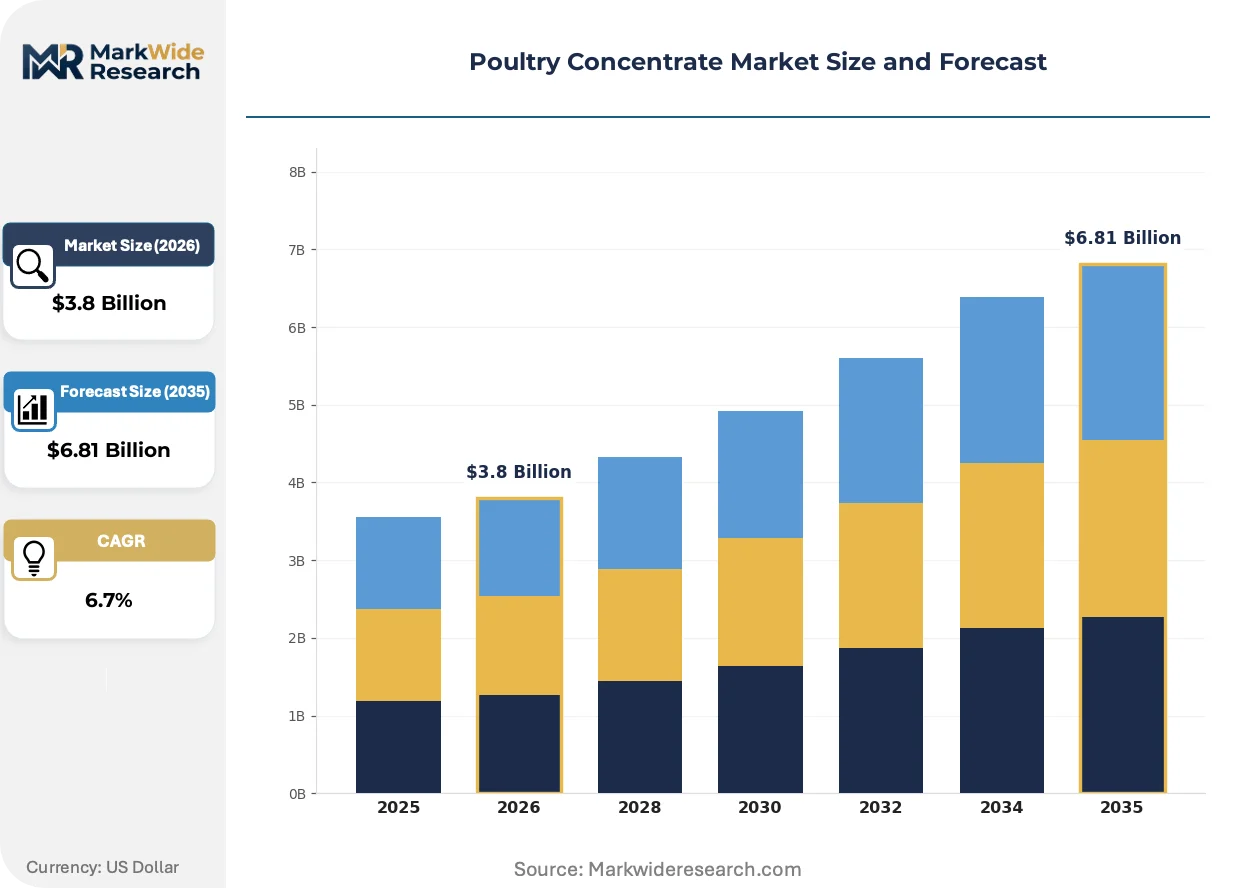
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mash Feed, Pelleted Feed, Crumble Feed, Liquid Feed End Use: Broilers, Layers, Turkeys, Other Poultry Ingredient Type: Protein Sources, Carbohydrates, Vitamins, Minerals Packaging Type: Bags, Bulk Containers, Sachets, Drums |
| Companies Covered | Cargill, CP Group, Archer Daniels Midland Company, Nutreco, New Hope Group, Purina Animal Nutrition, Evonik Industries, Tyson Foods, BRF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poultry Concentrate Market Evolving Landscape
Digital feed formulation platforms and alternative protein streams are compressing traditional ingredient procurement patterns while regulatory biotechnology frameworks accelerate novel additive approval pathways.
Precision fermentation-derived single-cell proteins are fragmenting conventional fishmeal and soybean meal incorporation rates in premium concentrate tiers. Specialist layer operations in the Netherlands and Japan are piloting these ingredients at 5-15% inclusion levels. The technology is fragmenting long-term supply contracts with commodity traders as formulators diversify protein sourcing.
REACH framework amendments on feed additive environmental fate are compelling reformulation toward biodegradable enzyme carriers and reduced-chelate mineral forms. Industrial consequence includes elevated toxicology dossier preparation costs for premix manufacturers. Layer concentrate exporters to EU member states are responding by segregating production lines and traceability systems.
Consolidated procurement by integrated poultry processors is compressing compounder negotiation leverage and accelerating long-term supply agreements with fixed pricing mechanisms. Regional feed mills serving independent growers are losing volume to captive compound production within vertically integrated operations. Thailand's broiler sector exhibits this pattern most acutely as CP Group and Betagro expand in-house milling capacity.
Poultry Concentrate Market Segmentation
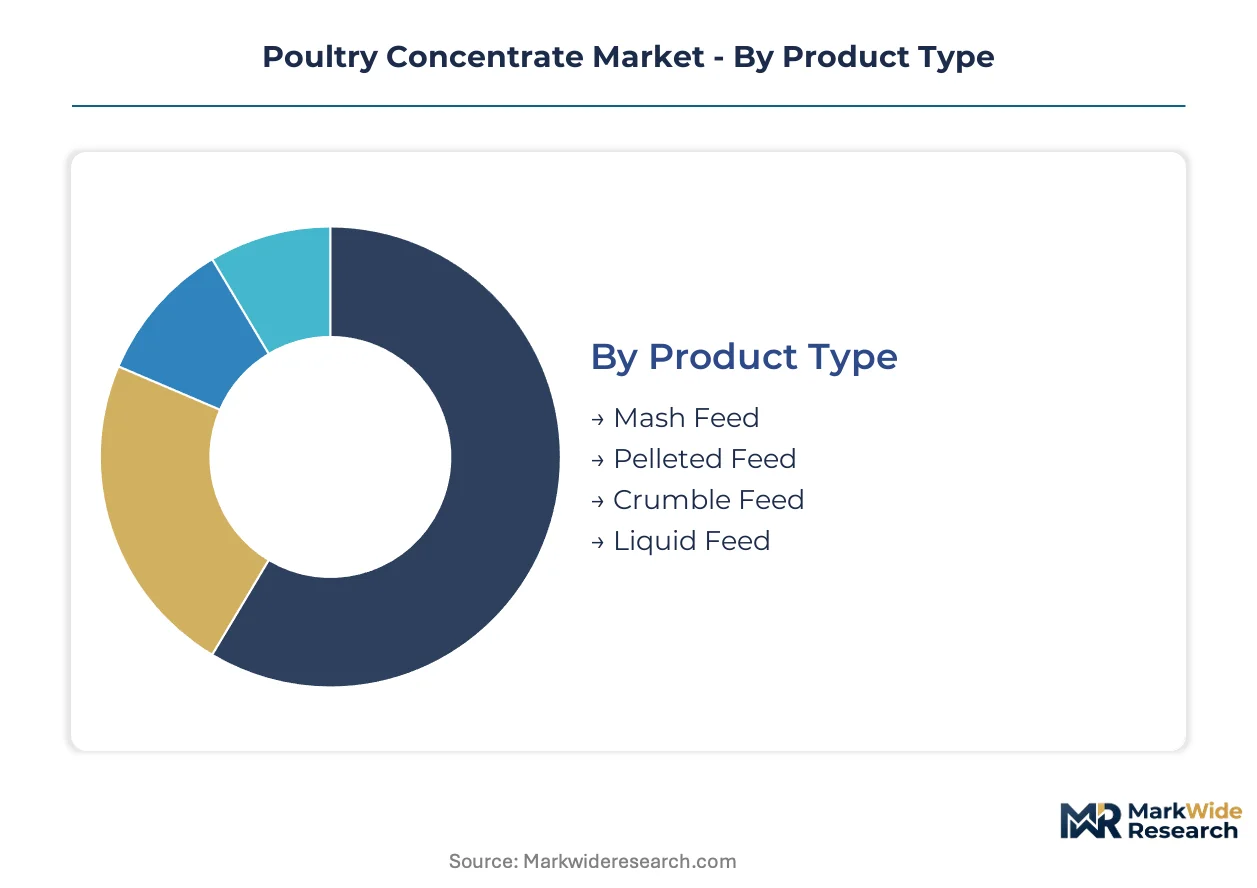
Poultry concentrate segmentation reveals how physical form, bird genetics, and supply chain infrastructure shape procurement patterns across intensive and extensive production systems. Formulation chemistry and packaging logistics create distinct margin profiles that reorganize competitive positioning among compounders.
Product Type:
Pelleted and liquid formats face intensifying substitution pressure from precision fermentation proteins and automated nutrient delivery systems that bypass traditional feed manufacturing entirely.
- Pelleted Feed:Thermally conditioned cylindrical particles manufactured through steam pelleting reduce feed wastage and improve flock uniformity in commercial broiler operations. Demand concentrates in Vietnam's Mekong Delta integrated complexes where contract growers operate under processor-mandated feed specifications. EU Green Deal sustainability mandates are accelerating pelleting line energy audits across Dutch and Danish compounders.
- Liquid Feed:Homogenized aqueous suspensions of vitamins, minerals, and amino acids designed for integration into automated drinking water systems. Demand concentrates in Japanese and Dutch layer houses where nipple drinker automation achieves precise nutrient titration. FDA Veterinary Feed Directive compliance costs favor liquid formats with simplified additive tracking versus solid feed matrices.
- Mash Feed:Ground, unprocessed blend retaining ingredient particle heterogeneity for backyard and smallholder systems with limited capital infrastructure.
- Crumble Feed:Intermediate particle size produced by crushing pellets, serving pullet rearing and breeder operations requiring gradual texture transition.
Pelleted feed anchors the volume base while liquid feed gains share at the steepest rate as layer house automation penetrates Southeast Asian markets.
End Use:
Broiler and layer segments stratify across cost tiers determined by genetic potential, slaughter weight targets, and egg production curves that dictate amino acid density requirements.
- Broilers:Rapid-growth genotype concentrates requiring 18-22% crude protein with crystalline lysine and methionine fortification to maximize breast meat yield. Thailand's CP Group and Betagro operations anchor demand through captive milling capacity expansion. EFSA maximum residue limits on antibiotic traces are forcing reformulation toward enzyme-based digestibility enhancers in export-oriented operations.
- Layers:Sustained egg production genotypes with calcium and phosphorus precision balancing for shell quality across extended laying cycles. Precision fermentation single-cell proteins are fragmenting traditional soybean meal inclusion rates in premium Dutch and Japanese layer concentrates.
- Turkeys:Heavy-weight genotype concentrates with elevated protein density and mineral premixes supporting extended rearing periods to mature slaughter weights.
- Other Poultry:Duck, quail, and game bird formulations with species-specific nutrient profiles addressing niche protein and fat metabolism requirements.
Broilers dominate tonnage throughput while layer concentrates expand most quickly through precision nutrition platform adoption.
Ingredient Type:
Protein sourcing exhibits the highest supply concentration risk with Moroccan phosphate rock and South American soybean meal creating geopolitical exposure for mineral and amino acid premix producers.
- Protein Sources:Soybean meal, rapeseed meal, and insect protein alternatives providing essential amino acid profiles. REACH framework deforestation-free sourcing mandates are accelerating insect protein pilot programs across EU compounders.
- Carbohydrates:Cereal grains and grain by-products supplying metabolizable energy bases of 2800-3200 kcal/kg formulations. Weather-driven harvest variability in Black Sea and North American grain belts generates formulation cost volatility.
- Vitamins:Fat-soluble and water-soluble micronutrient premixes manufactured through chemical synthesis or fermentation processes. FAMI-QS certification timelines extend 18-24 months for new vitamin premix facilities seeking export market access.
- Minerals:Macro-minerals and trace element chelates including phosphate sources subject to Moroccan and Chinese supply concentration. EFSA biodegradable carrier mandates are elevating toxicology dossier preparation costs for mineral premix exporters.
Protein sources command the largest procurement expenditure share while mineral premixes face the steepest regulatory compliance cost escalation.
Packaging Type:
Packaging selection tracks customer scale and distribution infrastructure maturity across integrated processor networks versus independent grower fragmentation.
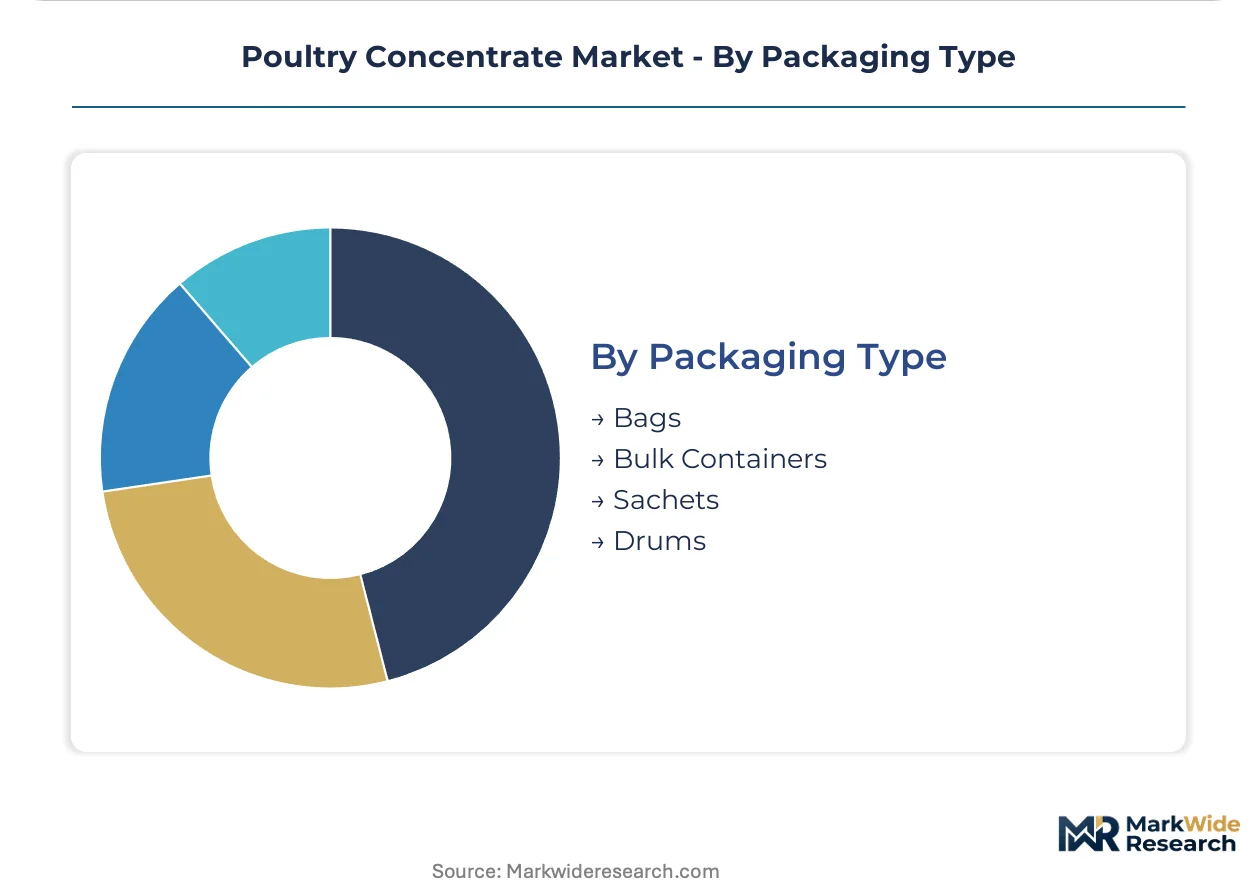
- Bags:Multi-layer paper or woven polypropylene containers serving small-to-medium independent growers and backyard operations. Mobile-enabled ordering platforms are penetrating Indonesian and Bangladeshi smallholder segments previously served by informal bagged distribution.
- Bulk Containers:Silo-delivered concentrates for integrated farming complexes with on-farm storage infrastructure. Vietnam's Mekong Delta cluster expansion is accelerating bulk container offtake as contract operations consolidate smallholder output.
- Sachets:Unit-dose packaging for specialty additives, probiotics, and veterinary-directed premixes requiring precise inclusion control.
- Drums:Liquid concentrate containment for automated drinking water system integration in layer and breeder operations.
Bulk containers anchor volume throughput in integrated supply chains while bagged formats retain dominance across fragmented smallholder procurement channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented poultry supply chains in Southeast Asia and South America generate substantial concentrate import demand, while European compounders face deforestation-free sourcing mandates that reshape procurement geography.
Vietnam
Contract broiler operations in the Mekong Delta cluster scale concentrate offtake as integrated farming complexes consolidate smallholder output. The Ministry of Agriculture and Rural Development enforces feed safety certification aligned with export market requirements. Ho Chi Minh City anchors distribution infrastructure for bulk container delivery to processing-integrated farms.
Thailand
Captive milling capacity expansion by vertically integrated processors reduces independent compounder market share. The Department of Livestock Development regulates antibiotic residue thresholds under export-oriented compliance frameworks. Bangkok-based logistics networks facilitate concentrate movement to contract grower operations across the Central Plains.
Netherlands
Layer house automation penetration drives liquid concentrate demand for precision nutrient delivery systems. REACH framework amendments mandate biodegradable enzyme carriers and reduced-chelate mineral forms in premix formulations. The Feed Design Lab in Wageningen pilots precision fermentation protein inclusion at commercial scale.
United States
Midwest grain belt proximity supports cost-competitive carbohydrate sourcing for metabolizable energy formulations. The FDA Veterinary Feed Directive mandates veterinary oversight for medically important antimicrobials in concentrate additives. Iowa and Arkansas processing corridors concentrate demand for high-protein broiler concentrates.
Brazil
Soybean meal supply integration with crushing operations provides protein sourcing advantages for domestic compounders. MAPA (Ministry of Agriculture, Livestock and Food Supply) enforces sanitary standards for export-oriented poultry supply chains. The southern states of Paraná and Santa Catarina cluster integrated broiler operations with captive feed milling capacity.
Poultry Concentrate Market Competitive Landscape
Concentration sits with integrated agribusiness conglomerates that control oilseed crushing and captive protein supplies across multiple continents. Regional compounders serving independent growers face margin compression from consolidated procurement by poultry processors. Three archetypes dominate: multinational traders with upstream oilseed assets, vertically integrated poultry processors with in-house milling, and precision nutrition specialists with genetic-strain formulation platforms. Capacity expansion and backward integration into oilseed crushing represent the dominant competitive moves.
Among North American agribusiness operators, Cargill and Archer Daniels Midland Company exemplify the trader-archetype with crushing footprint advantages. Nutreco occupies a position within the precision nutrition tier. CP Group anchors the Asia-Pacific processor-integrated archetype. Tyson Foods and BRF represent processor-compounders with captive milling strategies. New Hope Group, Evonik Industries, and Purina Animal Nutrition sit within regional specialist and additive supplier categories.
| Leading Market Players |
|---|
| Cargill |
| CP Group |
| Archer Daniels Midland Company |
| Nutreco |
| New Hope Group |
| Purina Animal Nutrition |
| Evonik Industries |
| Tyson Foods |
| BRF |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Southeast Asian pelleting facilities compresses both supply concentration and price floors as integrated processors expand captive milling. Moroccan phosphate rock dominance and South American soybean meal variability tether mineral premix and protein sourcing costs to geopolitical exposure, forcing compounders toward long-term offtake contracts with fixed pricing mechanisms.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing as Vietnam's Mekong Delta integrated complexes consolidate procurement leverage. Three-tier pricing structure across premium enzyme-fortified, standard vitamin-premixed, and economy mash tiers differentiates by certification grade and volume scale. Cost compression in standard tiers intensifies because CP Group and Betagro expand in-house milling capacity. Backyard smallholders exhibit highest price sensitivity; premium layer operations in the Netherlands show least sensitivity due to automation-driven precision nutrition requirements.
Supply Chain Analysis
Inventory lead times for feed-grade phosphate rock extend 8-12 weeks as Moroccan and Chinese suppliers concentrate global mineral premix inputs. Protein sourcing draws from Brazil, Argentina, and the United States; carbohydrate bases rest on Black Sea and North American grain belts. Single-source vulnerability in phosphate creates geopolitical exposure for amino acid premix manufacturers. Distribution runs through processor-integrated silo networks for bulk containers and mobile-enabled platforms for bagged smallholder channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation proteins and automated nutrient delivery systems threaten traditional concentrate formats, forcing incumbents to defend substitution through formulation platform differentiation.
For Market Incumbents: Consolidate backward integration into oilseed crushing to secure captive protein supplies against South American harvest volatility. Expand FAMI-QS certification coverage across Southeast Asian production lines to preempt EU Green Deal compliance barriers. Defend against enzyme-based digestibility platforms by locking long-term supply agreements with precision fermentation specialists. For New Entrants and Emerging Players: Lead with liquid concentrate integration into Indonesian and Bangladeshi layer house automation as the most penetrable white-space segment. Target mobile-enabled ordering platforms for backyard poultry operations previously served by informal distribution. Capture share through simplified FDA Veterinary Feed Directive compliance tracking versus solid feed matrices. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision nutrition specialists with genetic-strain formulation platforms over commodity compounders. Long-term viability across the analysis window hinges on deforestation-free sourcing certification and enzyme-based digestibility R&D pipelines. Watch EFSA maximum residue limit tightening as the inflection indicator for quality assurance expenditure escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Cargill leverages crushing footprint to secure captive soybean meal supplies across multiple continents. |
| Precision Nutrition Platform Development | Nutreco tailors mineral premixes to specific genetic strains, fragmenting commodity concentrate procurement. |
| Deforestation-Free Sourcing Certification | EU Green Deal mandates accelerate REACH-compliant soy and insect protein alternative incorporation. |
| Layer House Automation Partnership | Liquid concentrate integration into Dutch nipple drinker systems achieves precise nutrient titration. |
| Mobile-Enabled Smallholder Distribution | Indonesian and Bangladeshi ordering platforms penetrate backyard segments previously served informally. |
Research Methodology
Operator-level perspectives from feed mill plant managers, poultry processor procurement leads, veterinary nutritionists, and distribution channel partners anchored the qualitative base. Secondary validation drew from FAMI-QS certification databases, EFSA additive approval registers, USDA grain production statistics, and customs trade records for soybean meal and phosphate rock flows. Bottom-up volume estimates from country-level poultry stocking density data triangulated against top-down compound feed production aggregates.
Sensitivity analysis tested forecast outputs against variable input cost scenarios and regulatory compliance timeline shifts across the projection horizon. Segmentation modeling incorporated physical form, bird genetics, ingredient chemistry, and packaging logistics dimensions. CAGRs derived from historical consumption elasticities and projected intensification rates in Southeast Asian broiler operations. Industry-specific inputs included enzyme adoption curves and precision fermentation protein inclusion trajectories.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or abrupt phosphate supply disruption would require recalibration. Forecasts reflect documented assumptions on stocking density trends and additive approval pathways. Antibiotic residue threshold revisions and natural gas price instability for pelleting energy represent primary revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Saudi Arabia Poultry Market
Livestock Management
Colombia Animal Feed Market
Livestock Management
Cattle Head Catch Market
Livestock Management
Hominy Feed Market
Livestock Management
Animal Identification Market
Livestock Management
Cattle Squeeze Market
Livestock Management
Pig Feed Market
Livestock Management
Animal Feed Protease Market
Livestock Management
China Swine Feed Market
Livestock Management
Roughage Feed Market
Livestock Management
Europe Swine Feed Market
Livestock Management
Poultry Health Market
Livestock Management
Equine Artificial Insemination Market
Livestock Management
Cattle Mineral Feeder Market
Livestock Management
Dairy Herd Management Market
Livestock Management
Smart Feeding Systems Market