
 Animal Identification Market | 2026-2036
Animal Identification Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Identification Market Analytics
Market Context
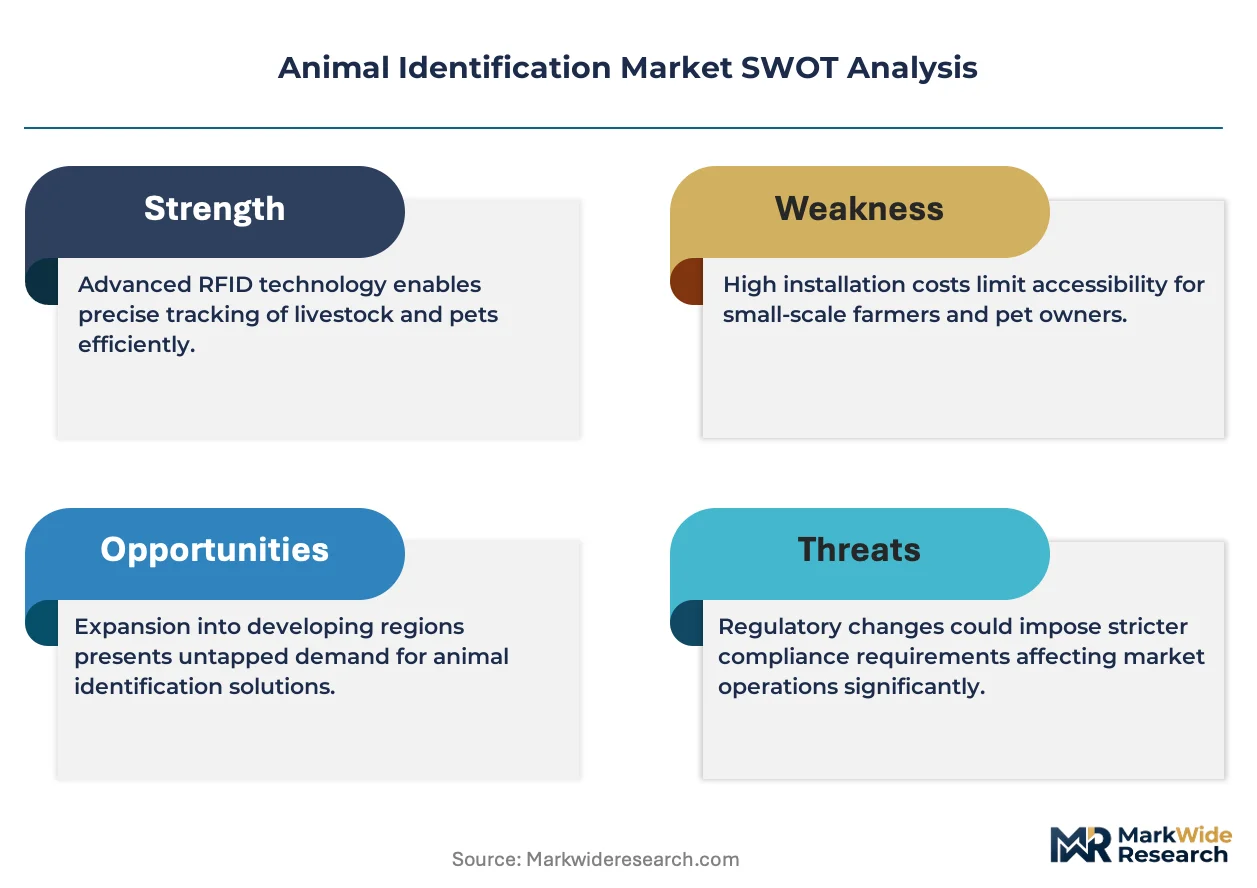
EU animal health traceability mandates are pivoting the cost-of-entry calculus for new suppliers seeking European market access. Merck & Co., Inc. leverages its pharmaceutical heritage to dominate veterinary-grade identification solutions. Datamars sustains technology leadership in RFID-enabled livestock monitoring across Australasia. Nedap N.V. anchors its position through precision livestock farming integration in Dutch dairy operations.
Technical Definition and Structural Segments
Animal identification encompasses permanent or temporary marking systems—ranging from subcutaneous microchips operating at 134.2 kHz ISO frequencies to visual ear tags with laser-etched numeric codes—that enable individual or herd-level tracking for health, ownership, and regulatory compliance purposes. RFID technology leads value capture due to mandatory electronic identification rollouts in bovine populations across multiple jurisdictions, while GPS-enabled collars represent the fastest-growing segment as pastoral operations adopt geofencing for extensive grazing management. Incorporated chips command premium margins in companion animal applications where pet registration databases require ISO 11784/11785 compliant transponders.
Regulatory Framework
USDA Animal and Plant Health Inspection Service, EU Commission Delegated Regulation on bovine electronic identification, and Australia's National Livestock Identification System collectively shape product standards and cross-border market access conditions. Compliance with ISO 11784/11785 standards has become a non-negotiable baseline for any supplier serving OECD veterinary markets. Stakeholders must monitor pending harmonization between national traceability databases to anticipate interoperability requirements that will determine competitive viability in export-oriented supply chains.
Market Dynamics
Electronic identification mandates from the EU Commission Delegated Regulation on bovine electronic identification and USDA APHIS traceability rules are forcing wholesale infrastructure replacement across commercial livestock operations, compressing supplier qualification timelines and concentrating procurement among ISO-certified vendors.
Growth Catalysts
- EU bovine EID mandate:Cattle producers across Germany, France, and the Netherlands must deploy ISO 11784/11785 compliant RFID systems by regulatory deadlines, creating immediate hardware demand.
- Pastoral geofencing adoption:Australian sheep stations and Brazilian cattle ranches are deploying GPS-enabled collars to manage extensive grazing territories and reduce labor-intensive mustering.
- Blockchain integration:Supply chain traceability platforms are layering immutable record-keeping atop RFID infrastructure to satisfy retail and export verification requirements.
Market Restraints
- Semiconductor supply concentration:RFID transponder production depends on concentrated Asian foundry capacity, exposing lead times to geopolitical friction.
- Veterinary infrastructure gaps:Rural regions in developing markets lack trained personnel and cold-chain logistics for biometric sample collection tied to identification systems.
- Copper and rare earth volatility:Antenna coil materials and permanent magnet components in electronic tags face input cost swings that compress hardware margins.
Strategic Opportunities
- Companion animal microchipping underpenetration:Urban centers in India and Southeast Asian megacities present untapped demand for ISO-compliant pet registration systems.
- AI-powered behavioral analytics:Machine learning models processing RFID location data enable predictive health monitoring, opening subscription revenue streams beyond hardware sales.
- Direct-to-producer digital channels:E-commerce platforms and veterinary telemedicine networks are disintermediating traditional agricultural supply distributors.
Industry Challenges
- Veterinary informatics skill scarcity:Livestock operations struggle to recruit personnel capable of managing integrated RFID, GPS, and cloud database systems.
- Legacy database interoperability:National livestock identification systems in Australia, Brazil, and EU member states use incompatible data formats, complicating cross-border trade verification.
- Hardware-software integration complexity:Proprietary reader protocols from equipment manufacturers create vendor lock-in that limits producer flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Identification Market |
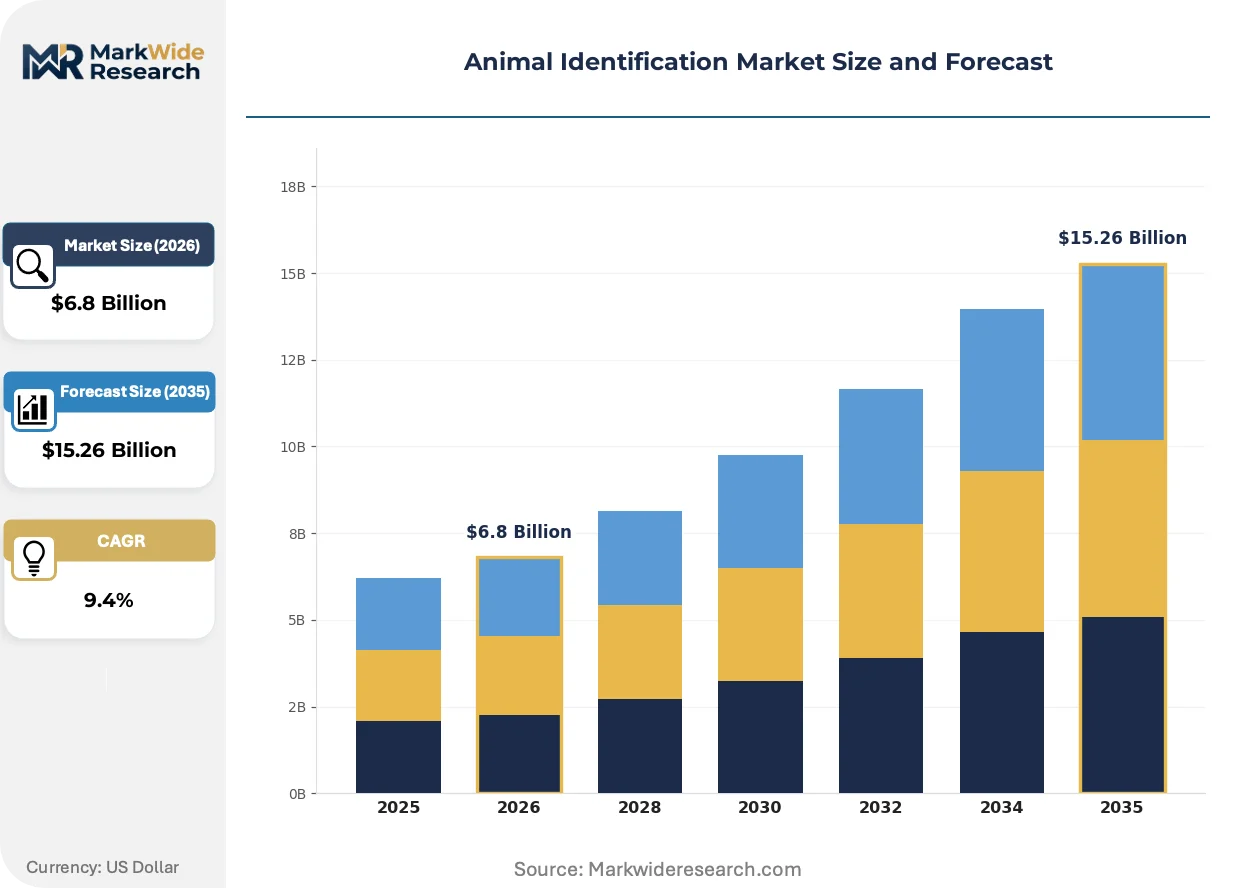
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Incorporated Chips, Ear Tags, Neck Bands, Tattoos Technology: RFID, GPS, Barcodes, Infrared End User: Farmers, Veterinarians, Research Institutions, Animal Shelters Application: Livestock Tracking, Pet Registration, Wildlife Management, Disease Control |
| Companies Covered | HID Global Corporation, Nedap N.V., Merck & Co., Inc., GAO RFID, Avid Identification Systems, Inc., Datamars, Shearwell Data Ltd., Avery Dennison Corporation, Allflex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Identification Market Evolving Landscape
Sensor miniaturization and edge computing capabilities are redistributing intelligence from centralized servers to field-deployed devices, enabling real-time decision-making without connectivity dependency.
Bluetooth Low Energy is decentralizing livestock monitoring by enabling smartphone-based tag reading without dedicated infrastructure. Smallholder dairy cooperatives in Kenya and Colombia are piloting these systems to bypass costly fixed reader installations. The technology is compressing capital requirements for traceability compliance among resource-constrained producers.
EU Commission Delegated Regulation on bovine electronic identification is mandating ISO-standard RFID across all member states by fixed deadlines. Hardware suppliers must recertify product lines to maintain market access. Dutch and Irish dairy exporters are accelerating compliance investments to preserve premium market positioning in Asian beef import channels.
Consolidated procurement by integrated protein packers is displacing fragmented farm-level purchasing. JBS, Tyson, and Cargill are mandating supplier-tag compatibility with their internal traceability platforms. This concentration is most visible in Brazil's Mato Grosso cattle feeding complexes and US Great Plains feedlot regions.
Animal Identification Market Segmentation
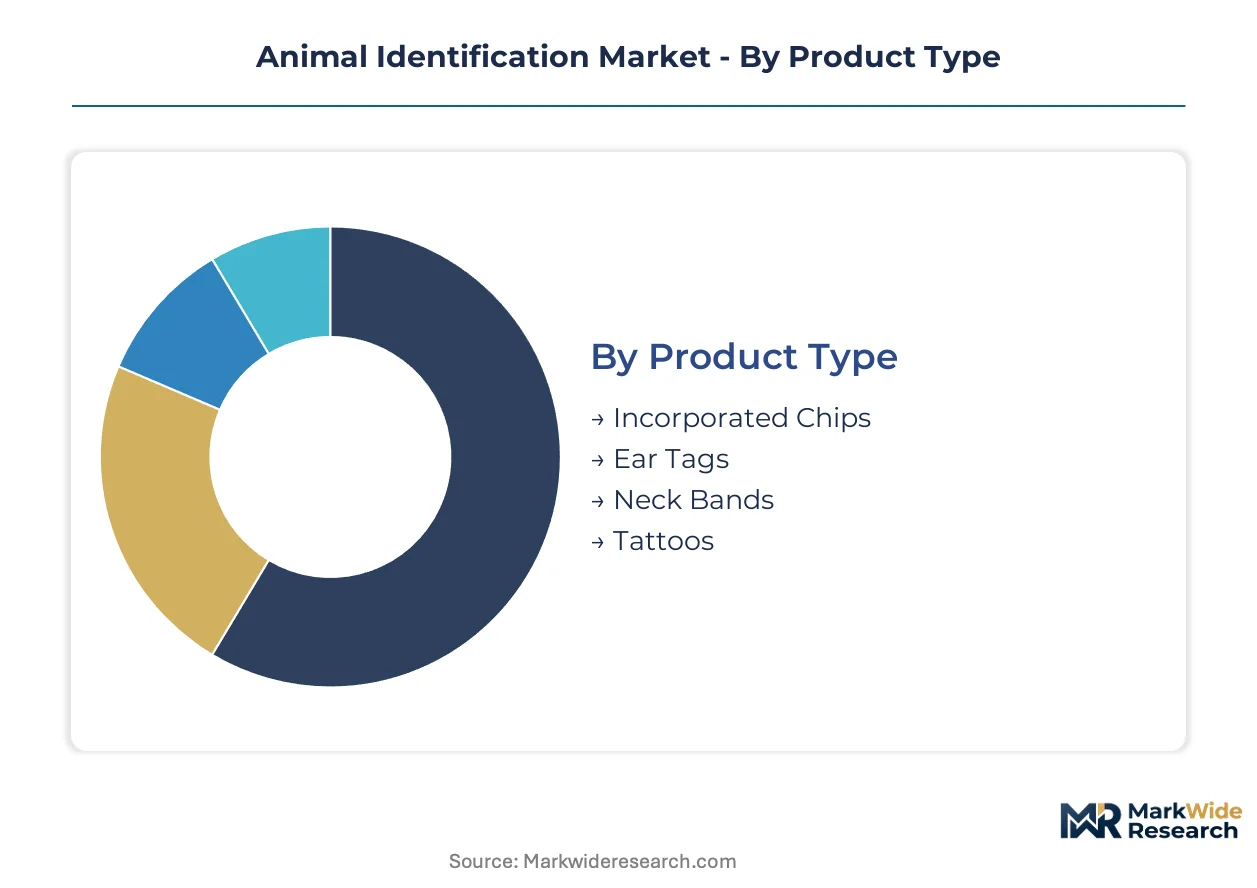
Segmentation in animal identification reflects divergent technical requirements across species, regulatory environments, and operational scales. Product architecture and technology selection directly determine compliance eligibility and total cost of ownership for end users.
Product Type:
Volume deployment favors low-unit-cost marking, while premium margins concentrate in implantable solutions with database integration requirements.
- Incorporated Chips:Subcutaneous glass-encapsulated transponders operating at 134.2 kHz ISO frequencies enable permanent, tamper-proof identification. Demand clusters in companion animal registration systems across OECD veterinary markets, driven by municipal pet licensing mandates and insurance verification requirements.
- Ear Tags:Visual and electronic variants—plastic, metal, or RFID-enabled—attach to livestock pinnae for herd-level management. Brazilian cattle operations and Australian sheep stations represent the dominant deployment geographies, pressured by export traceability mandates from USDA and EU Commission regulations.
- Neck Bands:Collar-mounted devices incorporating GPS or accelerometer sensors for behavioral monitoring. Deployed extensively in pastoral grazing systems requiring geofencing capabilities.
- Tattoos:Permanent ink-based identification applied to inner ear or flank tissue. Retains utility in cost-constrained swine operations and heritage breed conservation programs.
Mature deployment sits with ear tags. Newer deployment is concentrated in incorporated chips.
Technology:
Regulatory certification requirements segment technology adoption by jurisdictional mandate rather than producer preference.
- RFID:Passive and active radio-frequency systems dominate commercial livestock operations, with ISO 11784/11785 compliance mandatory for EU market access and USDA traceability programs. Reader infrastructure investments lock producers into multi-year hardware commitments.
- GPS:Satellite-enabled location tracking enables real-time perimeter monitoring and theft recovery. Australian extensive grazing operations and Brazilian ranching complexes are expanding collar deployment fastest, displacing labor-intensive mustering.
- Barcodes:Optical scanning systems retain niche application in laboratory specimen tracking and small-scale poultry operations with limited capital budgets.
- Infrared:Thermal and near-infrared imaging for biometric identification based on retinal or muzzle patterns. Experimental deployment in dairy parlor automation systems.
Established infrastructure supports RFID. GPS represents the fastest-growing trajectory as pastoral operations digitize.
End User:
Procurement authority varies sharply by operational scale and regulatory exposure.
- Farmers:Commercial livestock producers purchasing tags, readers, and database subscriptions at volume. Integrated protein packers increasingly mandate specific tag formats, concentrating supplier selection authority upstream.
- Veterinarians:Clinical practitioners administering microchips for companion animals and certifying health status in export-bound livestock. ISO-compliant transponder implantation requires specialized training and equipment.
- Research Institutions:Academic and government laboratories utilizing identification systems for longitudinal studies. Demand emphasizes data interoperability and archival stability.
- Animal Shelters:Municipal and nonprofit facilities processing intake, reunification, and adoption workflows. Cost constraints favor basic microchipping over comprehensive database integration.
Institutional procurement dominates research applications. Shelter deployment is expanding most quickly in urbanizing developing markets.
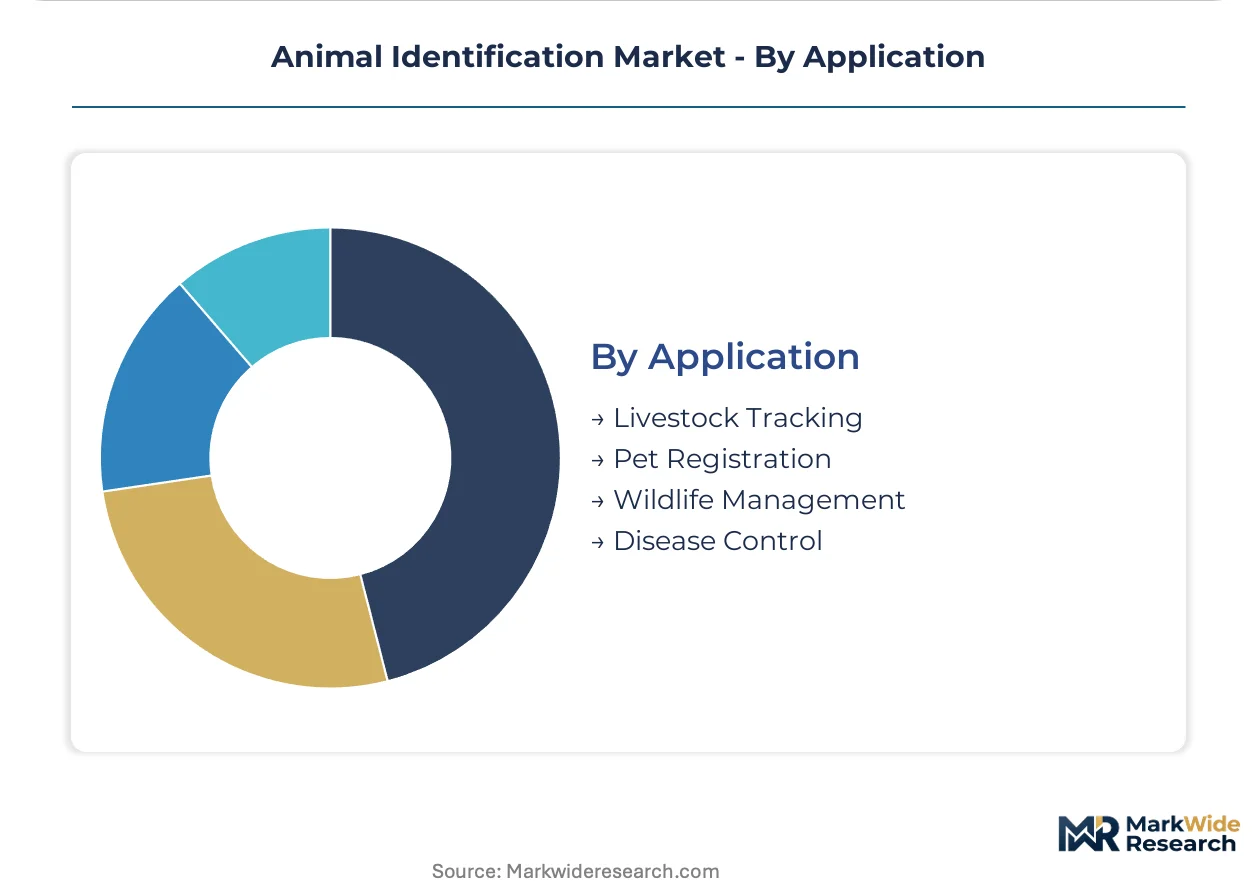
Application:
Use case determines hardware durability, data retention, and integration complexity requirements.
- Livestock Tracking:Herd management, movement documentation, and supply chain traceability for cattle, sheep, swine, and poultry. EU bovine electronic identification mandates and USDA traceability rules are compressing adoption timelines.
- Pet Registration:Permanent identification for dogs, cats, and exotic companion species linking animals to owner records. Municipal licensing enforcement and insurance claim verification drive compliance.
- Wildlife Management:Conservation biology applications including migration monitoring, population census, and reintroduction tracking. GPS collars and satellite transmitters enable data collection from remote habitats.
- Disease Control:Epidemiological surveillance and outbreak response requiring rapid animal identification and movement history retrieval. National livestock identification systems in Australia and Brazil prioritize this capability.
Commercial livestock tracking holds established scale. Wildlife management is gaining share fastest as conservation funding expands telemetry deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's SUDENE tax incentive zone concentrates cattle tagging demand among export-oriented ranches. Dutch dairy clusters drive precision livestock adoption. Australian pastoral regions expand GPS collar deployment for extensive grazing management.
United States
Integrated beef packers in Nebraska and Kansas mandate RFID compatibility from feedlot suppliers. USDA APHIS traceability rules compress hardware procurement timelines for commercial cattle operations. Texas Panhandle feeding complexes concentrate reader infrastructure investments.
Brazil
Mato Grosso cattle ranches face EU export verification requirements driving electronic ear tag adoption. MAPA enforces national livestock identification standards aligned with international trade protocols. São Paulo state meatpacking corridors concentrate supplier qualification activity.
Germany
Dairy cooperatives in Lower Saxony deploy ISO-compliant RFID for EU bovine EID mandate compliance. BMEL coordinates federal animal health database interoperability with member state systems. Bavarian alpine cattle operations accelerate infrastructure replacement before regulatory deadlines.
Australia
Queensland and New South Wales sheep stations adopt GPS-enabled collars for geofencing extensive pastoral leases. NLIS maintains national traceability database standards for export market access. Victoria's dairy regions integrate precision farming systems with identification hardware.
Netherlands
Dutch dairy operations in Friesland and Overijssel pioneer RFID integration with robotic milking systems. EU Commission Delegated Regulation on bovine electronic identification drives nationwide infrastructure standardization. Wageningen agricultural research clusters test next-generation sensor platforms.
Animal Identification Market Competitive Landscape
North American technology providers anchor one tier; European specialists hold regulatory compliance expertise. The supplier base concentrates around ISO certification capabilities and veterinary market access credentials. Three archetypes dominate: pharmaceutical-heritage conglomerates, RFID-native technology firms, and precision livestock farming integrators. Capacity expansion and strategic technology licensing represent the primary competitive vectors as mandates compress procurement windows.
Among diversified health science conglomerates, Merck & Co., Inc. occupies a position exemplifying pharmaceutical-heritage entry into veterinary-grade identification. RFID-native specialists include Datamars, which represents technology-led positioning across Australasian livestock markets. Nedap N.V. anchors the precision livestock farming integration archetype through Dutch dairy sector concentration. These three exemplify divergent strategic foundations responding to identical regulatory pressures.
| Leading Market Players |
|---|
| HID Global Corporation |
| Nedap N.V. |
| Merck & Co., Inc. |
| GAO RFID |
| Avid Identification Systems, Inc. |
| Datamars |
| Shearwell Data Ltd. |
| Avery Dennison Corporation |
| Allflex |
| Others |
Value Network & Pricing Analysis
Copper futures volatility on the London Metal Exchange cascades through RFID antenna coil production costs, compressing margins for standard-tier ear tag suppliers while ISO-certified vendors capture premium pricing through guaranteed compliance delivery.
Pricing Analysis
Short lead-time premiums of 15-20% apply to emergency procurement of USDA-compliant RFID readers by Texas feedlot operators facing APHIS traceability deadlines. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and volume commitment, with integrated protein packers commanding lowest unit costs through consolidated offtake agreements. Pricing pressure stems from semiconductor foundry concentration in Taiwan and South Korea, which extends component lead times and forces buyers toward spot-market premiums. Smallholder dairy cooperatives in Kenya and Colombia exhibit highest price sensitivity, prioritizing Bluetooth Low Energy smartphone-based systems over fixed reader infrastructure.
Supply Chain Analysis
RFID transponder assembly rests on concentrated foundry capacity in Taiwan, South Korea, and mainland China, with glass-encapsulated microchip production anchored in German and Swiss precision manufacturing facilities. Critical inputs include copper antenna wire, ferrite core materials, and biocompatible glass tubing for implantable devices. Single-source vulnerability in advanced semiconductor lithography exposes lead times to geopolitical friction and export control restrictions. Distribution runs through agricultural supply cooperatives in Brazil's Mato Grosso, veterinary distributor networks in Germany's Lower Saxony, and direct-to-producer digital channels accelerating in Australian pastoral regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Animal Identification Market has become a vertical-integration race, with hardware suppliers acquiring cloud database capabilities and protein packers bringing tag specification authority in-house to lock in traceability compliance.
For Market Incumbents: Extend ISO 11784/11785 certification coverage into emerging Bluetooth Low Energy and edge-computing product lines before regulatory harmonization favors multi-protocol vendors. Acquire veterinary telemedicine platforms or partner with precision livestock farming integrators to capture recurring subscription revenue beyond transactional tag sales. Defend against disintermediation by integrated protein packers through exclusive data-sharing agreements with national livestock identification systems in Australia and Brazil. For New Entrants and Emerging Players: Launch via direct-to-producer e-commerce channels targeting companion animal microchipping underpenetration in Indian and Southeast Asian urban centers, bypassing established veterinary distributor networks. Prioritize smartphone-based tag reading solutions for smallholder dairy cooperatives in Kenya and Colombia where capital constraints exclude fixed reader infrastructure. White-space concentration sits with AI-powered behavioral analytics subscriptions layered atop commodity RFID hardware. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision livestock farming integrators with established Dutch dairy sector relationships and ISO-certified hardware suppliers facing semiconductor input cost compression. Long-term viability hinges on regulatory compliance moats deepening through EU-APHIS database interoperability mandates. Acquisition target archetypes include RFID-native technology firms with Australasian livestock market penetration and veterinary-grade database operators. Watch for EU Commission Delegated Regulation enforcement deadlines as demand inflection triggers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Sourcing | Captive supply of RFID transponder chips insulates margins from Taiwan foundry lead-time volatility. |
| Cloud Database Acquisition | Ownership of ISO 11784/11785-compliant pet registration platforms locks in recurring subscription revenue streams. |
| Bluetooth Low Energy Product Launch | Smartphone-based tag reading bypasses costly fixed infrastructure for Kenya and Colombia smallholder cooperatives. |
| Precision Livestock Farming Partnership | Integration with Nedap-style robotic milking systems deepens Dutch dairy sector account control. |
| EU-APHIS Regulatory Harmonization Investment | Early compliance with interoperability standards secures premium positioning in cross-border beef export channels. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by structured interviews with livestock tagging equipment procurement managers at Brazilian protein packers, Dutch dairy cooperative technology directors, and Australian pastoral station managers. Primary fieldwork encompassed veterinary practitioners administering ISO-compliant microchips, agricultural supply cooperative inventory planners, and precision livestock farming systems integrators. Secondary sources included USDA APHIS traceability rule dockets, EU Commission Delegated Regulation submissions, Brazil MAPA enforcement records, and Australia NLIS database specifications. Bottom-up unit deployment estimates by species and region triangulated against top-down market value reconstructions.
Granularity-level modeling operated at individual country-product-technology intersections, with separate trajectory builds for RFID, GPS, barcode, and infrared identification systems across cattle, sheep, swine, poultry, and companion animal applications. CAGRs derived from logistic diffusion curves fitted to regulatory mandate enforcement timelines and protein packer procurement concentration patterns. Forecast inputs incorporated EU bovine EID compliance deadlines, Brazilian SUDENE tax incentive zone expansion, and Australian pastoral geofencing adoption rates. Volume projections reconciled against import-export flows from customs records and national livestock identification system registration growth.
Semiconductor supply disruption, EU-APHIS regulatory harmonization delays, and copper commodity price spikes are the dominant revision risks to baseline deployment assumptions. Forecasts embed assumptions regarding ISO certification maintenance, foundry capacity allocation priorities, and protein packer vertical integration timelines. A small set of named triggers—Taiwan Strait logistics interruption, EU database interoperability mandate acceleration, and JBS-Tyson-Cargill procurement standard consolidation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Africa Ruminant Feed Premix Market
Livestock Management
Feed Management Software Market
Livestock Management
Cattle Head Catch Market
Livestock Management
Cattle Management Software Market
Livestock Management
Colombia Animal Feed Market
Livestock Management
Cattle Mineral Feeder Market
Livestock Management
Saudi Arabia Poultry Market
Livestock Management
Bird Feeder Market
Livestock Management
Cattle Feeder Market
Livestock Management
Smart Feeding Systems Market
Livestock Management
Swine Artificial Insemination Market
Livestock Management
Digital Livestock Farming Market
Livestock Management
South America Ruminant Feed Market
Livestock Management
Hog Production and Pork Market
Livestock Management
Europe Swine Feed Market
Livestock Management
Roughage Feed Market