
 Global Insufflation Devices Market | 2026-2036
Global Insufflation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Insufflation Devices Market Foresight
Polymer composites in tubing sets are repositioning cost structures across the insufflation device supply chain. Olympus leverages captive manufacturing of endoscopic insufflators to sustain margin control in Japan and Europe. Stryker competes through integrated surgical platform bundles that anchor hospital purchasing decisions. Medtronic differentiates via connected-device architectures that extend digital service revenue beyond hardware sales.
Insufflation devices regulate pressurized gas delivery into body cavities to create operative workspace during minimally invasive surgery, typically maintaining CO2 pressures between 12 and 15 mmHg through electromechanical pump systems with real-time pressure sensing and automatic feedback loops. Insufflators dominate product type revenue due to their central role in every laparoscopic procedure, while safety valve systems represent the fastest-growing technology segment as liability-conscious hospitals prioritize patient protection. Ambulatory surgery centers constitute the most rapidly expanding end user channel, though specialty clinics still occupy the deepest installed base for replacement cycles.
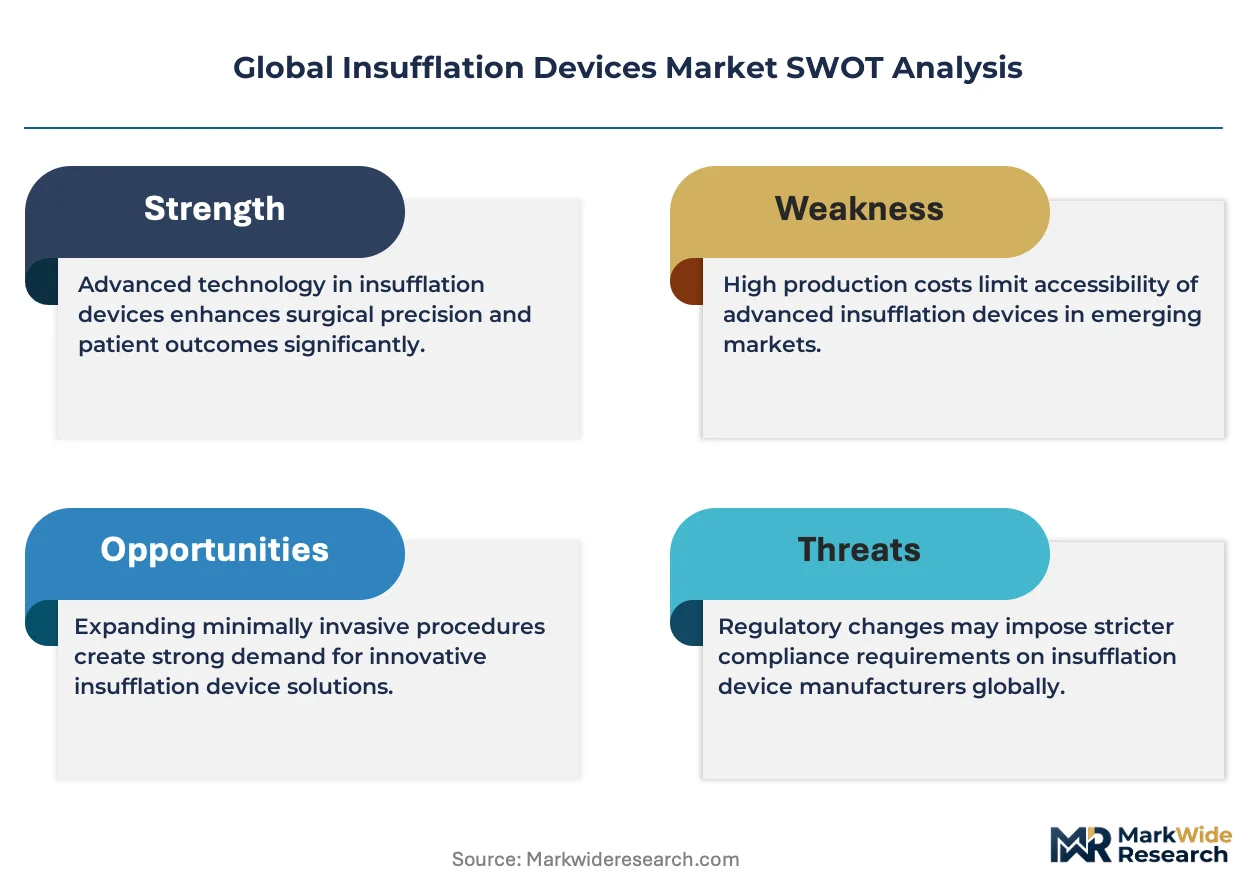
FDA 510(k) clearance pathways govern US market entry for insufflation systems, while the EU MDR and CE marking requirements are extending documentation burdens for gas delivery device manufacturers. Japan's PMDA enforces JIS-aligned electrical safety standards that shape product design for Asia-Pacific submissions. Stakeholders must monitor evolving carbon footprint regulations for disposable insufflation tubing and filtration consumables as sustainability criteria penetrate surgical supply procurement.
Market Dynamics
EU MDR documentation burdens are compressing manufacturer margins while surgical robot installations in Germany and Japan are forcing paired insufflator upgrade cycles that reshape procurement patterns.
Growth Catalysts
- Minimally invasive procedure volume expansion:Laparoscopic surgery suites in German hospitals are expanding insufflation system procurement as operative workspace requirements intensify.
- EU MDR compliance upgrades:Tightened conformity requirements for gas delivery components are mandating replacement of legacy insufflator installations across European surgical facilities.
- Surgical robotics pairing:Da Vinci and Versius robot installations in Japan are driving synchronized insufflator upgrades that anchor bundled purchasing decisions.
Market Restraints
- Polymer composite input volatility:Specialized tubing-grade polymers face price instability that compresses disposable set margins for insufflation accessory suppliers.
- Supply concentration in precision pump manufacturing:Electromechanical pressure pump assembly concentrates among German and Japanese component specialists, creating single-source vulnerability.
- CO2 delivery technical limitations:Humidity control and filtration standards in high-flow insufflation create performance ceilings that constrain procedure efficiency gains.
Strategic Opportunities
- Connected-device service revenue:Real-time pressure monitoring and predictive maintenance architectures enable recurring digital revenue streams beyond hardware sales.
- Ambulatory surgery center channel expansion:ASCs in the United States represent underpenetrated demand for compact, high-throughput insufflation systems with rapid turnover capability.
- Sustainability-driven consumable redesign:Carbon footprint regulations for disposable tubing and filtration components in the European Union create first-mover advantage for biodegradable material innovators.
Industry Challenges
- Biomedical engineering talent scarcity:Electromechanical system design expertise for pressure feedback loops remains concentrated among specialists in Germany and Japan, constraining R&D scaling.
- MDR technical documentation timelines:Extended CE marking pathways for gas delivery devices delay product launches by 18-24 months, compressing competitive windows.
- Legacy system integration complexity:New insufflator architectures must interface with installed endoscopic towers from multiple manufacturers, multiplying validation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Insufflation Devices Market |
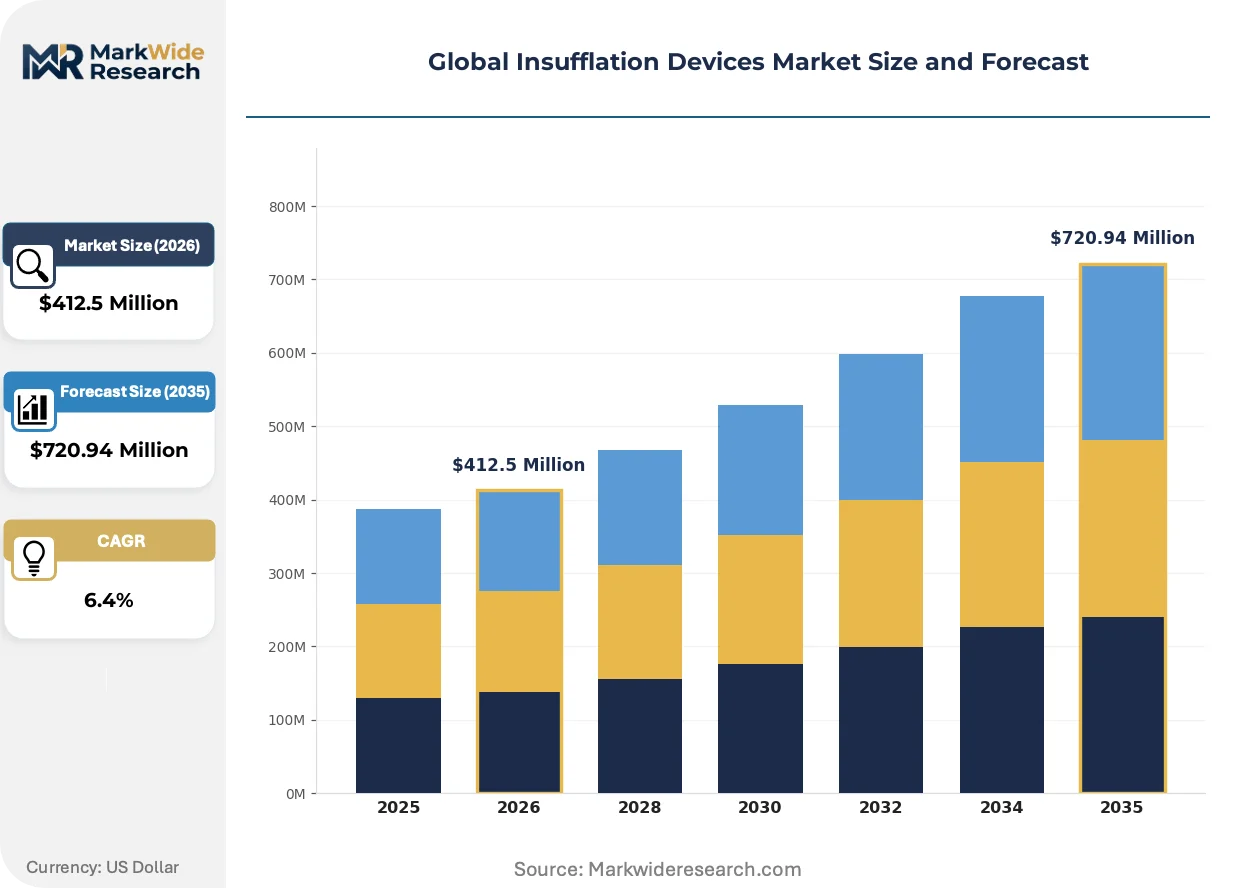
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insufflators, Gas Delivery Systems, Suction & Irrigation Devices, Insufflation Tubes, Filtration Units Technology: Automatic Pressure Control, Manual Pressure Control, Insufflation Flow Regulation, CO2 Delivery Technology, Safety Valve Systems Application: Laparoscopy, Endoscopy, Arthroscopy, Thoracoscopy, Urology Procedures End User: Ambulatory Surgery Centers, Specialty Clinics, Diagnostic Centers, Research Institutes, Veterinary Facilities |
| Companies Covered | Olympus, STERIS, Medtronic, Fujifilm, BD, Stryker, Smith & Nephew, B. Braun Melsungen, Karl Storz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Insufflation Devices Market Shifts & Advancements
Digital connectivity architectures and material science advances are restructuring how insufflation systems generate value, while regulatory frameworks in Europe and Asia-Pacific are accelerating compliance-driven product refresh cycles.
Smart insufflation platforms with embedded pressure sensing and automatic feedback loops are rewriting competitive positioning in the premium segment. Academic medical centers in Germany and Japan are adopting these systems at accelerated pace. The technology is compressing service contract structures toward predictive maintenance models that lock in multi-year revenue streams.
EU MDR Annex I general safety and performance requirements are extending clinical evaluation burdens for gas delivery device manufacturers. Technical documentation demands for biocompatibility and electrical safety have intensified. Class IIa insufflator submissions now face prolonged notified body review timelines that favor established players with regulatory affairs scale.
Hospital procurement departments are consolidating vendor relationships around integrated surgical platform bundles that span visualization, insufflation, and energy systems. Specialty clinics with deep installed bases are resisting this consolidation, preferring component-level sourcing that preserves flexibility. The tension is most visible in France and Italy, where regional purchasing cooperatives are fragmenting between centralized and decentralized models.
Global Insufflation Devices Market Segmentation
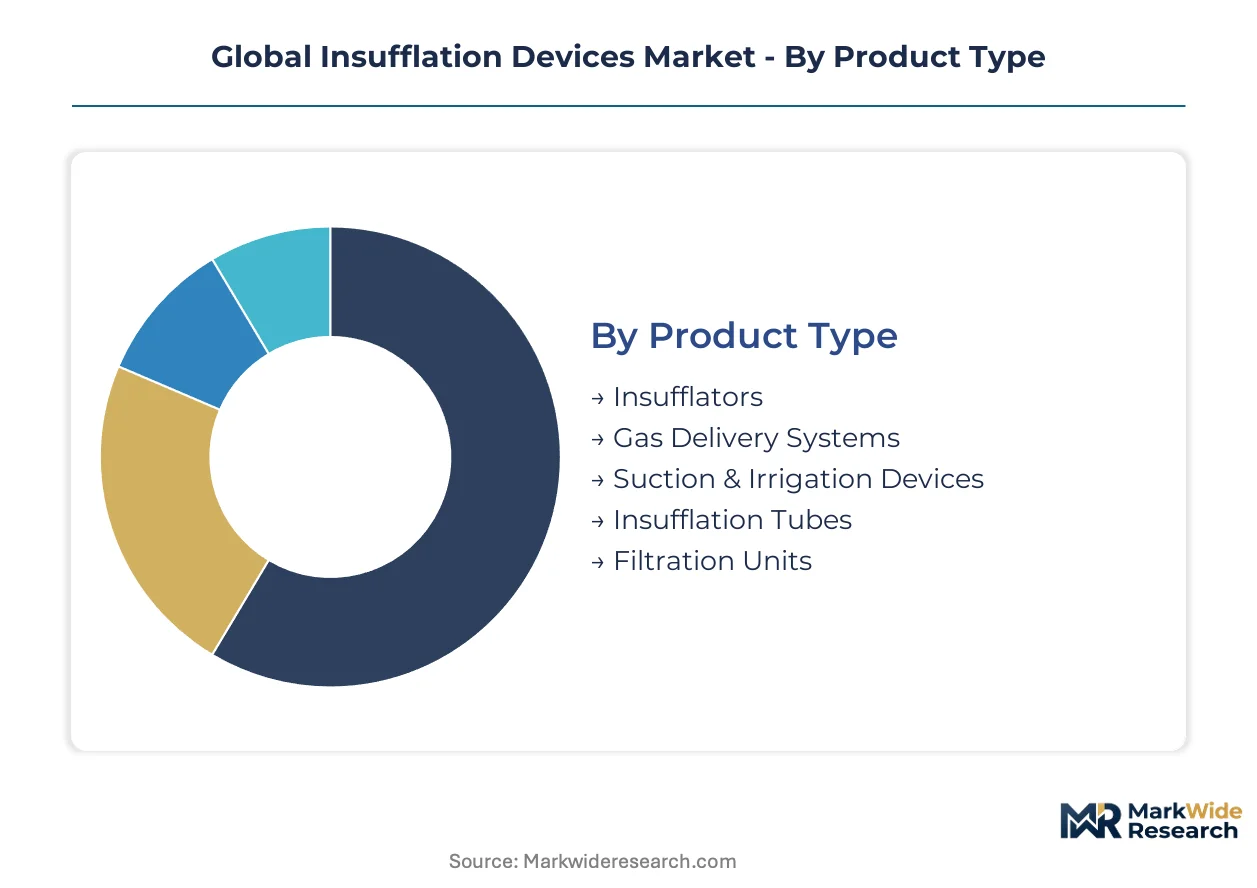
Segmentation in the insufflation devices market reveals how capital allocation, regulatory exposure, and procedure economics divide purchasing power across hardware systems, consumable attachments, and service architectures. Understanding these fault lines clarifies where manufacturers must concentrate R&D investment versus where commoditization pressures dominate.
Product Type:
Capital intensity varies sharply across this category, with electromechanical pump systems demanding the heaviest upfront manufacturing investment while disposable tubing sets operate on high-volume, low-margin economics.
- Insufflators:Electromechanical pump systems with real-time pressure sensing and automatic feedback loops form the core revenue engine. German and Japanese hospitals anchor replacement demand as surgical robot installations force paired upgrade cycles.
- Gas Delivery Systems:Integrated CO2 regulation modules with humidity control and filtration subsystems command premium positioning. Academic medical centers in Japan adopt these configurations at accelerated pace for high-flow laparoscopic suites.
- Suction & Irrigation Devices:Auxiliary fluid management attachments complete operative workspace systems in integrated surgical platforms.
- Insufflation Tubes:Polymer composite disposable sets face carbon footprint regulatory pressure in the European Union.
- Filtration Units:Bacterial and viral barrier consumables represent recurring revenue streams tied to procedure volume.
Insufflators absorb the bulk of installed capacity; filtration units are expanding most quickly as liability-conscious facilities mandate single-use barriers.
Technology:
Margin structures in this category stratify sharply between premium automated architectures and legacy manual systems facing replacement pressure from EU MDR compliance mandates.
- Automatic Pressure Control:Embedded sensor arrays with predictive maintenance algorithms enable multi-year service contracts. German academic centers drive adoption as bundled purchasing with surgical robots becomes standard.
- Safety Valve Systems:Redundant pressure relief mechanisms with real-time alarm protocols represent the fastest-growing technology segment. Liability exposure in French and Italian hospitals accelerates procurement of patient protection features.
- Manual Pressure Control:Dial-based regulation interfaces persist in cost-constrained veterinary and diagnostic settings.
- Insufflation Flow Regulation:High-flow rate management modules address efficiency demands in high-volume ambulatory surgery centers.
- CO2 Delivery Technology:Humidity and temperature conditioning subsystems hit performance ceilings in prolonged procedures.
Automatic pressure control commands the deepest installed base; safety valve systems are gaining share fastest as regulatory and liability pressures intensify.
Application:
Procedure volume concentration and reimbursement economics determine where insufflation system specifications tighten versus where standard configurations suffice.
- Laparoscopy:Abdominal cavity insufflation for minimally invasive general surgery generates the dominant procedure volume. German hospital expansion of laparoscopic suites drives synchronized insufflator procurement.
- Endoscopy:Gastrointestinal and bronchial workspace creation demands specialized low-pressure protocols. Japanese endoscopy volume sustains captive manufacturing advantages for domestic suppliers.
- Arthroscopy:Joint cavity distension for orthopedic procedures requires compact, high-precision pressure management.
- Thoracoscopy:Pleural space insufflation carries elevated safety requirements that favor automated pressure architectures.
- Urology Procedures:Retroperitoneal and pelvic cavity distension applications concentrate in specialty clinic settings.
Laparoscopy anchors the deepest procedure volume; endoscopy is climbing the fastest as screening program expansions in Japan and Germany drive demand.
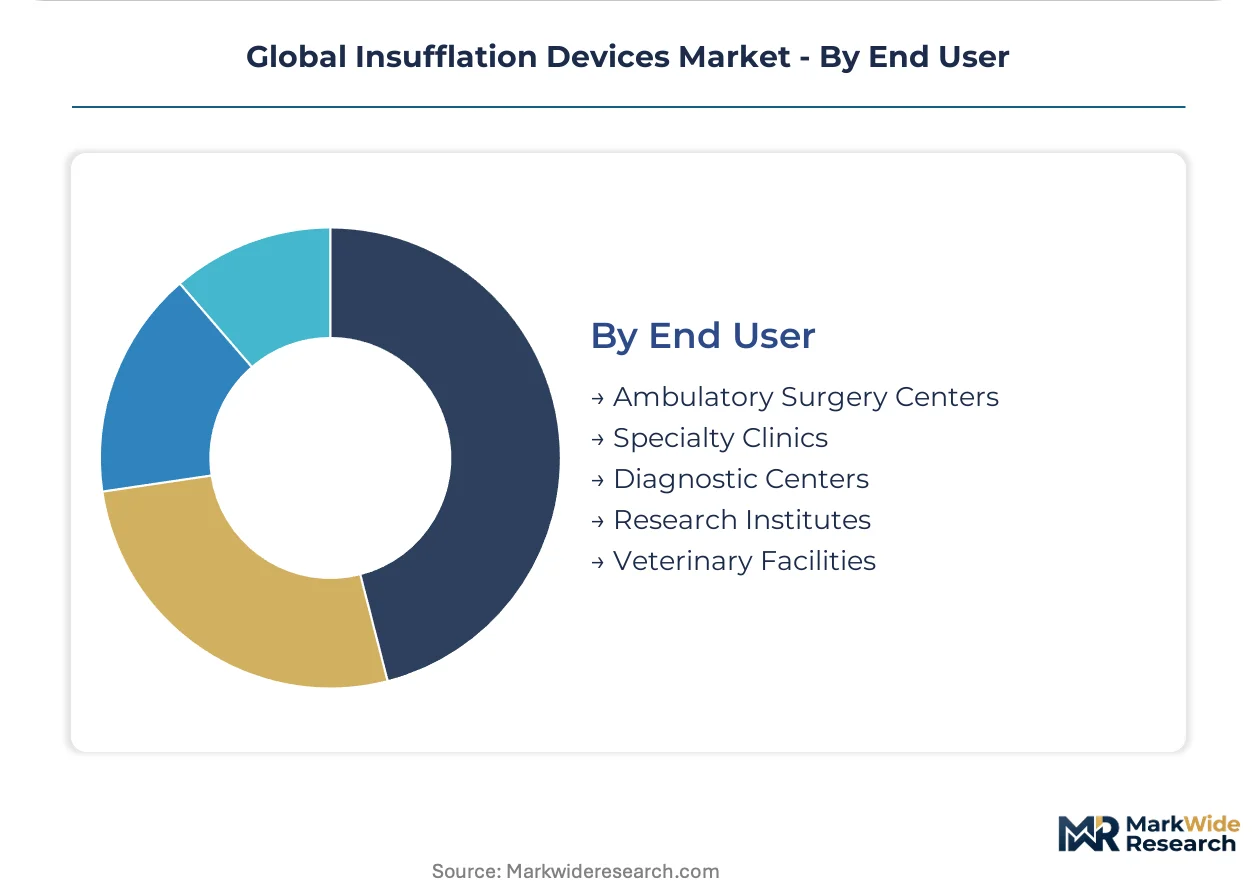
End User:
Procurement sophistication and capital access separate institutional buyers with integrated platform purchasing power from fragmented operators prioritizing component flexibility.
- Ambulatory Surgery Centers:High-throughput, rapid-turnover facilities in the United States represent underpenetrated demand for compact insufflation systems. Medicare reimbursement shifts toward outpatient settings accelerate capital deployment.
- Specialty Clinics:Deep installed bases in France and Italy resist vendor consolidation, preferring component-level sourcing that preserves interoperability with mixed-manufacturer endoscopic towers.
- Diagnostic Centers:Lower procedure volumes favor refurbished or entry-tier system configurations.
- Research Institutes:Preclinical and training applications drive demand for modular, reconfigurable insufflation platforms.
- Veterinary Facilities:Price-sensitive companion animal surgical settings standardize on manual pressure control systems.
Specialty clinics hold the deepest installed base; ambulatory surgery centers are expanding most quickly as outpatient migration reshapes procedure economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for medical technology manufacturing in Germany, Japan, and the United States concentrate insufflation device production capacity and R&D investment. Regulatory harmonization pressures across these jurisdictions reshape cross-border procurement patterns. Urban hospital clusters in each country anchor demand for next-generation surgical gas delivery systems.
United States
Ambulatory surgery center expansion across Texas and Florida drives demand for compact, high-throughput insufflation systems. FDA 510(k) clearance pathways govern market entry for electromechanical pump systems. The Greater Boston medical technology corridor hosts precision pump component specialists supplying domestic manufacturers.
Germany
Surgical robot installations in Bavaria and North Rhine-Westphalia force paired insufflator upgrade cycles among hospital systems. EU MDR conformity requirements tighten documentation burdens for gas delivery device manufacturers. The Stuttgart industrial cluster concentrates electromechanical pressure pump assembly capacity for European supply chains.
Japan
Endoscopy volume in Tokyo and Osaka sustains captive manufacturing advantages for domestic insufflator producers. PMDA enforces JIS-aligned electrical safety standards that shape product design for Asia-Pacific submissions. The Nagoya medical device manufacturing hub specializes in sensor-integrated pressure control modules.
United Kingdom
NHS procurement consolidation favors integrated surgical platform bundles spanning visualization and insufflation systems. MHRA post-Brexit regulatory divergence creates parallel conformity assessment requirements for gas delivery devices. The Cambridge-Oxford-London biotech triangle attracts connected-device R&D for predictive maintenance architectures.
France
Regional purchasing cooperatives in Île-de-France and Auvergne-Rhône-Alpes fragment between centralized platform bundles and component-level sourcing. ANSM vigilance reporting requirements intensify post-market surveillance for insufflation safety systems. The Lyon surgical instrument cluster specializes in disposable tubing and filtration consumables.
Global Insufflation Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors commanding hospital purchasing decisions while component suppliers serve specialty clinics. The vendor base concentrates among electromechanical system designers in Germany and Japan, with secondary fabrication capacity emerging in China and India. Three archetypes dominate: diversified medtech conglomerates with surgical robotics alignment, endoscopy-focused specialists with captive insufflator production, and precision pump component suppliers serving multiple OEMs. M&A activity targets connected-device capabilities and regulatory affairs scale, while geographic expansion focuses on ambulatory surgery center channels in the United States.
Among diversified medtech conglomerates, Olympus and Stryker exemplify contrasting strategic positions. Olympus leverages Japanese captive manufacturing of endoscopic insufflators to sustain margin control across Asia-Pacific and European markets. Stryker competes through integrated surgical platform bundles that anchor hospital purchasing decisions in North America. Medtronic occupies a distinct position via connected-device architectures that extend digital service revenue beyond hardware sales. These three represent how scale, specialization, and service integration split competitive terrain.
| Leading Market Players |
|---|
| Olympus |
| STERIS |
| Medtronic |
| Fujifilm |
| BD |
| Stryker |
| Smith & Nephew |
| B. Braun Melsungen |
| Karl Storz |
| Others |
Supply & Pricing Matrix
EU carbon footprint mandates for disposable medical tubing gate qualified supply and premium-tier pricing access, forcing manufacturers to source certified polymer composites or forfeit high-margin hospital contracts in Germany and France. This environmental compliance layer stratifies the supplier base between sustainability-certified premium vendors and price-competitive uncertified alternatives.
Pricing Analysis
Lead-time-driven pricing separates urgent procurement premiums from spot inventory discounts across German and Japanese hospital systems. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and bundled service intensity. Pricing pressure stems from polymer composite input volatility compressing disposable set margins. Ambulatory surgery centers in Texas and Florida exhibit highest price sensitivity, while academic medical centers in Bavaria and Tokyo absorb premium positioning for robot-paired systems.
Supply Chain Analysis
Precision electromechanical pump assembly rests on German and Japanese component specialists, with secondary fabrication emerging in China and India. Medical-grade polymer composites for tubing sets draw from specialized chemical producers in Germany and the United States. Single-source vulnerability concentrates in sensor-integrated pressure control modules from Nagoya industrial clusters. Distribution runs through regional medical device distributors serving hospital systems and GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The insufflation devices market sits in a technology-transition phase as smart pressure-sensing architectures with predictive maintenance capabilities displace legacy manual control systems across European and Asia-Pacific surgical facilities.
For Market Incumbents: Hedge against regulatory compliance cost escalation by accelerating EU MDR technical documentation completion for legacy system replacements. Prioritize backward integration into polymer composite tubing manufacturing to defend margin position against input price volatility. Lock in multi-year service contracts with German hospital systems undergoing synchronized robot-paired upgrade cycles.
For New Entrants and Emerging Players: Ambulatory surgery center distributors represent the most penetrable channel partner type for compact high-throughput system penetration. Target rapid-turnover ASCs in Texas and Florida with rapid-installation configurations and competitive leasing structures. Pursue white-label manufacturing partnerships with established precision pump component suppliers to bypass R&D scale barriers.
For Investors and Strategic Acquirers: Surgical robot installation announcements in Germany and Japan are the leading indicator that paired insufflator upgrade demand will concentrate in specific hospital systems. Long-term viability favors connected-device specialists with recurring digital revenue architectures over pure hardware manufacturers. Watch EU MDR notified body review timeline extensions as the signal for competitive window compression favoring regulatory affairs scale.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR compliance speed determines competitive positioning in German hospital procurement cycles. |
| Hospital System Partnership | Bundled purchasing with surgical robot installations anchors multi-year insufflator upgrade commitments. |
| Software Companion Development | Predictive maintenance algorithms enable recurring service revenue beyond hardware transaction margins. |
| Backward Integration into Tubing | Captive polymer composite supply insulates margin from carbon footprint regulation compliance costs. |
| Reimbursement Strategy Alignment | Medicare outpatient migration in the United States shapes ASC capital deployment for compact systems. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and GPO contract records, complemented by interviews with biomedical engineers, hospital purchasing committee members, surgical robotics program directors, and regulatory affairs specialists at gas delivery device manufacturers. Secondary validation drew from SEC filings, notified body guidance documents, and trade customs data. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation anchored market sizing.
Segment-level outputs across product type, technology tier, application specialty, and end-user channel were generated through the projection horizon. CAGRs derived from procedure volume trajectories, replacement cycle timing, and compliance-driven refresh patterns. Forecast inputs incorporated surgical robot installation pipelines, EU MDR implementation timelines, and ambulatory surgery center reimbursement shifts.
Caveats apply where EU MDR notified body capacity constraints, polymer composite supply disruptions, or surgical robot adoption delays could materially shift the outlook. A small set of named triggers including MDR documentation timeline extensions and carbon footprint regulation enforcement intensity warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Brazil Respiratory Devices Market
Medical Devices
MRI Safe Neurostimulation Systems Market
Medical Devices
Concentrator O2 Devices Market
Medical Devices
Digital Stethoscope Market
Medical Devices
Memory Implants Market
Medical Devices
Manometry System Market
Medical Devices
Annuloplasty System Market
Medical Devices
Electronic Nasal Spray Devices Market
Medical Devices
Global Pregnancy Detection Kits Market
Medical Devices
Deflectable Catheters Market
Medical Devices
South Africa General Surgical Devices Market
Medical Devices
Global Nerve Monitoring System Market
Medical Devices
Brazil Clear Aligners Market
Medical Devices
Artificial Eye Lenses Market
Medical Devices
Left Atrial Appendage (LAA) Closure Device Market
Medical Devices
Infertility Devices Market