
 Asia-Pacific Large Wind Turbine Market | 2026-2036
Asia-Pacific Large Wind Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Large Wind Turbine Market Outlook
Consolidation among state-owned utilities and independent power producers is realigning procurement patterns across the Asia-Pacific large wind turbine landscape. Goldwind leverages its captive blade manufacturing and coastal installation footprint to anchor contracts in China's offshore zones. Siemens Gamesa Renewable Energy SA competes through advanced drivetrain designs tailored for typhoon-resistant installations. Mingyang Smart Energy extends its position in the South China Sea with semi-submersible platform integrations.
Asia-Pacific large wind turbines are horizontal-axis or vertical-axis machines with rotor diameters exceeding 120 meters, designed to convert kinetic wind energy into grid-scale electricity through variable-speed generators and pitch-controlled blades. The primary commercial purpose centers on utility-scale power generation for integration into national transmission networks. Offshore product types command premium engineering margins due to foundation complexity and salt-corrosion resistance requirements, while onshore horizontal-axis units dominate volume deployment across inland provinces. Gearless direct-drive technology leads in offshore applications where maintenance access constraints favor reduced mechanical complexity, and smart turbine systems with predictive analytics are capturing growing share among independent power producers seeking optimized yield curves.
China's MIIT enforces GB standards for turbine certification and grid-code compliance, while Japan's METI administers offshore zoning and feed-in tariff qualification processes that shape project economics. Australia's Clean Energy Regulator and India's CEA impose local content and grid-stability requirements that condition market access for foreign OEMs. Stakeholders must monitor evolving seabed leasing frameworks and cross-border cable interconnection rules as these regulatory layers increasingly determine project bankability and equipment specification across the region.
Market Dynamics
China's MIIT offshore certification mandates are compressing nacelle replacement cycles across Jiangsu and Guangdong clusters, forcing turbine OEMs to accelerate blade and drivetrain refresh timelines while state-backed utilities consolidate procurement volumes.
Growth Catalysts
- Feed-in tariff revisions:Japan's METI has recalibrated offshore wind pricing bands, triggering project restarts in Kyushu and Hokkaido development zones. Independent power producers are advancing construction timelines to lock in grandfathered rates.
- Direct-drive technology maturation:Gearless generator architectures are eliminating gearbox maintenance burdens in typhoon-exposed installations. Offshore operators in the South China Sea prioritize these systems for reduced crew-vessel dispatch frequency.
- Grid interconnection investments:State Grid Corporation of China is expanding high-voltage direct current trunk lines from coastal generation hubs to inland load centers. This infrastructure buildout absorbs higher renewable penetration without stability curtailment.
Market Restraints
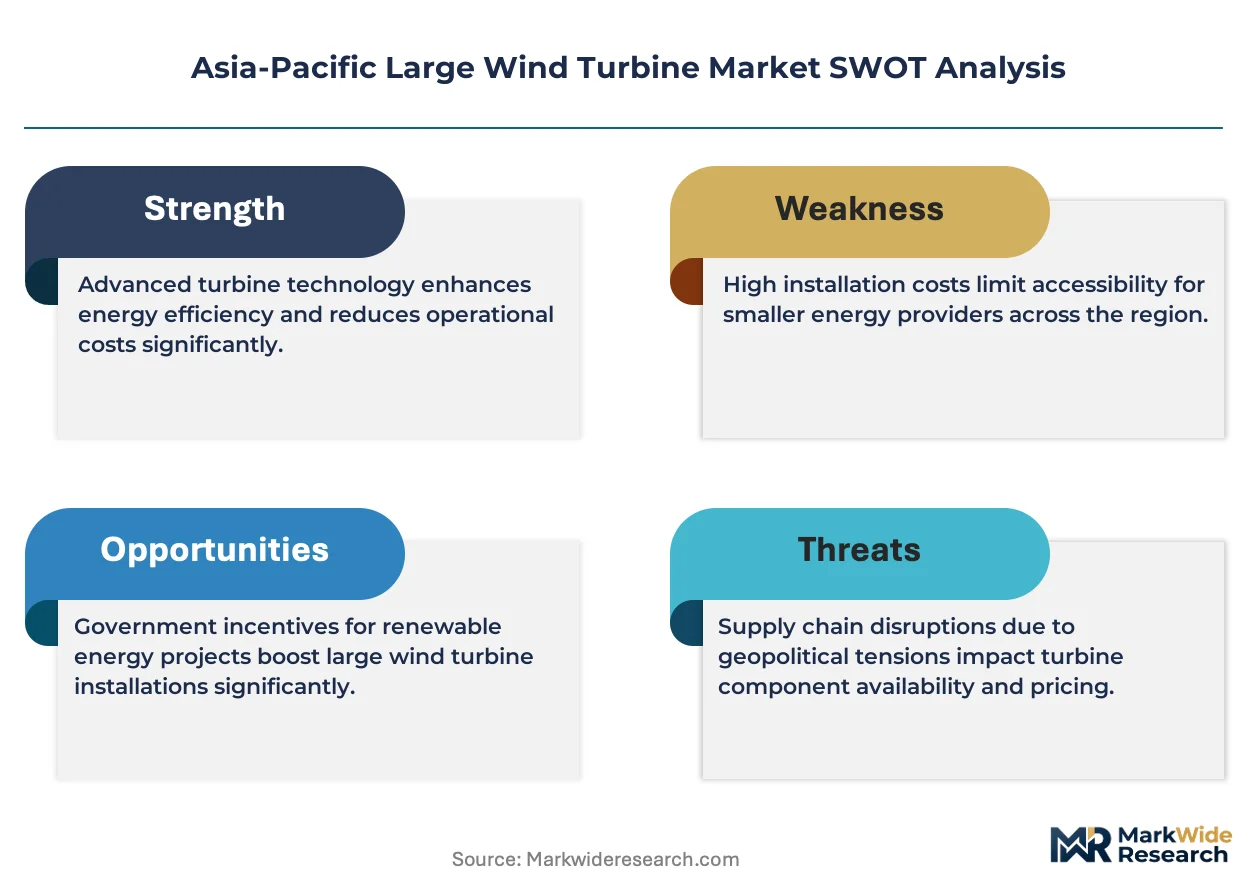
- Rare earth magnet dependency:Neodymium-iron-boron supply concentrates in Chinese processing facilities, exposing direct-drive turbine costs to export quota volatility and geopolitical friction.
- Foundation engineering complexity:Monopile and jacket substructure fabrication requires specialized yards with limited capacity across East Asian shipbuilding corridors, extending project lead times.
- Seabed leasing framework gaps:Australia's offshore zoning authority has delayed competitive auction rounds pending marine spatial planning completion, freezing early-mover project pipelines.
Strategic Opportunities
- Floating platform deployment:Semi-submersible foundations unlock wind resource access in Japan's deep-water Pacific Exclusive Economic Zone where fixed-bottom structures prove uneconomical.
- India's CEA renewable purchase obligations:State distribution companies must procure specified percentages from wind sources, creating offtake certainty for Gujarat and Tamil Nadu project developers.
- Predictive analytics convergence:Machine learning models trained on SCADA telemetry are automating blade pitch optimization and drivetrain thermal management, reducing unplanned downtime for independent power producers.
Industry Challenges
- Composite blade technician shortage:Vacuum infusion and resin transfer molding expertise remains scarce across Southeast Asian manufacturing hubs, constraining production scale-up for 120-meter-plus rotor platforms.
- Cross-border cable permitting:Submarine interconnector approvals involving multiple national maritime authorities create timeline uncertainty for multi-jurisdiction wind farm clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Large Wind Turbine Market |
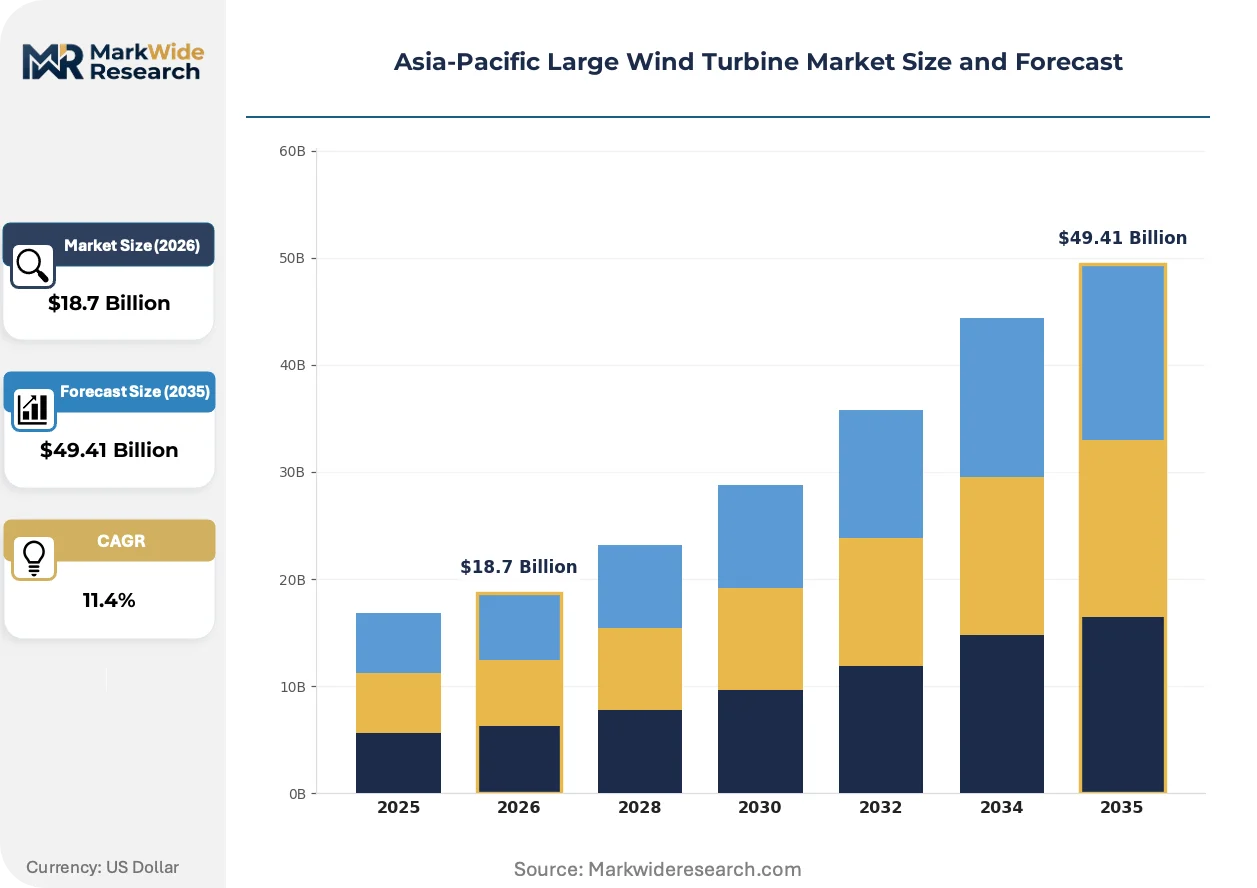
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Axis, Vertical Axis, Offshore, Onshore End User: Utilities, Independent Power Producers, Government, Industries Installation Type: Foundation, Tower, Rotor, Electrical System Technology: Gearless, Advanced Control, Smart Turbines, Hybrid Systems |
| Companies Covered | Vestas Wind Systems AS, Siemens Gamesa Renewable Energy SA, Goldwind, Suzlon Energy Limited, General Electric Company, Nordex SE, Mingyang Smart Energy, Envision Energy, Enercon GmbH, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Large Wind Turbine Market Strategic Shifts
Digital twin architectures and autonomous inspection systems are compressing operational expenditure profiles across Asia-Pacific offshore fleets, while regulatory pressure on recyclability forces material science pivots in blade manufacturing.
Condition monitoring systems integrating fiber-optic strain sensors and edge computing nodes are automating structural health assessment for blade root fatigue and tower foundation scour. Offshore operators in China's Guangdong cluster deploy these systems to reduce manned maintenance vessel rotations. The technology is compressing insurance premium calculations and extending asset residual value estimates for utility-scale portfolios.
China's MIIT has tightened GB standard compliance windows for turbine grid-code synchronization and low-voltage ride-through capability. Domestic OEMs must recertify existing platform designs within abbreviated timelines to maintain interconnection eligibility. This regulatory compression favors established manufacturers with captive testing facilities over newer market entrants dependent on third-party certification bodies.
Utility procurement committees are unbundling turbine supply agreements from long-term service contracts, forcing OEMs to compete on capital cost transparency rather than bundled lifecycle pricing. State-owned power groups in Jiangsu and Shandong provinces now tender equipment and O&M separately, enabling independent service provider entry. This disaggregation is most visible in China's coastal provinces where multiple installation contractors have achieved scale.
Asia-Pacific Large Wind Turbine Market Segmentation
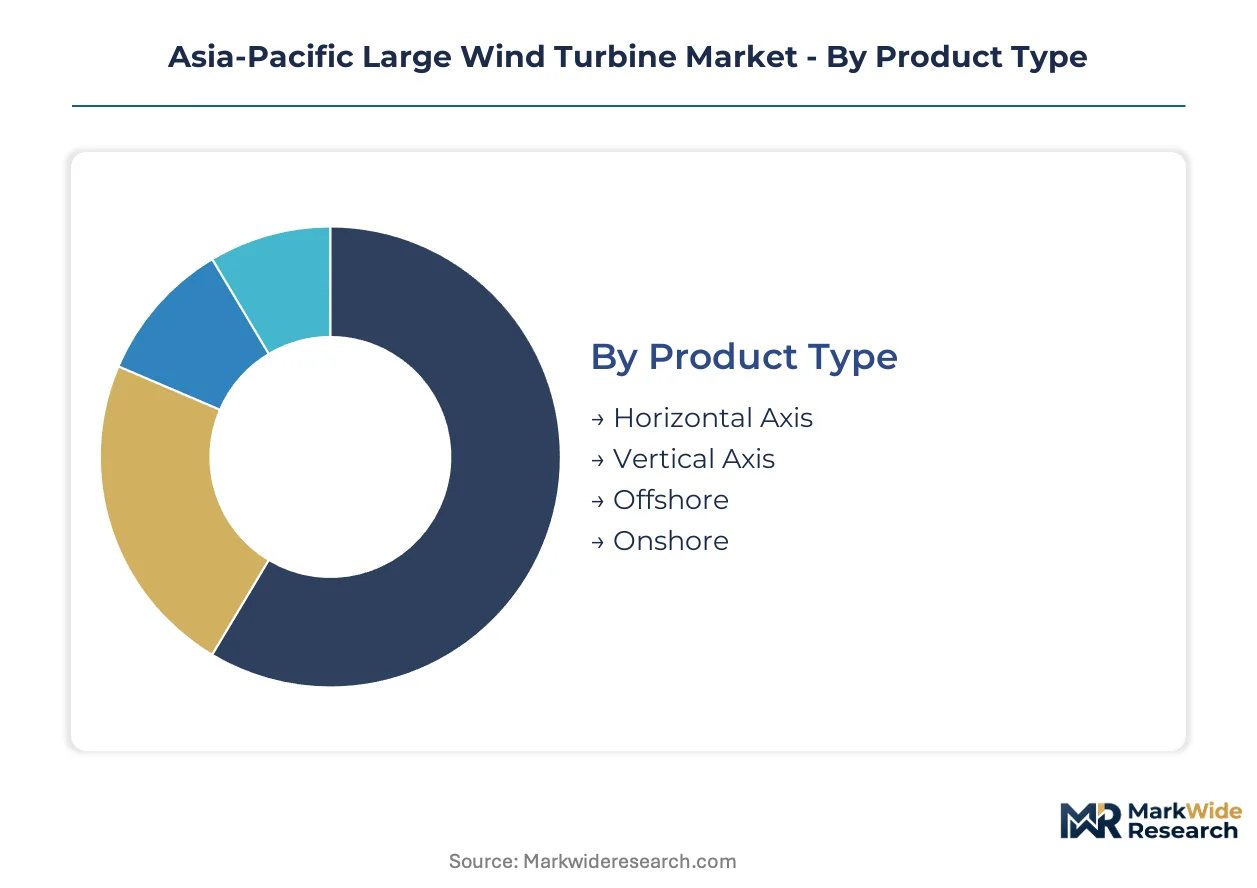
Segmentation in the Asia-Pacific large wind turbine market reveals how certification burdens, grid-code requirements, and foundation complexity reshape procurement economics across distinct equipment categories. Understanding these divisions clarifies why state-backed utilities and independent power producers prioritize different technical specifications in Jiangsu offshore clusters versus inland provinces.
Product Type:
China's MIIT enforces GB certification tiers that separate horizontal-axis platforms from vertical-axis designs, while Japan's METI applies distinct offshore zoning standards that elevate foundation-specific compliance costs for certain product configurations.
- Horizontal Axis:Dominant architecture featuring upwind rotor orientation with three blades mounted on a nacelle housing the drivetrain and generator. Demand concentrates in China's Jiangsu and Guangdong offshore clusters where state-backed utilities require 120-meter-plus rotor diameters for grid-scale capacity additions, though typhoon-resistant blade certification extends procurement timelines.
- Offshore:Purpose-built platforms with corrosion-resistant coatings, integrated transformer stations, and subsea cable termination systems. Procurement in Japan's Kyushu development zone accelerates as METI feed-in tariff revisions trigger project restarts, with semi-submersible foundation compatibility becoming a specified tender requirement.
- Vertical Axis:Darrieus and Savonius configurations capturing omnidirectional wind without yaw mechanisms, suited for distributed applications with lower hub heights.
- Onshore:Conventional tower-mounted systems deployed across inland provinces with standard IEC class certifications and simpler grid synchronization protocols.
Leading the category by volume: Horizontal Axis. Expanding most quickly: Offshore.
End User:
Procurement patterns diverge sharply between state-mandated renewable purchase obligations and merchant power economics, with each end-user category demanding different performance guarantees and service contract structures.
- Utilities:State-owned power groups consolidating equipment orders across provincial portfolios, unbundling turbine supply from long-term O&M contracts to drive capital cost transparency. China's State Grid Corporation procurement committees in Shandong and Jiangsu now tender equipment and maintenance separately, enabling independent service provider competition.
- Independent Power Producers:Merchant developers seeking optimized yield curves through predictive analytics integration and performance-based availability guarantees. These stakeholders prioritize smart turbine systems with SCADA telemetry for automated blade pitch optimization in the South China Sea.
- Government:Direct procurement for public sector renewable targets and demonstration projects with accelerated permitting timelines.
- Industries:Corporate offtake agreements driving captive generation for energy-intensive manufacturing with specific carbon reduction commitments.
Dominant procurement volume: Utilities. Fastest contract expansion: Independent Power Producers.
Installation Type:
Foundation engineering complexity creates the widest cost variance across installation categories, with monopile and jacket substructure fabrication bottlenecked at specialized East Asian shipbuilding yards.
- Foundation:Monopile, jacket, and floating substructures anchoring turbine loads to seabed or mooring systems. Australia's offshore zoning authority delays have frozen early-mover project pipelines pending marine spatial planning completion, while Japan's deep-water Pacific Exclusive Economic Zone unlocks demand for semi-submersible platform integrations.
- Rotor:Hub assembly integrating blades, pitch bearings, and lightning protection systems. Composite blade technician shortages across Southeast Asian manufacturing hubs constrain production scale-up for 120-meter-plus rotor platforms serving utility-scale deployments.
- Tower:Tubular steel or hybrid concrete-steel structures elevating nacelle to hub height with sectional transport logistics.
- Electrical System:Medium-voltage switchgear, transformers, and power conversion equipment managing grid interconnection.
Highest cost concentration: Foundation. Steepest demand trajectory: Rotor.
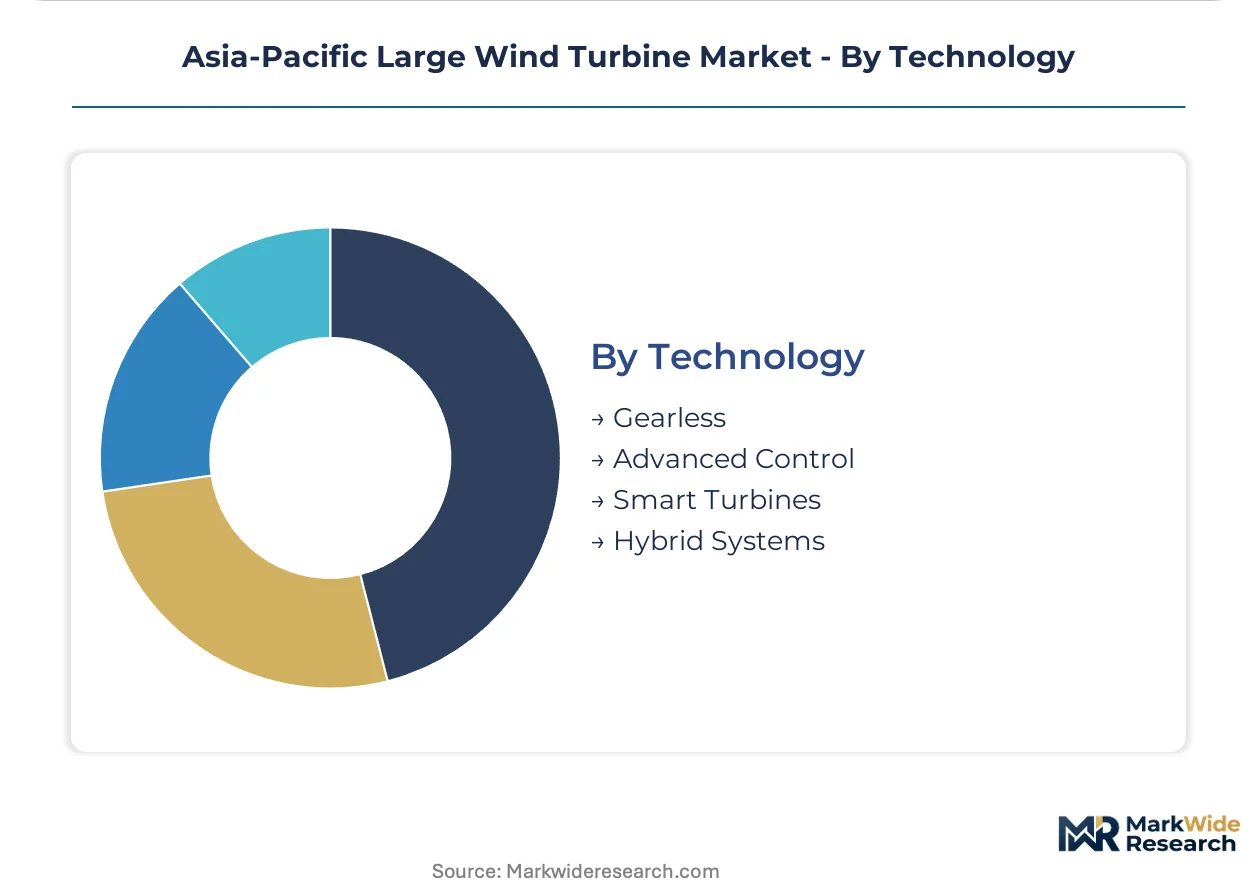
Technology:
Direct-drive architectures eliminate gearbox maintenance burdens but concentrate rare earth magnet exposure to Chinese neodymium-iron-boron processing quotas, reshaping technology selection risk profiles.
- Gearless:Permanent magnet synchronous generators eliminating gearbox components for reduced mechanical complexity and lower crew-vessel dispatch frequency. Offshore operators in typhoon-exposed South China Sea installations prioritize these systems where maintenance access constraints favor simplified drivetrain architectures despite magnet supply vulnerability.
- Smart Turbines:Integrated condition monitoring with fiber-optic strain sensors and edge computing nodes automating structural health assessment. Guangdong cluster deployments compress insurance premiums and extend residual value estimates through automated blade root fatigue detection.
- Advanced Control:Model predictive control algorithms optimizing power capture across variable wind shear conditions.
- Hybrid Systems:Co-located storage integration or multi-source generation combining wind with solar or hydrogen production.
Widest installed base: Gearless. Climbing the fastest: Smart Turbines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility-scale procurement concentrates in China's coastal provinces, where state-backed power groups consolidate orders across Jiangsu and Guangdong offshore clusters. Japan's METI feed-in tariff revisions and Australia's delayed seabed leasing frameworks are redistributing project pipelines across the region.
China
Jiangsu and Guangdong offshore clusters absorb the majority of nacelle and blade upgrades as MIIT certification rules compress replacement cycles. State Grid Corporation expands high-voltage direct current trunk lines from coastal generation hubs to inland load centers. Port infrastructure investments in Yancheng and Zhanjiang outpace other sub-regions.
Japan
Kyushu and Hokkaido development zones restart construction timelines as METI recalibrates offshore wind pricing bands. Independent power producers advance projects to lock in grandfathered rates. Semi-submersible foundation compatibility dominates tender specifications in the deep-water Pacific Exclusive Economic Zone.
India
Gujarat and Tamil Nadu project developers secure offtake certainty through CEA renewable purchase obligations mandating state distribution companies procure specified wind percentages. Local content requirements condition market access for foreign OEMs. Manufacturing scale-up faces composite blade technician shortages across Southeast Asian hubs.
Australia
Offshore zoning authority delays freeze early-mover project pipelines pending marine spatial planning completion. The Clean Energy Regulator imposes grid-stability requirements that shape equipment specifications. Competitive auction rounds remain suspended, redirecting developer attention toward onshore repowering opportunities.
South Korea
Busan-Ulsan shipbuilding corridors bottleneck monopile and jacket substructure fabrication capacity, extending project lead times. National offshore wind targets drive procurement committee formation at state utilities. Yeongnam region yards specialize in typhoon-resistant foundation engineering for export markets.
Asia-Pacific Large Wind Turbine Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue floating platform specialization and predictive analytics integration. The vendor base stratifies across three tiers: integrated OEMs with captive component manufacturing, pure-play turbine specialists, and regional fabricators serving domestic procurement. Three strategic archetypes dominate: state-affiliated champions leveraging policy alignment, European technology licensors targeting premium offshore niches, and cost-optimized challengers capturing utility-scale volume tenders. Competitive moves center on unbundling turbine supply from long-term service contracts and securing foundation engineering partnerships with East Asian shipbuilders.
Within the integrated OEM tier, Goldwind and Mingyang Smart Energy represent state-affiliated champions with coastal installation footprints. Siemens Gamesa Renewable Energy SA occupies a position among European technology licensors targeting typhoon-resistant specifications. Vestas Wind Systems AS anchors the premium-tier vector for advanced drivetrain designs. These three exemplify how geographic origin and corporate structure map onto distinct competitive archetypes in procurement realignment.
| Leading Market Players |
|---|
| Vestas Wind Systems AS |
| Siemens Gamesa Renewable Energy SA |
| Goldwind |
| Suzlon Energy Limited |
| General Electric Company |
| Nordex SE |
| Mingyang Smart Energy |
| Envision Energy |
| Enercon GmbH |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between GB-standard offshore platforms and conventional onshore units creates distinct pricing bands that map directly onto supply chain configurations. China's MIIT compliance tiers force dual sourcing strategies as buyers unbundle turbine supply from service contracts, compressing margins for non-compliant manufacturers while captive blade producers capture premium positioning in Jiangsu and Guangdong clusters.
Pricing Analysis
Volume deployment of onshore horizontal-axis units runs on per-megawatt transactional pricing with thin margins, while offshore gearless platforms command project-based long-term offtake structures with embedded service premiums. Price differentiation rests on GB certification grade and typhoon-resistance specification tier, with state-backed utilities in Shandong and Jiangsu provinces exhibiting lowest price sensitivity due to consolidated procurement scale. Cost compression in standard onshore tiers is intensifying because independent power producers now tender equipment and O&M separately, eroding bundled lifecycle pricing power.
Supply Chain Analysis
Dual-sourcing requirements for neodymium-iron-boron magnets and composite blade resin systems are reshaping procurement protocols across the region. Rare earth processing concentrates in China, while specialized carbon fiber feedstock draws from Japan and South Korea. Supply chain risk centers on single-source vulnerability for monopile foundation fabrication at Busan-Ulsan shipbuilding corridors. Distribution runs through state utility procurement committees in coastal provinces and independent power producer development offices in the South China Sea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-drive generator architectures are displacing conventional geared systems across Asia-Pacific offshore zones, creating asymmetric opportunity windows for stakeholders with captive magnet supply or predictive analytics capabilities.
For Market Incumbents: Deepen backward integration into permanent magnet supply chains to offset Chinese neodymium-iron-boron quota volatility, and accelerate captive certification facility investment to compress GB-standard recertification timelines against emerging entrants dependent on third-party testing bodies. For New Entrants and Emerging Players: Digital-channel route through SCADA-telemetry partnerships offers lowest-friction entry into independent power producer portfolios in the South China Sea, where predictive analytics integration remains underpenetrated relative to state utility segments dominated by established OEMs. For Investors and Strategic Acquirers: Re-rating potential sits with semi-submersible foundation specialists given Japan's METI deep-water Pacific Exclusive Economic Zone auction acceleration; long-term viability over the projection horizon favors acquisition targets with typhoon-resistant engineering IP and East Asian shipbuilder partnerships, with seabed leasing framework finalization across Australia's offshore zones as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Foundation Engineering Partnership | Semi-submersible platform alliances with Busan-Ulsan yards unlock Japan deep-water METI zones. |
| Predictive Analytics Integration | Machine learning on SCADA telemetry reduces unplanned downtime for Guangdong independent power producers. |
| Magnet Supply Diversification | Non-Chinese rare earth sourcing hedges direct-drive cost exposure to MIIT export quotas. |
| Certification Facility Investment | Captive GB testing capabilities compress recertification timelines against third-party dependent rivals. |
| Service Contract Unbundling | Separate O&M tendering enables independent service provider entry in Jiangsu state utility procurement. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with utility planning officers, independent power producer project developers, EPC contractors, and grid operators across China, Japan, and South Korea. Secondary validation drew from MIIT certification databases, METI offshore zoning announcements, CEA renewable purchase obligation circulars, and State Grid Corporation procurement disclosures. Bottom-up project pipeline aggregation and top-down regional capacity targets were triangulated to establish market sizing.
Data-stream reconciliation across installation capacity, nacelle shipment volumes, and foundation fabrication yard utilization established the analytical framework. Segmentation dimensions modeled include product architecture, end-user procurement structure, installation foundation type, and drivetrain technology category. CAGRs were derived from regression analysis against regulatory milestone schedules and grid interconnection investment trajectories. Forecast inputs incorporated seabed leasing auction timelines and composite blade technician pipeline constraints across Southeast Asian manufacturing hubs.
Inputs from METI tariff revision announcements and MIIT certification bulletins were available through the study window; gaps in Australia's offshore marine spatial planning completion dates introduce uncertainty bands around project restart assumptions. Forecasts reflect documented assumptions on grid code synchronization requirements and rare earth export quota stability. Deviation in China's neodymium-iron-boron processing policy or Japan's semi-submersible foundation technical standards would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
India Wind Energy Market
Wind Energy Systems
Global Offshore Wind Market
Wind Energy Systems
Wind Electric Power Generation Market
Wind Energy Systems
Wind Turbine Pitch and Yaw Drive Market
Wind Energy Systems
India Wind Industry Market
Wind Energy Systems
Germany Offshore Wind Energy Market
Wind Energy Systems
Wind Turbine Market
Wind Energy Systems
Medium-Speed Permanent Magnet Wind Turbine Generator System Market
Wind Energy Systems
Wind Turbine Forged Tower Flange Market
Wind Energy Systems
Peru Wind Energy Market
Wind Energy Systems
Wind Power Converter Systems Market
Wind Energy Systems
Ireland Wind Energy Market
Wind Energy Systems
Global Wind Automation Market
Wind Energy Systems
Chile Wind Energy Market
Wind Energy Systems
Wind Turbine Yaw and Pitch Gearbox Market
Wind Energy Systems
Wind Services Market