
 NGS Automation Market | 2026-2036
NGS Automation Market Size, Share, and Industry Trends Forecast 2026-2036
NGS Automation Market Intelligence
Integration of artificial intelligence into sample tracking and error correction is reshaping how NGS automation systems manage workflow complexity. Illumina leverages its installed base of sequencing instruments to anchor downstream automation sales. Thermo Fisher Scientific sustains competitive pressure through its vertical integration across reagents, instruments, and cloud-based data analysis software. QIAGEN specializes in sample-to-insight automation, positioning its liquid handling robots for clinical diagnostic workflows.
NGS automation encompasses robotic systems, microfluidic devices, and software platforms that execute nucleic acid extraction, library preparation, and quality control with minimal human intervention, typically processing 96 to 384 samples per run. These systems reduce contamination risk and improve reproducibility in high-throughput genomic analysis. Liquid handling robots occupy the largest revenue pool due to their ubiquity across pre-analytical steps. Microfluidics represents the fastest-expanding technology segment as miniaturization cuts reagent costs and reaction volumes. Data analysis software captures disproportionate margin contribution because cloud deployment creates recurring subscription revenue from biopharmaceutical end users.
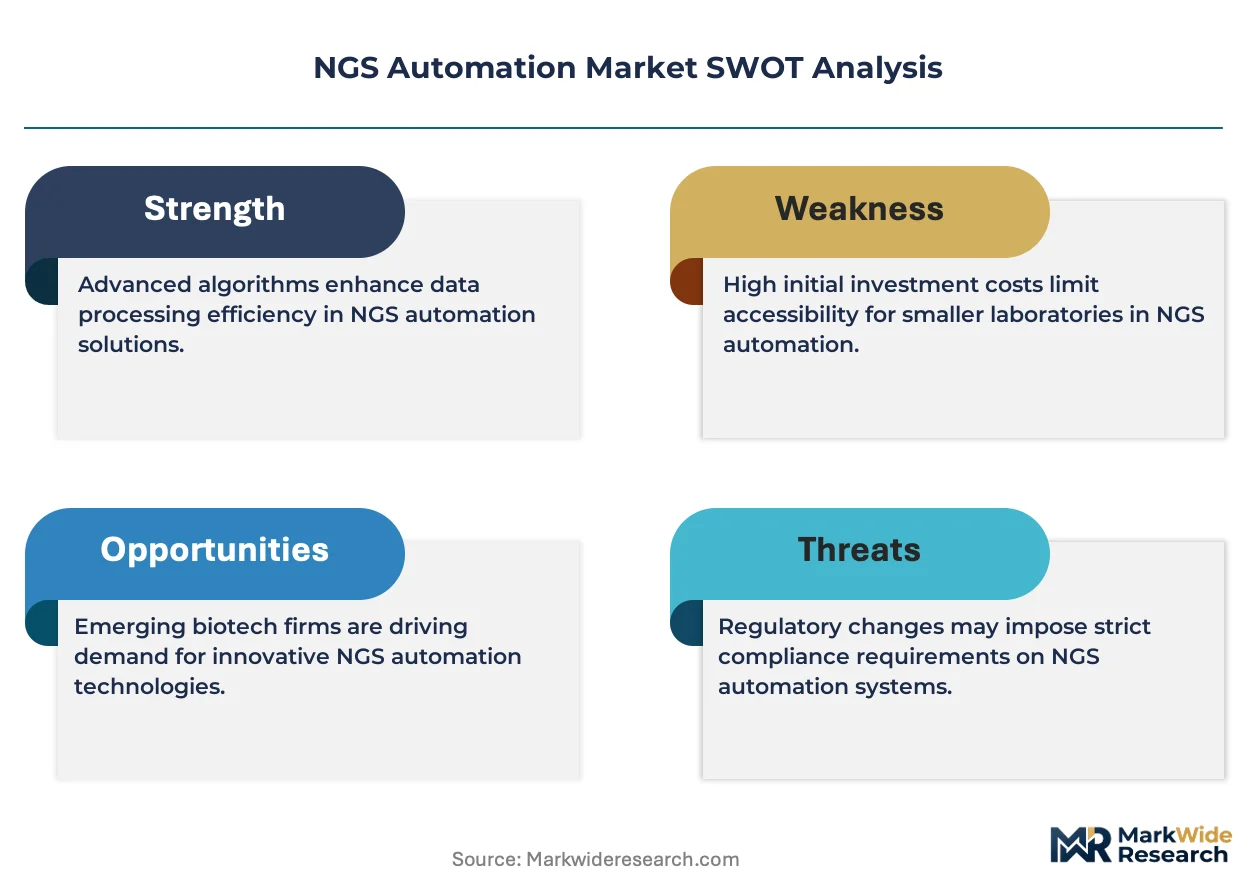
The FDA regulates NGS-based clinical tests as in vitro diagnostics or laboratory-developed tests depending on the distribution model, while the Clinical Laboratory Improvement Amendments mandate proficiency testing for automated genomic assays. ISO 15189 accreditation requirements in Europe and Japan's PMDA oversight of companion diagnostics shape market access conditions for instrument vendors. Stakeholders must monitor how regulatory convergence between the FDA and EMA on next-generation sequencing standards will affect product development roadmaps and geographic launch sequencing.
Market Dynamics
Clinical diagnostic laboratories face mounting pressure to process genomic samples at scale while meeting FDA's evolving oversight framework for laboratory-developed tests and precision medicine guidance. This regulatory compression is forcing automation vendors to redesign instrument architectures for traceability and audit compliance from the ground up.
Growth Catalysts
- CLIA-mandated proficiency testing:The Clinical Laboratory Improvement Amendments require rigorous quality assurance for automated genomic assays, driving replacement of manual protocols with validated robotic systems in US reference laboratories.
- Companion diagnostic expansion:Biopharmaceutical pipelines increasingly require biomarker-driven patient stratification, creating sustained demand for high-throughput library preparation automation in contract research organizations.
- Microfluidic miniaturization:Reaction volume reduction below one microliter cuts reagent expenditure by an order of magnitude, accelerating adoption in cost-constrained academic medical centers.
Market Restraints
- Optical component supply concentration:Precision fluorescence detection modules rely on Japanese and German photonics suppliers, exposing instrument manufacturers to extended lead times and single-source vulnerability.
- Capital intensity barriers:Fully integrated sample-to-insight platforms require seven-figure capital commitments, freezing out independent clinical laboratories and small research institutes.
- Technical limitation in complex matrices:Automated nucleic acid extraction from formalin-fixed paraffin-embedded tissue remains problematic, forcing retention of manual intervention steps in oncology workflows.
Strategic Opportunities
- Underpenetrated India market:The country's national pharmaceutical regulator CDSCO is streamlining in vitro diagnostic approvals, opening pathways for automated NGS platforms in emerging molecular diagnostics laboratories.
- AI-driven error correction convergence:Machine vision algorithms paired with liquid handling robots enable real-time pipetting verification, reducing costly rerun rates in high-stakes clinical settings.
- Cloud-based data analysis channel innovation:Subscription software deployment creates recurring revenue streams and locks in instrument ecosystem loyalty among biopharmaceutical end users.
Industry Challenges
- Bioinformatics specialist scarcity:Automated platforms generate terabyte-scale datasets that require computational biology expertise scarce in clinical laboratory staffing models, creating bottlenecks in report generation.
- ISO 15189 certification timelines:European and Japanese accreditation bodies demand extensive validation documentation for automated genomic assays, extending product launch cycles by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NGS Automation Market |
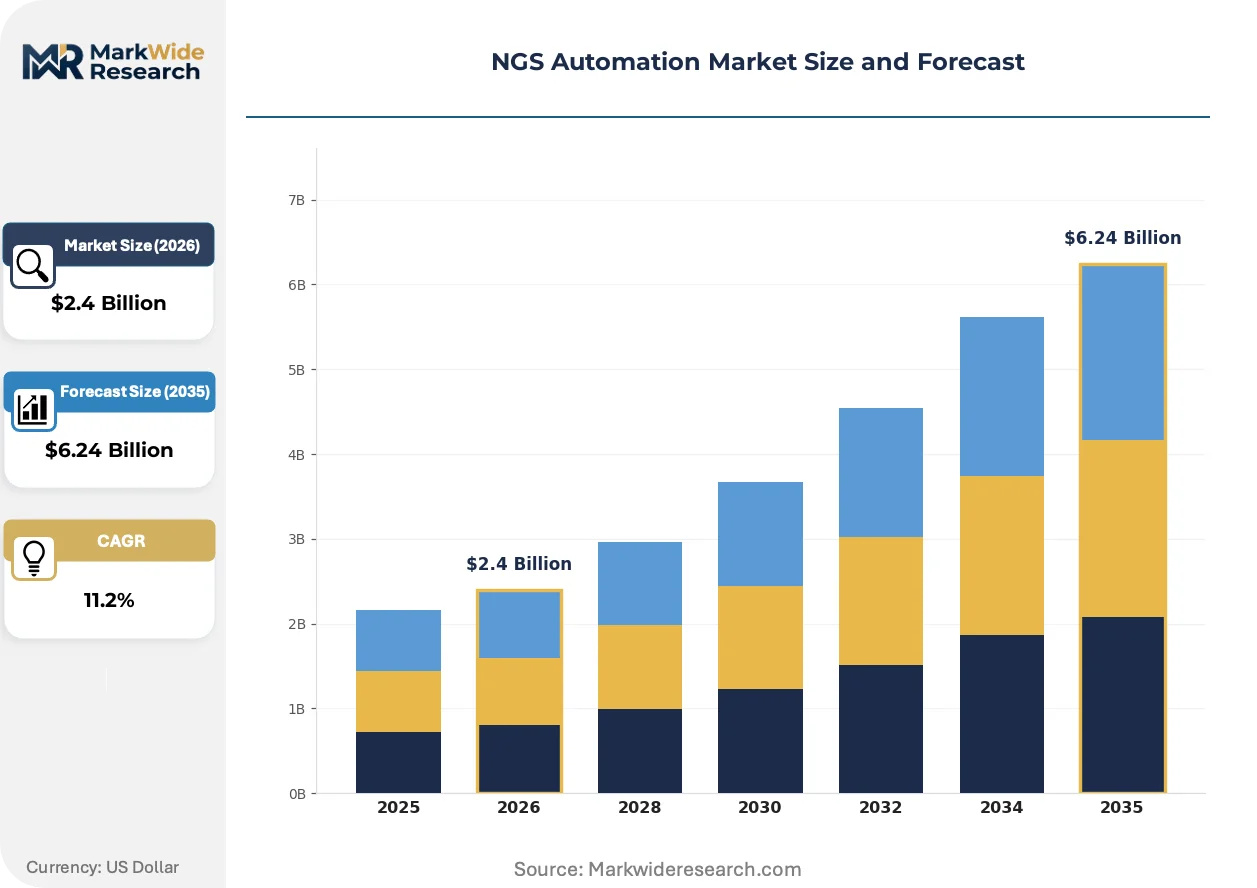
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.24 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Handling Robots, Library Preparation Systems, Sequencing Platforms, Data Analysis Software Technology: Microfluidics, Magnetic Bead Handling, Optical Detection, Robotics Integration Application: Genomic Research, Precision Medicine, Agricultural Genomics, Microbial Sequencing End User: Academic Institutions, Biopharmaceutical Companies, Contract Research Organizations, Forensic Laboratories |
| Companies Covered | QIAGEN, Roche, Thermo Fisher Scientific, Pacific Biosciences, Oxford Nanopore Technologies, Agilent Technologies, Illumina, BGI Genomics, PerkinElmer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NGS Automation Market Strategic Shifts & Innovations
Workflow orchestration software is displacing hardware-centric competition as the primary battleground for vendor differentiation. Buyers now prioritize seamless integration across extraction, library prep, sequencing, and analysis stages over incremental speed gains in isolated instruments.
Acoustic liquid handling is migrating from niche protein crystallography applications into mainstream NGS automation. Pharmaceutical screening facilities pioneered contactless nanoliter dispensing to preserve precious sample volumes. Genomic service providers are now adopting these systems to eliminate cross-contamination risks in multiplexed PCR setups and compress turnaround times for clinical trial enrollment screening.
The FDA's finalized guidance on artificial intelligence and machine learning-based software as a medical device is forcing automation vendors to rearchitect quality management systems. Algorithm updates that previously deployed via routine cloud patches now trigger formal validation protocols. Instrument manufacturers serving the US clinical market are responding by segregating regulated diagnostic modules from research-use-only feature branches.
Biopharmaceutical procurement teams are consolidating vendor relationships around full-stack platform providers capable of spanning reagents, instruments, and bioinformatics. This preference shift disadvantages point-solution specialists and rewards integrated ecosystem vendors. The trend is most pronounced in the United States, where large CROs negotiate enterprise framework agreements to standardize operations across multiple geographic sites.
NGS Automation Market Segmentation
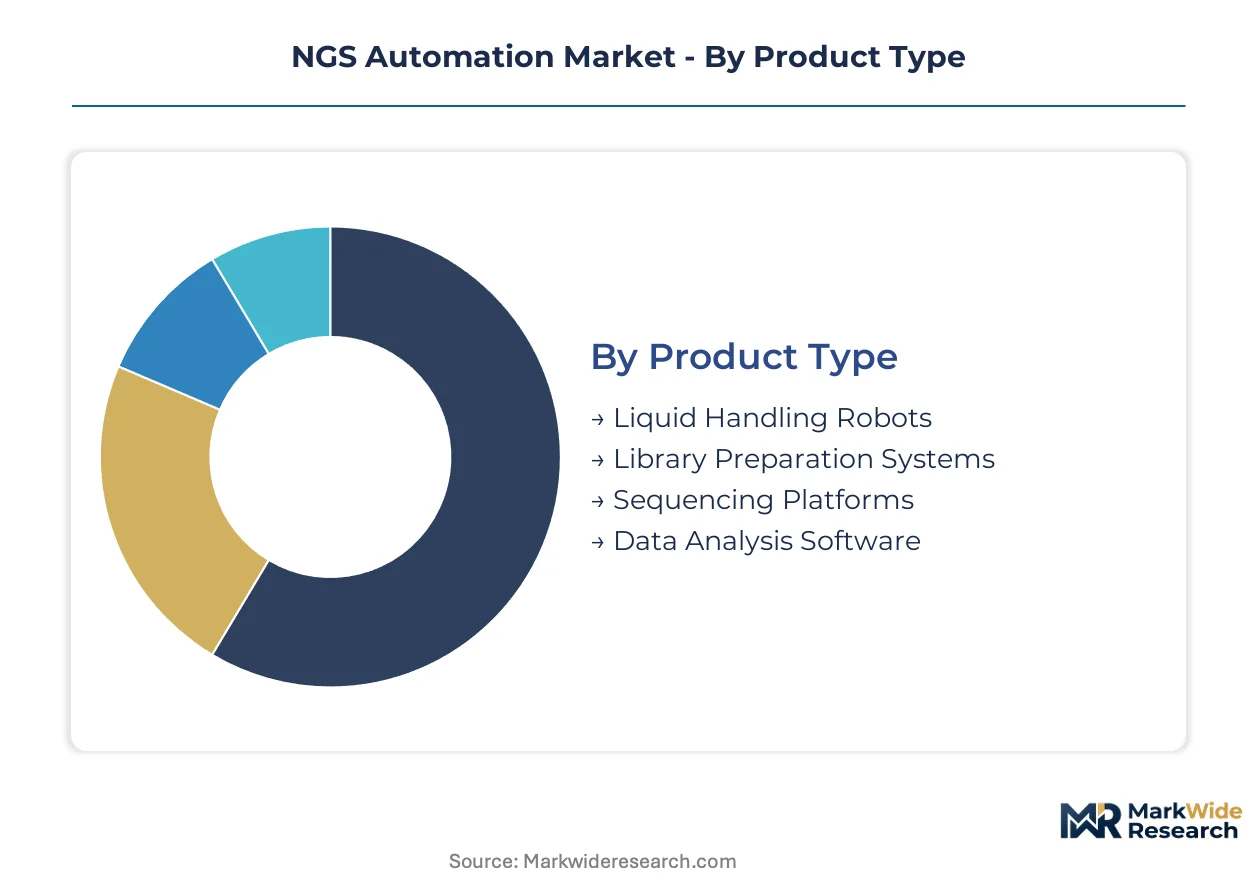
NGS automation vendors architect product portfolios around distinct workflow stages, each commanding different margin profiles and replacement cycles. Segmentation reveals where capital concentrates versus where disruptive technologies gain traction.
Product Type:
The use-case spectrum spans pre-analytical sample processing through downstream informatics, with hardware and software components exhibiting divergent revenue models and customer loyalty patterns.
- Liquid Handling Robots:Multi-axis robotic arms with disposable tip technology execute precise pipetting across 96- to 384-well formats. Academic medical centers in the United States deploy these systems for high-throughput screening, driven by CLIA-mandated reproducibility requirements that manual protocols cannot satisfy.
- Library Preparation Systems:Integrated workstations automate fragmentation, adapter ligation, and PCR amplification with barcoded tracking. Biopharmaceutical companies prioritize these platforms for companion diagnostic development, where FDA scrutiny of analytical validity elevates demand for validated, traceable workflows.
- Sequencing Platforms:Automated cluster generation and imaging systems interface with upstream sample prep modules.
- Data Analysis Software:Cloud-deployed pipelines for variant calling and annotation generate recurring subscription revenue from enterprise biopharmaceutical accounts.
Established volume favors liquid handling robots; emerging adoption favors data analysis software.
Technology:
Cost tier differentiation separates premium precision systems from commoditized automation components, with miniaturization commanding substantial price premiums.
- Microfluidics:Sub-microliter reaction chambers fabricated in glass or polymer substrates reduce reagent consumption by orders of magnitude. Agricultural genomics programs in cost-constrained research environments adopt these systems to stretch limited grant funding across larger sample cohorts.
- Magnetic Bead Handling:Automated magnetic separation modules enable high-purity nucleic acid extraction without centrifugation. Forensic laboratories processing mixed-evidence samples depend on bead-based cleanup for reproducible yield across degraded inputs.
- Optical Detection:Fluorescence and absorbance modules verify sample concentration and library quality.
- Robotics Integration:Coordinated multi-instrument orchestration software unifies disparate hardware into continuous workflows.
Magnetic bead handling dominates current installed base; microfluidics climbs the fastest as miniaturization economics improve.
Application:
Customer type concentration varies sharply across research, clinical, and industrial genomic applications, with regulatory intensity determining automation penetration rates.
- Genomic Research:Exploratory sequencing projects in basic biology require flexible, reconfigurable automation platforms. Contract research organizations scaling population genomics initiatives drive demand for modular systems that accommodate protocol evolution without hardware replacement.
- Precision Medicine:Companion diagnostic and pharmacogenomic testing demands locked, validated workflows with full audit trails. FDA oversight of laboratory-developed tests compels clinical laboratories toward closed-system automation that satisfies 21 CFR Part 11 electronic record requirements.
- Agricultural Genomics:Marker-assisted breeding and trait discovery in crops and livestock.
- Microbial Sequencing:Pathogen surveillance, microbiome characterization, and antibiotic resistance profiling.
Genomic research captures largest instrument shipments; precision medicine delivers highest per-unit margins.
End User:
Geographic and institutional scale determine procurement authority, with enterprise frameworks consolidating vendor relationships at large organizations.
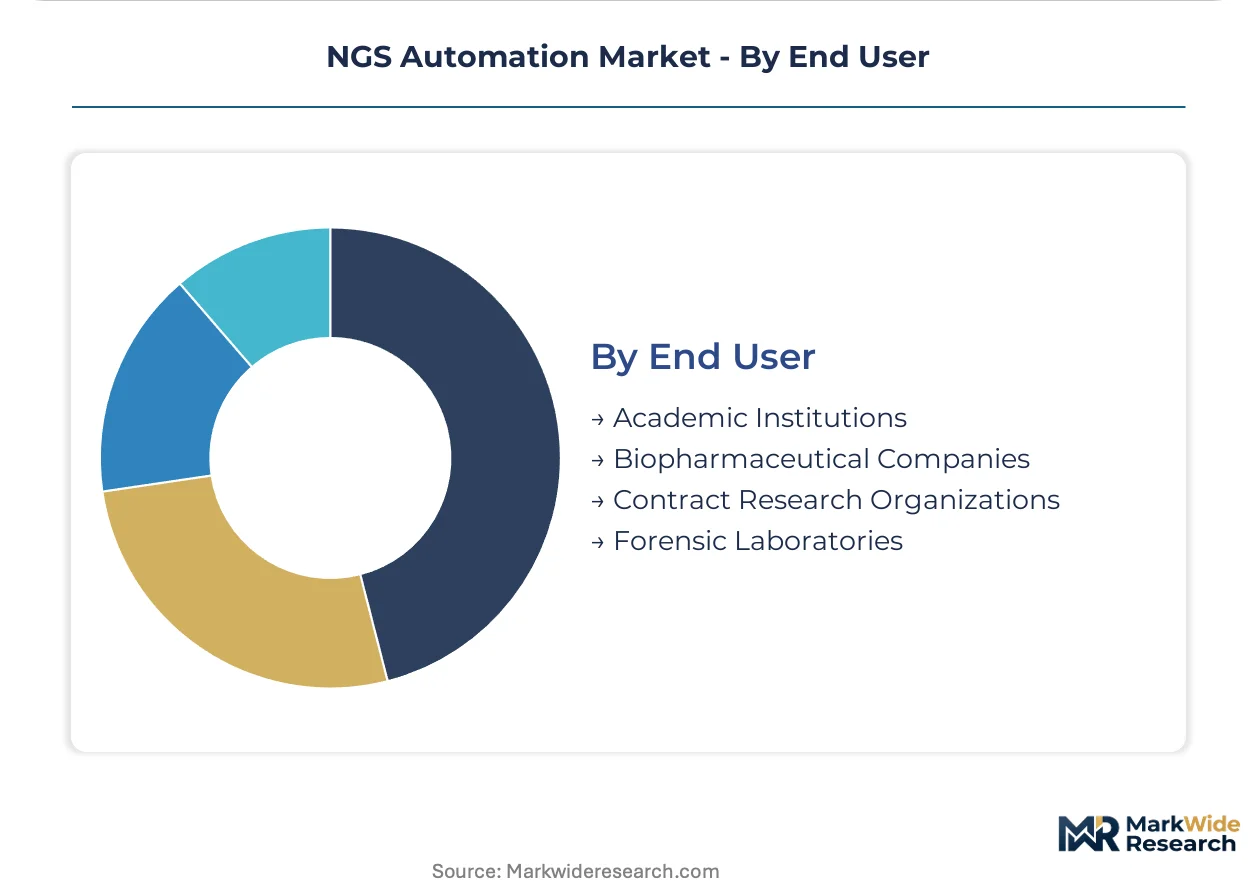
- Academic Institutions:University core facilities and medical school laboratories balance throughput requirements against capital constraints. Shared instrument access models in US research universities spread automation costs across multiple principal investigator grants, sustaining demand for mid-tier platforms.
- Biopharmaceutical Companies:Integrated drug development organizations prioritize sample-to-insight platforms that compress biomarker discovery timelines. Enterprise procurement teams negotiate multi-site framework agreements, favoring vendors with global service infrastructure and regulatory submission support.
- Contract Research Organizations:Externalized genomic service providers competing on turnaround time and regulatory documentation.
- Forensic Laboratories:Government crime labs and private DNA testing facilities with stringent chain-of-custody requirements.
Biopharmaceutical companies anchor premium segment revenue; contract research organizations represent fastest-expanding deployment volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German instrument manufacturers export precision liquid handling modules to biopharmaceutical clusters in the United States and China, while Japanese photonics suppliers dominate fluorescence detection component flows into North American and European system integrators.
United States
Academic medical centers in Boston and San Francisco scale high-throughput sequencing operations for precision medicine trials. FDA oversight of laboratory-developed tests under 21 CFR Part 11 elevates compliance requirements for automated genomic assay validation. The Research Triangle Park corridor in North Carolina hosts contract research organizations consolidating multi-site automation frameworks.
Germany
Industrial automation heritage from automotive and pharmaceutical machinery feeds into robotic liquid handling platform development. EMA convergence with FDA on next-generation sequencing standards shapes product roadmaps for vendors seeking transatlantic market access. The Munich-Stuttgart axis concentrates precision engineering suppliers serving diagnostic instrument manufacturers.
China
National genomics initiatives drive demand for cost-optimized library preparation automation in Beijing and Shanghai research institutes. NMPA regulatory pathways for in vitro diagnostics are streamlining approval timelines for automated clinical platforms. The Suzhou biomedical industrial park hosts emerging domestic instrument manufacturers targeting mid-tier hospital laboratories.
Japan
PMDA oversight of companion diagnostics compels rigorous analytical validation for automated pharmacogenomic workflows. METI funding for precision medicine infrastructure supports adoption of integrated sample-to-insight platforms in Tokyo and Osaka medical centers. The Kobe biomedical innovation cluster concentrates reagent suppliers and system integrators serving Asian diagnostic markets.
India
CDSCO streamlining of in vitro diagnostic approvals opens pathways for automated NGS platforms in emerging molecular diagnostics laboratories. Government-funded genome sequencing projects for rare diseases and agricultural applications drive instrument procurement in Bangalore and Hyderabad. The Genome Valley cluster near Hyderabad hosts contract research organizations scaling automated genomic service capacity.
NGS Automation Market Key Industry Players
Channel-controlling players compete with product-specialist players across workflow orchestration, reagent supply, and instrument hardware layers. The market structure consolidates around full-stack platform providers capable of spanning extraction through informatics, while point-solution specialists occupy narrower technology niches. Two strategic archetypes dominate: integrated ecosystem vendors leveraging installed bases for downstream automation attach, and modular component suppliers enabling flexible reconfiguration for research laboratories. Competitive moves center on strategic partnerships for regulatory submission support and backward integration into reagent manufacturing to capture margin pools.
Among instrumentation-focused players, Illumina and Thermo Fisher Scientific anchor the integrated ecosystem tier, while QIAGEN occupies a position exemplifying sample-to-insight automation specialization. These three companies represent distinct archetypes: the sequencing instrument incumbent leveraging platform dominance, the diversified life sciences conglomerate with vertical control across reagents and software, and the molecular diagnostics pure-play targeting clinical workflow integration. Their collective positioning illustrates how vendor consolidation around full-stack capabilities disadvantages modular specialists in biopharmaceutical procurement cycles.
| Leading Market Players |
|---|
| QIAGEN |
| Roche |
| Thermo Fisher Scientific |
| Pacific Biosciences |
| Oxford Nanopore Technologies |
| Agilent Technologies |
| Illumina |
| BGI Genomics |
| PerkinElmer |
| Others |
Cost & Logistics Intelligence
Trans-Pacific freight corridors linking Japanese photonics suppliers to North American system integrators transmit cost volatility directly into instrument pricing, amplifying differentiation between premium fluorescence detection modules and standard robotic components while compressing margins for mid-tier liquid handling platforms.
Pricing Analysis
Cost-plus contracts with Japanese and German optical component suppliers index precision fluorescence detection modules to rare earth metal spot markets, creating margin pressure for instrument manufacturers. Pricing stratifies across FDA-validated clinical tiers, research-use-only configurations, and reagent rental programs bundled with service contracts. Academic medical centers exhibit highest price sensitivity due to grant-funded capital constraints, while biopharmaceutical procurement teams prioritize total cost of ownership over upfront instrument expenditure. Cost compression in mid-tier robotics intensifies as Chinese domestic manufacturers expand export capacity for 96-well format liquid handlers.
Supply Chain Analysis
Contract manufacturing for precision robotic arms concentrates with German and Swiss industrial automation specialists, while microfluidic chip fabrication draws from Taiwanese semiconductor foundries and US polymer substrate specialists. Critical dependencies include rare earth-doped optical fibers from Japan, precision stepper motors from Germany, and fluoropolymer reagent reservoirs from US chemical processors. Single-source vulnerability in photonics components exposes instrument assemblers to extended lead time risk. Distribution runs through authorized dealer networks serving academic core facilities and direct enterprise sales teams targeting biopharmaceutical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NGS automation incumbents face substitution pressure from cloud-native bioinformatics platforms that disintermediate hardware-centric workflows, requiring defensive architecture investments to preserve instrument attach rates.
For Market Incumbents: Pre-empt disintermediation by cloud-native analysis platforms through backward integration into AI-driven variant interpretation software. Anchor ecosystem loyalty via subscription data pipelines that lock biopharmaceutical accounts into recurring revenue relationships. Defend against modular specialist encroachment by certifying end-to-end workflows under FDA 21 CFR Part 11 and EMA IVDR frameworks.
For New Entrants and Emerging Players: India's CDSCO-streamlined diagnostic approval pathways offer white-space expansion for cost-optimized library preparation automation targeting emerging molecular diagnostics laboratories. Agricultural genomics programs in cost-constrained research environments present penetrable entry points for microfluidic miniaturization platforms. Partner with domestic distributors in Bangalore and Hyderabad to navigate procurement processes at government-funded genome sequencing initiatives.
For Investors and Strategic Acquirers: Sample-to-insight workflow orchestration software specialists with validated clinical diagnostic deployments represent priority acquisition targets given bioinformatics specialist scarcity in laboratory staffing models. Long-term viability hinges on recurring revenue share expansion versus transactional instrument sales. Monitor CDSCO and NMPA regulatory pathway acceleration as inflection signals for emerging market penetration velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Error Correction Integration | Machine vision algorithms paired with liquid handling robots reduce costly rerun rates in CLIA-mandated clinical settings. |
| Cloud-Based Data Analysis Channel Development | Subscription software deployment locks in instrument ecosystem loyalty among biopharmaceutical end users. |
| Regulatory Submission Support Partnership | Collaboration with FDA and EMA consultants accelerates 21 CFR Part 11 validation timelines for automated genomic assays. |
| Microfluidic Miniaturization Scale-Up | Sub-microliter reaction chambers cut reagent expenditure by orders of magnitude for cost-constrained academic centers. |
| Backward Integration into Reagent Manufacturing | In-house production of magnetic bead separation modules captures margin pools from third-party consumable suppliers. |
Research Approach
A standing panel of clinical laboratory directors, biopharmaceutical development executives, regulatory affairs specialists, and precision medicine program managers provided ongoing calibration against operational realities. Primary interviews with instrument procurement teams at academic medical centers and contract research organizations combined with secondary validation from FDA 510(k) filings, EMA IVDR technical documentation, Clinical Laboratory Improvement Amendments proficiency testing records, and ISO 15189 accreditation databases. Bottom-up instrument shipment tracking and top-down biopharmaceutical R&D expenditure analysis triangulated market sizing across the analysis window.
Scenario-bracketing around regulatory convergence timelines and microfluidic adoption curves bounded projection uncertainty throughout the forecast period. Segmentation modeling spanned product type, technology platform, application area, and end-user institution scale. CAGRs derived from instrument replacement cycle analysis and reagent consumption intensity metrics. Forecast inputs included CLIA-mandated automation penetration rates, companion diagnostic pipeline expansion trajectories, and cloud-based analysis subscription attach rates.
The forecast holds incumbent behavior within observed patterns; aggressive ecosystem consolidation moves by full-stack platform providers would shift competitive dynamics and pricing power distribution. Regulatory divergence between FDA and EMA on AI-enabled software validation, or supply disruption in Japanese photonics components, could revise instrument availability and launch sequencing. Quarterly review of CDSCO and NMPA approval velocity, academic medical center capital expenditure commitments, and biopharmaceutical framework agreement announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Europe Gene Synthesis (Research Use) Market
Genomics
Genetic Analysis Services Market
Genomics
Latin America Gene Expression Market
Genomics
DNA Diagnostics Market
Genomics
Global Next-Generation Sequencing (NGS) Services Market
Genomics
Cancer-Focused Genetic Testing Services Market
Genomics
Global Pharmacogenomics Market
Genomics
Microarray Biochips Market
Genomics
Cancer Biomarkers Market
Genomics
United States DNA Sequencing Products Market
Genomics
United States Cancer Biomarkers Market
Genomics
Global Gene Amplification Technologies Market
Genomics
Global Metagenomic Sequencing Market
Genomics
Whole Exome Sequencing (WES) Market
Genomics
AI in Genomics Market
Genomics
Europe Hereditary Cancer Testing Market