
 Single-Cell Omics Market | 2026-2036
Single-Cell Omics Market Size, Share, and Industry Trends Forecast 2026-2036
Single-Cell Omics Market Analysis
The FDA's evolving cell therapy guidance is pivoting the cost-of-entry calculus for clinical-grade single-cell platforms toward extensive analytical validation suites. Illumina leverages its installed base of sequencing infrastructure to sustain recurring consumable revenue across academic and clinical accounts. 10x Genomics anchors the droplet-based RNA sequencing segment with proprietary microfluidic chip architectures that define workflow standards. Thermo Fisher Scientific competes through integrated sample-to-data solutions spanning instruments, reagents, and cloud analytics.
Single-cell omics encompasses the molecular profiling of individual cells through nucleic acid sequencing, protein detection, or metabolite measurement, typically resolving transcriptomes at picogram input levels using barcoded microfluidic encapsulation. The technology enables dissection of cellular heterogeneity in tissues, tumor microenvironments, and developmental systems with single-molecule resolution. Single-cell RNA sequencing commands the largest revenue share among product types due to mature library preparation protocols and broad publication footprint, while single-cell proteomics represents the fastest-expanding margin pool as antibody-based multiplexing achieves higher plex without amplification bias. Microfluidics dominates the technology dimension through droplet generation precision, though laser capture microdissection retains niche utility in spatially resolved archival tissue studies.
The FDA, EMA, and ISO 13485 standards collectively shape market access by mandating design controls, traceability, and quality management for instruments entering clinical laboratories. REACH and RoHS frameworks in Europe constrain material selection for microfluidic consumables, particularly regarding fluoropolymer and photoresist chemistries. Stakeholders must monitor how harmonization between FDA guidance on analytical validation and EMA's evolving advanced therapy medicinal product requirements reshapes platform qualification timelines and regional market entry sequencing.
Market Dynamics
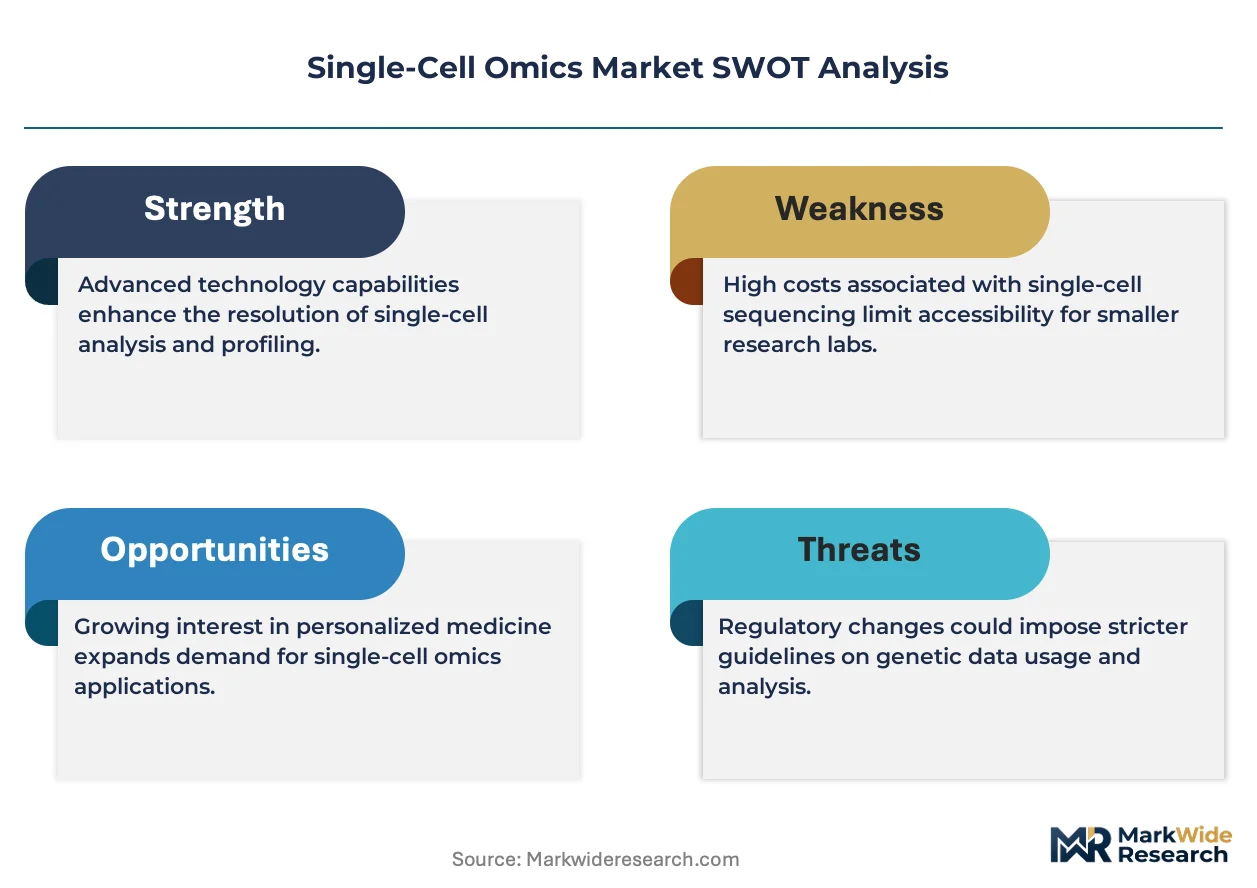
FDA guidance on cell and gene therapy analytics is forcing platform vendors to absorb analytical validation costs that previously sat with clinical laboratories, compressing margin structures while raising barriers for new entrants.
Growth Catalysts
- NIH funding concentration:Sustained federal research budgets in the United States create predictable procurement pipelines for high-parameter instruments across academic medical centers.
- ISO 13485 harmonization:Quality management system standardization accelerates dual-use platform development spanning research and clinical diagnostic applications.
- Immuno-oncology pipeline embedding:Pharmaceutical manufacturers now mandate single-cell resolution as a standard workflow checkpoint in therapeutic development programs.
Market Restraints
- Consumables cost structure:Proprietary microfluidic chips and barcoded reagents lock users into recurring expenditure cycles that constrain budget flexibility.
- Fluoropolymer supply concentration:REACH and RoHS material constraints in Europe limit qualified suppliers for photoresist chemistries used in droplet generation devices.
- Amplification bias in protein detection:Technical limitations in single-cell proteomics workflows restrict multiplex depth compared to transcriptomic methods.
Strategic Opportunities
- Spatial transcriptomics convergence:Integration of laser capture microdissection with in situ sequencing opens archival tissue banks to molecular profiling.
- Cloud analytics distribution:Subscription-based bioinformatics platforms enable smaller research groups to access computational pipelines without capital investment.
- Advanced therapy medicinal product tailwinds:EMA regulatory frameworks in Europe create qualification pathways for clinical-grade single-cell assays in cell therapy manufacturing.
Industry Challenges
- Bioinformatics talent scarcity:Shortage of computational biologists capable of interpreting multi-modal single-cell datasets slows platform adoption in clinical settings.
- Analytical validation timelines:Extended FDA qualification cycles for multi-parameter assays delay revenue recognition from clinical laboratory contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single-Cell Omics Market |
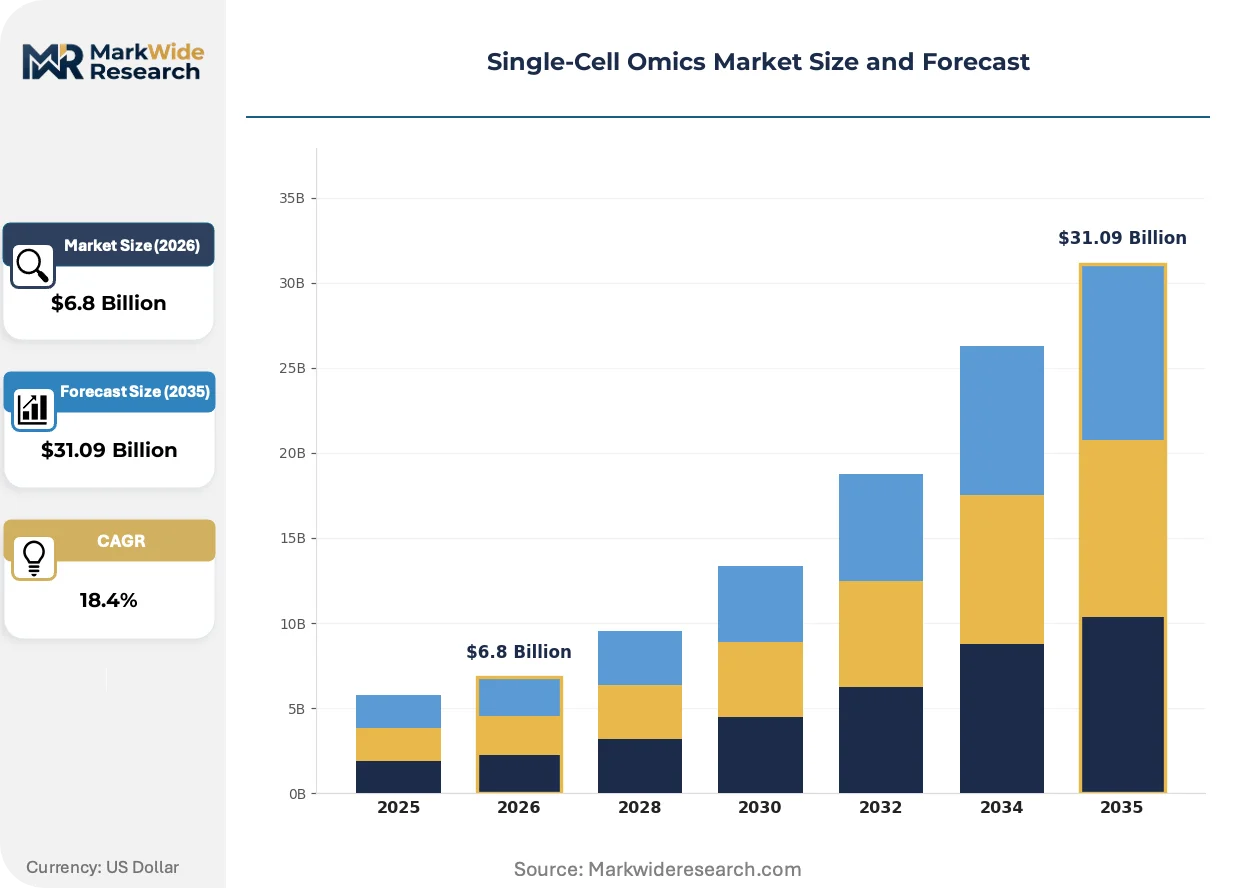
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Cell RNA Sequencing, Single-Cell DNA Sequencing, Single-Cell Proteomics, Single-Cell Metabolomics Technology: Microfluidics, Laser Capture Microdissection, Droplet Digital PCR, Flow Cytometry Application: Oncology, Neurology, Immunology, Cardiovascular End User: Research Institutions, Pharmaceutical Companies, Clinical Laboratories, Biotechnology Firms |
| Companies Covered | QIAGEN N.V., Standard BioTools, 10x Genomics, BD, Mission Bio, Illumina, Thermo Fisher Scientific, Danaher, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single-Cell Omics Market Emerging Trajectories
Workflow integration and regulatory harmonization are compressing the gap between research-grade discovery and clinical diagnostic deployment, reshaping how platforms prove analytical validity.
Multi-omic barcoding is decentralizing data generation by enabling simultaneous transcriptomic, epigenetic, and proteomic readouts from individual cells without instrument switching. Academic core facilities and mid-size biotechs are adopting these integrated chemistries faster than large pharmaceutical central labs, which retain legacy siloed workflows. The structural consequence is compressing the timeline from hypothesis to multi-modal dataset, reducing dependency on specialized service providers.
EMA's evolving advanced therapy medicinal product requirements are tightening traceability mandates for cell therapy manufacturing analytics. Industrial consequence includes mandatory audit trails for single-cell quality control assays used in release testing. Cell therapy contract development and manufacturing organizations in Germany and the Netherlands are responding by pre-qualifying platforms against both EMA and FDA standards simultaneously.
Consolidated procurement by institutional core facilities is displacing principal-investigator-driven instrument purchases across major research universities. Core facility directors now negotiate enterprise licenses spanning sequencing, proteomics, and imaging platforms, extracting volume discounts that individual labs cannot match. This concentration is most visible in the United States, where NIH-funded institutions are centralizing single-cell infrastructure to improve utilization rates and standardize training protocols.
Single-Cell Omics Market Segmentation
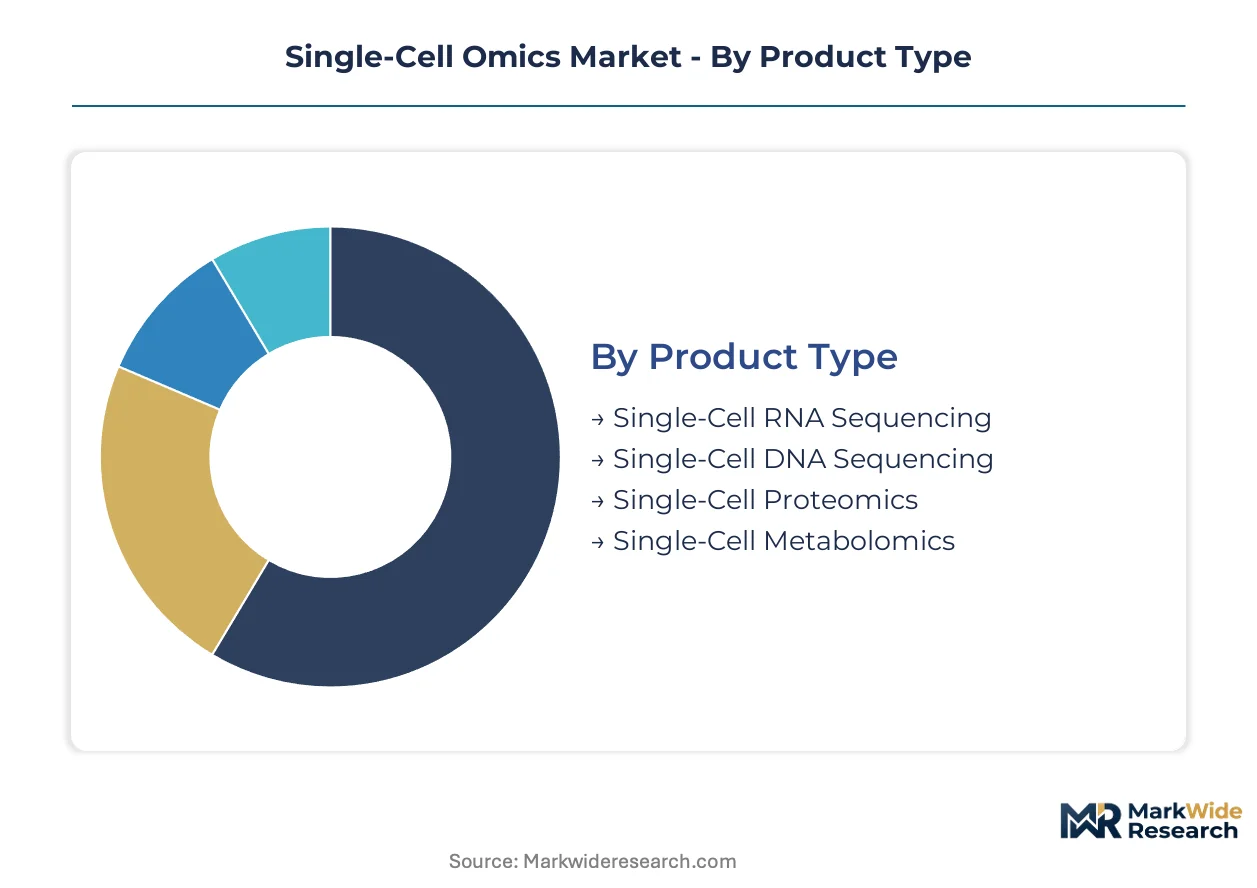
Single-cell omics segmentation reveals how technical specifications, workflow integration, and regulatory requirements fragment procurement patterns across research and clinical environments. Understanding these divides exposes where platform vendors must customize hardware configurations versus standardize consumable formats.
Product Type:
Technical maturity and amplification chemistry differentiate revenue concentration across molecular modalities.
- Single-Cell RNA Sequencing:Barcoded microfluidic encapsulation of polyadenylated transcripts generates picogram-scale libraries compatible with standard sequencing infrastructure. Pharmaceutical immuno-oncology pipelines in the United States absorb the highest instrument density due to FDA-guided analytical validation requirements for cell therapy release assays.
- Single-Cell Proteomics:Antibody-based multiplexing without enzymatic amplification reduces bias but constrains plex depth relative to transcriptomic methods. Biotechnology firms in Massachusetts and California are deploying these workflows fastest for biomarker discovery where protein-level validation precedes clinical translation.
- Single-Cell DNA Sequencing:Whole-genome amplification from isolated nuclei enables copy-number and single-nucleotide variant detection at clonal resolution.
- Single-Cell Metabolomics:Mass spectrometry coupling with live-cell isolation captures metabolic flux states in tumor microenvironment studies.
Mature deployment sits with Single-Cell RNA Sequencing. Newer deployment is concentrated in Single-Cell Proteomics.
Technology:
Precision requirements and sample throughput shape capital allocation between integrated platforms and modular components.
- Microfluidics:Droplet generation precision at nanoliter volumes enables parallel processing of thousands of cells per run with minimal reagent consumption. Research institutions in Germany and the Netherlands prioritize these systems for EMA-aligned cell therapy manufacturing analytics requiring traceable quality control.
- Laser Capture Microdissection:UV laser ablation preserves spatial context in formalin-fixed archival tissue, opening biobanks to retrospective molecular profiling. Oncology pathology departments in the United Kingdom and France are adopting these workflows for spatial transcriptomics where tissue architecture informs therapeutic stratification.
- Droplet Digital PCR:Absolute quantification without standard curves supports rare mutation detection in circulating tumor cell analysis.
- Flow Cytometry:High-parameter spectral detection enables rapid immunophenotyping with established clinical reimbursement pathways.
Established infrastructure dominates Flow Cytometry. Steepest expansion trajectory belongs to Microfluidics.
Application:
Disease biology complexity and therapeutic pipeline density determine where single-cell resolution delivers actionable insights.
- Oncology:Tumor heterogeneity mapping at clonal resolution guides combination therapy selection and resistance monitoring. Pharmaceutical companies now embed single-cell checkpoints into immuno-oncology development programs as standard practice across United States and European trial sites.
- Immunology:T-cell receptor repertoire analysis and cytokine profiling dissect autoimmunity mechanisms and vaccine responses. Academic medical centers in Boston and San Francisco concentrate procurement for NIH-funded autoimmune disease consortia requiring multi-modal immune cell atlases.
- Neurology:Rare cell type identification in brain tissue supports neurodegeneration biomarker discovery with limited sample availability.
- Cardiovascular:Single-nucleus transcriptomics from frozen cardiac biopsies enables cell-type-specific gene regulatory network reconstruction.
Clinical translation maturity clusters in Oncology. Emerging application intensity centers on Immunology.
End User:
Capital availability and regulatory exposure split procurement between centralized core facilities and distributed laboratory networks.
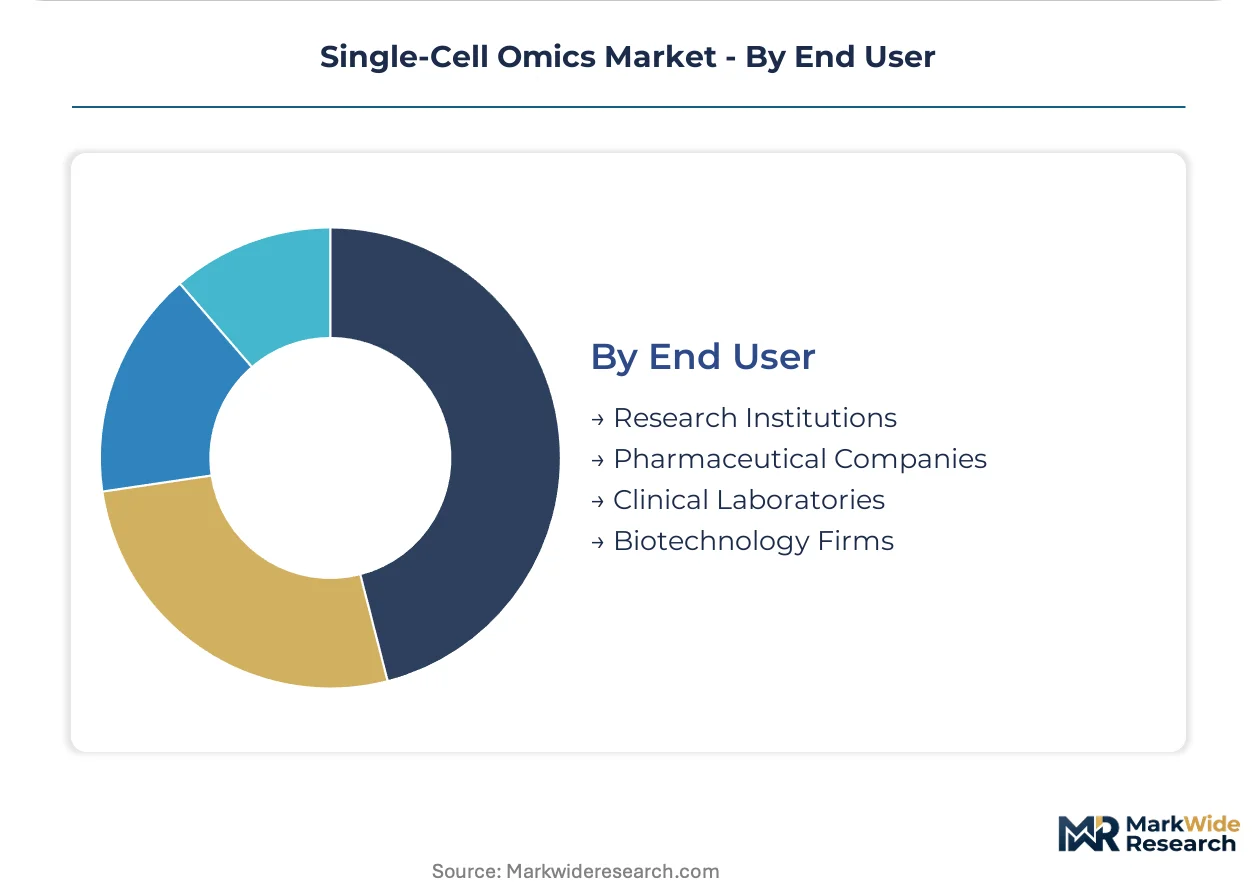
- Research Institutions:Consolidated core facility procurement across major universities extracts volume discounts and standardizes training protocols. NIH funding concentration in the United States drives predictable replacement cycles for high-parameter platforms at academic medical centers in Maryland, California, and Massachusetts.
- Pharmaceutical Companies:Vertical integration of single-cell workflows into therapeutic development mandates dedicated infrastructure with validated analytical pipelines. Large manufacturers in New Jersey and Pennsylvania are building captive cell therapy analytics capabilities to reduce dependency on contract research organizations.
- Clinical Laboratories:ISO 13485 quality management requirements and FDA analytical validation timelines constrain platform qualification for diagnostic use.
- Biotechnology Firms:Venture-funded startups prioritize flexible instrument access through core facility partnerships or cloud analytics subscriptions over capital ownership.
Instrument ownership concentrates with Research Institutions. Fastest-growing contract volume flows to Pharmaceutical Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research Triangle Park in North Carolina concentrates single-cell infrastructure through NIH-funded consortia, while venture capital corridors in Massachusetts and California drive commercial platform deployment.
United States
NIH funding concentration at academic medical centers in Maryland, Massachusetts, and California sustains predictable procurement cycles for high-parameter instruments. FDA guidance on cell and gene therapy analytics tightens analytical validation requirements for multi-modal assays entering clinical laboratories. Pharmaceutical manufacturers in New Jersey and Pennsylvania embed single-cell checkpoints into immuno-oncology pipelines as standard practice.
Germany
Cell therapy contract development and manufacturing organizations in Germany pre-qualify platforms against EMA advanced therapy medicinal product requirements. REACH and RoHS frameworks constrain fluoropolymer selection for microfluidic consumables, limiting qualified suppliers for photoresist chemistries. Industrial clusters in Munich and Heidelberg concentrate EMA-aligned quality control analytics for cell therapy release testing.
United Kingdom
Oncology pathology departments in London and Cambridge adopt laser capture microdissection for spatial transcriptomics in formalin-fixed archival tissue. The Medicines and Healthcare products Regulatory Agency aligns with FDA guidance timelines for analytical validation of multi-parameter assays. Biobanks in Manchester and Glasgow open retrospective molecular profiling pipelines to dissect tumor microenvironment heterogeneity.
China
NMPA regulatory frameworks for cell therapy manufacturing accelerate platform qualification for clinical-grade single-cell assays. Domestic biotech clusters in Shanghai and Suzhou deploy droplet-based RNA sequencing for biomarker discovery in immuno-oncology pipelines. Government funding for precision medicine initiatives concentrates procurement in Beijing-Tianjin-Hebei corridor institutions.
Netherlands
Cell therapy manufacturing analytics in Leiden and Amsterdam pre-validate against both EMA and FDA standards simultaneously. ISO 13485 quality management system harmonization supports dual-use platform development spanning research and clinical diagnostic applications. Contract manufacturing organizations concentrate procurement for traceable single-cell quality control assays in release testing workflows.
Single-Cell Omics Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across instrument, reagent, and analytics segments. The vendor base stratifies into three tiers: integrated life science conglomerates with sequencing infrastructure, microfluidic platform specialists with proprietary chip architectures, and emerging cloud analytics providers. Dominant competitive moves include strategic partnerships between instrument manufacturers and bioinformatics platforms, plus backward integration into reagent chemistries to capture recurring consumable revenue.
Within the integrated conglomerate tier, Thermo Fisher Scientific and Danaher occupy positions spanning sample-to-data workflows with broad reagent and instrument portfolios. Among sequencing-focused platforms, Illumina anchors recurring consumable revenue through installed base expansion across academic and clinical accounts. 10x Genomics exemplifies the microfluidic specialist archetype with droplet-based encapsulation systems that define workflow standards for high-throughput RNA sequencing.
| Leading Market Players |
|---|
| QIAGEN N.V. |
| Standard BioTools |
| 10x Genomics |
| BD |
| Mission Bio |
| Illumina |
| Thermo Fisher Scientific |
| Danaher |
| Bio-Rad Laboratories |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical central labs and academic core facilities command pricing power through consolidated procurement volumes, compressing margins for instrument vendors while sustaining premium tiers for validated clinical-grade platforms.
Pricing Analysis
Short lead-time premiums of validated microfluidic consumables support three-tier pricing structure across premium, standard, and economy levels, with ISO 13485-certified clinical-grade reagents commanding the highest tier. Price differentiation hinges on analytical validation documentation and geographic delivery cost to EMA-aligned manufacturing sites in Germany and the Netherlands. Pricing pressure stems from REACH-compliant fluoropolymer substitution costs that vendors absorb rather than pass through. Biotechnology startups exhibit highest price sensitivity, while cell therapy CDMOs prioritize traceability over unit cost.
Supply Chain Analysis
Freight costs for temperature-sensitive reagent shipments from microfluidic foundries in Germany, the Netherlands, and Massachusetts amplify total landed cost for Asian-Pacific cell therapy manufacturers. The supply chain draws from concentrated photoresist chemistry suppliers in Germany and fluoropolymer processors in the United States, creating single-source vulnerability for droplet generation chips. Distribution runs through authorized distributor networks with mandatory cold-chain custody documentation for clinical-grade consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluoropolymer supply concentration under REACH constraints props instrument pricing, as qualified material alternatives remain scarce across the European manufacturing base.
For Market Incumbents: Lock in captive fluoropolymer supply agreements with German and Dutch chemical processors before REACH restrictions tighten further. Deepen backward integration into barcoded reagent chemistries to capture recurring consumable revenue streams that emerging cloud analytics competitors cannot replicate. For New Entrants and Emerging Players: FDA guidance on cell and gene therapy analytics in the United States opens a window for analytical validation service providers to enter as platform-agnostic partners rather than hardware competitors. Target mid-size biotechnology firms in Massachusetts and California seeking flexible instrument access without capital ownership burdens, positioning through subscription-based bioinformatics platforms that bypass incumbent installed-base advantages. For Investors and Strategic Acquirers: The window for entry favors microfluidic consumables specialists with proprietary chip architectures and established clinical validation dossiers. Monitor EMA-FDA harmonization progress on advanced therapy medicinal product traceability requirements as the inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA analytical validation qualification accelerates clinical laboratory contract revenue recognition timelines. |
| Backward Integration | In-house production of barcoded reagent chemistries captures recurring consumable margins from sequencing infrastructure. |
| Platform Integration | Multi-omic barcoding convergence reduces customer dependency on specialized service providers for data interpretation. |
| Geographic Expansion | EMA-aligned manufacturing footprint in Germany and Netherlands qualifies platforms for cell therapy release testing. |
| Strategic Partnership | Cloud analytics distribution partnerships enable smaller research groups to access computational pipelines without capital investment. |
Methodological Framework
Independent corroboration across platform vendor technical documentation, EMA regulatory filings, and NIH procurement databases underwrites the qualitative findings. Primary interviews with cell therapy manufacturing directors, academic core facility managers, regulatory affairs specialists at instrument manufacturers, and pharmaceutical immuno-oncology pipeline executives combined with secondary validation from FDA guidance documents, EMA advanced therapy medicinal product submissions, ISO 13485 audit records, and REACH compliance certifications. Bottom-up instrument shipment tracking and top-down research budget allocation analysis provided cross-verification.
Rate-of-change decomposition across the analysis window separated volume effects from price-mix shifts in consumable revenue streams. Segmentation dimensions modeled include molecular modality, technology platform, therapeutic application, and end-user capital availability tier. CAGRs derived from instrument replacement cycle analysis, publication footprint expansion rates, and pharmaceutical pipeline embedding intensity. Forecast inputs incorporated NIH funding appropriation trajectories and EMA-FDA harmonization timeline assumptions.
The model assumes a particular technology adoption path; alternative pathways for spatial transcriptomics convergence with laser capture microdissection would alter the outlook for droplet-based RNA sequencing platform demand. Forecasts reflect assumptions about regulatory validation timeline compression and fluoropolymer supply continuity that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Apolipoprotein Test Market
Genomics
Multiomics Market
Genomics
AI in Genomics Market
Genomics
Asia-Pacific Whole Exome Sequencing Market
Genomics
Retail Genomics Market
Genomics
Next-Generation Sequencing for Non-Invasive Prenatal Testing Market
Genomics
Short-Read Sequencing Market
Genomics
Asia-Pacific Genetic Testing Market
Genomics
Global Pharmacogenomics Market
Genomics
Global Microbiome Sequencing Services Market
Genomics
North America Microarray Market
Genomics
Pre-Pregnancy Genetic Testing Market
Genomics
United States DNA Sequencing Products Market
Genomics
Next Generation Molecular Assay Market
Genomics
Europe Cancer Biomarkers Market
Genomics
Digital Genome Market