
 Europe Genetic Testing Market | 2026-2036
Europe Genetic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Genetic Testing Market Analysis
Clinical-grade sequencing accuracy is bifurcating the competitive landscape as laboratories demand higher analytical validity for diagnostic decisions. Eurofins Scientific leverages its pan-European laboratory network to sustain processing scale across multiple member states. Illumina anchors the upstream instrumentation layer through installed base dominance in sequencing platforms. QIAGEN differentiates via integrated sample-to-insight workflows that span extraction through bioinformatics interpretation.
Genetic testing encompasses molecular diagnostic methods that analyze DNA, RNA, chromosomes, or proteins to detect heritable mutations, somatic alterations, or pharmacogenomic variants, typically requiring nucleic acid extraction, amplification, and detection with defined analytical sensitivity and specificity thresholds. The primary purpose spans disease diagnosis, carrier screening, prenatal risk assessment, and therapy selection guidance. Oncology within the Application Area segment leads current value generation as tumor profiling becomes standard-of-care for targeted therapy eligibility. Next-Generation Sequencing within the Technology segment captures the fastest expansion as throughput gains and cost reductions displace Sanger methods in routine clinical workflows. Hospitals within the End User segment occupy the dominant procurement position due to embedded pathology infrastructure and direct patient access.
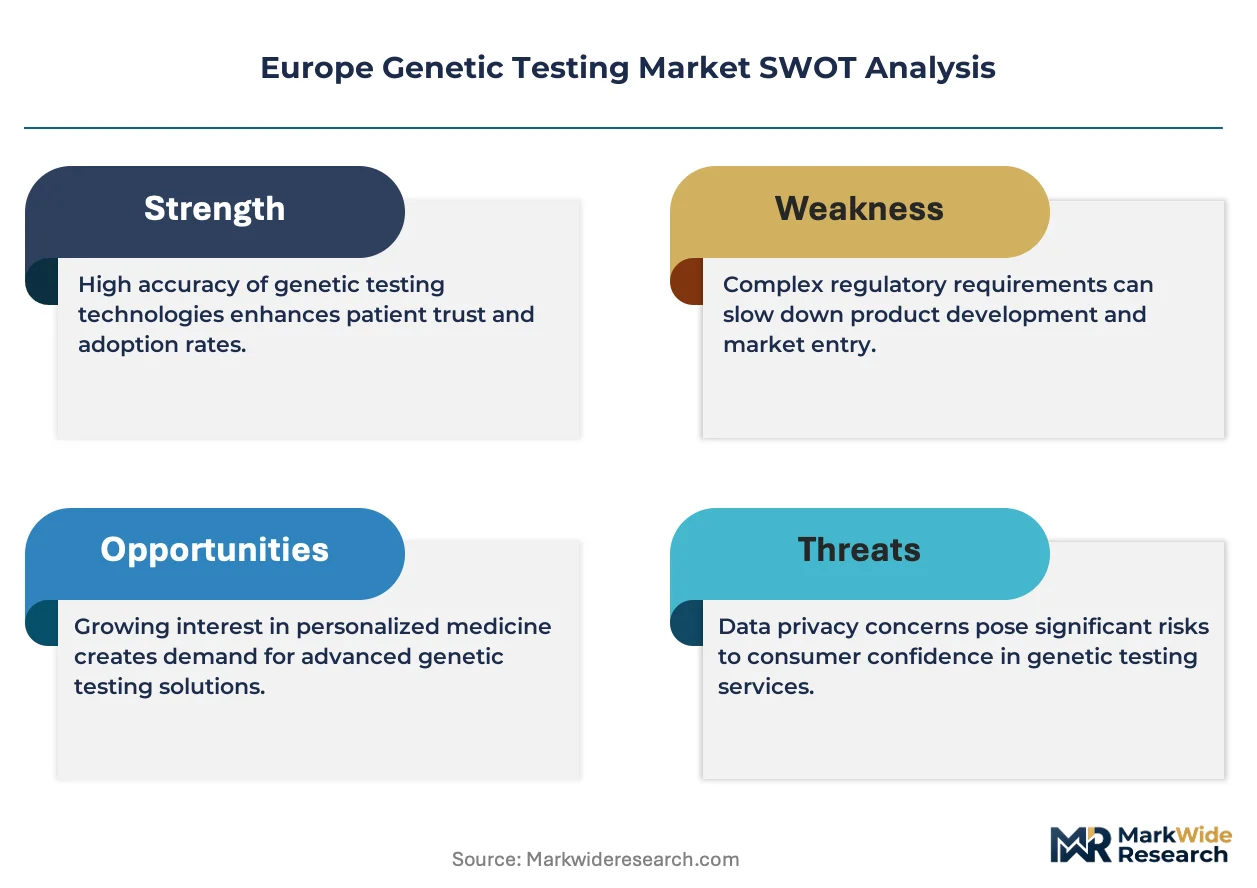
The European Medicines Agency coordinates centralized assessment of companion diagnostic validity while the EU In Vitro Diagnostic Regulation mandates enhanced clinical evidence and post-market surveillance for all genetic tests placed on the European market. EMA guidelines on biomarker qualification and the CE marking requirements under MDR/IVDR collectively elevate barriers to market entry and reshape competitive dynamics. Stakeholders must monitor evolving notified body capacity constraints and harmonized performance standard developments to anticipate compliance timelines and reimbursement negotiation positioning.
Market Dynamics
The EU In Vitro Diagnostic Regulation is compressing commercial timelines as manufacturers rebuild clinical evidence packages for legacy assays while scaling next-generation sequencing workflows.
Growth Catalysts
- Oncology molecular profiling:Tumor sequencing guides targeted therapy selection across European hospital networks. Pathology departments embed NGS into standard diagnostic pathways.
- CE marking under IVDR:Enhanced performance standards elevate analytical validity thresholds. Laboratories prioritize suppliers with robust technical documentation.
- Germany's laboratory infrastructure:Dense networks of specialized molecular diagnostics centers anchor regional processing capacity. Hospital consolidation drives centralized testing volume.
Market Restraints
- Notified body capacity constraints:Limited designated entities under IVDR extend certification timelines. Manufacturers face backlog-induced commercial delays.
- Reimbursement fragmentation:National health technology assessment bodies apply divergent evidence standards. Cross-border test access remains uneven.
- Sample logistics complexity:Cold-chain requirements for nucleic acid stability elevate operational costs. Remote collection networks underperform in Eastern European regions.
Strategic Opportunities
- Pharmacogenomic expansion:Drug-gene interaction testing penetrates cardiology and psychiatry prescribing. Polypharmacy management drives clinical utility.
- Liquid biopsy adoption:Circulating tumor DNA monitoring enables therapy response tracking. Minimal residual disease applications expand addressable testing occasions.
- Direct-to-consumer regulatory clarity:France's ANSM and Germany's BfArM develop oversight frameworks for wellness genetics. Channel diversification accelerates.
Industry Challenges
- Bioinformatics talent scarcity:Variant interpretation pipelines require specialized computational biology expertise. Academic training programs lag clinical demand curves.
- Legacy LIS integration:Hospital information systems lack native interoperability with cloud-based genomic platforms. Middleware development consumes implementation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Genetic Testing Market |
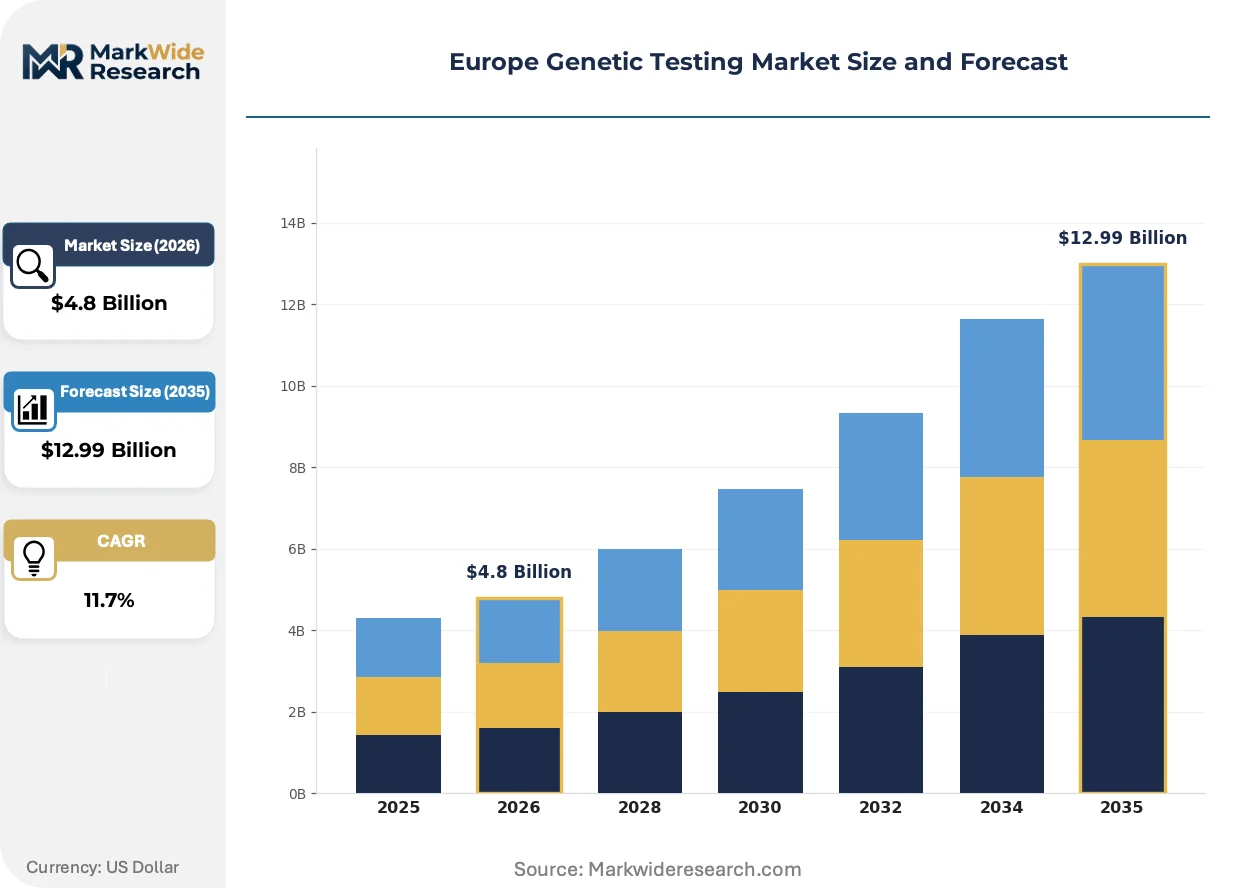
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Diagnostic Testing, Carrier Testing, Prenatal Testing, Newborn Screening Application Area: Oncology, Cardiovascular, Neurology, Pharmacogenomics End User: Hospitals, Laboratories, Research Institutions, Homecare Settings Technology: Sanger Sequencing, Next-Generation Sequencing, Microarray, PCR |
| Companies Covered | Centogene AG, Eurofins Scientific, F. Hoffmann-La Roche Ltd, Illumina, QIAGEN, Thermo Fisher Scientific, Myriad Genetics, Oxford Nanopore Technologies, Danaher, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Genetic Testing Market Emerging Trajectories
Sequencing chemistry advances and regulatory data requirements are restructuring how laboratories validate, procure, and operationalize genetic testing across European healthcare systems.
Long-read sequencing platforms are supplanting short-read methods for structural variant detection in hereditary disease panels. Clinical laboratories in the Netherlands and Switzerland adopt these systems for repeat expansion disorders. The technology is supplanting iterative testing algorithms that previously required multiple assay types.
The EU AI Act imposes risk-classification requirements on diagnostic algorithms that interpret genomic data. Software as a medical device faces enhanced conformity assessment under combined IVDR and AI Act jurisdiction. Oncology decision-support tools encounter the steepest compliance burden as manufacturers reengineer training documentation.
Hospital procurement committees now mandate total cost-of-ownership analysis over instrument acquisition price. Leasing arrangements with per-sample pricing displace capital purchase models in Spanish and Italian health systems. Pathology departments favor vendors offering embedded workflow automation and remote technical support.
Europe Genetic Testing Market Segmentation
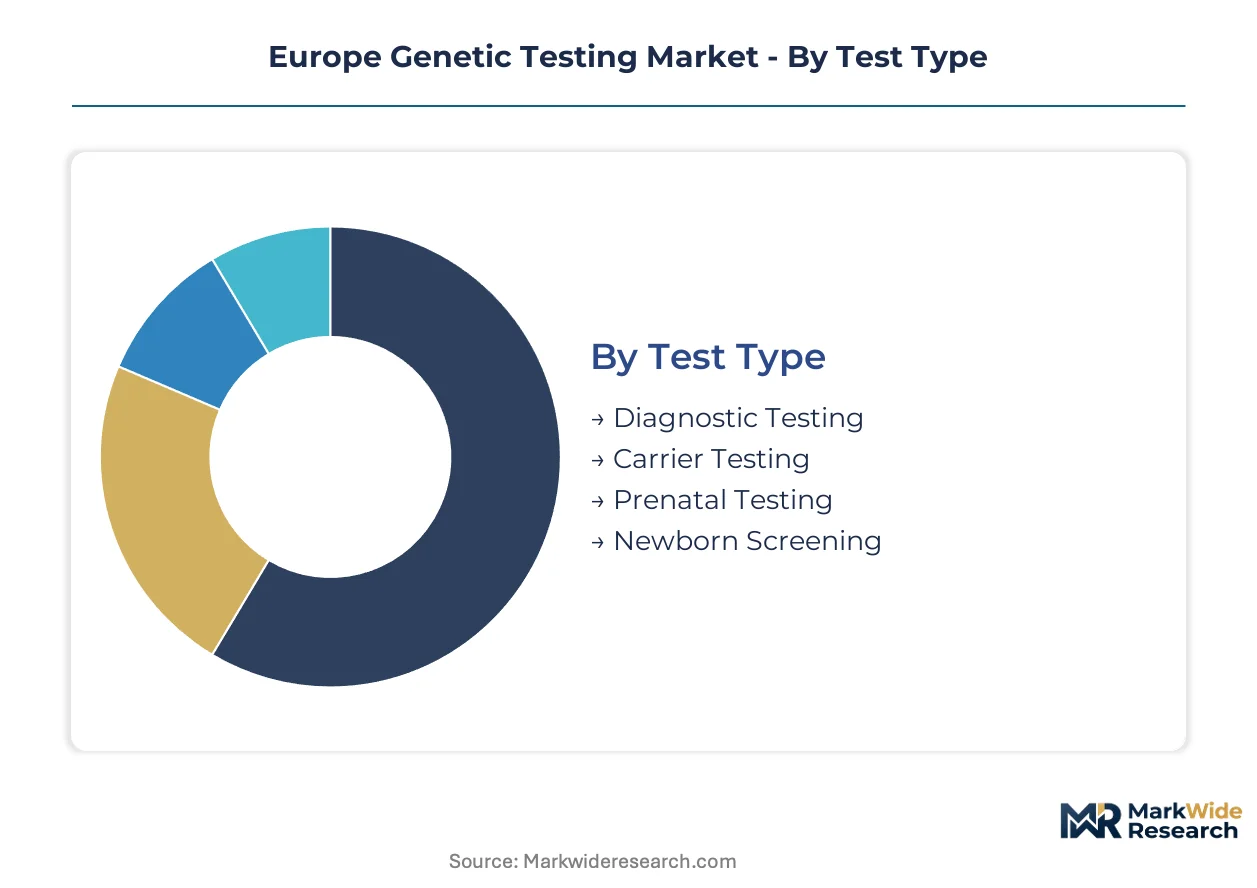
Genetic testing segmentation in Europe reflects divergent reimbursement pathways and technical infrastructure requirements across clinical settings. Test type and application area configurations determine pricing power and regulatory scrutiny intensity.
Test Type:
Margin pools concentrate in prenatal and diagnostic categories where clinical utility evidence commands premium pricing from statutory health insurers.
- Diagnostic Testing:Hereditary disease confirmation and somatic mutation identification drive hospital laboratory procurement. German and French pathology networks prioritize CE-IVDR certified assays with documented analytical validity for rare disease panels.
- Prenatal Testing:Non-invasive prenatal screening for fetal aneuploidy has displaced invasive procedures across Nordic and Benelux healthcare systems. Expanded carrier screening panels gain traction in private maternity clinics.
- Carrier Testing:Preconception screening for autosomal recessive disorders expands through fertility clinic partnerships.
- Newborn Screening:Public health program integration limits commercial pricing flexibility despite high test volumes.
The dominant share belongs to Diagnostic Testing, while Prenatal Testing is closing the gap fastest.
Application Area:
Volume concentration follows oncology therapeutic pipelines where companion diagnostics unlock targeted therapy access.
- Oncology:Tumor profiling for therapy selection dominates hospital molecular pathology budgets. Comprehensive genomic profiling panels identify actionable alterations in lung, breast, and colorectal malignancies across European cancer centers.
- Pharmacogenomics:Drug-gene interaction testing penetrates cardiology and psychiatry prescribing workflows. Dutch and Swedish health systems pilot preemptive pharmacogenomic screening programs.
- Cardiovascular:Hereditary cardiomyopathy and arrhythmia panels serve specialized cardiac genetics clinics.
- Neurology:Neurodegenerative and neuromuscular disorder testing concentrates in academic medical center reference laboratories.
Oncology commands the largest revenue base, with Pharmacogenomics expanding most quickly as polypharmacy management gains clinical traction.
End User:
Procurement sophistication varies sharply between integrated health systems and fragmented outpatient settings.
- Hospitals:Embedded pathology infrastructure and direct patient access anchor diagnostic testing volume. German hospital networks consolidate molecular diagnostics into centralized laboratory hubs.
- Laboratories:Independent and hospital-affiliated reference laboratories process outsourced specialized testing. Eurofins and similar pan-European networks achieve scale across multiple member states.
- Research Institutions:Academic medical centers drive early technology adoption and biomarker validation studies.
- Homecare Settings:Direct-to-consumer genetic testing faces evolving oversight from France's ANSM and Germany's BfArM.
Hospitals retain the dominant procurement position, though Laboratories are gaining share fastest through outsourcing consolidation.
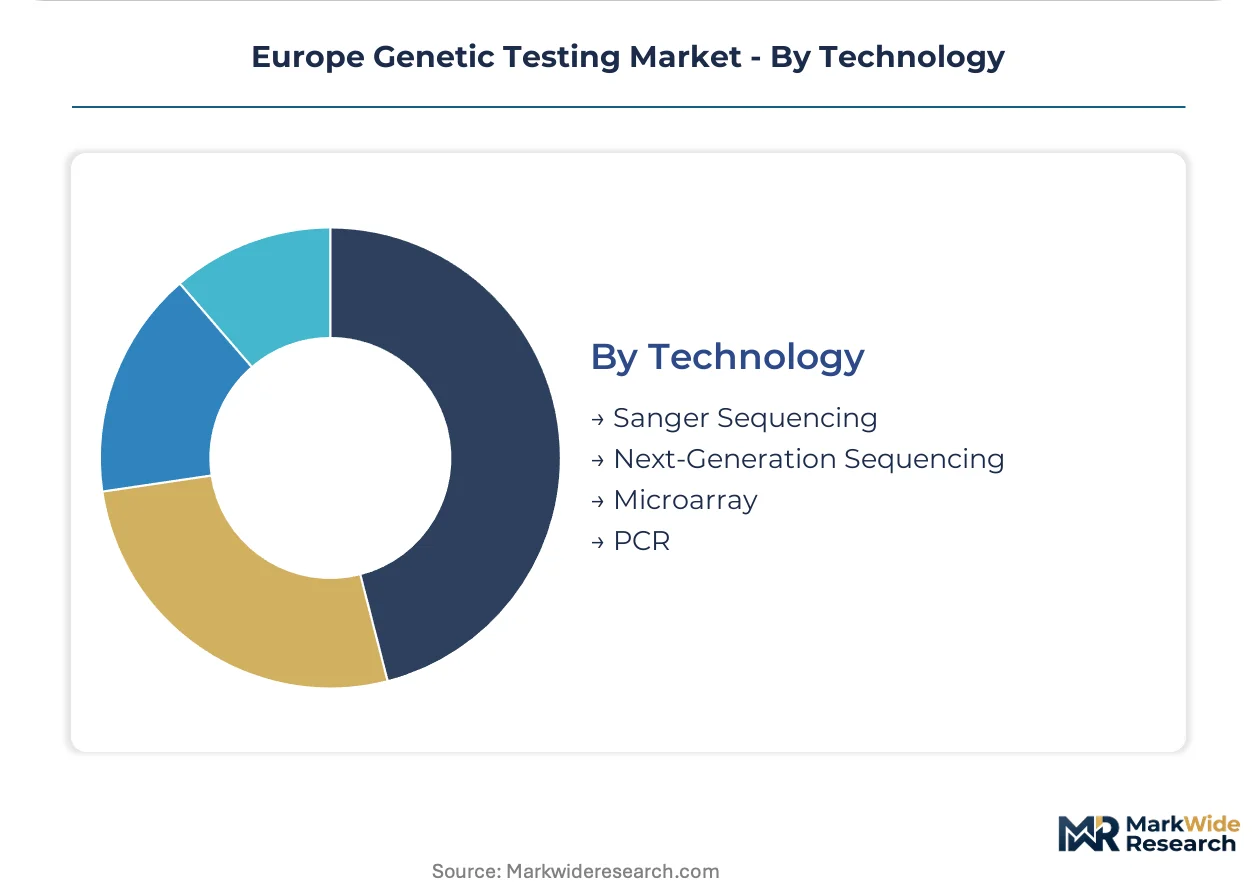
Technology:
Capital intensity and workflow integration requirements shape competitive positioning among platform suppliers.
- Next-Generation Sequencing:High-throughput platforms displace Sanger methods for multigene panel and whole exome applications. Illumina's installed base dominance anchors the upstream instrumentation layer.
- PCR:Real-time amplification remains essential for rapid turnaround applications and point-of-care deployment. QIAGEN integrates sample-to-insight workflows spanning extraction through interpretation.
- Sanger Sequencing:Targeted variant confirmation and single-gene analysis persist in smaller laboratories.
- Microarray:Chromosomal microarray analysis retains utility for copy number variation detection in developmental disorders.
Next-Generation Sequencing holds the leading technology position, while PCR maintains resilient demand through workflow automation advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's genetic testing trade flows reflect a net importer position for specialized reagents and instrumentation, with Germany and Switzerland anchoring export capacity in precision diagnostics while Southern and Eastern European markets rely on cross-border laboratory services and kit supply chains.
Germany
Hospital network consolidation and centralized molecular diagnostics hubs drive testing volume concentration. BfArM oversight of companion diagnostics and genetic tests under IVDR mandates rigorous post-market surveillance. The Munich-Stuttgart corridor hosts dense clusters of specialized pathology laboratories processing oncology panels for domestic and neighboring markets.
United Kingdom
NHS Genomic Medicine Service integration and 100,000 Genomes Programme infrastructure sustain national testing capacity. NICE health technology assessments determine reimbursement eligibility for rare disease and cancer panels. The Cambridge-London corridor concentrates sequencing facilities and bioinformatics talent pools serving both clinical and research demand.
France
Hospital-based molecular genetics platforms and national cancer institute screening programs anchor diagnostic utilization. ANSM regulates direct-to-consumer genetic tests while HAS evaluates clinical utility for statutory reimbursement. The Paris-Saclay cluster coordinates reference laboratory networks for rare disease diagnosis across the national territory.
Netherlands
Preemptive pharmacogenomic pilot programs and integrated primary care genetics expand testing indications beyond oncology. The Dutch Health Council advises on population screening criteria while ZIN governs diagnostic tariff negotiations. Rotterdam and Utrecht academic medical centers host European reference laboratories for hereditary cancer syndromes.
Switzerland
Swissmedic regulates in vitro diagnostics with convergence toward EU IVDR standards despite non-member status. Private health insurance reimbursement structures support premium-priced hereditary disease testing. Basel and Zurich concentrate pharmaceutical-linked diagnostic development alongside clinical laboratory networks serving the alpine region.
Europe Genetic Testing Market Vendor Landscape
Concentration sits with diversified life science conglomerates and specialized genomic platform developers. The competitive structure divides between upstream instrumentation suppliers, integrated workflow providers, and reference laboratory networks. Three archetypes dominate: pan-European laboratory service consolidators, sequencing platform technology owners, and sample-to-insight workflow integrators. Strategic moves center on IVDR compliance certification acceleration and cloud-based bioinformatics partnership architectures.
Among diversified laboratory service networks, Eurofins Scientific exemplifies scale-driven geographic coverage across multiple member states. QIAGEN and Illumina occupy anchor positions at the instrumentation and reagent layers, representing contrasting strategic postures—integrated workflow control versus platform ecosystem dominance. These three entities illustrate how European genetic testing competition stratifies between service scale, technology ownership, and workflow integration vectors.
| Leading Market Players |
|---|
| Centogene AG |
| Eurofins Scientific |
| F. Hoffmann-La Roche Ltd |
| Illumina |
| QIAGEN |
| Thermo Fisher Scientific |
| Myriad Genetics |
| Oxford Nanopore Technologies |
| Danaher |
| Others |
Supply Flow & Price Mechanics
Sequencing platform throughput economics concentrate procurement power among German and Swiss hospital networks, compressing price floors for reagent suppliers while elevating total cost-of-ownership scrutiny for instrumentation vendors. IVDR compliance investments reshape supplier cost structures, feeding through to tiered service pricing across European member states.
Pricing Analysis
Hospital laboratory procurement committees anchor European genetic testing pricing through multi-year reagent rental agreements and per-sample consumable contracts. Three-tier pricing structure across premium CE-IVDR certified assays, standard clinical-grade panels, and economy research-use-only products reflects analytical validity documentation depth and post-market surveillance bundling. Price differentiation hinges on IVDR certification tier and embedded bioinformatics interpretation services. Cost compression in the economy tier intensifies as Eastern European laboratories adopt research-grade workflows for clinical screening. Academic medical centers exhibit highest price sensitivity; private reference laboratories in Switzerland and Germany demonstrate lowest sensitivity due to premium reimbursement structures.
Supply Chain Analysis
Reagent cold-chain inventory cycles extend 6-12 weeks for nucleic acid stabilization chemistries, constraining just-in-time delivery models across Southern European markets. Supply concentrates in Germany, the Netherlands, and Switzerland for precision diagnostics manufacturing, with the United States and China anchoring upstream sequencing instrumentation and oligonucleotide synthesis. Raw material dependencies span fluorophore-conjugated polymerases, semiconductor-grade flow cells, and synthetic guide RNA libraries. Single-source vulnerability in flow cell manufacturing creates bottleneck exposure for NGS platform operators. Distribution runs through pan-European laboratory service networks and specialized cold-chain logistics providers serving hospital molecular pathology departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's genetic testing market represents a high-growth disruption as IVDR regulatory compression and AI Act algorithmic governance converge to reshape competitive entry barriers and incumbent compliance burdens.
For Market Incumbents: Compound installed base advantages through embedded workflow automation and remote technical support subscriptions that lock in hospital laboratory switching costs. Defend against emerging long-read sequencing entrants by accelerating IVDR certification for comprehensive genomic profiling panels. Prioritize backward integration into bioinformatics interpretation software to capture recurring revenue streams and reduce third-party platform dependency. For New Entrants and Emerging Players: Liquid biopsy minimal residual disease monitoring represents the most penetrable service-layer gap where incumbent oncology workflows under-serve therapy response tracking demand. Target pharmacogenomic applications in cardiology and psychiatry prescribing where reimbursement pathways remain unsettled and clinical utility evidence requirements are lower than oncology companion diagnostics. Pursue hospital-at-home partnerships for direct-to-consumer genetic testing channel diversification under France's ANSM and Germany's BfArM emerging oversight frameworks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated sample-to-insight workflow providers with demonstrated IVDR technical documentation capabilities and cloud-based variant interpretation platforms. Long-term viability rests on regulatory compliance infrastructure rather than pure sequencing chemistry innovation. Acquisition target archetype: pan-European reference laboratories with dense notified body relationships and centralized molecular diagnostics hub operations. Monitor notified body designation expansion under IVDR as the critical inflection signal for market entry timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Certification Acceleration | CE marking under IVDR mandates enhanced clinical evidence packages that reshape competitive positioning for legacy assay manufacturers. |
| Cloud Bioinformatics Partnership | Software-as-a-medical-device platforms face combined IVDR and EU AI Act jurisdiction, elevating compliance architecture requirements. |
| Liquid Biopsy Portfolio Expansion | Circulating tumor DNA monitoring unlocks therapy response tracking occasions beyond initial diagnostic profiling in oncology pathways. |
| Pharmacogenomic Screening Pilot | Dutch and Swedish health system programs validate preemptive drug-gene interaction testing for polypharmacy management applications. |
| Pan-European Laboratory Consolidation | Cross-border service networks achieve scale economies through centralized processing hubs serving multiple member state reimbursement regimes. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EMA biomarker qualification guidelines, EU IVDR implementing acts, and hospital procurement database records. Primary interviews engaged molecular pathology laboratory directors, IVDR regulatory affairs specialists, hospital purchasing committee members, and companion diagnostic commercial leads. Secondary validation drew from notified body designation registers, CE marking certification databases, and national health technology assessment body reimbursement determinations. Bottom-up test volume modeling and top-down healthcare expenditure allocation triangulate market size estimates.
Segmentation dimensions modeled span test type, application area, end user, and technology platform across the analysis window. Oncology therapeutic area segmentation incorporates tumor site, therapy line, and biomarker target complexity. Geographic clustering reflects national reimbursement pathway heterogeneity and laboratory infrastructure concentration patterns. CAGRs derive from test volume elasticity to targeted therapy pipeline expansion and sequencing cost decline curves. Forecast inputs include companion diagnostic co-development agreement disclosures and academic medical center NGS platform installation records.
Forecasts assume regulatory continuity in EU IVDR implementation and EMA biomarker qualification pathways; material policy shifts in notified body capacity or AI Act risk classification would require re-modeling. Specific risk factors encompass reimbursement fragmentation across national health technology assessment bodies and sample logistics underperformance in Eastern European cold-chain networks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Next-Generation Sequencing Library Preparation Market
Genomics
Latin America Gene Expression Market
Genomics
Global Genotyping Assay Market
Genomics
Microarray Scanners Market
Genomics
Global Gene Expression Market
Genomics
Genetic Testing Service Market
Genomics
Forensic Genomics Market
Genomics
North America Epigenetics Market
Genomics
Global Lab Automation in Genomics Market
Genomics
NGS-Based RNA-Sequencing Market
Genomics
Retail Genomics Market
Genomics
Apolipoprotein Test Market
Genomics
Microarray Biochips Market
Genomics
Middle East and Africa Whole Exome Sequencing Market
Genomics
Glycan Sequencing Market
Genomics
Japan Next Generation Sequencing Market