
 Latin America Gene Expression Market | 2026-2036
Latin America Gene Expression Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Gene Expression Market Intelligence
Platform licensing revenue is narrowing as instrument manufacturers bundle analytics software with sequencing hardware. Thermo Fisher Scientific leverages its reagent-instrument integration to sustain installed-base loyalty across Brazilian research centers. QIAGEN competes through sample-prep automation that anchors clinical diagnostic workflows in Mexican hospital networks. Illumina, Inc. dominates high-throughput sequencing placements, while Bio-Rad Laboratories specializes in digital PCR systems for translational oncology labs.
Gene expression analysis measures RNA transcript abundance to quantify cellular activity, typically requiring reverse transcription, amplification, and detection sensitivity down to single-copy resolution. The technique enables biomarker validation, drug target identification, and disease subtype classification across therapeutic areas. Reagent and kit segments capture recurring consumable demand tied to installed instrument bases, whereas next-generation sequencing and RNA-Seq platforms represent the fastest-expanding technology category as Brazilian and Argentine centers replace legacy microarray infrastructure. Pharmaceutical companies and biotechnology firms constitute the highest-margin end-user segment due to regulated assay validation requirements and longitudinal study contracts.
ANVISA in Brazil and COFEPRIS in Mexico enforce in vitro diagnostic registration pathways that shape product approval timelines for expression-based clinical assays. Argentina's national pharmaceutical regulator maintains import documentation requirements that affect reagent shelf-life logistics and cold-chain distribution economics. ISO 13485 certification and WHO prequalification standards increasingly determine vendor eligibility for public procurement tenders across the region. Stakeholders must weigh regulatory harmonization progress against fragmented national reimbursement policies when prioritizing country entry sequencing.
Market Dynamics
Platform consolidation around integrated reagent-instrument systems is compressing margins for standalone consumable suppliers across Brazilian and Mexican genomics centers. Thermo Fisher Scientific's bundled analytics software with sequencing hardware exemplifies this structural shift toward captive ecosystem lock-in.
Growth Catalysts
- ANVISA pathway alignment:Brazil's streamlined in vitro diagnostic registration for expression-based oncology assays accelerates clinical assay commercialization timelines for validated biomarker panels.
- RNA-Seq infrastructure replacement:Argentine and Chilean research centers are retiring legacy microarray systems, creating pull-through demand for next-generation sequencing consumables and bioinformatics support.
- FAPESP-funded cluster expansion:São Paulo-Campinas corridor genomics centers concentrate purchasing power and drive standardization around high-throughput workflows.
Market Restraints
- Reagent cold-chain fragility:Argentina's import documentation requirements extend customs clearance timelines, compressing effective shelf life for temperature-sensitive enzyme kits and amplification reagents.
- Instrument vendor concentration:Illumina's dominance in high-throughput sequencing placements across Brazil and Mexico limits buyer negotiating leverage and creates single-source dependency risk.
- Microarray substitution drag:Legacy Affymetrix and Agilent microarray infrastructure in Colombian and Peruvian academic centers delays full RNA-Seq migration, slowing consumable refresh cycles.
Strategic Opportunities
- COFEPRIS diagnostic expansion:Mexico's hospital network clinical diagnostic workflows remain underpenetrated for expression-based companion diagnostics, offering first-mover positioning for automated sample-prep platforms.
- Single-cell multi-omics convergence:Integration of single-cell RNA-Seq with spatial transcriptomics creates premium workflow bundles for translational oncology labs in Brazil's research triangle.
- ISO 13485 procurement eligibility:WHO prequalification standards increasingly determine vendor access to public tenders across Central American ministries of health.
Industry Challenges
- Bioinformatics talent scarcity:Shortage of trained computational biologists across Brazilian and Mexican academic centers constrains full utilization of sequencing instrument capacity and delays study turnaround.
- Multi-vendor integration complexity:Fragmented instrument fleets combining Illumina, Thermo Fisher, and Bio-Rad systems create interoperability friction for standardized data pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Gene Expression Market |
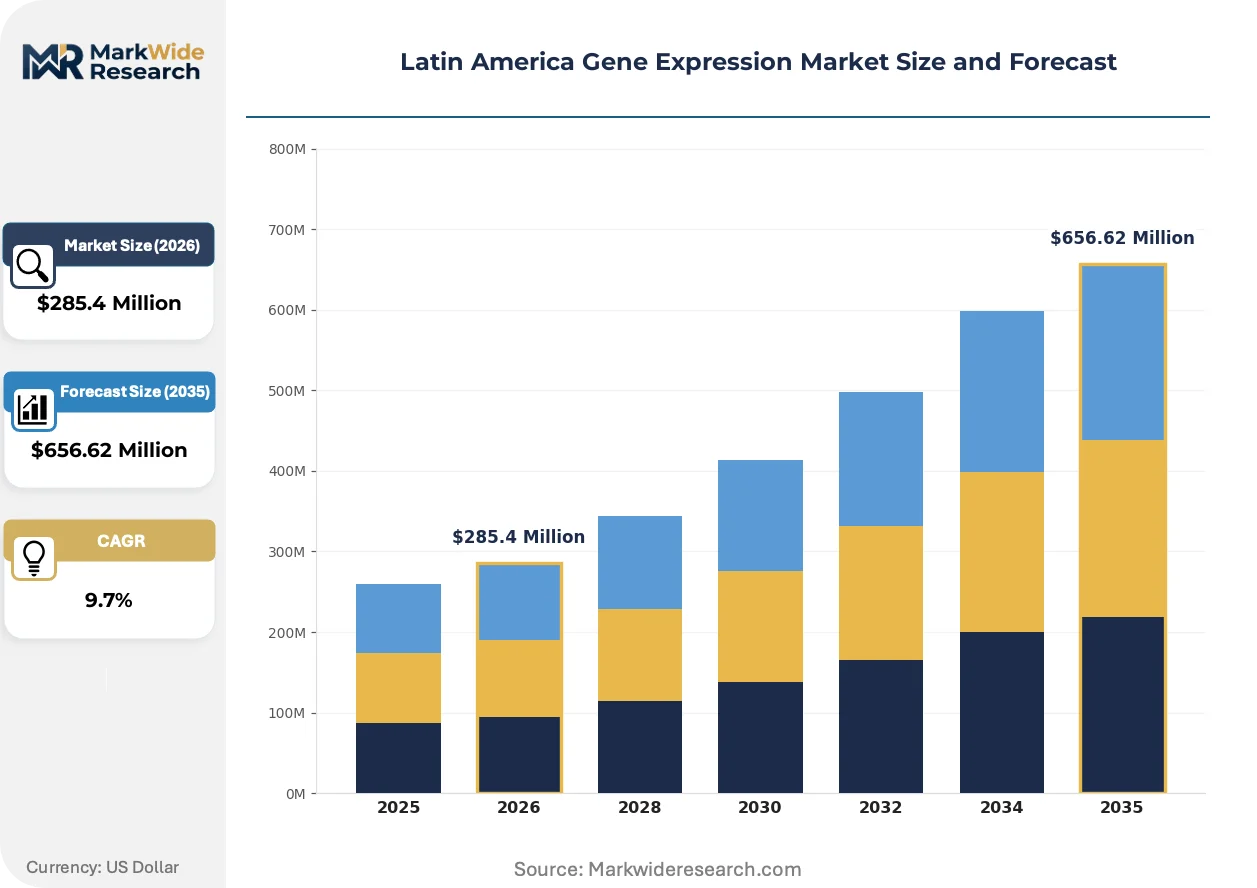
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $656.62 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Kits Application: Clinical Diagnostics, Drug Discovery, Academic Research, Agriculture Technology: RT-qPCR, Microarray, Next-Generation Sequencing, RNA-Seq End User: Hospitals, Research Institutions, Pharmaceutical Companies, Biotechnology Firms |
| Companies Covered | Illumina, Inc., QIAGEN, PerkinElmer, Agilent Technologies, Bio-Rad Laboratories, Thermo Fisher Scientific, Luminex Corporation, Oxford Gene Technology Group, GE Healthcare, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Gene Expression Market Strategic Shifts & Innovations
Cloud-native bioinformatics platforms are compressing the traditional hardware-software boundary in gene expression analysis, enabling distributed computing for transcriptomic data without localized server infrastructure. This shift reconfigures vendor value capture toward recurring software subscriptions.
Single-cell RNA-Seq is virtualizing the bulk transcriptomics market by enabling cell-type-specific expression profiling at scale. Brazilian oncology research centers adopt 10x Genomics Chromium platforms at twice the pace of bulk RNA-Seq expansions. This virtualization collapses the distinction between discovery and validation phases, compressing biomarker development timelines.
ANVISA and COFEPRIS are harmonizing in vitro diagnostic registration pathways for expression-based clinical assays, reducing redundant documentation burdens for cross-border kit commercialization. Manufacturers now submit unified technical files covering both Brazilian and Mexican market entry. Smaller reagent suppliers without regulatory affairs capacity face exclusion from this streamlined pathway.
Research consortia across São Paulo and Mexico City are consolidating purchasing through centralized procurement platforms, displacing individual laboratory reagent sourcing. FAPESP-funded centers negotiate multi-year consumable contracts with volume guarantees. This concentration shifts pricing power toward institutional buyers and compresses distributor margins in the corridor.
Latin America Gene Expression Market Segmentation
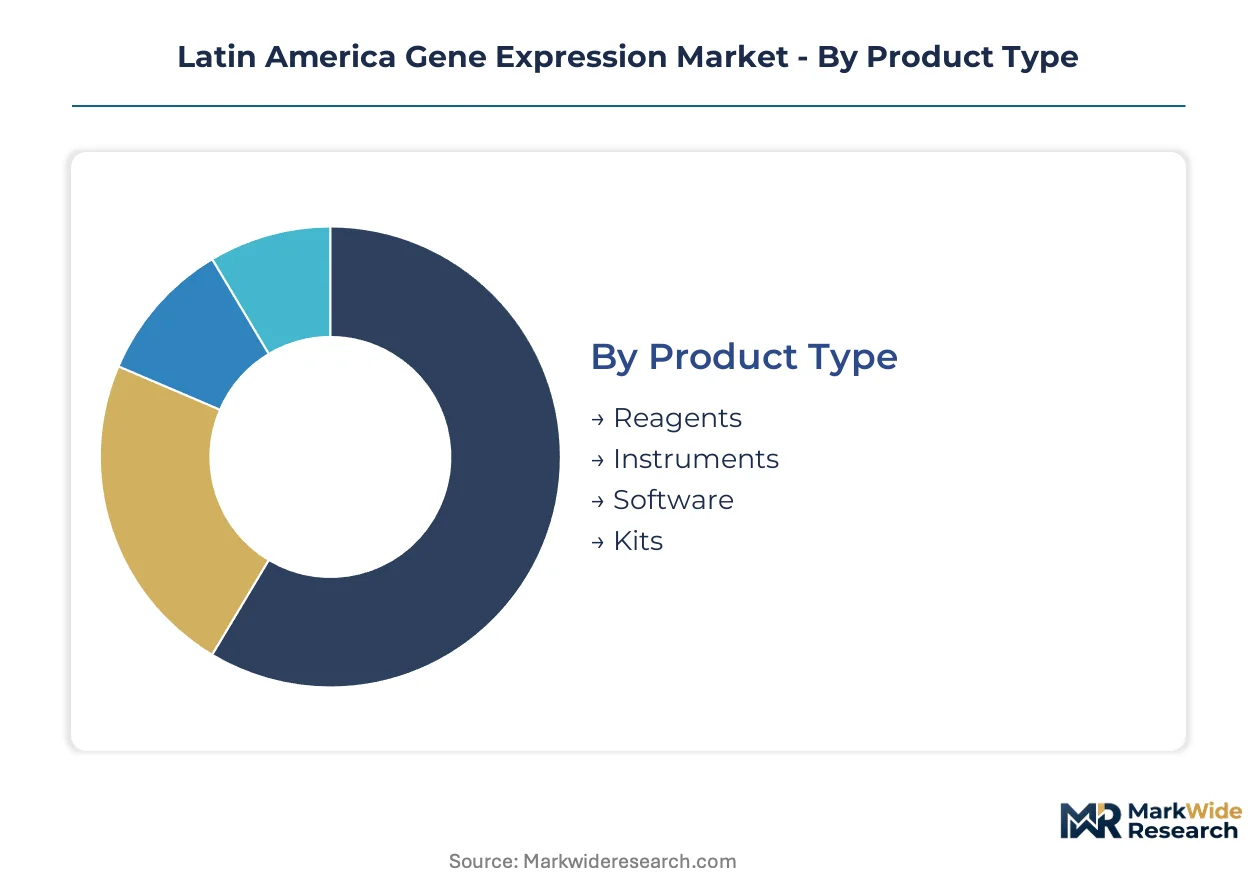
Gene expression market segmentation reveals distinct purchasing patterns across product tiers and end-use applications. Each dimension carries implications for margin structure, regulatory pathway complexity, and vendor positioning strategy across Brazilian and Mexican demand centers.
Product Type:
Cost tier stratification separates recurring consumable revenue from capital-intensive instrument placements and recurring software subscriptions.
- Reagents:Enzyme mixes, reverse transcription buffers, and amplification master mixes constitute the highest-velocity revenue stream. São Paulo-Campinas corridor genomics centers anchor regional demand through FAPESP-funded multi-year consumable contracts. Cold-chain logistics constraints in Argentina compress effective shelf life and inflate working capital requirements for distributors.
- Instruments:Sequencing platforms, thermal cyclers, and microarray scanners represent capital deployment decisions with 5-7 year replacement cycles. Brazilian academic centers concentrate purchasing power through centralized procurement platforms that shift negotiating leverage toward institutional buyers.
- Software:Bioinformatics pipelines and cloud-native analytics platforms capture recurring subscription revenue from research institutions facing computational biologist talent scarcity.
- Kits:Pre-formulated sample-prep and library construction bundles standardize workflows for hospital diagnostic laboratories under ANVISA and COFEPRIS oversight.
Reagents hold installed capacity. Software is rotating up the share rankings.
Application:
End-use purpose determines regulatory intensity, validation burden, and pricing elasticity across the value chain.
- Clinical Diagnostics:Companion diagnostic assays and oncology biomarker panels require ANVISA or COFEPRIS in vitro diagnostic registration. Mexican hospital networks remain underpenetrated for expression-based testing, creating first-mover positioning for automated workflow providers.
- Drug Discovery:Pharmaceutical target identification and lead optimization programs command premium pricing for validated, GMP-compliant reagent grades. Longitudinal study contracts generate multi-year revenue visibility for kit suppliers.
- Academic Research:RNA-Seq and single-cell transcriptomics projects at Brazilian and Argentine universities drive instrument utilization rates. Bioinformatics talent bottlenecks constrain full sequencing capacity deployment.
- Agriculture:Crop trait mapping and livestock genomics applications concentrate in Brazilian agribusiness research institutes with distinct procurement timelines from biomedical sectors.
Clinical Diagnostics commands margin premiums. Academic Research is climbing the fastest.
Technology:
Platform maturity and throughput capability segment vendor ecosystems and customer switching costs.
- RT-qPCR:Quantitative reverse transcription PCR remains the workhorse for targeted gene expression validation with established regulatory acceptance. Mexican hospital laboratories standardize on this modality for infectious disease and oncology marker detection.
- Microarray:Legacy Affymetrix and Agilent infrastructure persists in Colombian and Peruvian academic centers, delaying full RNA-Seq migration and slowing consumable refresh cycles. Argentine and Chilean centers are retiring these systems.
- Next-Generation Sequencing:Illumina dominates high-throughput placements across Brazil and Mexico, creating single-source dependency risk for buyers. Platform consolidation around integrated reagent-instrument bundles compresses standalone consumable margins.
- RNA-Seq:Whole-transcriptome sequencing represents the steepest expansion trajectory as Brazilian oncology research centers adopt 10x Genomics Chromium platforms at twice the pace of bulk RNA-Seq expansions.
Next-Generation Sequencing holds installed capacity. RNA-Seq is rotating up the share rankings.
End User:
Customer type differentiation separates regulated diagnostic workflows from exploratory research environments with distinct procurement authority structures.
- Hospitals:Clinical diagnostic laboratories in São Paulo and Mexico City drive demand for automated sample-prep platforms and regulatory-compliant assay kits. COFEPRIS registration requirements shape vendor eligibility.
- Research Institutions:FAPESP-funded genomics centers in the São Paulo-Campinas corridor concentrate purchasing power and drive standardization around high-throughput workflows. Bioinformatics support contracts accompany instrument placements.
- Pharmaceutical Companies:Regulated assay validation requirements and longitudinal biomarker study contracts generate the highest-margin revenue segment for reagent suppliers with ISO 13485 certification.
- Biotechnology Firms:Translational oncology startups in Brazil's research triangle adopt single-cell multi-omics bundles, integrating spatial transcriptomics with RNA-Seq for compressed biomarker development timelines.
Research Institutions hold installed capacity. Biotechnology Firms is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Latin America. Brazilian buyers absorb premium pricing for integrated sequencing systems, while Argentine and Peruvian purchasers remain acutely sensitive to reagent cost per run and extended customs clearance timelines.
Brazil
FAPESP-funded genomics centers in the São Paulo-Campinas corridor drive concentrated purchasing power for high-throughput RNA-Seq workflows. ANVISA's streamlined in vitro diagnostic registration pathway accelerates commercialization timelines for oncology biomarker panels. São Paulo's research triangle anchors translational oncology activity where single-cell multi-omics bundles command premium positioning.
Mexico
Hospital network clinical diagnostic workflows in Mexico City and Guadalajara generate underpenetrated demand for automated sample-prep platforms. COFEPRIS registration requirements shape vendor eligibility for expression-based companion diagnostics. The Mexico City Metro clusters purchasing authority for hospital laboratory procurement decisions.
Argentina
Research centers in Buenos Aires and Córdoba are retiring legacy microarray infrastructure, creating replacement demand for next-generation sequencing consumables. The national pharmaceutical regulator's import documentation requirements extend customs clearance timelines and compress effective shelf life for temperature-sensitive enzyme kits. Buenos Aires anchors academic RNA-Seq adoption despite cold-chain logistics constraints.
Chile
Santiago-based oncology research institutes pursue RNA-Seq infrastructure upgrades with funding from national science agencies. The country's national pharmaceutical regulator maintains alignment with international quality benchmarks for diagnostic reagent registration. The Santiago-Valparaíso corridor concentrates genomics research capacity and drives standardization around validated assay workflows.
Colombia
Bogotá academic centers retain legacy Affymetrix and Agilent microarray systems, delaying full RNA-Seq migration and slowing consumable refresh cycles. The national health regulator's diagnostic registration pathways remain fragmented compared to Brazilian and Mexican harmonization progress. Bogotá's university hospital networks represent latent demand for expression-based clinical assays pending regulatory clarity.
Latin America Gene Expression Market Key Industry Players
Integrated-system providers and standalone consumable specialists split the market along workflow-capture versus price-competition lines. The vendor base concentrates around three strategic archetypes: instrument manufacturers bundling captive reagent ecosystems, sample-prep automation specialists anchoring diagnostic workflows, and bioinformatics platform providers capturing recurring software subscriptions. Dominant competitive moves include strategic partnerships between hardware manufacturers and cloud analytics providers, plus geographic expansion through distributor network consolidation in underpenetrated hospital segments.
Among US-based integrated-system providers, Thermo Fisher Scientific and Illumina occupy positions exemplifying the captive-ecosystem archetype through reagent-instrument bundling. QIAGEN represents the sample-prep automation specialist tier competing for clinical diagnostic workflow anchoring. These three companies collectively illustrate how platform consolidation compresses margins for standalone consumable suppliers while shifting value capture toward recurring revenue streams.
| Leading Market Players |
|---|
| Illumina, Inc. |
| QIAGEN |
| PerkinElmer |
| Agilent Technologies |
| Bio-Rad Laboratories |
| Thermo Fisher Scientific |
| Luminex Corporation |
| Oxford Gene Technology Group |
| GE Healthcare |
| Others |
Cost & Logistics Intelligence
Undercapacity in Brazilian bioinformatics talent pipelines compresses instrument utilization rates and forces pricing premiums on bundled software support contracts across São Paulo-Campinas genomics centers. This utilization squeeze simultaneously inflates after-sales service margins and accelerates vendor consolidation around integrated reagent-instrument systems that capture lifetime value through captive consumable lock-in.
Pricing Analysis
After-sales revenue from multi-year bioinformatics support contracts and reagent subscription tiers drives lifetime value capture for instrument manufacturers serving Brazilian research institutions. Three-tier pricing structure across premium, standard, and economy levels separates GMP-compliant pharmaceutical-grade reagents from research-use-only kits and bulk academic consumables. Pricing pressure stems from centralized procurement platforms at FAPESP-funded centers that aggregate volume and squeeze distributor margins. Academic research buyers exhibit highest price sensitivity due to grant-funded budget constraints, while pharmaceutical companies absorb premium pricing for validated assay validation services.
Supply Chain Analysis
Tariff exposure between the United States and Brazil dominates landed cost calculations for sequencing instruments and thermal cycler hardware imported into Latin American markets. Manufacturing concentration in the United States, Germany, and China shapes regional availability of RNA-Seq platforms and sample-prep automation systems. Raw material dependencies on purified enzymes, fluorescent dyes, and synthetic oligonucleotides sourced from North American and European suppliers create single-source vulnerability for temperature-sensitive reagent kits. Distribution runs through authorized distributor networks with cold-chain certification requirements, particularly critical for Argentine customs clearance timelines that compress enzyme shelf life.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Latin America gene expression market rewards vendors who control scarce bioinformatics deployment capabilities, as computational biologist shortages across Brazilian and Mexican academic centers constrain full instrument utilization and create service-anchoring opportunities.
For Market Incumbents: Harden installed-base loyalty by deepening reagent-instrument integration through exclusive consumable contracts at São Paulo-Campinas corridor genomics centers. Invest in ISO 13485 certification to maintain eligibility for public procurement tenders as WHO prequalification standards tighten vendor access across Central American ministries of health. Acquire specialized bioinformatics platform providers to fill talent gaps and capture recurring software subscription revenue from research institutions facing computational workforce constraints. For New Entrants and Emerging Players: Build out automated sample-prep platform offerings targeting underpenetrated Mexican hospital diagnostic workflows before COFEPRIS registration pathways mature and incumbent positions solidify. Establish partnerships with Argentine distributors possessing validated cold-chain logistics capabilities to circumvent extended customs clearance timelines that compress reagent shelf life. Lead with RNA-Seq infrastructure replacement narratives at retiring microarray centers in Buenos Aires and Córdoba to differentiate from legacy platform vendors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among bioinformatics software providers with cloud-native analytics platforms that capture subscription income from research institutions facing persistent computational biologist scarcity. Long-term viability favors vendors with regulatory affairs capacity spanning ANVISA and COFEPRIS harmonization pathways, as streamlined cross-border registration reduces commercialization friction. Watch for inflection signals in single-cell multi-omics adoption rates at Brazilian translational oncology labs, where 10x Genomics platform expansion indicates premium workflow bundle readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Affairs Capacity Expansion | ANVISA-COFEPRIS harmonization pathway access accelerates cross-border kit commercialization timelines for validated biomarker panels. |
| Bioinformatics Platform Acquisition | Cloud-native analytics capabilities address computational biologist scarcity constraining sequencing instrument utilization across Brazilian academic centers. |
| Cold-Chain Distribution Partnership | Argentine customs clearance complexity demands logistics partners with validated temperature-controlled warehousing to protect enzyme kit shelf life. |
| Single-Cell Multi-Omics Bundle Development | Integration of 10x Genomics Chromium platforms with spatial transcriptomics captures premium positioning in São Paulo's translational oncology research triangle. |
| Centralized Procurement Platform Engagement | FAPESP-funded genomics center contracts aggregate purchasing power and drive standardization around high-throughput RNA-Seq workflows. |
Research Approach
A spread of perspectives from genomics center directors, hospital laboratory managers, regulatory affairs specialists at kit manufacturers, and distributor logistics operators converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against ANVISA registration databases, COFEPRIS approval filings, FAPESP funding disbursement records, and academic publication repositories tracking RNA-Seq platform adoption. Bottom-up instrument placement counts and top-down reagent consumption estimates were triangulated to anchor market sizing.
Demand-supply balance modeling tracked replacement cycles for legacy microarray infrastructure against new RNA-Seq platform deployments across the analysis window. Segmentation dimensions included product type tier, application regulatory intensity, technology platform maturity, and end-user procurement authority structure. CAGRs were derived from fitted growth curves incorporating academic funding trajectories, pharmaceutical biomarker study pipelines, and diagnostic assay commercialization timelines specific to oncology companion diagnostic development.
Stress conditions across Argentine import documentation delays, Brazilian bioinformatics talent availability, and Mexican hospital network penetration rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts incorporate assumptions regarding ANVISA-COFEPRIS harmonization progress, centralized procurement platform expansion, and single-cell technology adoption velocity that could shift if regulatory clarity or funding priorities diverge from baseline trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Pharmacogenomic (Pgx) Testing Market
Genomics
Global Whole Genome Sequencing (WGS) Market
Genomics
Point-Of-Care Genetic Testing Market
Genomics
Gene Sequencing Market
Genomics
Genetic Testing Panels Market
Genomics
Europe Genetic Testing Market
Genomics
NGS Automation Market
Genomics
Alagille Syndrome Market
Genomics
Middle East and Africa Genetic Testing Market
Genomics
Rare Disease Genetic Testing Market
Genomics
Global NGS Sample Preparation Market
Genomics
Spatial OMICS Market
Genomics
Mendelian Disorders Testing Market
Genomics
Kearns-Sayre Syndrome Market
Genomics
Europe Epigenetics Market
Genomics
Genetic Testing Service Market