
 Oligonucleotide Pool Market | 2026-2036
Oligonucleotide Pool Market Size, Share, and Industry Trends Forecast 2026-2036
Oligonucleotide Pool Market Outlook
The split between premium-grade and commodity oligonucleotide pools is hardening. Twist Bioscience leverages semiconductor-based DNA synthesis to anchor high-throughput screening contracts with top-ten pharmaceutical buyers. Integrated DNA Technologies sustains its position through proprietary Ultramer chemistry that extends sequence length capabilities beyond standard offerings. Eurofins Scientific competes on geographic coverage, operating synthesis facilities across three continents to reduce shipping times for time-sensitive CRISPR libraries.
An oligonucleotide pool comprises thousands to millions of distinct DNA or RNA sequences synthesized in parallel, typically ranging from 20 to 120 nucleotides with controlled modifications at the 5' or 3' termini, and serves as a reagent for multiplexed gene editing, barcode sequencing, and synthetic biology assembly. Synthetic oligonucleotides occupy the largest revenue share due to their ubiquity in PCR primer sets and sequencing adapters, while CRISPR technology represents the fastest-expanding technology segment as pooled guide RNA libraries displace single-target approaches in functional genomics. Diagnostic tests applications retain mature, steady demand, but therapeutic development commands the deepest margin pools because cGMP-grade synthesis requires extensive purification and traceability documentation.
FDA nucleic acid guidance documents and EMA's Good Manufacturing Practice Annex 2 revisions shape product standards by mandating residual solvent limits and endotoxin thresholds that filter out smaller synthesis providers. ISO 13485 certification for in vitro diagnostic raw materials further constrains market access for uncertified entrants. Stakeholders must monitor evolving pharmacopeial monographs for synthetic oligonucleotides, as impending purity specification changes will force capital allocation decisions between upgrading existing capacity or exiting sub-scale operations.
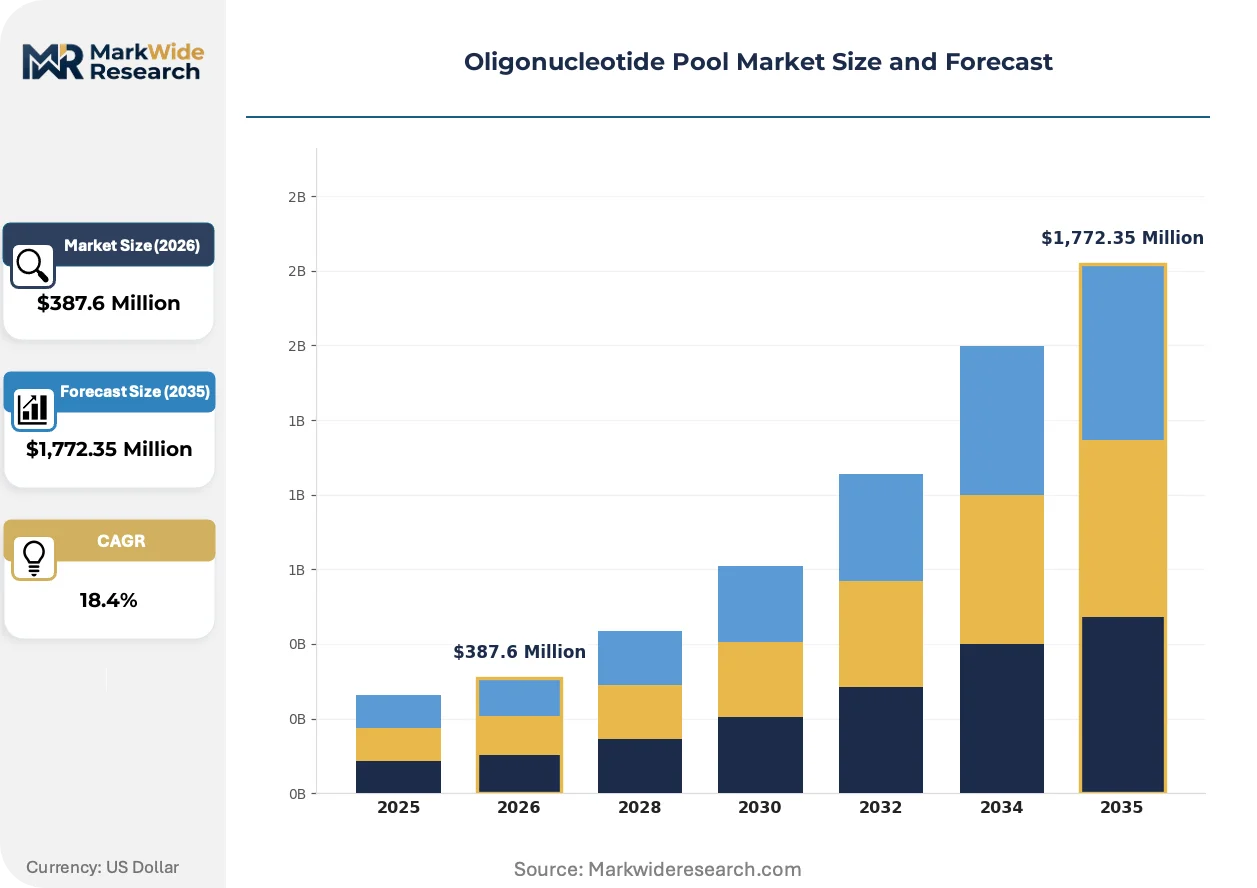
Market Dynamics
CRISPR-based functional genomics is accelerating oligonucleotide pool consumption as pharmaceutical firms shift from single-target validation to multiplexed screening architectures. This technological pivot compresses synthesis timelines and elevates purity requirements, restructuring procurement relationships between buyers and synthesis providers.
Growth Catalysts
- EMA Good Manufacturing Practice Annex 2 revisions:Tightened nucleic acid purity benchmarks compel therapeutic developers to source cGMP-grade pools, filtering demand toward certified manufacturers with validated synthesis protocols.
- CRISPR screening platforms:Biotechnology firms expanding target validation programs require high-complexity guide RNA libraries that commodity synthesis cannot deliver, pulling volume toward premium-capability providers.
- Boston and San Diego biotech clusters:Concentrated R&D expenditure in these metropolitan hubs generates disproportionate demand for rapid-turnaround oligo pools with extensive modification flexibility.
Market Restraints
- Phosphoramidite input cost volatility:Specialized nucleotide building blocks face supply concentration among German and Japanese chemical manufacturers, exposing synthesis costs to currency and energy price fluctuations.
- ISO 13485 certification barriers:Diagnostic-grade pool requirements constrain market access for uncertified entrants, consolidating supply among established players with quality management infrastructure already deployed.
- Residual solvent elimination complexity:FDA-mandated limits on acetonitrile and ammonia traces require capital-intensive purification upgrades that sub-scale facilities cannot finance.
Strategic Opportunities
- Cell and gene therapy manufacturing:Viral vector production and CAR-T engineering require patient-specific oligo barcodes and primers, opening specialized synthesis contracts outside traditional research reagent channels.
- India's PLI scheme for biopharma:Production-linked incentives for active pharmaceutical ingredients extend to oligonucleotide precursors, attracting contract manufacturing investment to reduce import dependence.
- Next-generation sequencing library prep automation:Convergence of acoustic liquid handling and enzymatic fragmentation creates demand for pre-pooled adapter sets with standardized concentrations and plate-ready formatting.
Industry Challenges
- Oligonucleotide chemist talent scarcity:Phosphoramidite synthesis and purification process development require specialized expertise that academic programs produce insufficiently, extending hiring timelines for scale-up operations.
- Multi-site cGMP qualification:Synthesis providers expanding geographic coverage must replicate analytical validation and environmental monitoring systems across facilities, multiplying compliance documentation burdens.
- Guide RNA off-target liability:Therapeutic developers face indemnification and performance risk as CRISPR pools with imperfect specificity enter clinical pipelines, requiring enhanced sequence verification protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oligonucleotide Pool Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,772.35 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Oligonucleotides, Amplification Oligonucleotides, Labeled Oligonucleotides, Modification Oligonucleotides Application: Genetic Engineering, Therapeutic Development, Diagnostic Tests, Antisense Therapeutics End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Contract Research Organizations Technology: Polymerase Chain Reaction, Next-Generation Sequencing, Microarray Analysis, CRISPR Technology |
| Companies Covered | Agilent Technologies, Twist Bioscience, Integrated DNA Technologies, GenScript, Creative Biogene, Eurofins Scientific, Merck KGaA, CustomArray, LGC Biosearch Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oligonucleotide Pool Market Strategic Shifts
Semiconductor-based DNA synthesis is compressing cost curves and throughput ceilings simultaneously, enabling applications previously constrained by reagent economics. Three interconnected developments are restructuring how pools are designed, manufactured, and consumed.
Semiconductor-driven parallel synthesis is expanding into pharmaceutical discovery workflows. Twist Bioscience's silicon-based manufacturing platform generates millions of distinct sequences per run, enabling genome-wide CRISPR libraries that were economically unfeasible with traditional column-based chemistry. Top-ten pharmaceutical buyers now specify semiconductor synthesis for high-throughput screening contracts, compressing per-sequence costs by an order of magnitude and displacing lower-throughput alternatives in target validation.
REACH chemical registration requirements are extending to oligonucleotide manufacturing inputs. The European Chemicals Agency's substance evaluation process now captures phosphoramidite monomers and specialized reagents, forcing synthesis providers to document supply chain provenance and toxicity profiles. European therapeutic developers face extended qualification timelines for imported pools, accelerating regional manufacturing investment to avoid customs-related release delays.
Consolidated procurement through centralized biotech purchasing cooperatives is reshaping supplier relationships. Mid-sized pharmaceutical and agricultural biotechnology firms now aggregate oligonucleotide demand through group purchasing organizations, extracting volume discounts and standardized quality agreements that individual buyers could not negotiate. This concentration is most visible in the United States, where Boston-area purchasing cooperatives have consolidated reagent sourcing for over fifty gene therapy and genome editing ventures.
Oligonucleotide Pool Market Segmentation
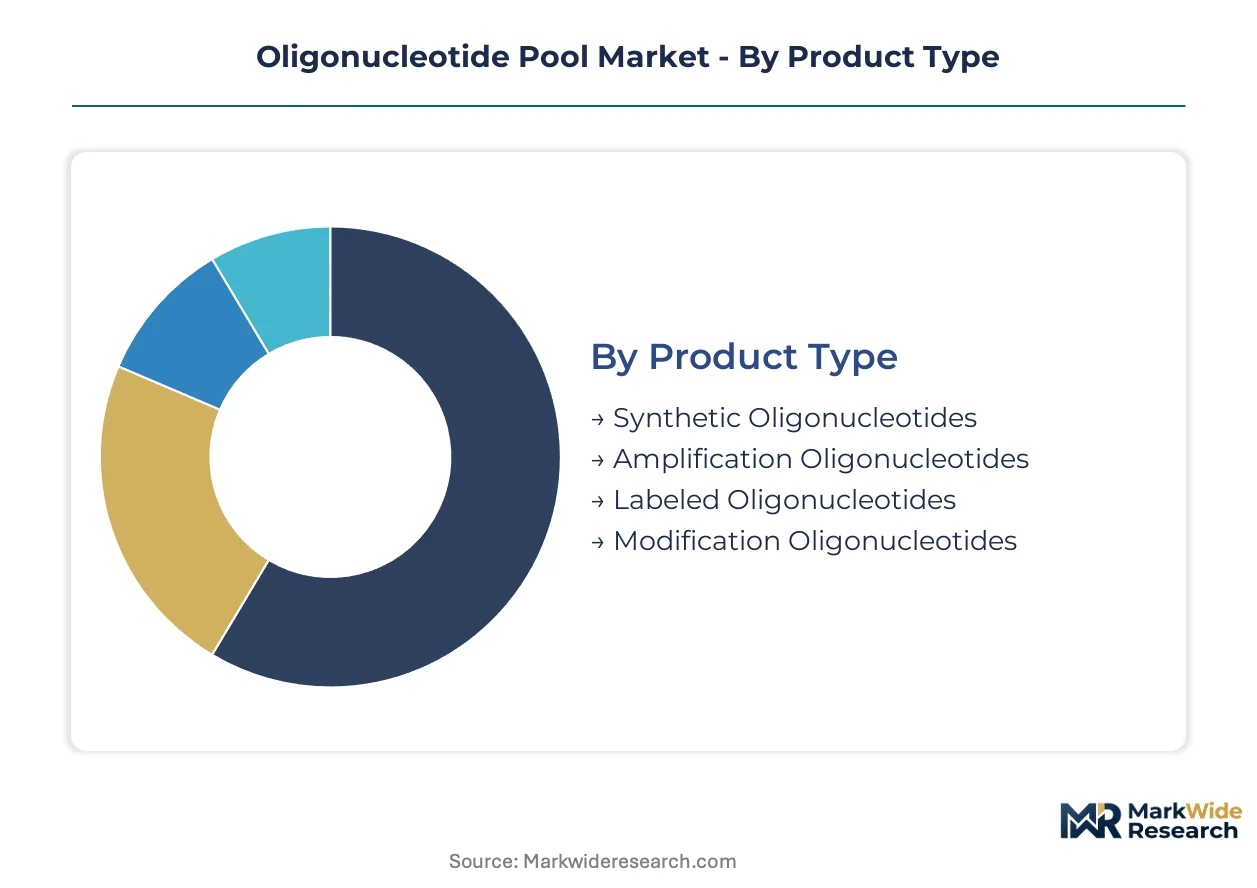
Oligonucleotide pool procurement patterns diverge sharply across product specifications, therapeutic applications, and synthesis technologies. Understanding these segment boundaries clarifies why certain manufacturers command premium positioning while others compete on throughput scale.
Product Type:
Technical specifications around sequence length, modification density, and purity grade determine manufacturing complexity and pricing tiers.
- Synthetic Oligonucleotides:Standard DNA and RNA sequences manufactured through phosphoramidite chemistry, typically 20-120 nucleotides with unmodified backbones. Pharmaceutical screening programs in the United States consume disproportionate volumes for primer sets and sequencing adapters where rapid turnaround outweighs customization needs.
- Amplification Oligonucleotides:Specialized pools designed for multiplex PCR and whole-genome amplification with optimized melting temperatures and minimal cross-reactivity. Diagnostic test manufacturers in Germany and Japan source these under ISO 13485 protocols for infectious disease panel production.
- Labeled Oligonucleotides:Fluorophore- or quencher-conjugated sequences for quantitative PCR and FISH applications.
- Modification Oligonucleotides:Backbone-modified variants including phosphorothioate linkages and 2'-O-methyl ribose for enhanced nuclease resistance.
Synthetic oligonucleotides lead on scale; modification oligonucleotides lead on momentum.
Application:
End-use requirements around regulatory scrutiny, batch documentation, and purity thresholds segment demand into distinct procurement channels.
- Genetic Engineering:CRISPR guide RNA pools and homology-directed repair templates for multiplexed genome editing. Boston and San Diego biotech clusters drive concentrated demand for complex libraries exceeding 10,000 unique sequences per pool.
- Therapeutic Development:cGMP-grade oligonucleotides for antisense, siRNA, and mRNA therapeutic candidates. FDA nucleic acid guidance documents and EMA Annex 2 revisions mandate residual solvent limits below 0.1% and comprehensive traceability documentation.
- Diagnostic Tests:PCR primers, hybridization probes, and sequencing adapters for clinical and research assays.
- Antisense Therapeutics:Sequence-specific oligonucleotides designed to modulate RNA processing through steric blocking or RNase H recruitment.
Diagnostic tests dominate current procurement volumes; therapeutic development commands the steepest expansion trajectory.
End User:
Customer scale and internal synthesis capabilities determine whether pools are sourced through spot purchases, annual contracts, or captive manufacturing.
- Pharmaceutical Companies:Large-scale buyers with centralized procurement functions negotiating multi-year supply agreements. Top-ten pharmaceutical firms now specify semiconductor-based synthesis platforms for high-throughput screening libraries.
- Biotechnology Firms:Mid-sized ventures lacking internal chemistry infrastructure and dependent on rapid-turnaround contract synthesis. These buyers prioritize modification flexibility and compressed lead times over per-sequence pricing.
- Academic Institutions:Fragmented demand across individual laboratories with limited volume consolidation.
- Contract Research Organizations:Service providers reselling oligo pools as components of integrated discovery and development offerings.
Pharmaceutical companies anchor procurement scale; biotechnology firms are gaining share fastest.
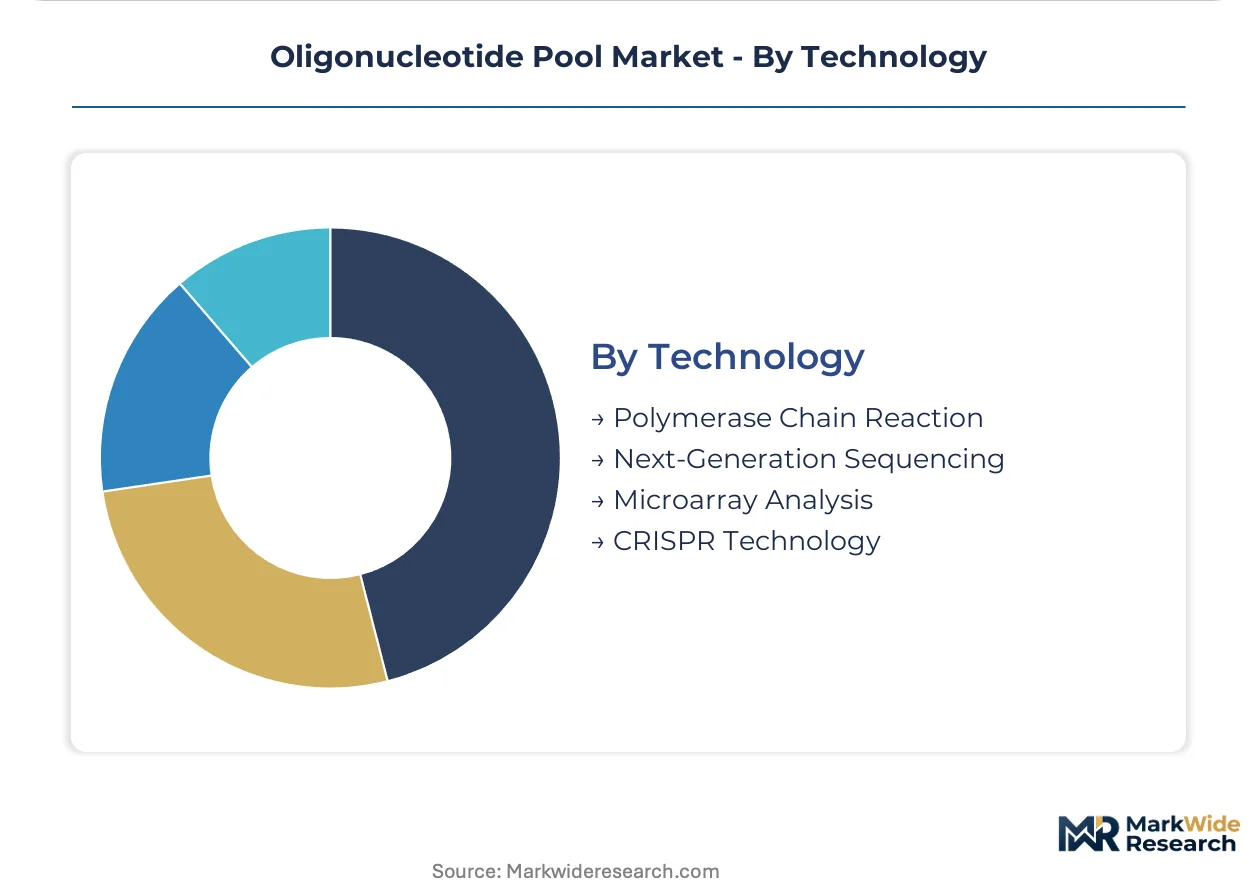
Technology:
Synthesis platform selection determines throughput ceilings, per-sequence economics, and compatibility with downstream enzymatic workflows.
- CRISPR Technology:Pooled guide RNA libraries for functional genomics screening and therapeutic candidate validation. Semiconductor-based manufacturing platforms now enable genome-wide libraries previously uneconomical with column chemistry.
- Next-Generation Sequencing:Adapter and barcode pools for library preparation and multiplexed sample tracking. Acoustic liquid handling automation is driving demand for pre-formatted, plate-ready adapter sets.
- Polymerase Chain Reaction:Traditional thermal cycling applications for amplification and detection.
- Microarray Analysis:Oligonucleotide probes immobilized on solid substrates for gene expression profiling and variant detection.
Polymerase chain reaction retains installed base dominance; CRISPR technology leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates therapeutic-grade oligonucleotide procurement, while Germany anchors European phosphoramidite precursor manufacturing. Japan and India are expanding synthesis capacity to reduce import dependence. China's domestic biotech sector is accelerating pooled guide RNA consumption for CRISPR applications.
United States
FDA nucleic acid guidance documents mandate residual solvent limits below 0.1% for therapeutic-grade pools. Boston and San Diego biotech clusters generate concentrated demand for high-complexity guide RNA libraries exceeding 10,000 sequences. Twist Bioscience's semiconductor-based platform in South San Francisco now supplies top-ten pharmaceutical firms with genome-wide CRISPR libraries.
Germany
EMA Annex 2 revisions on Good Manufacturing Practice tighten nucleic acid purity benchmarks for therapeutic developers. REACH chemical registration requirements now capture phosphoramidite monomers, forcing documentation of supply chain provenance. Merck KGaA operates synthesis facilities in Darmstadt serving European diagnostic and therapeutic markets with ISO 13485-certified pools.
India
The PLI scheme for biopharma extends production-linked incentives to oligonucleotide precursors, attracting contract manufacturing investment. CDSCO guidelines on nucleic acid therapeutics are aligning with international purity standards. Hyderabad and Bengaluru biotech corridors are establishing local synthesis capacity to serve domestic CRISPR screening programs and reduce import lead times.
Japan
PMDA consultations on nucleic acid drug master files are standardizing documentation requirements for imported therapeutic pools. METI funding for synthetic biology infrastructure supports domestic semiconductor-based synthesis platform development. The Kanto region around Tokyo concentrates demand from pharmaceutical firms expanding CRISPR-based target validation programs.
China
NMPA technical guidelines on gene editing reagents are formalizing quality benchmarks for CRISPR guide RNA pools. The Yangtze River Delta biotech corridor in Shanghai and Suzhou is scaling pooled oligonucleotide consumption for functional genomics. Domestic synthesis providers are upgrading phosphoramidite chemistry capabilities to serve therapeutic developers previously dependent on imports.
Oligonucleotide Pool Market Competitive Environment
Top-tier vendors anchor the premium-grade therapeutic segment, while mid-scale specialists compete on rapid-turnaround research reagents. The market structure stratifies across three capability tiers: semiconductor-based high-throughput platforms, phosphoramidite chemistry specialists with extended modification menus, and geographic coverage players optimizing logistics for time-sensitive CRISPR libraries. Dominant competitive moves include capacity expansion into cGMP-grade synthesis suites and strategic partnerships with cell and gene therapy developers requiring patient-specific barcodes.
Within the semiconductor synthesis archetype, Twist Bioscience occupies a position exemplifying silicon-based parallel manufacturing. Among phosphoramidite chemistry specialists, Integrated DNA Technologies and LGC Biosearch Technologies represent established providers with proprietary chemistries extending sequence length capabilities. Eurofins Scientific anchors the geographic coverage tier, operating synthesis facilities across multiple continents to reduce shipping times for time-sensitive libraries.
| Leading Market Players |
|---|
| Agilent Technologies |
| Twist Bioscience |
| Integrated DNA Technologies |
| GenScript |
| Creative Biogene |
| Eurofins Scientific |
| Merck KGaA |
| CustomArray |
| LGC Biosearch Technologies |
| Others |
Value Chain & Pricing Dynamics
Phosphoramidite monomer costs cascade through three distinct pricing tiers as specialized nucleotide building blocks move from German and Japanese chemical manufacturers to synthesis providers, then to therapeutic developers facing FDA-mandated purity thresholds. This input cost concentration creates asymmetric pricing power where certified cGMP-grade pool producers capture margin premiums while commodity synthesis faces relentless cost compression.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for research-grade oligonucleotide pools, pressuring legacy providers in the United States and Europe. Three-tier pricing structure across premium, standard, and economy levels separates cGMP-certified therapeutic-grade pools from ISO 13485 diagnostic reagents and basic research-grade sequences. Price differentiation rests on certification tier and modification complexity, with therapeutic developers showing least price sensitivity due to regulatory compliance requirements while academic laboratories face acute budget constraints.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and China's NMPA technical guidelines are reshaping sourcing patterns for CRISPR guide RNA libraries. Manufacturing concentrates in the United States, Germany, and China, with phosphoramidite precursors drawing from concentrated chemical production in Japan and Germany. Single-source vulnerability in specialized nucleotide monomers creates exposure to currency and energy price fluctuations. Distribution runs through direct procurement contracts for pharmaceutical buyers and purchasing cooperatives for mid-scale biotechnology firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Oligonucleotide Pool Market compounds steadily as CRISPR-based functional genomics entrenches across pharmaceutical discovery workflows, creating durable demand for high-complexity synthesis capabilities.
For Market Incumbents: Anchor defensive positioning through backward integration into phosphoramidite precursor manufacturing to blunt input cost volatility from German and Japanese chemical suppliers. Pursue multi-site cGMP qualification across three continents to preempt regional purchasing cooperatives from consolidating supply relationships with single-source providers. Semiconductor-based synthesis platforms represent the critical capability gap that column-chemistry incumbents must address to retain top-ten pharmaceutical contracts. For New Entrants and Emerging Players: Launch via automated NGS library prep partnerships with acoustic liquid handling platform manufacturers, embedding pre-pooled adapter sets into standardized workflows. Target India's Hyderabad and Bengaluru biotech corridors where domestic synthesis capacity lags accelerating CRISPR screening demand under PLI incentives. Cell and gene therapy manufacturing offers the most penetrable white space, with patient-specific oligo barcodes requiring specialized synthesis contracts outside established research reagent channels. For Investors and Strategic Acquirers: Consolidation pressure builds where sub-scale synthesis providers lack capital to finance FDA-mandated residual solvent elimination upgrades. The market supports long-term compounder returns as therapeutic nucleic acid pipelines deepen and regulatory barriers to uncertified entrants intensify. Acquisition targets should display ISO 13485 certification infrastructure with latent cGMP upgrade capacity. Monitor EMA Annex 2 implementation timelines as the inflection signal for therapeutic-grade pool demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| cGMP Manufacturing Scale-Up | EMA Annex 2 revisions force capital allocation toward certified synthesis suites. |
| Semiconductor Platform Integration | Silicon-based DNA synthesis compresses per-sequence costs for genome-wide CRISPR libraries. |
| Backward Integration into Precursors | In-house phosphoramidite production mitigates supply concentration risk from Japan and Germany. |
| Geographic Expansion via Joint Venture | Local synthesis capacity in India and China reduces customs-related release delays for therapeutic developers. |
| Regulatory Approval Pathway Investment | FDA nucleic acid guidance compliance opens therapeutic-grade procurement channels with deepest margins. |
Study Parameters
Direct dialogue with oligonucleotide synthesis chemists, pharmaceutical procurement directors, regulatory affairs leads at diagnostic manufacturers, and CRISPR platform engineers grounded the qualitative foundation. Secondary validation drew from FDA nucleic acid guidance documents, EMA GMP Annex 2 revisions, CDSCO technical circulars, and SEC filings of publicly traded synthesis providers. Bottom-up demand modeling across therapeutic development, diagnostic test, and research reagent channels triangulated against top-down market sizing from phosphoramidite precursor trade flows.
Segment-level projections across the analysis window incorporated product type specifications, application purity requirements, end-user procurement scale, and synthesis technology platform economics. The analytical framework modeled price elasticity differentials between cGMP therapeutic-grade and research-grade pools, with CAGRs derived from patent filing trajectories in nucleic acid therapeutics and capital expenditure disclosures from semiconductor synthesis platform operators.
Forecast precision tightens around the base case; tail outcomes carry wider variance under phosphoramidite supply disruption scenarios or accelerated EMA purity standard enforcement. The analytical envelope reflects assumptions around CRISPR screening platform adoption curves and regulatory harmonization timelines across FDA, EMA, and NMPA jurisdictions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Global Optical Genome Mapping Market
Genomics
RNA Transcriptome Profiling Test Market
Genomics
Global Genotyping Assay Market
Genomics
PCR and NGS Based Diagnostic Testing Market
Genomics
Antisense Oligonucleotides Market
Genomics
Genotyping Market
Genomics
Tumor-Sequencing Blood Testing Market
Genomics
Asia-Pacific Whole Exome Sequencing Market
Genomics
Next-Generation Sequencing (NGS) Workflow Quality Control Test Kits and Instruments Market
Genomics
Europe Hereditary Cancer Testing Market
Genomics
Middle East and Africa Genetic Testing Market
Genomics
Genetic Material Market
Genomics
Prenatal Genetic Testing Market
Genomics
DNA Microarray Market
Genomics
Cancer Biomarkers Market
Genomics
Global Long Read Sequencing Market