
 Gene Sequencing Market | 2026-2036
Gene Sequencing Market Size, Share, and Industry Trends Forecast 2026-2036
Gene Sequencing Market Analysis
China is tilting toward domestic sequencing instrument manufacturing as a strategic priority. Illumina sustains its installed base advantage through proprietary flow cell chemistry and locked-in reagent contracts. Thermo Fisher Scientific leverages vertical integration from sample prep through cloud analytics to capture full workflow value. BGI dominates in population-scale genomics through state-backed sequencing infrastructure and sovereign data mandates.
Gene sequencing determines the order of nucleotides in DNA or RNA using fluorescent detection, semiconductor sensing, or nanopore current measurement, with read lengths spanning from short 50-base-pair fragments to continuous million-base-pair strands for de novo assembly and structural variant calling. Reagents and consumables anchor recurring revenue streams as instruments require proprietary chemistry cycles with locked validation protocols. NGS platforms lead in throughput and cost per base, while nanopore technology extends into field-deployable and real-time applications where rapid turnaround outweighs raw accuracy.
FDA regulates sequencing-based diagnostic devices through premarket authorization pathways that demand analytical and clinical validation, while EMA's In Vitro Diagnostic Regulation tightens conformity assessment for EU market access. China's NMPA accelerates review timelines for domestically manufactured sequencers under innovation channel programs. Stakeholders must monitor how sovereign data localization laws and evolving reimbursement codes for whole-genome testing reshape deployment economics and geographic prioritization.
Market Dynamics
Pharmaceutical pipelines are compressing discovery timelines through integrated sequencing workflows, forcing instrument vendors to embed bioinformatics and cloud analytics directly into platform architecture rather than treating software as an aftermarket add-on.
Growth Catalysts
- FDA Companion Diagnostic Framework:Tightened premarket authorization pathways for sequencing-based diagnostics are pulling validated platforms into oncology drug development partnerships.
- Population Genomics Mandates:Sovereign data programs in China are driving instrument placement at state-backed biobanks and national health registries.
- Cloud-Native Bioinformatics:Academic medical centers are shifting compute-heavy variant calling from on-premise servers to AWS and Azure infrastructure, reducing total cost of ownership for high-throughput labs.
Market Restraints
- Flow Cell Supply Concentration:Proprietary reagent chemistry locks users into single-source consumable contracts, creating vulnerability when manufacturing disruptions occur at primary suppliers.
- Fluorescent Dye Cost Volatility:Specialty dye synthesis depends on concentrated chemical feedstock suppliers, exposing consumable margins to input price swings.
- Short-Read Structural Blind Spots:Illumina-style short-read platforms struggle with repetitive genomic regions and complex structural variants, limiting diagnostic yield in certain hereditary disease applications.
Strategic Opportunities
- Point-of-Care Deployment:Nanopore sequencers are penetrating rural health networks in India where cold-chain logistics for sample transport to centralized labs remain unreliable.
- AI-Accelerated Variant Interpretation:Machine learning models trained on ClinVar and gnomAD databases are compressing reporting timelines from weeks to days in clinical diagnostic settings.
- Pharmacogenomics Reimbursement Expansion:CMS coverage determinations for preemptive pharmacogenomic testing are opening reimbursement pathways for community hospital laboratories.
Industry Challenges
- Bioinformatics Talent Scarcity:Variant interpretation and pipeline development require hybrid computational-biological expertise that outpaces graduate program output.
- Multi-Omic Data Integration Complexity:Combining genomic, transcriptomic, and proteomic datasets demands standardized APIs that remain fragmented across vendor platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gene Sequencing Market |
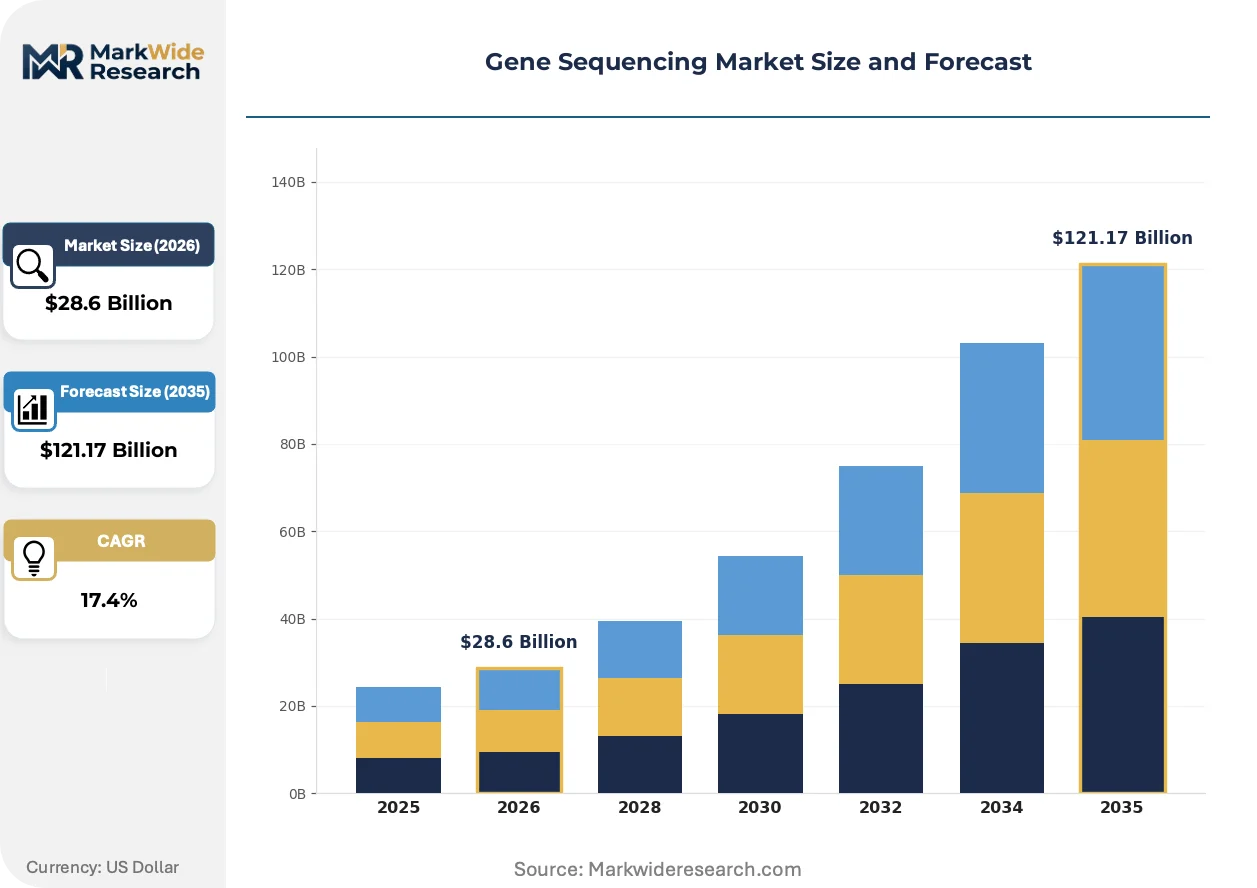
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $121.17 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Services End User: Academic Research, Clinical Laboratories, Pharmaceutical Companies, Hospitals Technology: NGS, Sanger Sequencing, PCR, Microarray Application: Infectious Disease, Oncology, Genetic Disorders, Personalized Medicine |
| Companies Covered | Illumina, Thermo Fisher Scientific, F. Hoffmann-La Roche, QIAGEN, Pacific Biosciences, Oxford Nanopore Technologies, BGI, PerkinElmer, Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gene Sequencing Market Emerging Trajectories
Sequencing workflows are fragmenting into modular, best-of-breed components as buyers resist full-stack vendor lock-in, while regulatory pressure accelerates validation standards for clinical-grade outputs.
Long-read sequencing platforms from Pacific Biosciences and Oxford Nanopore are virtualizing the de novo assembly market by enabling telomere-to-telomere chromosome reconstruction without reference genomes. Agricultural biotechnology firms are adopting these systems for complex crop genome characterization at scale. This capability is compressing breeding cycle timelines and displacing short-read scaffolding approaches in plant science applications.
EMA's In Vitro Diagnostic Regulation is tightening conformity assessment requirements for sequencing-based devices entering EU markets. Manufacturers must now submit analytical and clinical validation dossiers to notified bodies under expanded technical documentation rules. Medium-sized diagnostic firms are responding by delaying EU commercialization timelines or pursuing UKCA certification for Great Britain access first.
Hospital procurement committees are unbundling instrument purchases from multi-year reagent commitments, forcing vendors to compete on per-run economics rather than total contract value. Integrated delivery networks in Texas and California are piloting competitive bidding for consumables across their sequencing footprints. This behavioral shift is most visible in United States academic medical centers where centralized procurement offices have gained influence over individual principal investigator purchasing authority.
Gene Sequencing Market Segmentation
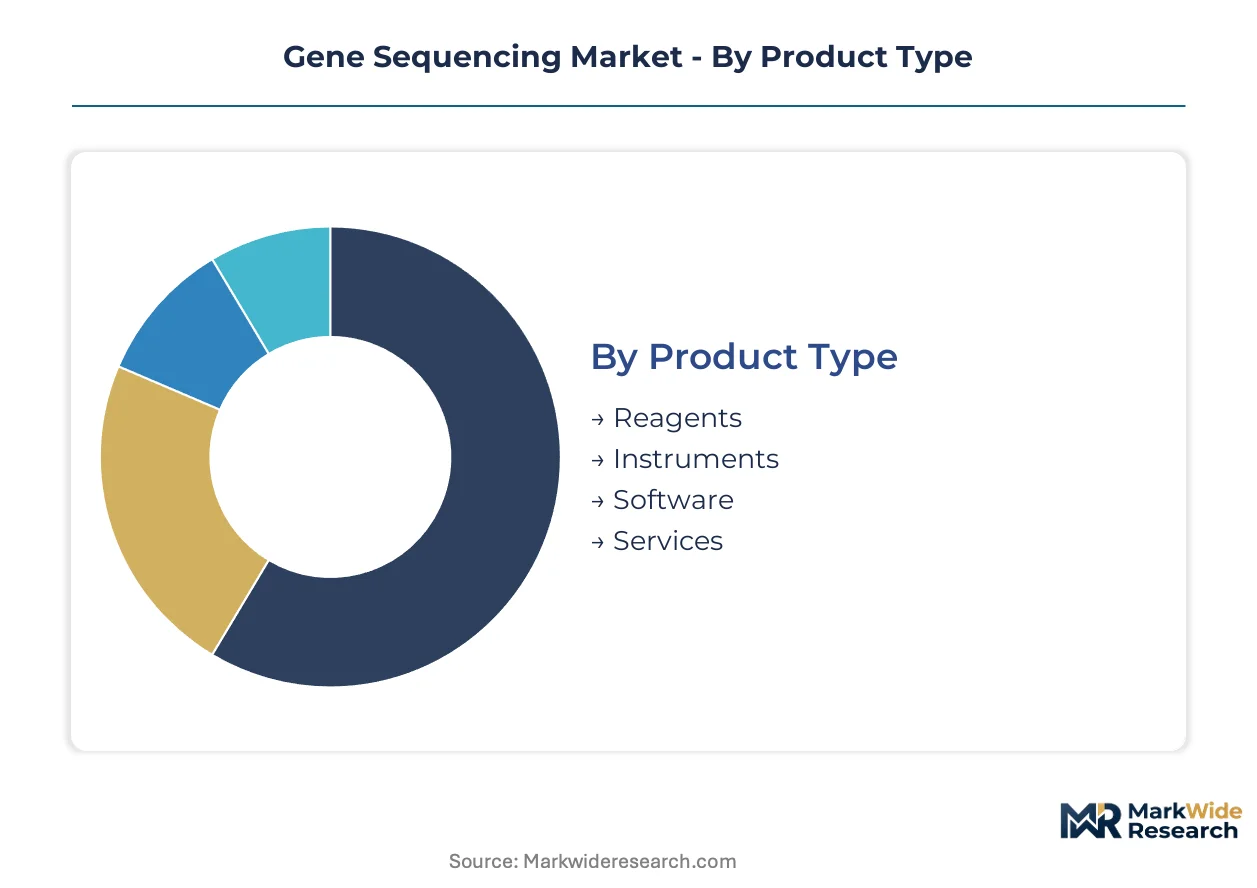
Segmentation reveals how gene sequencing revenue pools fragment across hardware, consumables, and analytical layers. Each category carries distinct margin profiles, regulatory exposure, and customer concentration patterns that shape vendor strategy.
Product Type:
Use-case spectrum spans single-run reagent purchases through multi-year enterprise software licenses, with recurring consumable revenue anchoring platform economics.
- Reagents:Proprietary flow cell chemistries and library preparation kits lock users into validated protocol cycles. Academic medical centers in the United States drive pull-through volume as sequencing depth requirements expand for research consortia.
- Instruments:Capital equipment spans benchtop units for clinical diagnostics to production-scale systems for national biobanks. China's state-backed genomics infrastructure is accelerating placement timelines for high-throughput platforms under sovereign data mandates.
- Software:Cloud-native variant calling and pipeline management tools compress bioinformatics bottlenecks. AWS and Azure deployments are displacing on-premise server farms at mid-sized clinical laboratories.
- Services:Contract sequencing and bioinformatics outsourcing address talent scarcity in hybrid computational-biology roles. Pharmaceutical companies leverage external capacity to compress drug discovery timelines without fixed asset commitments.
The dominant share belongs to Reagents, while Software is closing the gap fastest.
End User:
Customer maturity varies from exploratory research budgets through regulated diagnostic reimbursement pathways.
- Academic Research:University consortia and medical schools deploy sequencing for discovery genomics and population-scale cohort studies. Grant-funded principal investigators prioritize per-run cost over total cost of ownership.
- Clinical Laboratories:CAP-accredited and CLIA-certified facilities process patient samples for hereditary disease testing and oncology profiling. FDA premarket authorization requirements for sequencing-based diagnostics tighten validation standards.
- Pharmaceutical Companies:Integrated sequencing workflows compress target identification through patient stratification timelines. Companion diagnostic partnerships with platform vendors lock in preferred supplier status.
- Hospitals:Community and academic medical centers are expanding in-house molecular pathology capabilities. CMS reimbursement determinations for pharmacogenomic testing are opening budget lines for preemptive genotyping programs.
Pharmaceutical Companies command the largest absolute spend, though Hospitals are expanding capacity most aggressively.
Technology:
Performance trade-offs between throughput, accuracy, and read length segment deployment by application requirements.
- NGS:Massively parallel short-read platforms dominate clinical and research throughput economics. Illumina's installed base sustains reagent lock-in through proprietary flow cell validation protocols.
- Sanger Sequencing:Gold-standard accuracy for targeted variant confirmation and forensic applications. Reference laboratories retain capacity for regulatory submissions requiring orthogonal validation.
- PCR:Amplicon-based targeted sequencing for hotspot mutation panels in oncology diagnostics. Community hospital laboratories favor workflow simplicity over comprehensive genomic profiling.
- Microarray:Genotyping arrays for copy number variation and SNP detection at scale. Agricultural biotechnology firms apply these for marker-assisted breeding in complex crop genomes.
NGS holds the dominant installed base, with long-read alternatives gaining traction in de novo assembly applications.
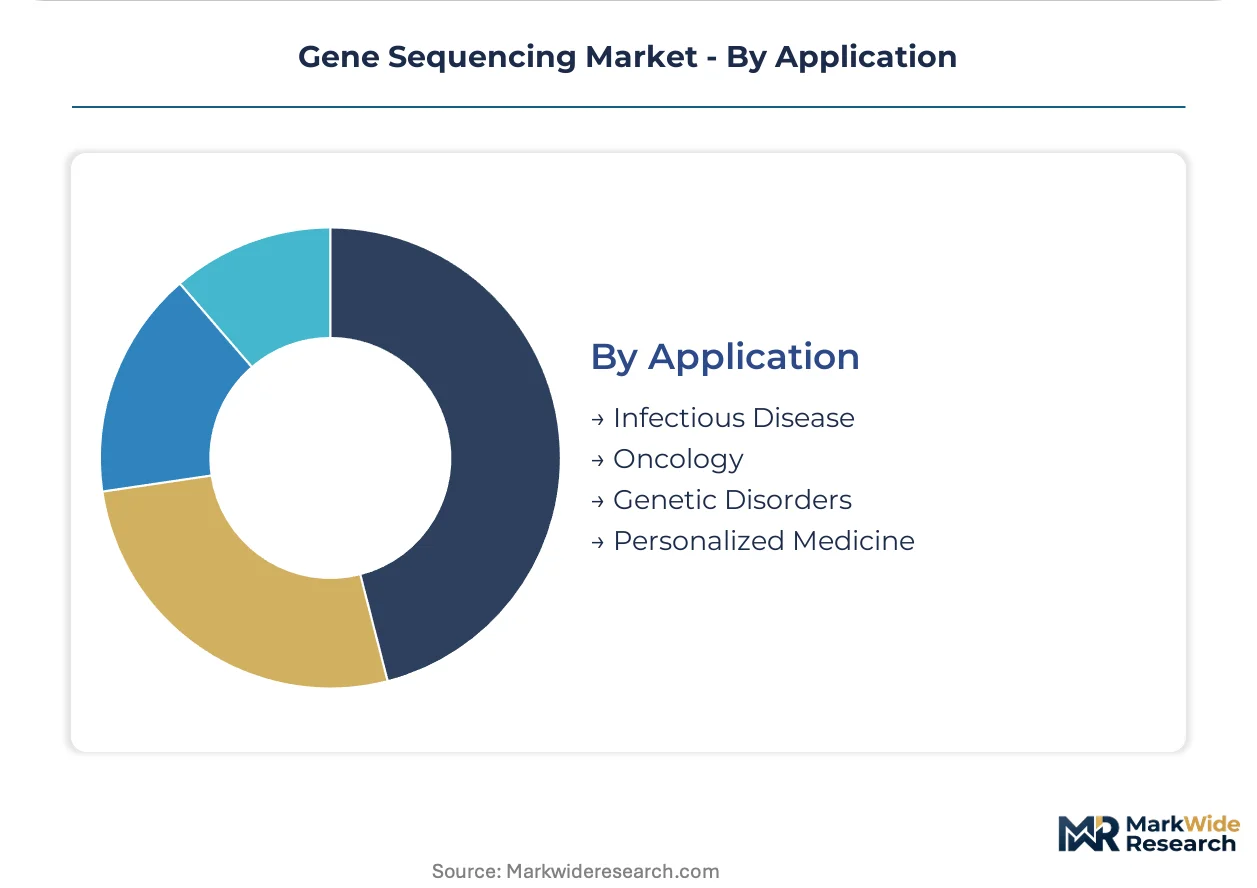
Application:
Disease area priorities reflect regulatory pathway maturity and reimbursement code availability.
- Infectious Disease:Pathogen genome sequencing for outbreak surveillance and antimicrobial resistance profiling. Nanopore platforms enable field-deployable surveillance where cold-chain logistics fail.
- Oncology:Tumor-normal paired sequencing for somatic mutation calling and therapy selection. FDA companion diagnostic frameworks pull validated platforms into drug development partnerships.
- Genetic Disorders:Exome and genome sequencing for rare disease diagnosis in pediatric and prenatal settings. Short-read structural blind spots limit diagnostic yield in repetitive genomic regions.
- Personalized Medicine:Pharmacogenomic testing for drug metabolism and adverse event prediction. CMS coverage determinations are expanding reimbursement for preemptive genotyping in community settings.
Oncology generates the highest revenue concentration, while Infectious Disease is scaling fastest through public health infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The San Diego-Torrey Pines corridor anchors North American sequencing infrastructure through dense fiber connectivity to cloud compute clusters. This biotech cluster concentrates instrument R&D and companion diagnostic validation capacity.
United States
FDA premarket authorization pathways pull validated platforms into oncology drug development partnerships at academic medical centers. CMS reimbursement determinations for pharmacogenomic testing open budget lines for community hospital laboratories. The Boston-Cambridge cluster compresses discovery timelines through integrated sequencing workflows and cloud-native bioinformatics.
China
NMPA innovation channel programs accelerate review timelines for domestically manufactured sequencers. Sovereign data mandates drive instrument placement at state-backed biobanks and national health registries. Shenzhen and Beijing house production-scale sequencing infrastructure under population genomics programs.
Germany
EMA In Vitro Diagnostic Regulation tightens conformity assessment for sequencing-based devices entering EU markets. REACH compliance requirements shape reagent chemistry sourcing decisions for diagnostic manufacturers. The Munich biotech cluster hosts reference laboratories retaining Sanger capacity for regulatory submissions.
United Kingdom
UKCA certification pathways attract manufacturers delaying EU commercialization timelines under expanded EMA technical documentation rules. Genomics England infrastructure sustains population-scale cohort sequencing demand. The Cambridge-Oxford corridor concentrates nanopore technology development for field-deployable applications.
India
CDSCO regulatory frameworks govern diagnostic device market access for sequencing-based tests. Cold-chain logistics failures in rural health networks drive point-of-care nanopore deployment. Hyderabad and Bengaluru clusters address bioinformatics talent scarcity through contract sequencing and pipeline outsourcing services.
Gene Sequencing Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in reagent and flow cell chemistry. The vendor base stratifies between locked-in consumable economics and modular best-of-breed resistance. Three archetypes dominate: full-stack instrument-reagent bundlers, long-read technology disruptors, and cloud-native bioinformatics layer specialists. Competitive moves concentrate on multi-year reagent contract unbundling and AI-accelerated variant interpretation partnerships.
Among platform integrators, Illumina and Thermo Fisher Scientific exemplify the locked-ecosystem archetype through proprietary flow cell validation protocols and vertical workflow integration. Oxford Nanopore Technologies occupies the field-deployable disruption tier, representing long-read alternatives gaining traction where rapid turnaround outweighs raw accuracy. BGI anchors the state-backed scale tier, sitting within sovereign data infrastructure mandates and population genomics deployment timelines.
| Leading Market Players |
|---|
| Illumina |
| Thermo Fisher Scientific |
| F. Hoffmann-La Roche |
| QIAGEN |
| Pacific Biosciences |
| Oxford Nanopore Technologies |
| BGI |
| PerkinElmer |
| Agilent Technologies |
| Others |
Supply Flow & Price Mechanics
Shenzhen's concentrated flow cell manufacturing capacity grants incumbent vendors substantial pricing power over reagent-dependent laboratories locked into proprietary chemistry validation cycles. This geographic concentration of consumable production creates asymmetric leverage where supply disruptions translate immediately into per-run cost volatility for buyers lacking alternative sourcing pathways.
Pricing Analysis
Volume-discount tiering structures stratify across enterprise multi-year commitments, mid-scale academic consortia, and spot purchasing for exploratory research. Pricing differentiation rests on sequencing throughput guarantees and FDA premarket authorization tiering for diagnostic-grade platforms. Cost compression in the spot-purchasing tier is intensifying as procurement committees unbundle reagent contracts from instrument placements. Academic medical centers exhibit highest price sensitivity due to grant-funded budget constraints, while pharmaceutical companion diagnostic partnerships demonstrate lowest sensitivity given pipeline timeline imperatives.
Supply Chain Analysis
Contract manufacturing concentration at Foxconn and Jabil Electronics anchors instrument assembly capacity, with specialty flow cell fabrication tethered to concentrated chemical synthesis operations in Germany and Japan. Raw material dependencies center on high-purity silicon substrates, fluorescent dye precursors, and semiconductor-grade reagents. Single-source vulnerability in proprietary flow cell chemistry creates exposure when primary suppliers face manufacturing disruptions. Distribution runs through direct vendor sales organizations for enterprise accounts and specialized life science distributors for mid-tier clinical laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene sequencing platform economics increasingly favor recurring revenue attachment over hardware margins, with cloud-native bioinformatics services and AI-accelerated variant interpretation layers expanding faster than instrument placements.
For Market Incumbents: Insulate consumable revenue streams through deeper backward integration into fluorescent dye synthesis and expanded captive production of flow cell substrates. Lock-in validation protocols at academic medical centers create switching costs that emerging long-read disruptors struggle to overcome. Priority defensive investment centers on embedding AI variant interpretation directly into platform architecture rather than treating analytics as detachable aftermarket modules. For New Entrants and Emerging Players: Establish a beachhead in point-of-care infectious disease surveillance where nanopore field-deployability outweighs raw accuracy specifications. Rural health networks in India and Southeast Asia present penetrable white space given cold-chain logistics failures that disadvantage centralized laboratory models. Go-to-market positioning should emphasize rapid turnaround guarantees and minimal infrastructure requirements rather than throughput benchmarking against incumbent short-read platforms. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cloud-native bioinformatics layer specialists over hardware-dependent instrument vendors given margin compression in capital equipment. Long-term viability across the projection horizon rests on recurring revenue attachment rates and sovereign data infrastructure partnerships rather than installed base scale alone. Watch for inflection signals in CMS reimbursement determinations for preemptive pharmacogenomic testing as indicator of clinical market expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Accelerated Variant Interpretation Partnership | Machine learning deployment at Mayo Clinic and Mass General compresses diagnostic reporting timelines from weeks to days. |
| Companion Diagnostic Regulatory Submission | FDA premarket authorization pathways for oncology platforms lock in preferred supplier status with pharmaceutical development pipelines. |
| Cloud-Native Bioinformatics Platform Launch | AWS and Azure infrastructure deployments displace on-premise server farms at mid-sized clinical laboratories seeking reduced total cost of ownership. |
| Backward Integration into Reagent Chemistry | In-house production of fluorescent dyes and flow cell substrates insulates margins from specialty chemical feedstock price volatility. |
| Point-of-Care Field Deployment Expansion | Nanopore sequencer placement in rural Indian health networks addresses sample transport failures where cold-chain logistics remain unreliable. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA premarket authorization databases, EMA In Vitro Diagnostic Regulation guidance documents, and NMPA innovation channel filings. Primary interviews engaged platform engineering directors at instrument manufacturers, chief scientific officers at pharmaceutical sequencing facilities, procurement managers at academic medical centers, and regulatory affairs leads at diagnostic laboratories. Secondary validation drew from SEC 10-K instrument revenue disclosures, CMS reimbursement determination records, and sovereign genomics program procurement announcements. Bottom-up segmentation modeling triangulated against top-down market sizing from trade flow analysis.
Forecast inputs incorporate instrument placement trajectories, consumable pull-through coefficients, and software attachment rate assumptions across the projection horizon. Segmentation dimensions span product type, end user archetype, technology platform, and application area with geographic regulatory cluster overlays. CAGRs derive from logistic diffusion modeling of platform adoption curves calibrated to historical sequencing cost reduction trajectories. Industry-specific inputs include companion diagnostic partnership formation rates and population genomics program budget authorization cycles.
Macroeconomic conditions sit as an overlay; deviation in NIH grant funding levels, pharmaceutical R&D budget allocations, or sovereign healthcare infrastructure investment would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway stability and reimbursement code expansion timelines. Quarterly review of FDA premarket authorization queue depth and CMS national coverage determination announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Whole Genome Amplification Market
Genomics
Global Whole Genome Sequencing (WGS) Market
Genomics
North America Whole Exome Sequencing Market
Genomics
NGS-Based RNA-Sequencing Market
Genomics
Genomics Personalized Health Market
Genomics
Glycan Sequencing Market
Genomics
Genetic Analysis Services Market
Genomics
Animal Genetics Market
Genomics
DNA Sequencing Services Market
Genomics
Antisense Oligonucleotides Market
Genomics
Next-Generation Sequencing Library Preparation Market
Genomics
Global Single-Cell Genome Sequencing Market
Genomics
Europe Genetic Testing Market
Genomics
Europe Gene Synthesis (Research Use) Market
Genomics
Predisposition Biomarkers Market
Genomics
Spatial Genomics and Transcriptomics Market