
 North America Genetic Testing Market | 2026-2036
North America Genetic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Genetic Testing Market Outlook
Buyer concentration among hospital networks and integrated delivery systems is expanding as health systems bring molecular diagnostics in-house rather than outsourcing to reference laboratories. Quest Diagnostics leverages its national logistics infrastructure to sustain reference lab dominance across outpatient settings. Laboratory Corporation of America Holdings anchors its position through extensive payer contracts and specialized oncology testing menus. Illumina competes at the platform layer, controlling sequencing instrument placements that determine downstream test volumes.
North America genetic testing encompasses molecular assays that analyze DNA, RNA, chromosomes, or proteins to detect inherited disorders, somatic mutations, or pharmacogenomic variations, typically requiring CLIA-certified laboratory environments with analytical sensitivity thresholds measured in variant allele frequency. Its primary commercial purpose centers on informing clinical treatment decisions, reproductive planning, and therapeutic selection across oncology and cardiology. Disease risk tests and pharmacogenomic testing occupy distinct margin pools, with the former commanding premium pricing through specialist channel access while the latter scales through retail pharmacy partnerships. Sequencing technology leads instrument placement value, though PCR sustains higher test throughput in infectious disease and carrier screening applications.
The FDA oversees in vitro diagnostic and direct-to-consumer test approvals, while CLIA regulates laboratory quality standards and state-level licensure creates patchwork compliance requirements across California, New York, and other jurisdictions with stringent personnel and proficiency rules. The Centers for Medicare and Medicaid Services shapes reimbursement codes that determine commercial viability for emerging test categories. Stakeholders must monitor how the FDA's phased LDT oversight framework alters market access timelines and whether Canadian provincial health technology assessments accelerate or constrain adoption of whole-genome sequencing in neonatal intensive care.
Market Dynamics
Hospital systems across the United States and Canada are accelerating in-house molecular diagnostics programs, compressing reference laboratory volumes and forcing CLIA-certified laboratories to defend specimen access through specialized oncology and pharmacogenomic menus.
Growth Catalysts
- Expanded newborn screening mandates:Canadian provincial health authorities are widening heel-prick screening panels to include spinal muscular atrophy and severe combined immunodeficiency, creating sustained demand for high-throughput sequencing infrastructure.
- Pharmacogenomic reimbursement codes:The Centers for Medicare and Medicaid Services established Category 1 CPT codes for preemptive PGx testing, enabling commercial viability for retail pharmacy distribution models.
- Liquid biopsy adoption in oncology:Community oncology practices are integrating circulating tumor DNA assays into routine surveillance protocols, displacing tissue-based re-biopsy requirements for resistance monitoring.
Market Restraints
- Reagent supply concentration:Polymerase and nucleotide supply chains concentrate among three global enzyme manufacturers, exposing testing laboratories to allocation rationing during demand surges.
- Variant interpretation bottleneck:The American College of Medical Genetics and Genomics classification framework creates reporting delays for variants of uncertain significance, constraining test turnaround times.
- State licensure fragmentation:New York State's permit requirements for out-of-state laboratories create compliance friction that limits test menu standardization across multi-site health systems.
Strategic Opportunities
- Direct-to-consumer regulatory clarity:The FDA's final rule on 23andMe-style carrier screening kits opens pathway for pharmacy-channel distribution of expanded carrier panels without physician intermediaries.
- Whole-genome sequencing in NICUs:Provincial health technology assessments in Ontario and British Columbia are evaluating rapid WGS for critically ill neonates, creating pilot-to-scale transition opportunities.
- AI-assisted variant classification:Machine learning tools trained on ClinVar databases are converging with cloud-based interpretation platforms to reduce genetic counselor labor intensity per case.
Industry Challenges
- Bioinformatics workforce scarcity:CLIA-compliant variant analysis requires dual-trained personnel in computational biology and clinical genetics, with accredited training programs producing insufficient pipeline volume.
- Electronic health record integration:Structured genomic data insertion into Epic and Cerner workflows requires custom interface development that delays test result availability at point-of-care.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Genetic Testing Market |
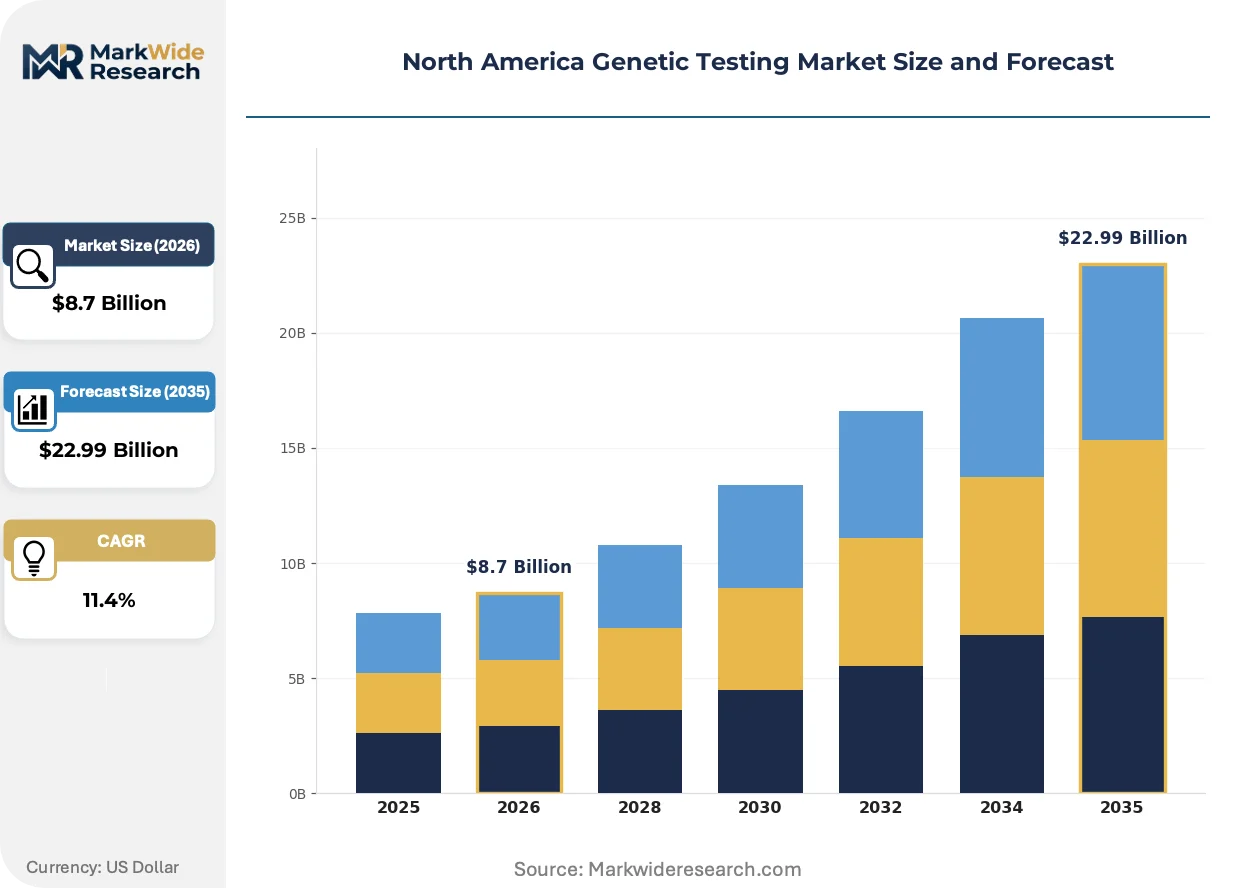
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disease Risk Tests, Carrier Testing, Newborn Screening, Pharmacogenomic Testing End User: Hospitals, Laboratories, Research Institutions, Direct-to-Consumer Technology: Microarray, Sequencing, PCR, Genotyping Application: Oncology, Cardiology, Neurology, Prenatal |
| Companies Covered | Quest Diagnostics, Laboratory Corporation of America Holdings, Invitae Corporation, Illumina, Thermo Fisher Scientific, Myriad Genetics, Bio-Rad Laboratories, PerkinElmer, Natera, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Genetic Testing Market Strategic Shifts
Next-generation sequencing platforms are compressing per-sample costs while expanding into point-of-care formats, fundamentally altering where and how genetic information enters clinical workflows across ambulatory and acute settings.
Long-read sequencing is overtaking short-read platforms for structural variant detection in constitutional disorders. Pediatric genetics departments at academic medical centers are adopting Pacific Biosciences and Oxford Nanopore instruments for neurodevelopmental and rare disease workups. The technology is overtaking microarray-based copy number analysis by resolving complex rearrangements in a single assay, collapsing multi-modal testing algorithms into unified workflows.
The FDA's phased oversight framework for laboratory-developed tests is reshaping compliance investment priorities. High-complexity molecular laboratories must now assemble premarket submission packages or pursue third-party review pathways previously reserved for IVD manufacturers. Oncology companion diagnostic developers are most affected, with several sponsors pivoting toward dual-track FDA submissions to preserve Medicare coverage under the NCD for next-generation sequencing.
Health system procurement teams are consolidating genetic testing contracts under centralized laboratory stewardship programs. Multi-hospital networks in Texas and California are replacing fragmented send-out arrangements with exclusive reference laboratory partnerships that include data sharing and quality benchmarking. This concentration is most visible in oncology, where integrated delivery systems negotiate population-based pricing for somatic profiling across their entire patient cohorts.
North America Genetic Testing Market Segmentation
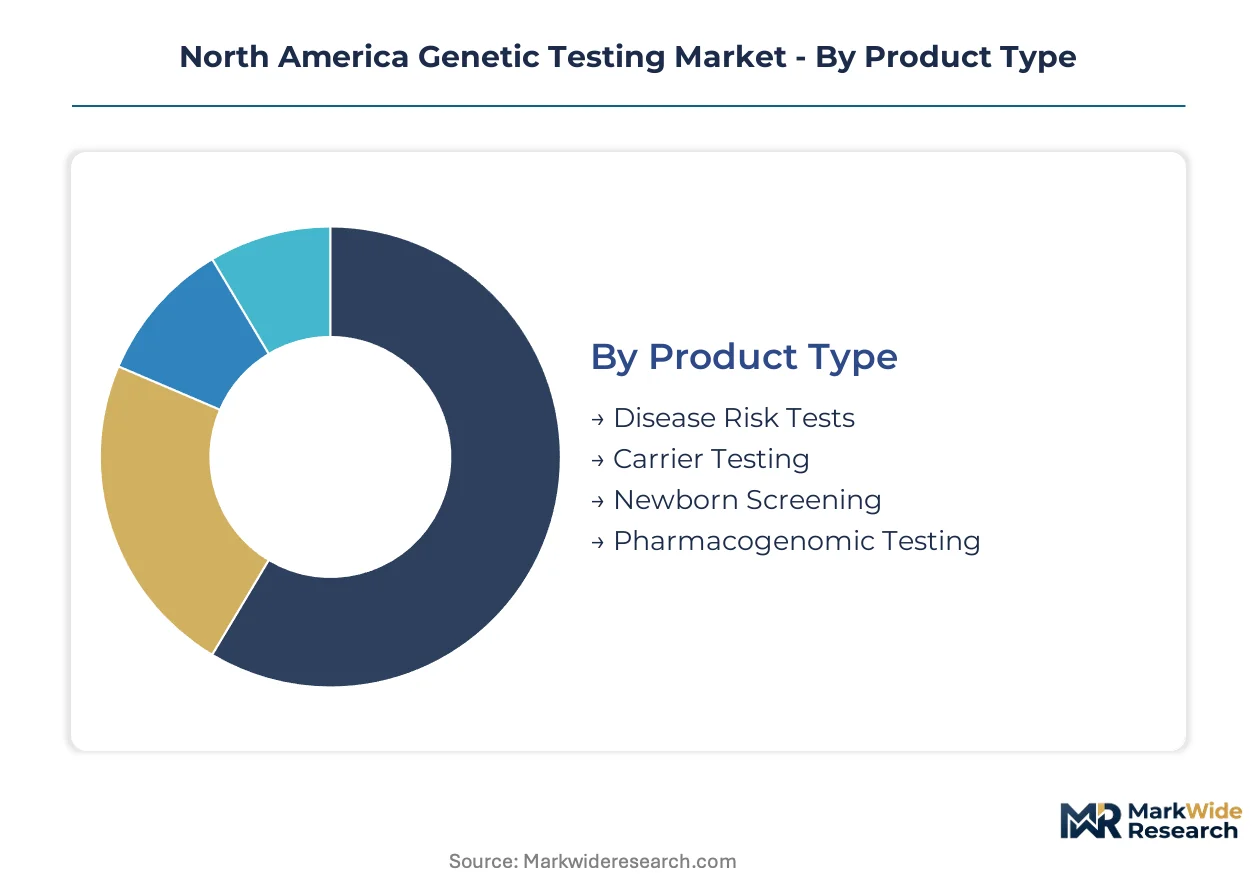
Genetic testing segmentation in North America reflects divergent reimbursement pathways and technology substitution cycles. Product categories split between high-margin clinical decision-support assays and volume-scaled screening panels. Technology choices determine laboratory capital deployment and staffing models across health system tiers.
Product Type:
Upgrade cycles in molecular diagnostics follow reimbursement code establishment rather than raw technology obsolescence, with laboratories deferring platform investments until CMS coverage determinations stabilize.
- Disease Risk Tests:Polygenic risk score assays aggregate thousands of common variants to quantify susceptibility for conditions including type 2 diabetes and coronary artery disease. Demand concentrates in concierge medicine practices and employer wellness programs seeking differentiated preventive offerings, constrained by limited insurance coverage for asymptomatic screening.
- Pharmacogenomic Testing:Single-nucleotide variant panels guide warfarin dosing, clopidogrel selection, and psychiatric medication titration. CVS Health and Walgreens Boots Alliance are scaling preemptive PGx programs through retail pharmacy clinics, enabled by Category 1 CPT codes that secure Medicare reimbursement.
- Carrier Testing:Expanded panels screen for cystic fibrosis, spinal muscular atrophy, and Ashkenazi Jewish disorders in preconception counseling.
- Newborn Screening:State-mandated heel-prick panels detect inborn errors of metabolism, with Canadian provinces adding sequencing-based conditions to traditional biochemical assays.
Disease Risk Tests sits at the top of the volume ranking, with Pharmacogenomic Testing climbing the fastest.
End User:
Customer-type concentration is shifting as health systems internalize testing capacity that reference laboratories previously captured, compressing margins for outsourced specimen processing.
- Hospitals:Academic medical centers and community hospital networks operate CLIA-certified molecular laboratories for STAT oncology profiling and neonatal diagnostics. Texas Medical Center and Mayo Clinic anchor in-house sequencing programs that displace send-out volumes for hereditary cancer panels.
- Laboratories:Reference laboratories including Quest Diagnostics and LabCorp maintain dominance in outpatient settings through national logistics networks and payer contracting scale.
- Research Institutions:Universities and contract research organizations deploy sequencing for drug target discovery and biomarker validation.
- Direct-to-Consumer:23andMe and AncestryDNA distribute ancestry and carrier screening kits through e-commerce and pharmacy retail, operating under FDA enforcement discretion for low-risk devices.
Hospitals capture the largest revenue share among end users, with Direct-to-Consumer expanding most quickly.
Technology:
Technology selection tracks application-specific requirements for sensitivity, throughput, and variant resolution, with instrument placement decisions locking laboratories into multi-year reagent supply commitments.
- Sequencing:Next-generation sequencing platforms from Illumina dominate oncology somatic profiling and constitutional disorder diagnosis. Pacific Biosciences and Oxford Nanopore systems are penetrating pediatric genetics for structural variant resolution.
- PCR:Quantitative real-time PCR sustains highest test throughput for infectious disease, carrier screening, and pharmacogenomic single-site assays.
- Microarray:Chromosomal microarray analysis remains standard for developmental delay evaluation and prenatal copy number assessment.
- Genotyping:Targeted SNP arrays support ancestry inference and polygenic risk calculation at lowest per-sample cost.
Sequencing commands the highest instrument placement value, with PCR maintaining the steepest expansion trajectory in infectious disease applications.
Application:
Application prioritization follows oncology therapeutic pipeline density and cardiology guideline integration, with neurology and prenatal segments advancing on diagnostic yield improvements.
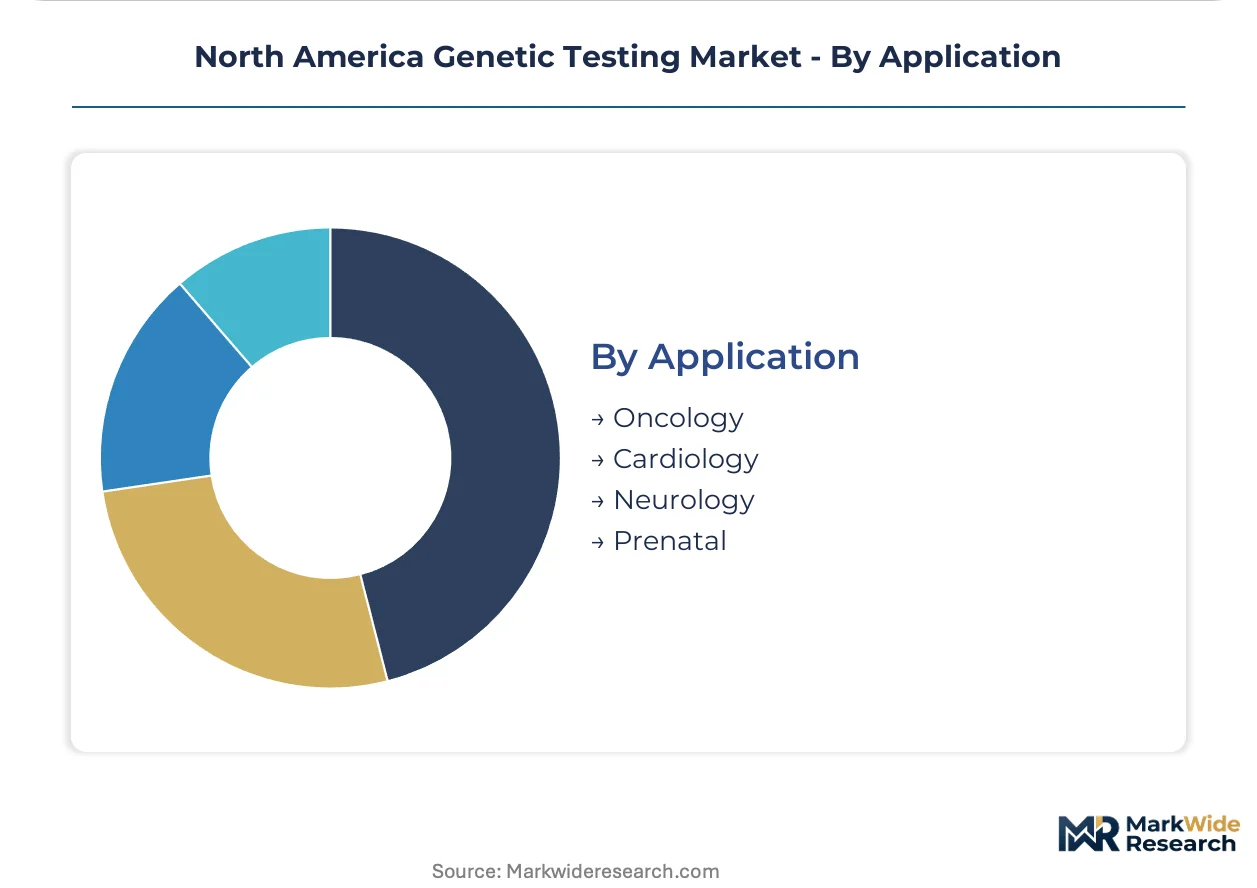
- Oncology:Somatic mutation profiling for therapy selection and minimal residual disease monitoring anchors commercial value. Liquid biopsy adoption is displacing tissue re-biopsy for resistance surveillance in lung and colorectal malignancies.
- Prenatal:Non-invasive prenatal testing for fetal aneuploidy has achieved standard-of-care status, with expanded panels adding microdeletion screening.
- Cardiology:Hereditary cardiomyopathy and arrhythmia panels guide implantable defibrillator decisions and family cascade screening.
- Neurology:Epilepsy and neurodevelopmental disorder gene panels resolve diagnostic odysseys for pediatric patients with complex phenotypes.
Oncology generates the highest absolute revenue, with Prenatal gaining share fastest as expanded NIPT panels achieve reimbursement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands substantially greater absolute testing volume than Canada, though Canadian provincial health authorities are narrowing the gap through accelerated newborn screening investments and NICU sequencing pilots.
United States
FDA oversight of laboratory-developed tests and direct-to-consumer kits creates compliance complexity that favors well-capitalized laboratories with dedicated regulatory affairs teams. The Centers for Medicare and Medicaid Services shapes commercial viability through reimbursement code establishment, with Category 1 CPT codes for pharmacogenomic testing enabling retail pharmacy distribution. Texas Medical Center and Mayo Clinic anchor in-house sequencing programs that displace reference laboratory volumes across hereditary cancer and neonatal diagnostics.
Canada
Provincial health technology assessments in Ontario and British Columbia are evaluating rapid whole-genome sequencing for critically ill neonates, creating pilot-to-scale transition pathways. Health Canada regulates in vitro diagnostic approvals while provincial laboratories operate under parallel quality frameworks. Toronto's Hospital for Sick Children and Vancouver's BC Children's Hospital lead structural variant detection capabilities through long-read sequencing adoption in pediatric genetics departments.
California
The state's stringent CLIA personnel requirements and separate laboratory licensure regime create compliance friction for multi-site health systems seeking standardized test menus across state lines. Silicon Valley clusters anchor bioinformatics workforce development and AI-assisted variant classification tool commercialization. Stanford Medicine and UCSF Medical Center drive liquid biopsy integration into community oncology surveillance protocols throughout the Bay Area and Los Angeles metropolitan regions.
New York
New York State's permit requirements for out-of-state laboratories limit specimen referral patterns and constrain reference laboratory market access for multi-regional health systems. The state Department of Health maintains separate proficiency testing and personnel qualification standards beyond federal CLIA minima. Memorial Sloan Kettering Cancer Center and NewYork-Presbyterian anchor somatic profiling capabilities that serve as referral destinations for complex oncology cases across the Northeast corridor.
North America Genetic Testing Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across platform, assay, and service layer segments. The market structure concentrates around three strategic tiers: national reference laboratories with logistics scale, integrated health systems with captive testing capacity, and technology vendors controlling instrument placement and reagent supply. Dominant competitive moves include vertical integration into bioinformatics interpretation and exclusive payer contracting to lock in specimen flow.
Among diversified diagnostic service providers, Quest Diagnostics and Laboratory Corporation of America Holdings exemplify the reference laboratory archetype through national logistics infrastructure and extensive payer relationships. Illumina occupies a platform-layer position that determines downstream test volumes through sequencing instrument placements. These three entities represent distinct competitive vectors—logistics scale, contracting depth, and technology control—that shape margin capture across the testing value chain.
| Leading Market Players |
|---|
| Quest Diagnostics |
| Laboratory Corporation of America Holdings |
| Invitae Corporation |
| Illumina |
| Thermo Fisher Scientific |
| Myriad Genetics |
| Bio-Rad Laboratories |
| PerkinElmer |
| Natera |
| Others |
Value Chain & Pricing Dynamics
Reagent enzyme costs flow from three global polymerase manufacturers through CLIA-certified laboratories into tiered test pricing that separates STAT oncology profiling from routine carrier screening panels. Polymer supply rationing during demand surges compresses margins for high-throughput screening programs while specialized pharmacogenomic assays retain pricing power through retail pharmacy exclusivity.
Pricing Analysis
Capacity additions in Texas and California health systems are reshaping price floors for reference laboratory send-out volumes. Three-tier pricing structure across premium, standard, and economy levels separates academic medical center STAT testing from community hospital panels and direct-to-consumer carrier screening. Pricing pressure stems from in-house molecular diagnostics programs that displace outsourced specimen processing. Hospital networks exhibit lowest price sensitivity due to captive patient flow, while retail pharmacy distributors face margin compression from Medicare reimbursement rate constraints.
Supply Chain Analysis
Direct-to-CLIA-laboratory channels handle high-complexity molecular diagnostics demand, with secondary distribution through national reference laboratory logistics networks. Manufacturing concentrates in the United States, Germany, and Japan for sequencing instruments, while polymerase and nucleotide reagents draw from concentrated enzyme production in Denmark and the United States. Raw material dependencies include fluorophore-labeled primers, modified nucleotides, and semiconductor-grade flow cells. Single-source vulnerability in thermostable polymerase supply exposes testing laboratories to allocation rationing during respiratory virus surge seasons.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America genetic testing market functions as a stable compounder anchored by expanding newborn screening mandates and pharmacogenomic reimbursement code establishment that lock in recurring test volumes.
For Market Incumbents: Anchor market position through exclusive payer contracting that locks in specimen flow across integrated delivery networks. Pursue backward integration into bioinformatics interpretation platforms to reduce third-party variant analysis costs. Defend against health system in-house sequencing programs by specializing in complex oncology companion diagnostics that require FDA submission pathways. Prioritize CLIA laboratory acquisitions in New York and California to capture state-licensed testing capacity. For New Entrants and Emerging Players: AI-assisted variant classification tools offer the most penetrable entry point for cloud-based interpretation platforms that reduce genetic counselor labor intensity per case. Target direct-to-consumer carrier screening distribution through pharmacy-channel partnerships enabled by FDA regulatory clarity for expanded panels. White-space exists in long-read sequencing services for structural variant detection in pediatric neurodevelopmental disorders. Go-to-market execution should emphasize rapid turnaround guarantees for NICU whole-genome sequencing pilots in Ontario and British Columbia. For Investors and Strategic Acquirers: Consolidation pressure builds where bioinformatics workforce scarcity constrains CLIA-compliant variant analysis capacity. Five-to-ten-year viability favors platforms with captive reagent supply and instrument placement lock-in. Acquisition target archetype: regional reference laboratories with established New York State permits and specialized oncology menus. Signal to watch: CMS coverage determinations for preemptive pharmacogenomic testing in Medicare Advantage populations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for LDT Oversight Compliance | Premarket approval pathways preserve Medicare coverage under NGS national coverage determination. |
| Hospital System Partnership | Exclusive reference laboratory contracts displace fragmented send-out arrangements in Texas and California networks. |
| Software Companion Development | Epic and Cerner workflow integration accelerates test result availability at point-of-care. |
| Reimbursement Strategy | Category 1 CPT code establishment enables commercial viability for retail pharmacy pharmacogenomic programs. |
| CE Marking Pathway | Canadian provincial health technology assessments accelerate adoption of rapid whole-genome sequencing in neonatal intensive care. |
Study Parameters
Direct dialogue with laboratory directors, genetic counselors, health system procurement officers, and FDA regulatory affairs specialists grounded qualitative findings in operational realities across CLIA-certified environments. Secondary validation drew from CMS Medicare data, FDA 510(k) and PMA filings, state laboratory licensure databases, and hospital procurement records. Bottom-up test volume modeling triangulated against top-down market sizing from instrument placement data and reagent consumption patterns.
Bottom-up segmentation analysis tracked product type, end user, technology, and application dimensions across the projection horizon. CAGRs were derived from test volume trajectories weighted by reimbursement code establishment timelines and technology substitution cycles. Forecast inputs incorporated provincial screening program expansion schedules, FDA LDT oversight phase-in assumptions, and health system capital expenditure patterns for in-house molecular diagnostics infrastructure.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA premarket submission requirements, polymerase supply allocation disruptions, and AI-assisted variant classification regulatory acceptance. Forecasts reflect documented assumptions regarding CMS coverage determination timelines and provincial health technology assessment outcomes. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
China Genetic Testing Market
Genomics
Global Digital PCR Market
Genomics
RNA Transcriptome Profiling Test Market
Genomics
Animal Genetics Market
Genomics
Genome Sequencing Market
Genomics
NGS-Based RNA-Sequencing Market
Genomics
Sequencing Electrophoresis Systems Market
Genomics
Genomics Personalized Health Market
Genomics
Global Gene Expression Market
Genomics
Nutrigenomics Testing Market
Genomics
Global Whole Genome Sequencing (WGS) Market
Genomics
Direct-To-Consumer (DTC) Genetic Testing Market
Genomics
Europe Genetic Testing Market
Genomics
Targeted DNA RNA Sequencing Market
Genomics
US Genetic Testing Market
Genomics
AI in Genomics Market