
 Global Silicone Adhesives Market | 2026-2036
Global Silicone Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Silicone Adhesives Market Intelligence
Direct sales channels to large-scale electrical equipment manufacturers and aircraft assemblers are tilting the competitive balance away from traditional distributors. This shift favors suppliers with extensive technical support and global logistics capabilities. Dow leverages its vast chemical production scale to offer competitive pricing on high-volume contracts. Meanwhile, Wacker Chemie AG specializes in high-purity silicone formulations for the electronics and healthcare sectors, commanding premium prices.
Silicone adhesives are elastomers based on siloxane polymers that cure to form a durable, flexible bond. They exhibit exceptional thermal stability and resistance to moisture, making them ideal for sealing and bonding applications across a wide temperature range. Within the technology segment, solvent-free and UV cure formulations are displacing older solvent-based products due to environmental regulations. Among product types, neutral cure silicones see widespread use in construction, while specialized RTV silicones dominate industrial maintenance applications.
The market's product specifications are shaped by multiple regulatory frameworks. The European Union's REACH and RoHS directives restrict certain chemicals, pushing manufacturers towards greener formulations. In the United States, the FDA governs the use of silicone adhesives in food packaging and medical device applications. Stakeholders must now navigate the increasing complexity of material certifications to secure market access in high-value end-use sectors.
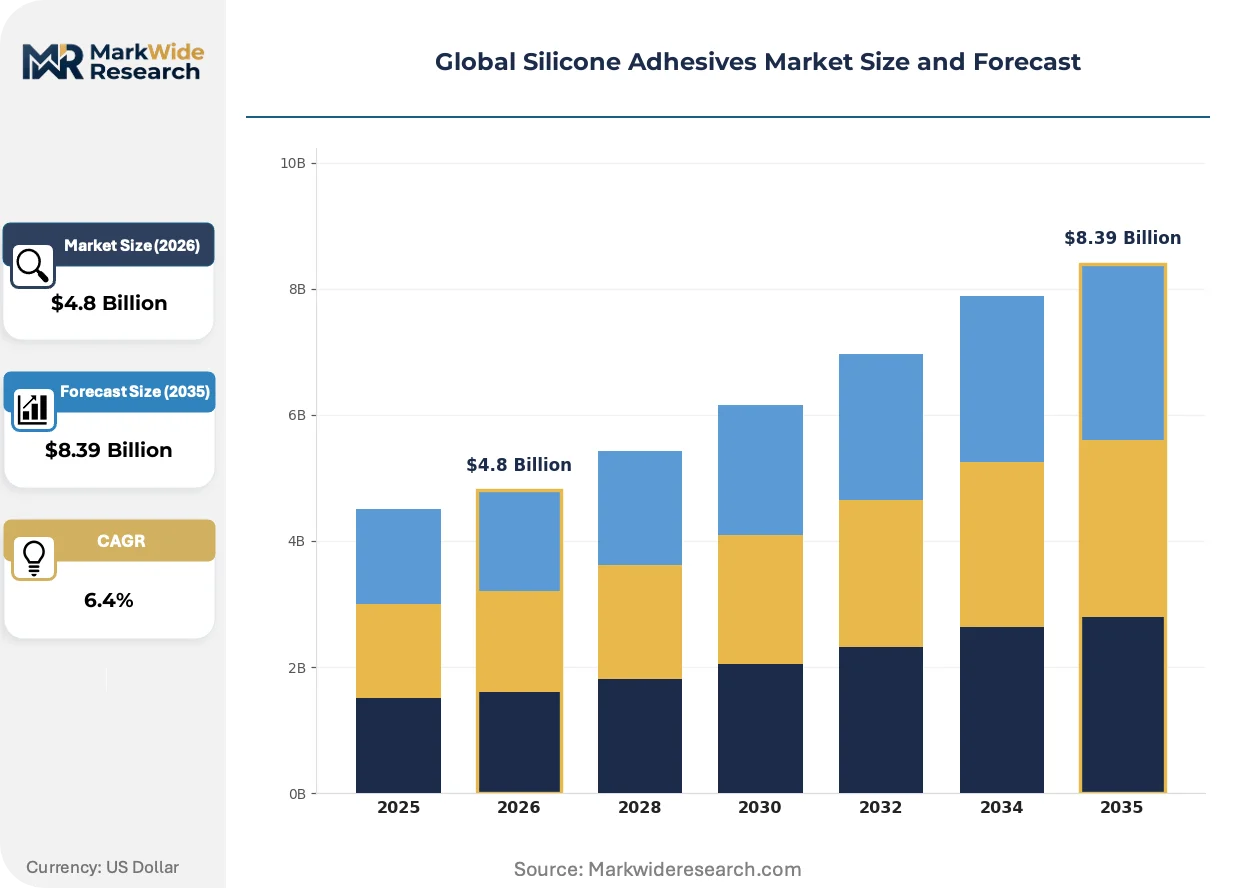
Market Dynamics
The market's structure is defined by a bifurcation between high-volume industrial contracts and specialized, high-margin applications. This split is driven by stringent end-use regulations and the technical demands of advanced manufacturing in electronics and healthcare.
Growth Catalysts
- Electric Vehicle Production:The global ramp-up in EV manufacturing creates significant demand for thermally conductive silicone adhesives for battery pack sealing and thermal interface materials, particularly within automotive supply chains in China and Germany.
- Solvent-Free Formulations Mandate:European Union regulations like REACH are accelerating the phase-out of solvent-based adhesives, directly boosting demand for compliant solvent-free and UV-cure silicone technologies across industrial and construction sectors.
- Consumer Electronics Miniaturization:The continuous drive for smaller, more complex devices in the consumer electronics industry propels the need for high-performance silicone adhesives for bonding dissimilar materials and providing moisture resistance in compact assemblies.
Market Restraints
- Siloxane Precursor Price Volatility:The cost of foundational siloxane polymers, the primary feedstock for silicone adhesives, is subject to significant price fluctuations tied to silicon metal supply, compressing manufacturer margins on standard-grade products.
- Competition from Alternative Adhesives:In less demanding thermal or moisture environments, lower-cost polyurethane and epoxy adhesives present a persistent substitution threat, particularly in general industrial assembly and construction applications.
- Limited Structural Bonding Strength:Compared to structural adhesives like epoxies, silicones exhibit lower tensile and shear strength, limiting their use in high-load-bearing applications within the aerospace and automotive frame sectors.
Strategic Opportunities
- Biocompatible Adhesives for Medical Wearables:The expansion of remote patient monitoring and wearable health devices creates a significant opportunity for specialized, skin-contact grade silicone adhesives that meet stringent biocompatibility standards like ISO 10993.
- Manufacturing Growth in Southeast Asia:The development of new electronics and automotive assembly hubs in countries like Vietnam and Malaysia presents an underpenetrated market for silicone adhesives outside of established Chinese industrial clusters.
- Integration with UV/LED Curing Systems:Developing silicone adhesives that cure rapidly under specific UV or LED light wavelengths offers a pathway to increase throughput on automated assembly lines in the electronics and medical device sectors.
Industry Challenges
- Navigating Multi-Jurisdictional Certifications:Manufacturers face long and costly timelines to secure material approvals across different regulatory bodies, such as the FDA for medical use in the US and ECHA under REACH in Europe.
- Demand for Specialized Application Support:Supporting large-scale industrial customers requires a deep bench of technical experts capable of co-developing custom formulations, creating a significant talent acquisition and retention challenge for suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Silicone Adhesives Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetoxy Silicone, Neutral Cure Silicone, Oxime Silicone, RTV Silicone, LSR Silicone Technology: Solvent-Based, Solvent-Free, Hot Melt, UV Cure, Two-Component Application: Electronics Assembly, Construction Bonding, Consumer Goods, Aerospace Components, Packaging Sealants End User Industry: Electrical Equipment Manufacturers, Building Materials Suppliers, Consumer Electronics Producers, Aircraft Assemblers, Food Packaging Companies |
| Companies Covered | Wacker Chemie AG, Elkem Silicones, Dow, Sika AG, 3M Company, Henkel AG & Co. KGaA, Momentive Performance Materials Inc., Arkema S.A., Shin-Etsu Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Silicone Adhesives Market Strategic Shifts & Innovations
Formulation advancements are pushing silicone adhesives beyond basic sealing into roles defined by manufacturing efficiency and sustainability. The focus is on materials that accelerate production cycles and comply with a tightening global regulatory landscape for chemical products.
UV-curing silicone adhesives provide on-demand, rapid curing when exposed to specific light wavelengths. Electronics and medical device manufacturers are rapidly adopting these systems to increase assembly line speeds. The technology is migrating from slower, two-part thermal or moisture-cure systems toward highly automated, high-throughput production lines where seconds of cure time matter.
The European Union's Restriction of Hazardous Substances (RoHS) directive continues to tighten limits on materials like lead and certain phthalates in electronic equipment. This forces adhesive manufacturers to validate and certify their formulations as compliant, removing non-compliant products from the supply chain. The consumer electronics segment is most directly impacted, requiring full material declarations from suppliers.
A clear shift towards direct technical collaboration between end-users and adhesive formulators is underway, bypassing traditional multi-line distributors. This model allows for co-development of application-specific adhesives, a practice now standard for procurement in the aerospace and automotive EV sectors. This trend is most pronounced in industrial clusters in Germany and China.
Global Silicone Adhesives Market Segmentation
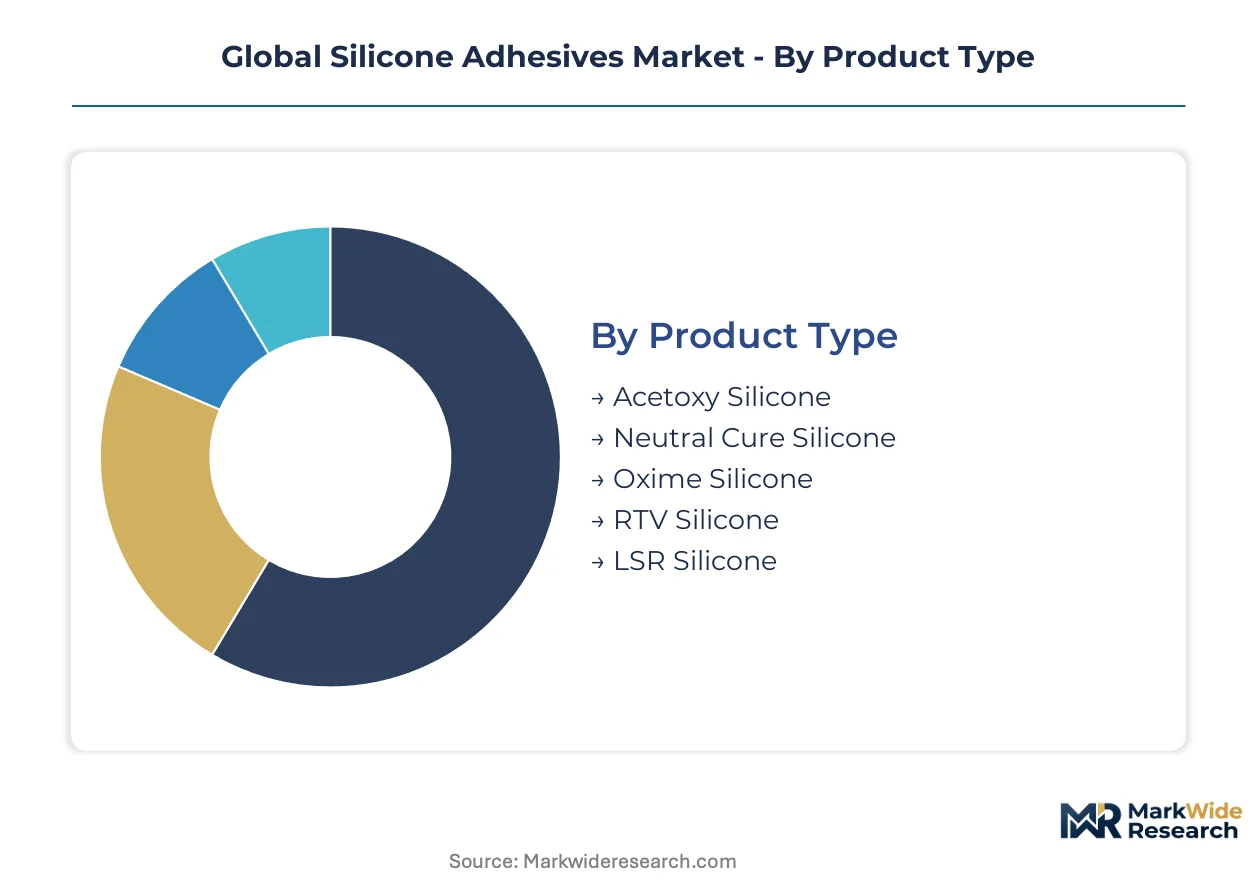
The Global Silicone Adhesives Market segmentation illuminates the diverse requirements shaping product development and market penetration strategies. Understanding these distinct categories helps manufacturers align their offerings with specific industry demands and regulatory landscapes. This granular view reveals critical areas for investment and competitive differentiation.
Product Type:
The product type segmentation highlights varying production cycle times, from rapid-cure formulations to those requiring extended processing.
- Neutral Cure Silicone:These formulations release non-corrosive byproducts, making them suitable for sensitive substrates like electronics and metals. Demand concentrates in construction and automotive manufacturing in Germany, driven by long-term durability.
- RTV Silicone:Room Temperature Vulcanizing silicones cure at ambient temperatures, forming flexible, durable elastomers. Their demand is strong in industrial maintenance and sealing applications across China's manufacturing base.
- Acetoxy Silicone:Releases acetic acid during curing, offering fast adhesion for general-purpose sealing in less sensitive environments.
- Oxime Silicone:Oxime-cure silicones provide good adhesion and non-corrosive curing, used in automotive and electronics where odor is a concern.
- LSR Silicone:Liquid Silicone Rubber formulations offer high-precision molding and rapid curing for medical devices and complex consumer electronics.
Neutral Cure Silicone anchors the volume base while LSR Silicone gains share at the steepest rate.
Technology:
The technological approaches vary significantly in upfront investment and long-term operational costs for manufacturers.
- UV Cure:These adhesives polymerize rapidly under ultraviolet light, enabling high-speed automated assembly lines in electronics and medical device production. Demand is strong in advanced manufacturing hubs in the US and Japan, where throughput is critical.
- Solvent-Free:Formulations without volatile organic compounds comply with stringent environmental regulations like the EU's REACH directive. Consumer electronics and construction companies in Europe rapidly adopt these safer solutions.
- Two-Component:These systems cure upon mixing two parts, providing controlled reaction times and robust bonding for structural applications.
- Hot Melt:Hot melt adhesives are thermoplastic, applied molten and solidifying upon cooling, offering fast initial tack for packaging.
- Solvent-Based:Traditional adhesives using organic solvents that evaporate during curing, but their use declines due to environmental and health concerns.
UV Cure technology expands most quickly due to its efficiency, while Solvent-Free formulations align with evolving environmental standards.
Application:
Application segments delineate where the largest volumes of silicone adhesives are consumed, influencing production scale.
- Electronics Assembly:Silicone adhesives provide critical bonding, sealing, and thermal management for miniaturized components, protecting against moisture and vibration. Significant demand comes from consumer electronics producers in China.
- Construction Bonding:Silicones offer durable, weather-resistant seals for glazing, panel bonding, and expansion joints in buildings, ensuring long-term structural integrity. Demand is consistent across global construction markets, particularly in Southeast Asia.
- Consumer Goods:Silicone adhesives bond and seal various household items, appliances, and personal care products for flexibility and durability.
- Aerospace Components:These adhesives provide high-temperature resistance and vibration dampening for critical sealing and bonding in aircraft structures.
- Packaging Sealants:Silicone sealants offer excellent moisture barrier properties and chemical resistance for food and pharmaceutical packaging.
Electronics Assembly drives high-performance product development, while Construction Bonding remains a consistent, high-volume segment.
End User Industry:
End user industries exhibit distinct procurement patterns, from large-scale direct contracts to distributed supply chains.
- Consumer Electronics Producers:This industry requires high-performance, fast-curing adhesives for intricate assemblies, moisture protection, and thermal management. Manufacturers in South Korea and Vietnam drive demand for advanced silicone formulations.
- Electrical Equipment Manufacturers:These companies utilize silicone adhesives for sealing, potting, and bonding components in transformers, circuit boards, and power generation equipment. Industrial clusters in China and the US represent substantial procurement volumes.
- Building Materials Suppliers:These suppliers integrate silicone adhesives into window frames, facade systems, and architectural elements for durable, weather-resistant sealing.
- Aircraft Assemblers:The aerospace sector demands certified silicone adhesives for critical sealing, gasketing, and bonding applications requiring extreme conditions.
- Food Packaging Companies:This industry uses FDA-compliant silicone adhesives for sealing food containers and flexible packaging, ensuring product safety.
Consumer Electronics Producers demand innovative, high-throughput solutions, contrasting with the stable, long-term requirements of Building Materials Suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The integrated manufacturing corridors, spanning from Asian electronics hubs to European automotive production lines, underpin the global silicone adhesives market. These vital arteries facilitate the movement of raw materials and finished goods. They connect key industrial clusters requiring high-performance bonding solutions.
China
China's vast electronics assembly and electric vehicle production drive significant demand for silicone adhesives. The country's dual carbon goals accelerate the need for advanced battery pack sealing materials. Industrial clusters like the Pearl River Delta actively integrate these solutions into high-volume manufacturing.
Germany
The German automotive industry, particularly in electric vehicle manufacturing, requires specialized silicone adhesives for thermal management. European Union regulations like REACH drive the adoption of solvent-free formulations. Production hubs in Bavaria and Baden-Württemberg focus on precision bonding for advanced industrial applications.
United States
American consumer electronics and medical device sectors increasingly demand high-performance silicone adhesives for miniaturized components. FDA regulations govern biocompatible formulations for wearables and medical implants. Innovation centers in Silicon Valley and the Northeast Corridor develop advanced UV-cure technologies.
South Korea
South Korea's leading consumer electronics producers and battery manufacturers require high-throughput silicone adhesives for complex assemblies. National standards from KATS ensure quality and performance across industrial applications. The Seoul Capital Area drives innovation in liquid silicone rubber for precision molding.
Vietnam
Emerging electronics assembly hubs in Vietnam present a growing market for silicone adhesives, particularly for consumer devices. The government's industrialization policies attract foreign direct investment into manufacturing. Production facilities around Ho Chi Minh City and Hanoi integrate these materials for efficient production.
Global Silicone Adhesives Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying foundational materials. The silicone adhesives market exhibits a tiered structure, with global chemical giants providing base polymers and specialized formulators offering high-performance solutions. Key archetypes include large-scale chemical producers, niche technology developers, and regional distributors. Capacity expansion and strategic partnerships are dominant competitive moves among these players.
On the premium-tier vector, Dow, a major American chemical corporation, exemplifies a large-scale producer leveraging vast production capacity for high-volume industrial contracts. Germany-based Wacker Chemie AG represents a specialist in high-purity silicone formulations, commanding premium prices within the electronics and healthcare sectors. Japan's Shin-Etsu Chemical Co., Ltd. occupies a similar position, focusing on advanced silicone technologies and maintaining a strong global footprint across diverse end-use industries.
| Leading Market Players |
|---|
| Wacker Chemie AG |
| Elkem Silicones |
| Dow |
| Sika AG |
| 3M Company |
| Henkel AG & Co. KGaA |
| Momentive Performance Materials Inc. |
| Arkema S.A. |
| Shin-Etsu Chemical Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Silicon metal supply concentration directly influences the cost structure of siloxane polymers, compressing margins for standard-grade silicone adhesives. This upstream dynamic shapes pricing power for high-volume producers and specialized formulators.
Pricing Analysis
Tiered pricing separates high-volume industrial contracts from specialized, high-margin formulations. Price differentiation stems from formulation purity, technical support requirements, and critical material certifications like FDA approval. Cost compression on standard-grade products intensifies due to siloxane precursor price volatility. Construction and general industrial buyers exhibit higher price sensitivity compared to electronics and medical device manufacturers seeking high-performance solutions.
Supply Chain Analysis
Contract manufacturing for electronics and automotive assembly concentrates heavily in China, South Korea, and Vietnam. The supply chain draws from foundational siloxane polymers, which are derived from silicon metal. Commodity price volatility for siloxane precursors presents a structural supply chain risk for manufacturers. Distribution runs increasingly through direct sales channels for large industrial customers, displacing traditional multi-line distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The silicone adhesives market is in an early-cycle expansion phase, driven by the rapid penetration of electric vehicle manufacturing. This transition creates significant new demand for thermal management and battery pack sealing materials.
For Market Incumbents:Build technical expertise moats by investing heavily in R&D for advanced UV-cure and biocompatible formulations. Expand global logistics and technical support networks to maintain direct sales channels, countering traditional distributor erosion. Prioritize material certification investments for FDA and REACH compliance, addressing the threat of regulatory barriers. Deepen vertical integration into specialized siloxane precursor production to mitigate commodity price volatility.
For New Entrants and Emerging Players:Build out specialized portfolios targeting biocompatible adhesives for medical wearables, meeting stringent ISO 10993 standards. Penetrate emerging electronics assembly hubs in Vietnam and Malaysia, offering UV-cure formulations for automated lines. Focus on co-development partnerships with regional manufacturers, providing tailored solutions for rapid throughput. This approach leverages unmet demand in high-growth, technically demanding applications.
For Investors and Strategic Acquirers:Capital is best deployed toward specialized formulators with strong IP in UV-cure and biocompatible silicone technologies. The market demonstrates long-term viability, underpinned by essential applications in electric vehicles and medical devices. Target firms that possess robust material certifications and established direct sales channels to high-value end-users. Monitor the accelerating adoption of solvent-free and UV-cure formulations as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in UV-Cure Formulations | This initiative increases supply for automated electronics and medical device assembly lines. |
| Investment in Biocompatible R&D | Developing skin-contact grade adhesives opens new opportunities in the rapidly expanding medical wearables market. |
| Global Logistics Network Enhancement | Strengthening distribution capabilities supports direct sales to large-scale electrical equipment and automotive manufacturers. |
| Strategic Partnership for Solvent-Free Technologies | Collaborating on greener formulations ensures compliance with European Union REACH and RoHS directives. |
| Material Certification Portfolio Expansion | Securing approvals like FDA and ISO 10993 enables market access in high-value medical and food packaging sectors. |
Research Approach
Operator-level perspectives from R&D directors, procurement leads at consumer electronics producers, and regulatory affairs specialists anchored the qualitative base. Primary interviews were triangulated with secondary research from industry association reports and patent databases. This dual approach ensured robust validation of market dynamics and technology trends. Both bottom-up and top-down analyses were integrated.
Scenario-bracketing underpinned the quantitative framework, modeling growth trajectories across the analysis window. Segmentation dimensions included product type, technology, application, and end-user industry, alongside regional regulatory impacts. Compound annual growth rates were derived from historical trends and projected EV production volumes. Miniaturization trends in consumer electronics also informed forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by niche technology developers would shift outcomes. Assumptions reflect raw material stability and regulatory consistency. Quarterly review of EV production and new material certifications is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Vascular Sealant Market
Adhesives & Sealants
Gasket and Seal Material Market
Adhesives & Sealants
Wood Adhesives Market
Adhesives & Sealants
North America & Europe Adhesives and Sealants Market
Adhesives & Sealants
Global Tissue Sealants Market
Adhesives & Sealants
Die Cut Adhesive Market
Adhesives & Sealants
Middle-East and Africa Contact Adhesives Market
Adhesives & Sealants
Temporary Bonding Adhesives Market
Adhesives & Sealants
Adhesive Dispensing Systems Market
Adhesives & Sealants
Dispersion Adhesives Market
Adhesives & Sealants
North America Automotive Adhesives and Sealants Market
Adhesives & Sealants
Pvc Based Adhesive Market
Adhesives & Sealants
Malaysia Adhesives Market
Adhesives & Sealants
Metal Glue Market
Adhesives & Sealants
Europe Chemical Anchors Market
Adhesives & Sealants
Packaging Adhesives Market