
 Marine Sealants Market | 2026-2036
Marine Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Sealants Market Analysis
The capital-intensity divergence between integrated resin producers and formulation specialists is unwinding competitive stability in marine sealants. Dow Inc. leverages captive silicone monomer supply to dominate premium hull-sealing grades. Sika AG anchors its position through construction-adjacent distribution networks that extend into yacht refit channels. Henkel AG & Co. KGaA differentiates via adhesive-sealant cross-selling to industrial marine OEMs.
Marine sealants are elastomeric compounds formulated to resist saltwater immersion, UV degradation, and cyclic thermal stress while maintaining adhesion to fiberglass, aluminum, and coated steel substrates. These materials cure through moisture-triggered polymerization or solvent evaporation to form flexible watertight barriers critical to hull integrity, deck sealing, and through-hull fitting security. Polyurethane formulations command the largest volume share due to their balance of tensile strength and elasticity in dynamic joint applications, while silicone grades capture margin pools in high-temperature engine-room sealing where thermal stability exceeds polysulfide performance. The boat building application segment sustains the fastest growth trajectory as composite hull production expands and OEMs specify longer warranty periods requiring certified sealant systems.
The U.S. Coast Guard and EPA jointly enforce substrate-specific VOC limits that force reformulation of solvent-borne acrylic caulks in domestic shipyard applications. The EU REACH framework and F-Gas Regulation restrict certain curing-agent chemistries, compelling Arkema Group and Bostik to accelerate bio-based catalyst development for European market access. Stakeholders must monitor regulatory divergence between IMO conventions and national implementation timelines to avoid stranded inventory in multi-jurisdiction supply chains.
Market Dynamics
The International Maritime Organization's revised anti-fouling standards are forcing reformulation cycles across all major sealant chemistries, compressing certification timelines and redrawing competitive boundaries between integrated resin producers and formulation specialists.
Growth Catalysts
- LNG Carrier Construction:South Korean shipyard clusters are specifying certified polyurethane systems for cryogenic cargo containment, creating sustained volume pull for high-performance grades.
- REACH Framework Evolution:The EU F-Gas Regulation is accelerating bio-based catalyst adoption, opening formulation windows for producers with sustainable chemistry capabilities.
- Composite Hull Expansion:Fiberglass-reinforced plastic production is expanding across recreational and commercial segments, driving demand for elastomeric sealing systems compatible with thermoset substrates.
Market Restraints
- Silicone Monomer Concentration:Captive supply chains among integrated petrochemical majors limit formulation specialists' access to premium-grade raw materials for engine-room applications.
- VOC Compliance Costs:The U.S. EPA's substrate-specific emission limits for solvent-borne acrylics are forcing costly reformulation without price recovery mechanisms in domestic shipyard contracts.
- Polysulfide Substitution:Silicone grades are displacing polysulfide formulations in high-temperature sealing, eroding volume bases for producers without thermal-stable polymer capabilities.
Strategic Opportunities
- Yacht Refit Channel Expansion:Construction-adjacent distribution networks are extending into Mediterranean and Caribbean maintenance hubs, capturing aftermarket margin pools.
- IMO 2025 Certification Pre-positioning:Early alignment with pending anti-fouling convention amendments offers first-mover advantage in multi-jurisdiction supply chains.
- Adhesive-Sealant Cross-Selling:Industrial marine OEMs are consolidating procurement around multi-functional bonding systems, rewarding suppliers with integrated product portfolios.
Industry Challenges
- Formulation Chemist Scarcity:Specialized expertise in moisture-triggered polymerization systems is concentrated among aging technical workforces in European and East Asian chemical clusters.
- Multi-Jurisdiction Inventory Stranding:Divergent national implementation timelines for IMO conventions create compliance gaps that expose distributors to stranded stock risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Sealants Market |
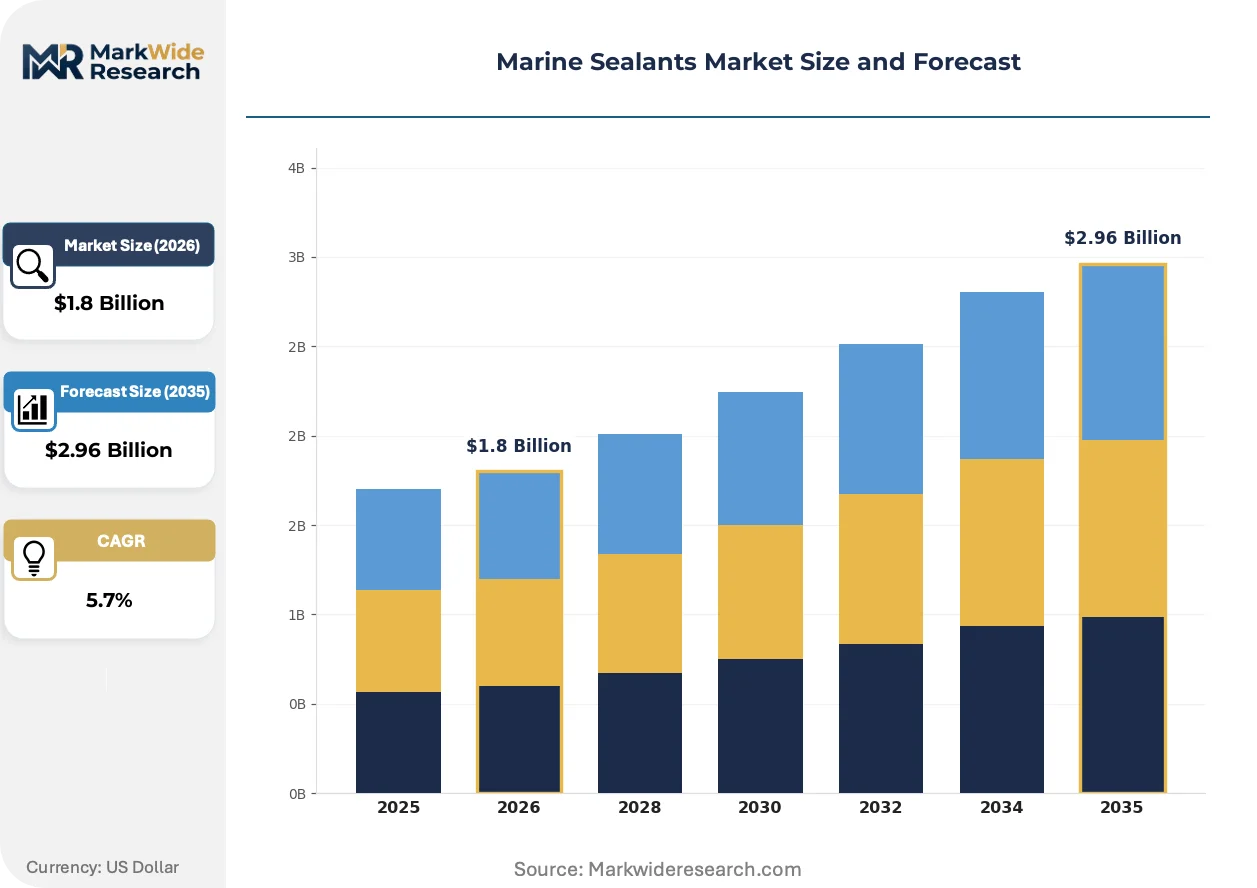
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Polysulfide, Polyurethane, Silicone, Acrylic Application: Boat Building, Maintenance, Repair, Marine Engineering End User: Manufacturers, Dealers, DIY Customers, Service Providers Form: Caulk, Tape, Sealant Cartridge, Liquid |
| Companies Covered | 3M Company, Sika AG, Henkel AG & Co. KGaA, Dow Inc., Arkema Group, H.B. Fuller Company, Illinois Tool Works Inc., Bostik, DuPont de Nemours Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Sealants Market Emerging Trajectories
Formulation science is pivoting toward bio-derived curing agents and hybrid polymer architectures that reconcile performance specifications with tightening chemical restrictions across major maritime jurisdictions.
Moisture-cured silane-terminated polyurethane technology is fragmenting the traditional segmentation between hull-sealing and deck-joint applications. Commercial ferry operators are adopting these hybrid systems for their combined tensile strength and UV resistance. The technology is fragmenting established procurement patterns by enabling single-specification programs across previously distinct product categories.
The EU F-Gas Regulation is restricting hydrofluorocarbon-based blowing agents in sealant foam formulations. Industrial consequences include accelerated R&D spending on physical blowing agent alternatives and compressed reformulation timelines for European market access. Marine OEMs serving EU-flagged vessels are qualifying water-blown polyurethane systems ahead of enforcement deadlines.
Shipyard procurement departments are consolidating adhesive and sealant specifications under unified technical approval systems. The traditional separation between structural bonding and watertight sealing is collapsing into combined material callouts. This consolidation is most visible in German and Dutch yacht construction, where classification society rules are being rewritten around integrated bonding-sealing performance standards.
Marine Sealants Market Segmentation
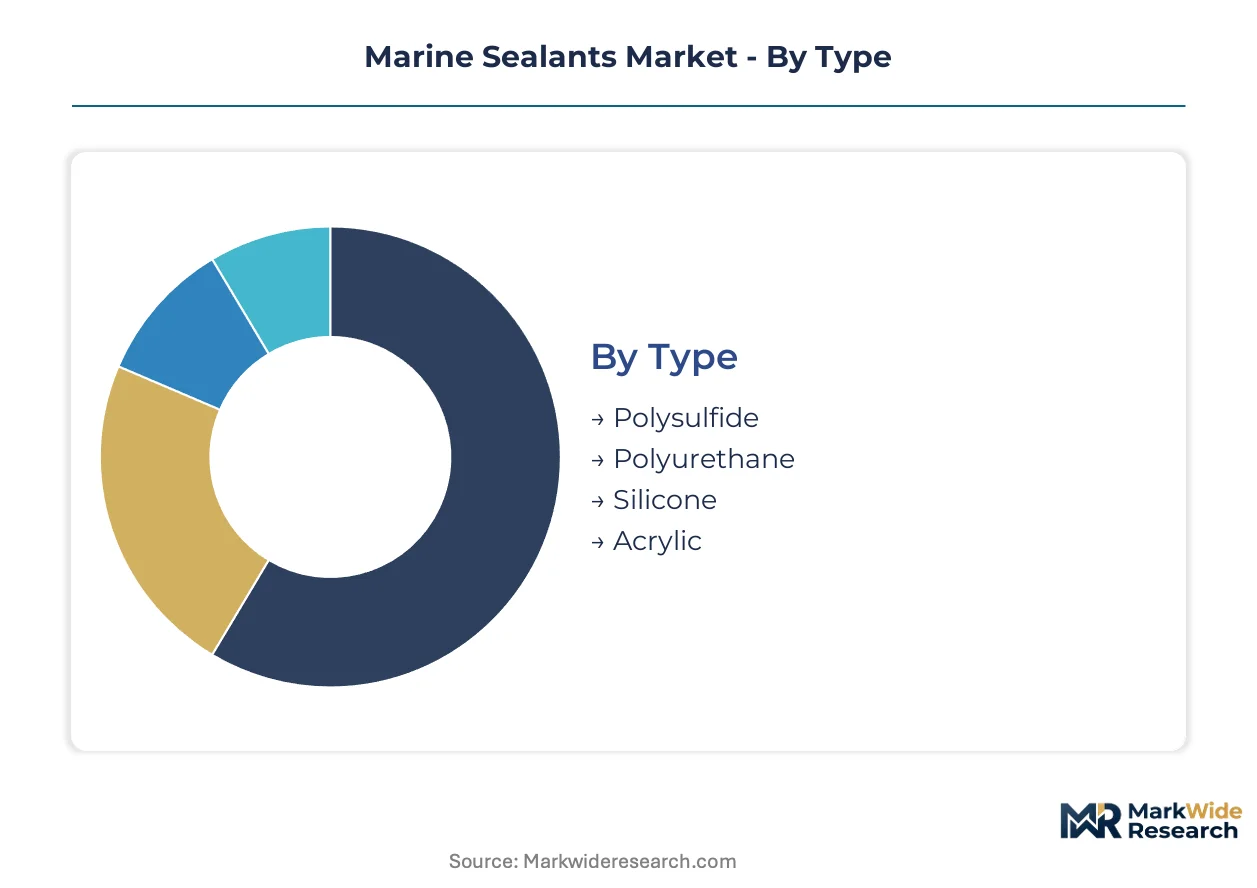
Marine sealant procurement patterns diver sharply across chemistry families and end-use channels. IMO certification requirements and substrate-specific VOC limits create non-overlapping demand pools that reward specialized formulation capabilities.
Type:
REACH and F-Gas Regulation timelines are fragmenting competitive positioning across chemistry families, with thermal stability specifications and catalyst restrictions determining market access.
- Polyurethane:Moisture-cured silane-terminated architectures dominate cryogenic cargo containment applications. South Korean LNG carrier yards specify certified polyurethane systems for cargo barrier sealing, with qualification cycles extending to IMO anti-fouling amendments.
- Silicone:Thermal stability above 200°C positions silicone grades for engine-room sealing where polysulfide performance degrades. Captive monomer supply chains among integrated petrochemical majors constrain formulation specialists' access to premium feedstock.
- Polysulfide:Historic hull-sealing standard now retreating to cost-sensitive maintenance applications as silicone displaces high-temperature use cases.
- Acrylic:Solvent-borne formulations face EPA substrate-specific VOC limits in domestic US shipyards, forcing water-borne reformulation without price recovery mechanisms.
Polyurethane handles the majority of throughput; silicone is the fastest mover on share.
Application:
Volume concentration tracks composite hull production expansion and warranty period extensions by OEMs.
- Boat Building:Fiberglass-reinforced plastic production expansion drives elastomeric sealing system demand compatible with thermoset substrates. OEM specification of longer warranty periods requires certified sealant systems with documented performance data.
- Maintenance:Mediterranean and Caribbean yacht refit hubs concentrate aftermarket margin capture. Construction-adjacent distribution networks extend into seasonal maintenance corridors.
- Repair:Emergency hull integrity restoration in commercial shipping channels demands rapid-cure formulations with saltwater immersion resistance.
- Marine Engineering:Through-hull fitting security and deck sealing in industrial vessels require dynamic joint performance under cyclic thermal stress.
Boat building commands the largest volume position; maintenance is climbing the fastest on revenue contribution.
End User:
Procurement consolidation patterns separate specification authority from purchasing execution across the value chain.
- Manufacturers:Industrial marine OEMs consolidate procurement around multi-functional bonding systems, collapsing traditional separation between structural adhesive and watertight sealant specifications. German and Dutch yacht construction leads this integration.
- Service Providers:Technical approval systems for classification society compliance concentrate purchasing power among certified applicators with documented cure control capabilities.
- Dealers:Channel intermediaries stock fast-moving SKUs for emergency repair demand in commercial shipping corridors.
- DIY Customers:Recreational boat owners drive cartridge-format demand through retail marine supply networks.
Manufacturers dominate specification authority; service providers are gaining share fastest on technical compliance requirements.
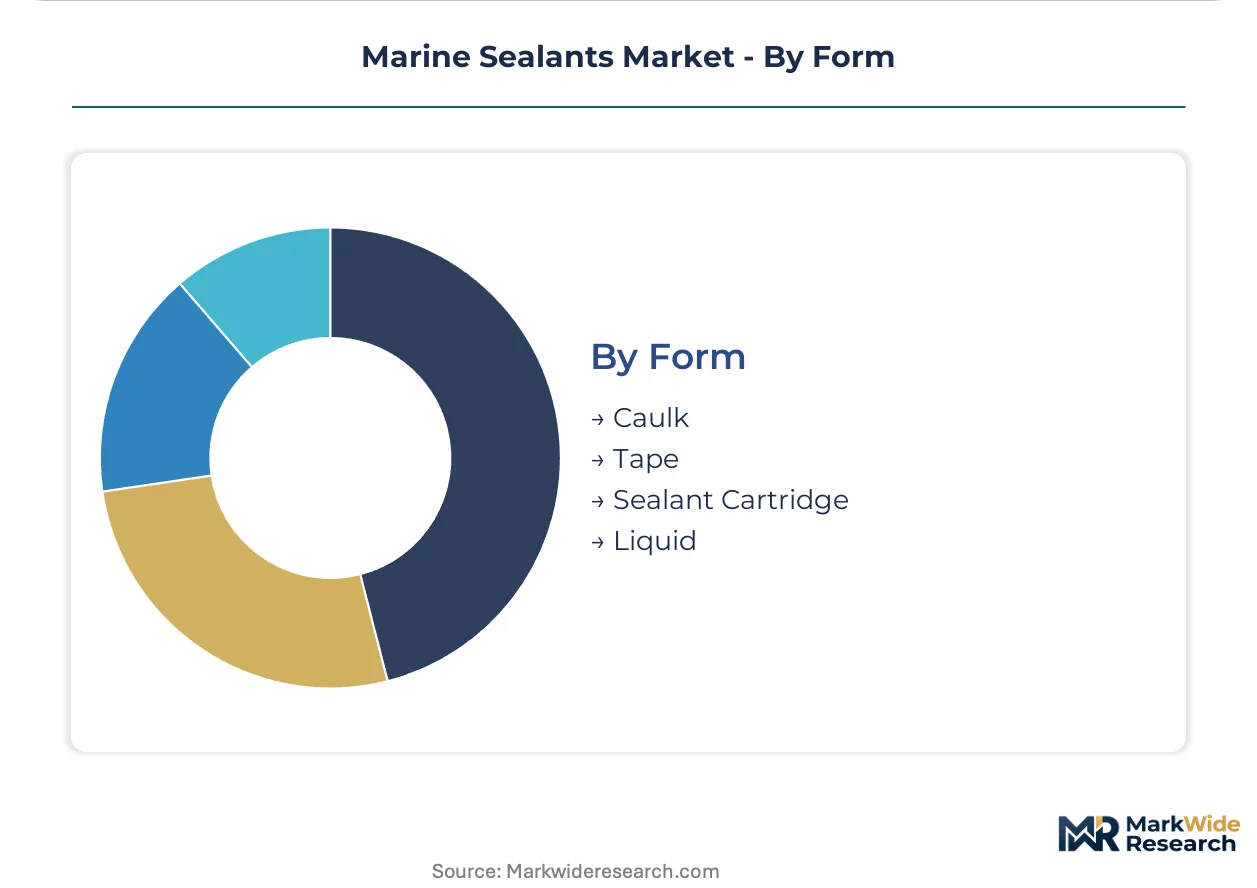
Form:
Packaging format selection reflects application scale, cure control requirements, and substrate access constraints.
- Sealant Cartridge:Standard dispensing format for precision joint filling in hull sealing and deck applications. Compatible with manual and pneumatic application equipment across shipyard and field conditions.
- Liquid:Bulk delivery for industrial-scale composite hull lamination and OEM production lines requiring metered-mix dispensing systems.
- Caulk:Gun-grade consistency for gap-filling in irregular substrates and retrofit applications with variable joint geometry.
- Tape:Preformed sections for rapid deployment in emergency repairs and temporary watertight barriers.
Sealant cartridge moves the highest unit volume; liquid is expanding most quickly on OEM production scale-up.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in marine sealants diverges sharply by end-use channel. Commercial shipping operators prioritize certified performance over unit cost, while recreational boat builders face margin compression that rewards formulation efficiency.
South Korea
LNG carrier construction at Hyundai Heavy Industries and Samsung Heavy Industries drives specification of cryogenic-grade polyurethane systems. The Korean Register of Shipping enforces IMO anti-fouling certification timelines that compress supplier qualification cycles. Ulsan and Geoje shipyard clusters concentrate demand for elastomeric cargo barrier sealants with documented thermal cycling performance.
Germany
Yacht construction in northern shipyards consolidates adhesive and sealant procurement under unified technical approval systems. The Federal Maritime and Hydrographic Agency implements EU REACH and F-Gas Regulation restrictions on curing-agent chemistries. Hamburg and Bremen industrial corridors host formulation specialists accelerating bio-based catalyst development for European market access.
United States
Commercial ferry operators adopt hybrid silane-terminated polyurethane systems for combined hull and deck sealing. The EPA enforces substrate-specific VOC limits that force water-borne reformulation of solvent-borne acrylic caulks in domestic shipyards. Gulf Coast and Pacific Northwest marine manufacturing clusters specify certified systems to satisfy extended OEM warranty requirements.
China
Composite hull production expansion across recreational and commercial segments drives elastomeric sealing system demand. The Ministry of Ecology and Environment aligns national standards with IMO convention timelines for anti-fouling product certification. Yangtze River Delta shipbuilding centers concentrate procurement of moisture-cured formulations compatible with fiberglass-reinforced plastic substrates.
Netherlands
Classification society rules in Dutch yacht construction rewrite technical standards around integrated bonding-sealing performance. The Human Environment and Transport Inspectorate enforces EU chemical restrictions that accelerate sustainable formulation adoption. Rotterdam and Amsterdam distribution hubs extend construction-adjacent networks into Mediterranean and Caribbean refit corridors.
Marine Sealants Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics. Integrated petrochemical majors control captive silicone monomer supply for premium engine-room applications, while formulation specialists compete on application-specific technical service. Three archetypes dominate: resin-integrated multinationals, construction-chemical conglomerates with marine-adjacent distribution, and regional formulation specialists serving shipyard clusters. Competitive moves concentrate on certification pre-positioning ahead of IMO regulatory amendments and cross-selling adhesive-sealant portfolios to consolidating marine OEM procurement departments.
Among resin-integrated multinationals, Dow Inc. and Arkema Group exemplify the technology leadership archetype through upstream control over specialty monomer supply. Sika AG and Henkel AG & Co. KGaA occupy positions within the construction-chemical conglomerate tier, leveraging adjacent distribution infrastructure into marine aftermarket channels. These four companies represent the competitive poles around which formulation specialists and regional suppliers coordinate qualification strategies.
| Leading Market Players |
|---|
| 3M Company |
| Sika AG |
| Henkel AG & Co. KGaA |
| Dow Inc. |
| Arkema Group |
| H.B. Fuller Company |
| Illinois Tool Works Inc. |
| Bostik |
| DuPont de Nemours Inc. |
| Others |
Supply Flow & Price Mechanics
Silicone displacement of polysulfide in engine-room sealing simultaneously concentrates supply geography around captive monomer producers in South Korea and Germany while compressing pricing economics for formulation specialists lacking thermal-stable polymer capabilities. This substitution dynamic rewards integrated petrochemical majors with backward control over specialty silicone feedstock while eroding margin pools for independent compounders serving maintenance channels.
Pricing Analysis
Aftermarket service contracts and emergency repair callouts drive lifetime value capture in marine sealants. Three-tier pricing structure across IMO-certified premium grades, shipyard-standard formulations, and cost-optimized maintenance tiers separates specification authority from purchasing execution. Cost compression in solvent-borne acrylic segments intensifies as EPA VOC limits force water-borne reformulation without contract price recovery mechanisms. Commercial shipping operators demonstrate lowest price sensitivity due to classification society compliance requirements, while recreational boat builders face acute margin pressure from composite hull OEMs.
Supply Chain Analysis
Inventory cycles for moisture-cured polyurethane systems stretch 8-12 weeks at South Korean LNG carrier yards due to cryogenic certification batch testing. Supply concentration in Germany, South Korea, and the United States reflects proximity to major shipbuilding clusters and regulatory approval infrastructure. Formulation depends on specialty isocyanate and silane-terminated polyether feedstocks sourced from integrated chemical producers. Single-source vulnerability in silicone monomer supply chains exposes formulation specialists to allocation risk during petrochemical turnaround seasons. Distribution runs through construction-adjacent networks extending into Mediterranean and Caribbean yacht refit corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine sealants function as a substitution defense market where silicone and hybrid polyurethane architectures threaten to commoditize traditional polysulfide and acrylic positions. Incumbents must navigate this chemistry transition while preserving certification-derived pricing power.
For Market Incumbents: Fortify captive feedstock positions through backward integration into silane-terminated polyether production or long-term offtake agreements with Korean and German chemical producers. Accelerate IMO 2025 anti-fouling certification pre-positioning to lock out formulation specialists lacking qualification bandwidth. Prioritize adhesive-sealant cross-selling to German and Dutch yacht OEMs consolidating procurement under unified technical approval systems. For New Entrants and Emerging Players: Anchor in Caribbean and Mediterranean yacht refit channels where construction-adjacent distributors seek secondary supply sources for fast-moving maintenance SKUs. Target bio-based catalyst formulations for EU market access as REACH and F-Gas Regulation timelines compress incumbent reformulation windows. Pursue private-label partnerships with regional shipyard clusters lacking in-house formulation capabilities. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European formulation specialists holding aging technical workforces and stranded polysulfide capacity. Five-to-ten year viability hinges on successful chemistry transition to thermal-stable polymers and hybrid architectures. Monitor IMO convention implementation divergence as inflection indicator for multi-jurisdiction inventory stranding risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane-Terminated Polyether | Captive feedstock supply secures cryogenic-grade polyurethane qualification at Hyundai Heavy Industries. |
| IMO 2025 Certification Pre-Positioning | Early anti-fouling amendment alignment creates first-mover advantage in multi-jurisdiction supply chains. |
| Bio-Based Catalyst Development | Sustainable chemistry capabilities unlock EU market access under tightening F-Gas Regulation timelines. |
| Yacht Refit Channel Expansion | Construction-adjacent networks capture aftermarket margin pools in Mediterranean maintenance hubs. |
| Adhesive-Sealant Portfolio Integration | Combined bonding-sealing specifications consolidate procurement at German and Dutch yacht OEMs. |
Methodological Framework
The analysis maps polyurethane, silicone, polysulfide, and acrylic chemistry families, each validated through formulation chemists, shipyard procurement managers, classification society surveyors, and marine OEM technical directors. Primary interviews with these stakeholders combined with secondary validation from customs trade data, Korean Register of Shipping certification records, EPA enforcement disclosures, and SEC chemical producer filings. Bottom-up volume builds from shipyard consumption patterns triangulate against top-down resin producer revenue allocations.
Consistency checks against external benchmarks validated output plausibility across the projection horizon. Segmentation dimensions modeled include chemistry type, application channel, end-user procurement authority, and packaging format. CAGRs derive from elasticity-adjusted volume projections incorporating LNG carrier construction schedules, composite hull production expansion, and regulatory implementation timelines. Forecast inputs incorporate IMO convention amendment schedules and EU chemical restriction enforcement windows without assigning specific dates.
Material uncertainties — regulatory implementation divergence, raw material allocation disruptions, and chemistry substitution velocity — sit outside the modeled envelope. Forecasts reflect documented assumptions about certification timeline compression and shipyard procurement consolidation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Structural Sealants Market
Adhesives & Sealants
Water-Borne Adhesives Market
Adhesives & Sealants
Acrylates Copolymer Market
Adhesives & Sealants
Lead Encapsulants Market
Adhesives & Sealants
Europe Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Global Slack Wax Market
Adhesives & Sealants
South America Waterborne Adhesives Market
Adhesives & Sealants
Marine Adhesives Market
Adhesives & Sealants
Spain Sealants Market
Adhesives & Sealants
Specialty Adhesives Market
Adhesives & Sealants
United States Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Global Dental Adhesives and Sealants Market
Adhesives & Sealants
Corrosion Protection Tapes Market
Adhesives & Sealants
North America Construction Adhesives and Sealants Market
Adhesives & Sealants
Construction Repair and Rehabilitation Chemicals Market
Adhesives & Sealants
Soft Skin Adhesives Market