
 Germany Sealants Market | 2026-2036
Germany Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Sealants Market Foresight
Automotive bonding is expanding as vehicle manufacturers shift toward multi-material body-in-white assemblies requiring structural adhesion. Henkel AG & Co. KGaA leverages its engineering adhesives portfolio to dominate OEM specification lists for crash-durable bonding. Sika AG anchors its position through polyurethane systems calibrated to German automaker durability standards. Wacker Chemie AG specializes in silicone technologies that sustain performance across thermal cycling ranges critical to electric vehicle battery enclosures.
Germany sealants are polymeric compounds formulated to fill gaps, prevent fluid ingress, and maintain structural integrity under mechanical stress, thermal cycling, and chemical exposure; typical specifications include elongation-at-break exceeding 400% for polyurethane construction grades and Shore A hardness between 20 and 60 for automotive applications. Silicone sealants lead volume share in construction joints due to proven UV resistance and movement accommodation in facade engineering. Polyurethane competes aggressively in automotive bonding where tensile-shear strength above 10 MPa meets crashworthiness requirements. Acrylic formulations occupy the fastest-growing niche in packaging sealing as food packaging firms seek solvent-free curing compatible with recycled substrate streams.
KBA vehicle-type approval frameworks and REACH chemical registration requirements shape formulation chemistry decisions across German sealant producers. The EU F-Gas Regulation and national Bauordnung building codes constrain solvent content and fire-performance classifications respectively, filtering market access toward compliant suppliers. Stakeholders must monitor evolving battery enclosure sealing specifications from German OEMs and anticipate how the EU AI Act's product liability extensions might redefine quality assurance documentation for automated dispensing systems.
Market Dynamics
German sealant producers face intensifying formulation pressure as the EU F-Gas Regulation and national Bauordnung codes tighten simultaneously, forcing chemistry redesigns across polyurethane and silicone product lines while OEMs demand crash-durable bonding specifications for electric vehicle platforms.
Growth Catalysts
- Automotive Lightweighting Mandates:Multi-material body-in-white assemblies at BMW, Mercedes-Benz, and Volkswagen plants require structural adhesives replacing mechanical fasteners, pulling advanced polyurethane systems into specification lists.
- REACH Chemical Registration:Pre-registered substance dossiers under ECHA guidelines provide compliant German suppliers with preferred-supplier status versus importers facing registration backlogs.
- Bavaria Automotive Corridor Concentration:Dense clustering of OEM final assembly and tier-1 component plants around Munich and Ingolstadt creates localized demand pull for just-in-time sealant logistics.
Market Restraints
- MDI and Polyol Feedstock Volatility:Polyurethane sealant margins compress when isocyanate and polyol pricing spikes, with German producers lacking backward integration into petrochemical feedstocks.
- Silicone Precursor Supply Concentration:Methylchlorosilane capacity clusters in China and Germany's Wacker Chemie AG facilities, creating single-source vulnerability for domestic formulators.
- Technical Limitation in Battery Thermal Management:Current silicone grades face performance ceilings above 180°C continuous operation, constraining sealing solutions for next-generation 800V EV architectures.
Strategic Opportunities
- North Rhine-Westphalia Construction Belt Retrofit Wave:Aging commercial building stock in Cologne-Düsseldorf corridor drives demand for high-movement facade sealants meeting EnEV energy efficiency standards.
- EU Green Deal Public Procurement:Federal and state infrastructure tenders now mandate environmental product declarations, advantaging domestic suppliers with verified lifecycle data.
- UV-LED Curing Convergence:Combination of acrylic resin chemistry with UV-LED curing hardware enables solvent-free packaging sealant lines running at speeds matching conventional thermal systems.
Industry Challenges
- Formulation Chemist Talent Scarcity:German universities produce insufficient polymer science graduates versed in both silicone crosslinking chemistry and automotive OEM specification protocols.
- EV Battery Enclosure Certification Timelines:KBA type-approval for new sealant grades in crash-critical battery pack applications extends 18-24 months, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Sealants Market |
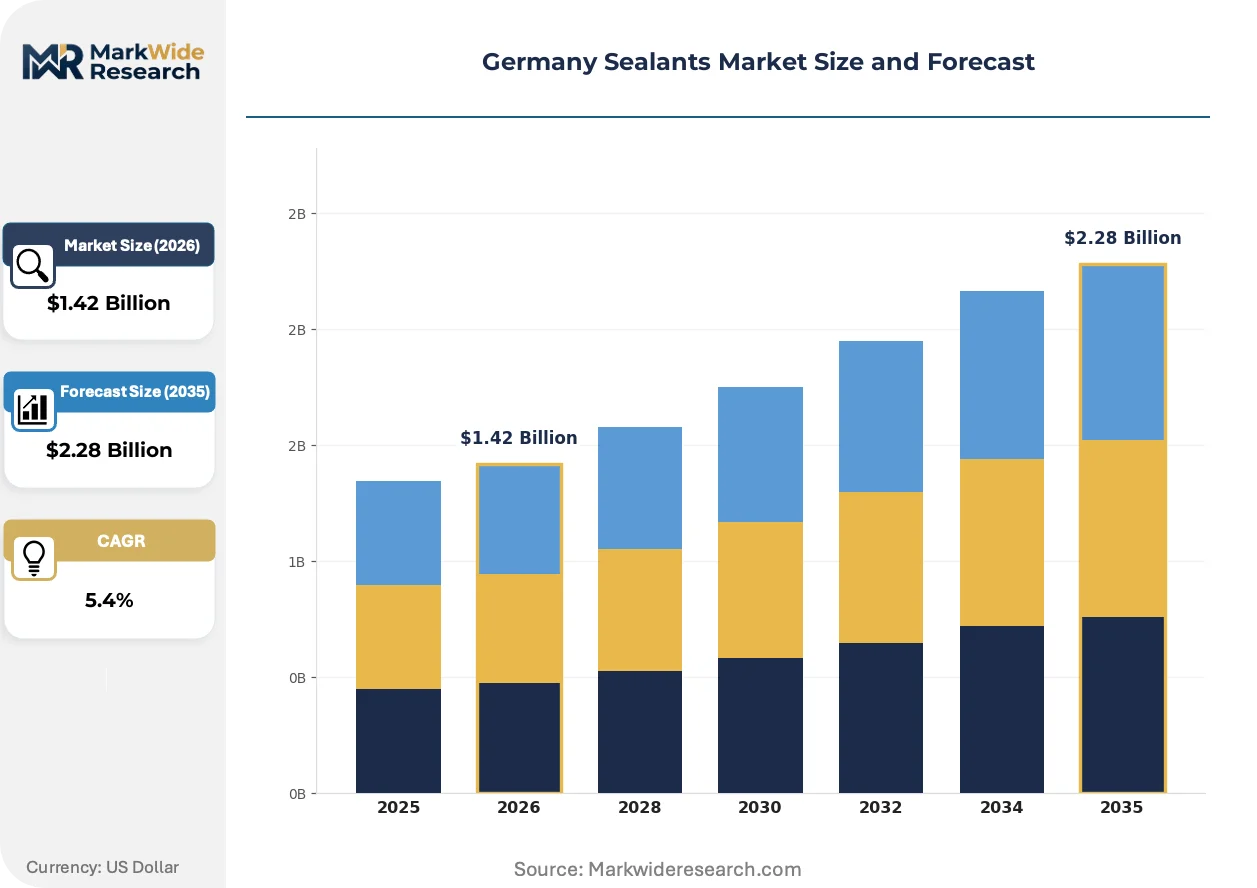
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silsesquioxane, Polyurethane, Silicone, Acrylic, Butyl, Polysulfide Application: Construction Joints, Automotive Bonding, Aerospace Assembly, Electrical Insulation, Marine Coatings, Packaging Sealing End User: Building Contractors, Vehicle Manufacturers, Aircraft Assemblers, Electronics Producers, Shipbuilders, Food Packaging Firms Packaging Type: Tubes, Cartridges, Bulk Drums, Pails, Sachets, Buckets |
| Companies Covered | Henkel AG & Co. KGaA, Sika AG, 3M, H.B. Fuller Company, Dow, Wacker Chemie AG, Arkema, Soudal Holding N.V., Jowat SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Sealants Market Shifts & Advancements
Automation of dispensing systems and real-time viscosity monitoring are compressing production cycle times while regulatory pressure on fluorinated compounds forces chemistry reinvention across German manufacturing facilities.
Robotic sealant dispensing is automating bead placement accuracy to within 0.1 millimeter tolerance in automotive final assembly lines. BMW's Leipzig and Regensburg plants have retrofitted 40% of body shop stations with vision-guided application systems since 2022. This automation is compressing labor content per vehicle while reducing material waste from over-application.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon propellants in aerosol sealants is forcing propellant substitution toward compressed gas and hydrocarbon alternatives. German aerosol formulators face reformulation costs exceeding EUR 500,000 per product line for flammability testing and stability validation. Construction-grade silicone aerosols are most affected, with producers accelerating pump-dispensed paste packaging to bypass propellant constraints entirely.
Specification-led procurement now dominates German automotive tier-1 buying, with engineering teams mandating approved-product lists rather than sourcing departments negotiating spot purchases. Henkel and Sika hold dual-source positions on most German OEM adhesive specification sheets, freezing out smaller competitors lacking crash-test validation data. This concentration is most visible in battery enclosure bonding, where thermal runaway containment requirements demand supplier liability coverage exceeding EUR 50 million per incident.
Germany Sealants Market Segmentation
German sealant procurement patterns diverge sharply across product chemistries and end-use specifications, with automotive OEMs and construction contractors driving incompatible performance requirements. Understanding these segment boundaries clarifies why formulation specialization dominates competitive strategy.
Product Type:
Supply concentration tilts toward silicone and polyurethane chemistries where German producers command captive methylchlorosilane and isocyanate conversion capabilities.
- Silicone:Crosslinked polydimethylsiloxane networks deliver UV stability and thermal cycling resistance from -50°C to 200°C. Demand concentrates in Bavaria's automotive corridor for electric vehicle battery enclosure sealing, constrained by precursor supply clustering at Wacker Chemie AG facilities. Silicone absorbs the bulk of installed capacity; acrylic is expanding most quickly.
- Polyurethane:Isocyanate-terminated prepolymers cure to elastomers with tensile-shear strength exceeding 10 MPa. North Rhine-Westphalia construction contractors specify these grades for high-movement facade joints meeting EnEV thermal bridging standards.
- Acrylic:Water-based or solvent-free emulsions cure through moisture evaporation or UV-LED initiation, compatible with recycled packaging substrates.
- Butyl:Isobutylene-isoprene copolymers provide permanent tack and vapor barrier performance in curtain wall secondary seals.
- Polysulfide:Liquid polymer systems with thiol terminal groups accommodate extreme joint movement in airport runway and bridge applications.
- Silsesquioxane:Hybrid organic-inorganic frameworks offer nanoscale thermal stability for aerospace composite bonding.
Polyurethane and silicone together command production line priority; silsesquioxane is climbing the fastest on aerospace qualification timelines.
Application:
Cost tier stratification separates specification-grade automotive bonding from commodity construction joint compounds.
- Automotive Bonding:Structural adhesives replace mechanical fasteners in multi-material body-in-white assemblies at BMW, Mercedes-Benz, and Volkswagen plants. Crash-durable formulations require KBA type-approval extending 18-24 months.
- Construction Joints:High-movement facade sealants accommodate thermal expansion in Cologne-Düsseldorf commercial retrofit stock. Bavaria's building contractors favor silicone grades for UV-exposed curtain wall applications.
- Packaging Sealing:UV-LED curable acrylic systems enable solvent-free lines running at thermal-cure speeds for food packaging firms.
- Electrical Insulation:Silicone potting compounds protect power electronics from thermal cycling and moisture ingress.
- Aerospace Assembly:Polysulfide and silsesquioxane grades meet flammability and outgassing specifications for aircraft primary structure.
- Marine Coatings:Polyurethane and polysulfide systems provide elastomeric waterproofing for ship deck sealing.
Construction joints absorb the bulk of volume throughput; packaging sealing is gaining share fastest on sustainability mandates.
End User:
Customer type determines procurement modality, with vehicle manufacturers enforcing approved-product lists versus construction contractor spot purchasing.
- Vehicle Manufacturers:Engineering teams at German OEMs mandate dual-source specifications from Henkel and Sika, freezing out competitors lacking crash-test validation data.
- Building Contractors:North Rhine-Westphalia facade specialists procure through distributor networks, prioritizing just-in-time availability over brand loyalty.
- Food Packaging Firms:Recycled substrate compatibility drives solvent-free acrylic adoption.
- Electronics Producers:Thermal management requirements pull silicone potting compounds for power module encapsulation.
- Aircraft Assemblers:EASA certification requirements constrain supplier pools to established aerospace adhesive specialists.
- Shipbuilders:Meyer Werft and other German yards specify polysulfide deck sealants for cruise vessel construction.
Vehicle manufacturers absorb the bulk of R&D-directed capacity; food packaging firms are expanding most quickly.
Packaging Type:
Volume scale separates bulk industrial supply from precision dispensing formats.
- Cartridges:310ml and 600ml foil-wrapped sausages dominate construction site dispensing for facade and interior joint applications.
- Bulk Drums:200-liter containers feed automated dispensing systems at automotive OEM body shops.
- Tubes:Small-format retail packaging serves DIY and maintenance repair operations.
- Pails:Mid-volume containers suit flooring and waterproofing contractors.
- Sachets:Single-use portions enable field repair kits and sample distribution.
- Buckets:Large-opening containers facilitate trowel-applied construction sealants.
Bulk drums absorb the bulk of automotive throughput; sachets are expanding most quickly on maintenance logistics optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grunderzentrum Bayern's innovation subsidies cluster sealant R&D around Munich-Ingolstadt automotive corridors, concentrating formulation talent and pilot-scale production facilities within tax-advantaged zones.
Bavaria
BMW and Audi assembly plants in Munich and Ingolstadt pull structural polyurethane adhesives for multi-material body-in-white construction. KBA type-approval frameworks govern crash-durable bonding specifications. The Ingolstadt supplier park hosts just-in-time sealant logistics operations serving Audi's electric vehicle platforms.
North Rhine-Westphalia
Cologne-Düsseldorf commercial retrofit stock drives high-movement facade sealant demand meeting EnEV thermal bridging standards. Bauordnung building codes constrain solvent content and fire-performance classifications. Düsseldorf-based distributors maintain construction-grade silicone inventories for Rhine-Ruhr contractor networks.
Baden-Württemberg
Mercedes-Benz Sindelfingen and Porsche Zuffenhausen facilities specify crash-durable adhesives for aluminum-intensive vehicle architectures. REACH chemical registration requirements filter supplier pools toward ECHA-compliant domestic formulators. Stuttgart's engineering services cluster supports OEM specification development for battery enclosure bonding.
Lower Saxony
Volkswagen Wolfsburg headquarters anchors procurement of assembly-line sealants for high-volume production runs. The EU F-Gas Regulation's propellant phasedown affects aerosol packaging formats used in aftermarket distribution. Braunschweig technical universities supply polymer science graduates to regional adhesive laboratories.
Hesse
Frankfurt-Rhine-Main logistics hubs facilitate bulk chemical distribution to sealant compounders across central Germany. EU Green Deal public procurement mandates environmental product declarations for federal infrastructure tenders. Offenbach specialty chemical operations supply methylchlorosilane intermediates to downstream formulators.
Germany Sealants Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with automotive OEMs enforcing approved-product lists while construction contractors procure through distributor networks. The vendor base concentrates around three strategic archetypes: diversified chemical conglomerates with captive silicone feedstock, construction-focused system suppliers with facade engineering expertise, and automotive adhesive specialists with crash-test validation capabilities. Competitive moves center on specification-list penetration at German OEMs and reformulation investments to meet F-Gas Regulation compliance deadlines.
Within the diversified chemical tier, Henkel AG & Co. KGaA and Wacker Chemie AG occupy positions reflecting distinct feedstock strategies—Henkel through engineered adhesives portfolios and Wacker through captive methylchlorosilane production. Sika AG exemplifies the construction-specialist archetype with polyurethane systems calibrated to German building codes. These three anchors illustrate how competitive positioning follows chemistry ownership and end-use certification depth rather than scale alone.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Sika AG |
| 3M |
| H.B. Fuller Company |
| Dow |
| Wacker Chemie AG |
| Arkema |
| Soudal Holding N.V. |
| Jowat SE |
| Others |
Supply & Pricing Matrix
MDI and polyol commodity indices cascade through German sealant supply chains, compressing margins at polyurethane formulators while concentrating pricing power among producers with captive methylchlorosilane supply. This feedstock volatility stratifies procurement tiers: automotive OEMs absorb premium pricing for KBA-certified grades, while construction contractors face spot-market exposure on standard silicone cartridges.
Pricing Analysis
Lead-time premiums reward just-in-time logistics contracts with Bavarian OEMs, while spot inventory liquidations discount standard construction grades through Rhine-Ruhr distributor networks. Pricing stratifies across specification-grade automotive bonding, certified construction facade systems, and commodity DIY cartridges. Cost compression in commodity tiers intensifies because of Chinese import competition and energy-intensive European production. Building contractors exhibit highest price sensitivity, demanding distributor price-matching; vehicle manufacturers prioritize specification compliance over unit cost.
Supply Chain Analysis
Silicone precursor supply rests on Wacker Chemie AG's Burghausen facilities and concentrated Chinese methylchlorosilane capacity, creating single-source vulnerability for domestic formulators. Isocyanate feedstocks draw from German and Belgian petrochemical complexes; polyols source from Dutch and Polish polyether producers. Tariff exposure on Chinese silicone intermediates threatens margin stability at mid-tier compounders. Distribution runs through construction chemical distributors in North Rhine-Westphalia and direct OEM supply contracts in Bavaria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capacity constraints on methylchlorosilane and isocyanate feedstocks prop pricing power for integrated producers, while non-integrated formulators face persistent margin compression. Supply scarcity favors asset-heavy incumbents with upstream chemical ownership.
For Market Incumbents: Cement specification-list dominance at BMW, Mercedes-Benz, and Volkswagen by accelerating KBA crash-test validation for battery enclosure grades. Deepen backward integration into silicone precursor production to offset Chinese supply volatility. Prioritize R&D investment in 800V thermal management formulations before next-generation EV architectures lock in competitor specifications. For New Entrants and Emerging Players: E-commerce platform routes into construction contractor procurement bypass entrenched distributor relationships in the Cologne-Düsseldorf corridor. Target food packaging sealants as the most penetrable segment: sustainability mandates favor solvent-free acrylic formulations where incumbent certification advantages remain weakest. Pursue UV-LED curing equipment partnerships to differentiate on line-speed compatibility. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier polyurethane compounders in North Rhine-Westphalia facing feedstock margin squeeze but holding EnEV-compliant formulation libraries. Five-to-ten-year viability hinges on successful EV battery enclosure qualification timelines. Watch KBA type-approval backlog clearance rates as the inflection signal for revenue recognition acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methylchlorosilane | Wacker Chemie AG's captive supply anchors pricing power against Chinese import volatility. |
| KBA Battery Enclosure Certification | Crash-test validation locks Henkel and Sika into dual-source positions at German OEMs. |
| UV-LED Curing Platform Partnership | Acrylic sealant lines matching thermal-cure speeds capture food packaging sustainability mandates. |
| Construction Distributor Channel Control | Rhine-Ruhr network ownership secures just-in-time availability premiums from facade contractors. |
| EU F-Gas Regulation Compliance Investment | Aerosol propellant reformulation costs filter market access toward capitalized domestic suppliers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with polyurethane plant managers, automotive Tier 1 procurement leads, construction chemical distributors, and ECHA regulatory affairs specialists. Bottom-up triangulation against top-down macroeconomic indicators validated volume estimates across silicone, polyurethane, and acrylic chemistry segments.
Granularity-level modeling deployed product-type, application, end-user, and packaging-format dimensions at the SKU level across the projection horizon. CAGRs derived from trend-line extrapolation of automotive lightweighting adoption curves and EnEV retrofit cycle timing. Forecast inputs incorporated KBA type-approval pipeline data and EU Green Deal procurement mandate implementation schedules.
Inputs from ECHA substance dossiers and KBA approval registries were available through the study window; gaps in proprietary OEM specification timelines introduce uncertainty bands around battery enclosure segment projections. Forecasts reflect documented assumptions on EV platform rollout pacing and F-Gas Regulation enforcement intensity. Regulatory amendment triggers and feedstock price volatility spikes warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Wood Adhesives and Binders Market
Adhesives & Sealants
Asia-Pacific Cyanoacrylate Adhesives Market
Adhesives & Sealants
Global Construction Adhesives Market
Adhesives & Sealants
Cold Seal Adhesives Market
Adhesives & Sealants
South America Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Asia-Pacific Epoxy Adhesive Market
Adhesives & Sealants
Spain Adhesives Market
Adhesives & Sealants
Global Ethyl Methacrylate (97-63-2) Market
Adhesives & Sealants
Global Methyl Methacrylate (MMA) Adhesive Market
Adhesives & Sealants
Europe Reactive Adhesives Market
Adhesives & Sealants
Electric Vehicle Adhesives Market
Adhesives & Sealants
Asia-Pacific Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Carpet Adhesive Market
Adhesives & Sealants
Global Vascular Sealant Market
Adhesives & Sealants
Malaysia Sealants Market
Adhesives & Sealants
Capillary Underfill Material Market