
 France Sealants Market | 2026-2036
France Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
France Sealants Market Foresight
Hybrid silyl-modified polymer chemistry is recalibrating cost-performance trade-offs across mid-tier construction applications. Sika AG leverages its integrated mortar-adhesive-sealant portfolio to dominate specification-driven infrastructure channels. Arkema Group anchors its position through advanced acrylic and specialty polymer R&D operations centered in France.
Sealants are elastomeric compounds formulated to fill joints and gaps while maintaining adhesion and flexibility across temperature cycles, typically specified by Shore A hardness, elongation at break, and movement accommodation factors. Silicone formulations command premium positioning in structural glazing and weathersealing due to UV stability and 50-year service life ratings; polyurethane competes aggressively in flooring and civil engineering where modulus and paintability drive selection. Acrylic segments serve interior caulking and decorator markets with faster cure and lower material cost, though movement capability constraints limit exterior exposure applications.
France's national building code and RE2020 thermal regulation framework, administered by the Ministry of Ecological Transition, mandate reduced carbon footprints in construction materials and drive specification shifts toward low-emission sealant categories. ECHA REACH compliance and forthcoming CSRD corporate sustainability reporting obligations tighten chemical disclosure and lifecycle transparency requirements across the supply chain. Stakeholders must monitor regulatory calibration between performance standards and environmental thresholds to anticipate formulation investment cycles.
Market Dynamics
RE2020 thermal regulation is compressing specification cycles across French construction, forcing reformulation investments toward low-carbon chemistries before cost parity with conventional systems has stabilized.
Growth Catalysts
- Île-de-France construction density:Paris-area renovation and new-build activity channels premium sealant volumes through concentrated contractor networks, reducing customer acquisition costs for specification-grade suppliers.
- ECHA REACH chemical disclosure mandates:Lifecycle transparency requirements accelerate substitution of solvent-based systems, opening market share for compliant waterborne and hybrid formulations.
- Hybrid silyl-modified polymer platforms:These chemistries bridge silicone performance with polyurethane economics, enabling mid-tier contractors to upgrade weathersealing specifications without full premium cost exposure.
Market Restraints
- Petrochemical feedstock volatility:Polyurethane and silicone precursor costs swing with crude-linked propylene and methanol markets, compressing margin predictability for formulators without backward integration into monomer supply.
- Specialty additive supply concentration:Tin catalysts and platinum crosslinkers for condensation-cure silicones source predominantly from Chinese and German chemical clusters, exposing French compounders to single-point disruption risk.
- Acrylic movement capability ceiling:±12.5% joint movement accommodation limits exterior durability validation, restricting specification in structural glazing and expansion-joint applications regardless of cost advantage.
Strategic Opportunities
- Auvergne-Rhône-Alpes industrial corridor:Lyon-Grenoble manufacturing and logistics infrastructure expansion creates underpenetrated demand for high-temperature industrial gasketing and transportation assembly sealants.
- CSRD corporate sustainability reporting:Scope 3 emissions disclosure obligations push construction primes toward certified low-carbon sealant categories, generating specification pull for bio-based and recycled-content formulations.
- Prefabricated building envelope modules:Offsite construction growth concentrates sealant application into factory-controlled conditions, enabling automated dispensing and quality systems that reduce field-performance risk.
Industry Challenges
- Formulation chemist scarcity:Hybrid polymer and silicone chemistry expertise concentrates among retiring specialists, constraining R&D velocity for next-generation low-VOC systems.
- ETB certification timelines:European Technical Assessment pathways for novel sealant chemistries extend 18-24 months, delaying market entry for innovative formulations even after laboratory validation completes.
- Legacy substrate compatibility:Historic building renovation projects demand adhesion to oxidized metals and porous stone, requiring extensive substrate-specific testing that fragments product portfolios and inventory requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Sealants Market |
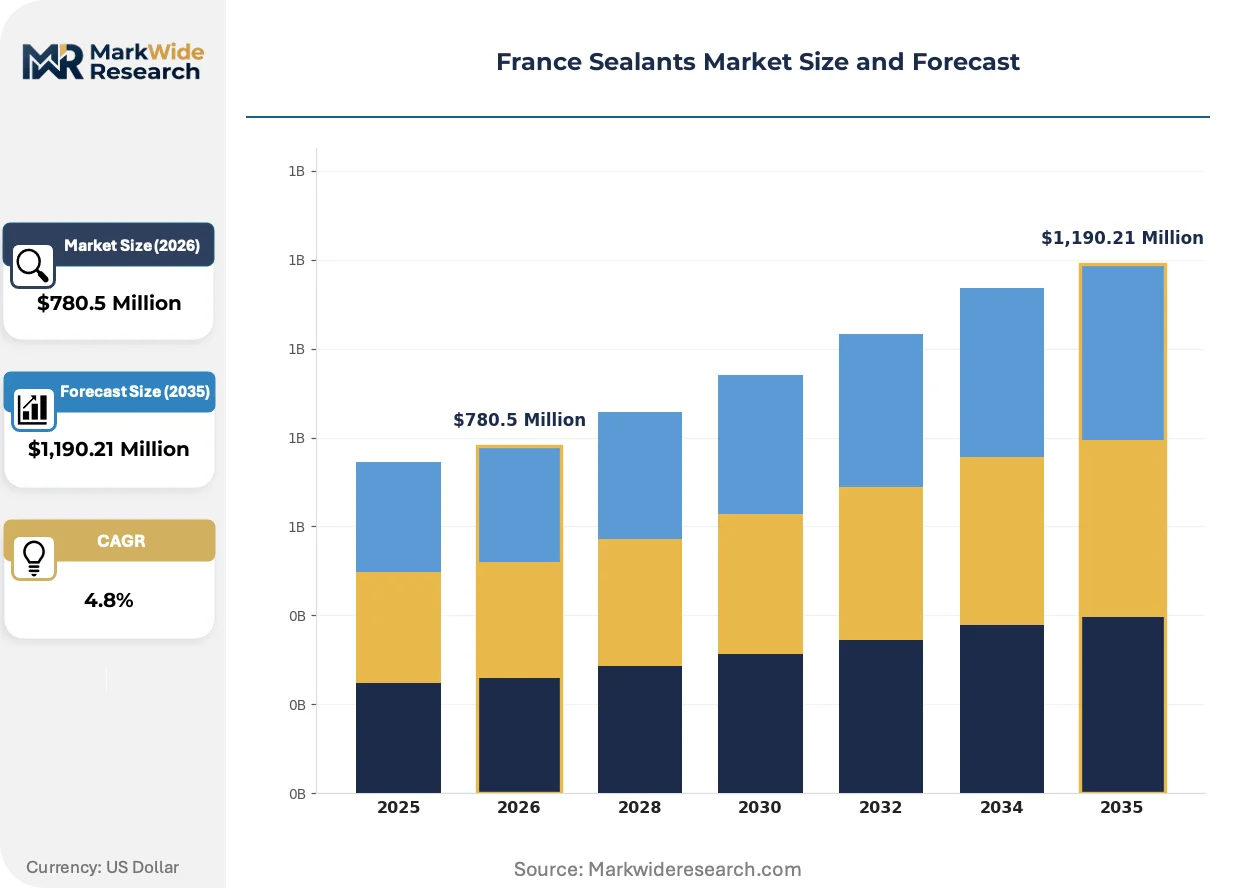
| Market Size in 2026 | $780.5 Million |
| Market Size in 2035 | $1,190.21 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, Polyurethane, Acrylic, Polysulfide, Butyl, Hot Melt End Use Industry: Construction & Infrastructure, Transportation Equipment, Marine Assembly, Electrical & Electronics, Industrial Manufacturing Form: Paste, Liquid, Foam, Tape, Gel Distribution Channel: Direct Sales, Distributors, Retailers, Online Platforms, Wholesalers |
| Companies Covered | Sika AG, Arkema Group, Henkel AG & Co. KGaA, 3M, Dow, Soudal Holding N.V., MAPEI S.p.A., RPM International Inc., CERMIX, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Sealants Market Shifts & Advancements
Formulation chemistry and procurement architecture are diverging sharply, with regulatory carbon thresholds forcing material reinvention while buyer consolidation reshapes channel economics.
Hybrid silyl-modified polymer chemistry is absorbing specification volume across mid-tier construction applications. Regional contractors in commercial envelope and flooring segments are specifying these platforms at accelerating rates. The technology is absorbing market space previously divided between premium silicones and cost-optimized polyurethanes, compressing the middle tier into a single dominant chemistry.
France's Ministry of Ecological Transition is tightening RE2020 carbon intensity thresholds for construction materials through 2030. The regulation forces sealant formulators to document embodied carbon and operational emissions across product lifecycles. Specification-grade silicone and polyurethane suppliers serving Île-de-France commercial projects are accelerating bio-based feedstock substitution to maintain eligibility on public and prime-contractor tenders.
Consolidation among French construction primes is compressing supplier rosters and extending payment terms. Mid-sized sealant distributors serving regional contractors face disintermediation pressure as national buying groups centralize procurement. The channel shift is most visible in Occitanie and Nouvelle-Aquitaine, where regional distributors are losing specification influence to manufacturer-direct technical sales teams aligned with consolidated contractor purchasing offices.
France Sealants Market Segmentation
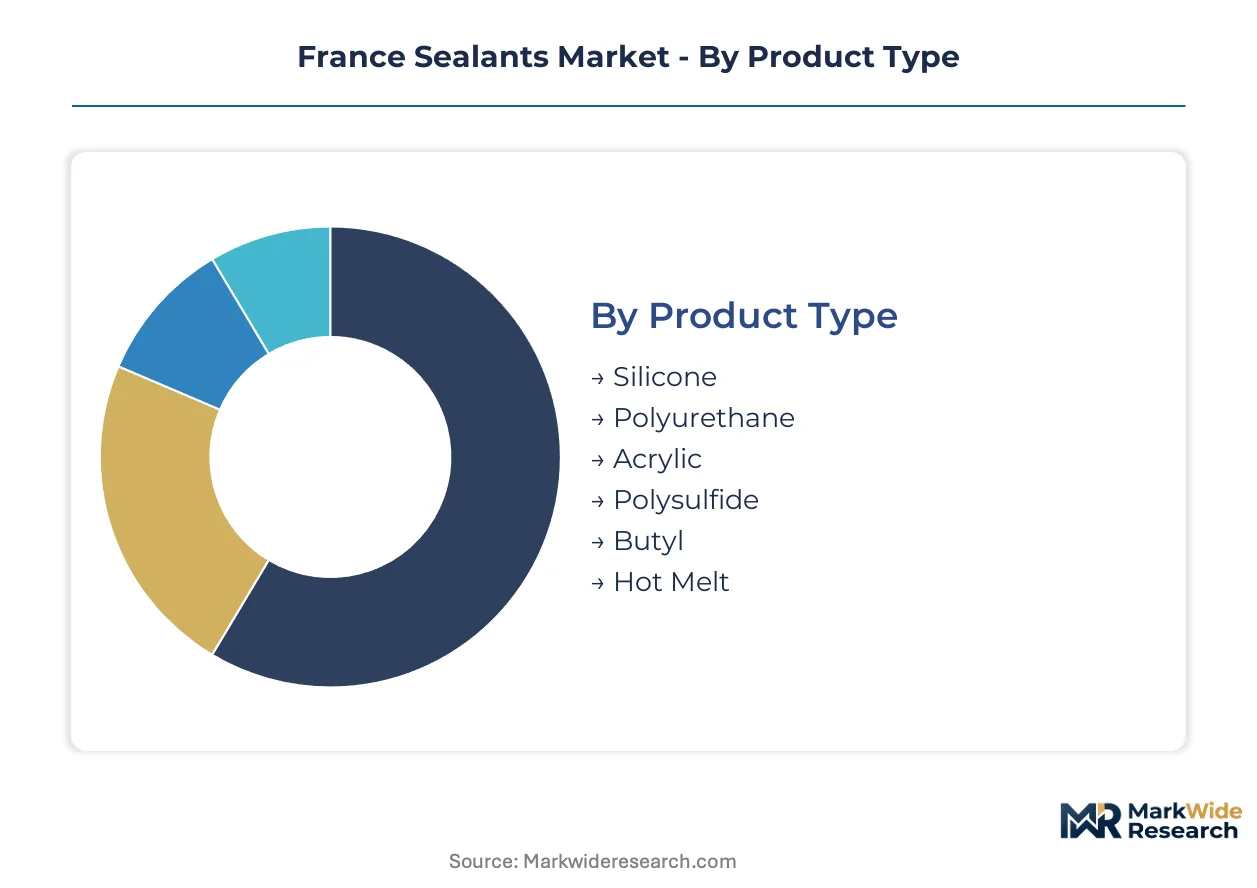
Segmentation in the France Sealants Market reveals how specification requirements, application environments, and procurement channels fragment demand across distinct performance tiers. Understanding these divisions enables suppliers to align formulation investments with the regulatory and operational pressures shaping each segment.
Product Type:
Technology selection in French construction and industrial applications tracks directly to movement accommodation requirements, UV exposure levels, and RE2020 carbon intensity thresholds.
- Silicone:Condensation-cure and addition-cure formulations deliver 50-year service life ratings with ±50% joint movement capability. Structural glazing specifications in Paris commercial towers absorb premium volumes, though platinum catalyst supply concentration creates formulation cost volatility.
- Polyurethane:Two-component systems dominate flooring and civil engineering where modulus control and paintability drive selection. Auvergne-Rhône-Alpes infrastructure corridors channel specification-grade demand, yet petrochemical feedstock swings compress margin predictability for non-integrated compounders.
- Acrylic:Waterborne emulsions serve interior caulking and decorator markets with rapid skin formation and lower material cost. Movement accommodation capped at ±12.5% restricts exterior structural applications regardless of cost advantage.
- Polysulfide:Jet-fuel-resistant formulations anchor aerospace and marine sealing specifications requiring chemical inertness.
- Butyl:Preformed tapes and solvent-based caulks concentrate in roofing membrane and vapor barrier applications.
- Hot Melt:Reactive polyurethane hot melts are gaining industrial assembly traction for bond-line speed and green strength.
Mature deployment sits with silicone in structural glazing and weathersealing. Newer deployment is concentrated in hybrid-modified polymer platforms bridging polyurethane economics with silicone performance.
End Use Industry:
Demand concentration across French end-use sectors reflects the divergence between public infrastructure procurement cycles and private industrial capital expenditure patterns.
- Construction & Infrastructure:Building envelope, flooring, and civil engineering specifications absorb the majority of volume. RE2020 thermal regulation and ETB certification pathways force reformulation investments toward low-carbon chemistries before cost parity stabilizes.
- Transportation Equipment:Automotive, rail, and aerospace assembly lines demand vibration-damping and NVH (noise, vibration, harshness) management. Lyon-Grenoble manufacturing clusters generate underpenetrated demand for high-temperature gasketing formulations.
- Marine Assembly:Submerged and weather-exposed sealing for commercial and leisure vessel construction concentrates in Atlantic and Mediterranean coastal yards.
- Electrical & Electronics:Potting and encapsulation specifications for EV battery modules and renewable energy infrastructure are climbing the fastest.
- Industrial Manufacturing:Process equipment, HVAC ductwork, and machinery assembly require chemical-resistant and high-temperature formulations.
Procurement consolidation among construction primes compresses supplier rosters in building applications. Industrial manufacturing retains fragmented sourcing with specification authority distributed across plant engineering teams.
Form:
Physical form selection determines application equipment requirements, cure conditions, and field-performance risk profiles across French installation environments.
- Paste:Thixotropic formulations enable vertical and overhead application without sag. Commercial facade remediation in Île-de-France channels high-viscosity silicone and hybrid volumes through contractor networks.
- Liquid:Self-leveling grades dominate flooring and civil engineering joints where gravity flow ensures void-free coverage. Automated dispensing systems in prefabricated envelope modules reduce field-performance risk.
- Foam:One-component polyurethane foams serve perimeter sealing and insulation-gap filling with expansion ratios driving yield economics.
- Tape:Preformed butyl and acrylic tapes accelerate installation speed in roofing and vapor barrier applications.
- Gel:Soft, conformable formulations address irregular substrates and vibration-prone electrical connections.
Manual application persists in renovation and small-scale construction. Factory-controlled dispensing is displacing field application in offsite building envelope manufacturing.
Distribution Channel:
Channel economics in France are restructuring around buyer consolidation and technical specification complexity.
- Direct Sales:Manufacturer technical teams engage prime contractors and specification authorities on large commercial and infrastructure projects. National buying group consolidation extends payment terms and compresses distributor margins.
- Distributors:Regional stockholding intermediaries serve mid-tier contractors with inventory availability and credit terms. Occitanie and Nouvelle-Aquitaine distributors are losing specification influence to manufacturer-direct teams.
- Retailers:Big-box and specialty trade outlets capture decorator, DIY, and small contractor demand for standard-grade acrylic and silicone cartridges.
- Online Platforms:Digital procurement is penetrating MRO (maintenance, repair, operations) replenishment and small-project specifications.
- Wholesalers:Volume aggregators supply secondary distributors and large regional contractors with palletized standard grades.
Specification-grade volume concentrates through direct technical sales. Standard-grade and consumable demand fragments across distributor, retail, and emerging digital channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France's ZAC des Docks de Saint-Ouen and other priority development zones channel premium sealant volumes through concentrated contractor networks, reducing customer acquisition costs for specification-grade suppliers while concentrating demand in Paris-area renovation and new-build activity.
Île-de-France
Paris commercial towers and facade remediation projects absorb structural glazing and weathersealing volumes at premium price points. The Ministry of Ecological Transition administers RE2020 thermal regulation mandates that force specification shifts toward low-carbon chemistries. La Défense business district and peripheral ZAC developments concentrate high-performance bonding system demand among national construction primes.
Auvergne-Rhône-Alpes
Lyon-Grenoble manufacturing clusters generate underpenetrated demand for high-temperature industrial gasketing and transportation assembly sealants. ECHA REACH compliance obligations tighten chemical disclosure requirements across regional chemical processing operations. Saint-Étienne logistics infrastructure expansion creates specification opportunities for flooring and civil engineering joint systems.
Provence-Alpes-Côte d'Azur
Mediterranean coastal yards concentrate marine assembly sealant demand for commercial and leisure vessel construction. The country's national building code mandates UV-stable formulations for extended service life in high-solar-exposure environments. Marseille port modernization and Toulon naval maintenance facilities channel specialty polysulfide and hybrid polymer volumes.
Hauts-de-France
Cross-border industrial corridors with Belgium absorb automotive and rail assembly sealant specifications for vibration-damping applications. CSRD corporate sustainability reporting obligations push manufacturing primes toward certified low-carbon sealant categories. Lille metropolitan logistics platforms and Dunkirk industrial zones concentrate demand for process equipment and HVAC ductwork formulations.
Nouvelle-Aquitaine
Atlantic coastal shipbuilding and offshore wind fabrication yards drive submerged and weather-exposed sealing specifications. Regional distributors serving mid-tier contractors face disintermediation pressure as national buying groups centralize procurement. Bordeaux metropolitan construction and Bayonne industrial maintenance operations fragment demand across standard-grade acrylic and silicone cartridges.
France Sealants Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with specification-grade channels consolidating around integrated mortar-adhesive-sealant portfolios while standard-grade markets fragment across regional distributors and retail outlets. Three archetypes dominate: integrated construction chemical conglomerates with backward control over monomer supply, regional European compounders leveraging proximity to ECHA regulatory processes, and specialty polymer innovators anchored in French R&D operations. Competitive moves concentrate on portfolio diversification into hybrid silyl-modified polymer platforms and geographic expansion through manufacturer-direct technical sales teams displacing traditional distribution.
Within the integrated construction chemical tier, Sika AG and MAPEI S.p.A. exemplify scale-driven positioning through specification-driven infrastructure channels. Arkema Group anchors the specialty polymer innovation vector with advanced acrylic and hybrid chemistry operations centered in France. Henkel AG & Co. KGaA occupies a position bridging industrial adhesive integration with consumer-facing retail distribution. These three represent distinct competitive postures: Sika AG exemplifies vertical construction chemical integration, Arkema Group represents materials science R&D concentration, and Henkel AG & Co. KGaA illustrates dual-channel market presence spanning specification-grade and standard-grade segments.
| Leading Market Players |
|---|
| Sika AG |
| Arkema Group |
| Henkel AG & Co. KGaA |
| 3M |
| Dow |
| Soudal Holding N.V. |
| MAPEI S.p.A. |
| RPM International Inc. |
| CERMIX |
| Others |
Supply & Pricing Matrix
Captive supply of platinum crosslinkers and tin catalysts anchors pricing power for integrated French silicone compounders while exposing non-integrated rivals to Chinese and German supply volatility. RE2020 carbon intensity documentation requirements and ECHA REACH disclosure mandates compress margin buffers across mid-tier polyurethane and acrylic segments, forcing specification-grade suppliers to absorb certification costs or cede share to backward-integrated competitors.
Pricing Analysis
Specification-grade silicone volumes command premium positioning against compressed margins in standard-grade acrylic and polyurethane tiers. Price differentiation rests on ETB certification status and RE2020 carbon intensity documentation, with certified low-carbon formulations extracting measurable premiums from Île-de-France construction primes. Cost compression in polyurethane feedstocks intensifies as propylene and methanol markets swing, squeezing non-integrated compounders. National buying groups exhibit lowest price sensitivity in structural glazing specifications, while regional distributors serving Occitanie and Nouvelle-Aquitaine renovation contractors face acute margin pressure.
Supply Chain Analysis
Formulation chemist scarcity in Lyon-Grenoble and Paris-area R&D clusters constrains production scaling for hybrid silyl-modified polymer platforms. Raw material sourcing draws from German chemical clusters for platinum catalysts, Chinese processors for tin crosslinkers, and domestic French petrochemical infrastructure for polyurethane precursors. Single-source vulnerability concentrates in specialty additive supply, with 18-24 month ETB certification timelines amplifying disruption risk. Distribution runs through manufacturer-direct technical sales teams for specification-grade volume, while standard-grade cartridges fragment across regional distributors and retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France sealants market is becoming a vertical-integration race as players pursue captive control over platinum and tin catalyst supply to defend margin structure against Chinese supply volatility.
For Market Incumbents: Deepen backward integration into specialty additive supply chains to neutralize single-source concentration risk from Chinese and German chemical clusters. Expand ETB certification capabilities to compress 18-24 month validation timelines for hybrid polymer innovations. Hybrid silyl-modified polymer platforms threaten traditional silicone-polyurethane segmentation; preemptive capacity positioning in Auvergne-Rhône-Alpes industrial corridors secures transportation assembly growth.
For New Entrants and Emerging Players: Bio-based sealant chemistry offers a technology-first wedge into CSRD-driven procurement at French construction primes. Target underpenetrated high-temperature gasketing demand in Lyon-Grenoble manufacturing clusters where incumbent presence remains thin. Prefabricated building envelope modules concentrate application into factory-controlled conditions; automated dispensing partnerships with offsite construction specialists accelerate specification traction without field-service infrastructure.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialty polymer innovators with captive French R&D operations and ETB certification track records. Long-term viability hinges on bio-based feedstock substitution capabilities as RE2020 carbon thresholds tighten through 2030. Acquisition targets should demonstrate hybrid chemistry expertise and regional distributor relationships in Occitanie or Nouvelle-Aquitaine. Monitor ETB certification backlog duration as inflection indicator for formulation velocity and market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Supply | Captive platinum and tin sourcing neutralizes Chinese supply concentration risk for French compounders. |
| ETB Certification Acceleration | Compressed validation timelines enable faster market entry for RE2020-compliant hybrid formulations. |
| Bio-Based Feedstock Substitution | Carbon intensity documentation satisfies CSRD disclosure obligations for construction prime procurement. |
| Automated Dispensing Partnerships | Factory-controlled application in prefabricated modules reduces field-performance risk and warranty exposure. |
| Auvergne-Rhône-Alpes Capacity Positioning | Proximity to Lyon-Grenoble transportation manufacturing clusters captures high-temperature gasketing demand. |
Research Methodology
Independent corroboration across formulation chemists at French compounders, procurement leads at Île-de-France construction primes, and distribution channel partners in Occitanie underwrites the qualitative findings. Primary interviews engaged technical R&D directors, ETB certification specialists, and regional contractor purchasing managers alongside secondary validation through ECHA REACH filings, French Ministry of Ecological Transition regulatory notices, and customs trade data for silicone and polyurethane precursor flows. Bottom-up segmentation modeling triangulates against top-down construction spending projections.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models demand by product chemistry (silicone, polyurethane, acrylic, hybrid), end-use industry (construction, transportation, marine, electrical), physical form (paste, liquid, tape), and distribution channel (direct sales, distributor, retail). CAGRs derive from regression against construction permit data, industrial production indices, and regulatory implementation timelines. Forecast inputs incorporate RE2020 carbon threshold calibration and ETB certification velocity assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under petrochemical feedstock volatility or Chinese catalyst export restrictions. Material deviation in RE2020 enforcement intensity, ETB backlog duration, or construction prime consolidation pace warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Gasket and Seal Material Market
Adhesives & Sealants
Epoxy Glue Market
Adhesives & Sealants
Latex Binders Market
Adhesives & Sealants
High Performance Adhesives Market
Adhesives & Sealants
Global EVA Adhesives Market
Adhesives & Sealants
Soft Skin Adhesives Market
Adhesives & Sealants
Dibutyl Maleate (DBM) Market
Adhesives & Sealants
Global Epoxy Adhesive Market
Adhesives & Sealants
Tobacco and Cigarette Adhesives Market
Adhesives & Sealants
Joint Sealants Market
Adhesives & Sealants
Wood Glue Market
Adhesives & Sealants
North America Adhesives and Sealants Market
Adhesives & Sealants
Wood to Metal Glue Market
Adhesives & Sealants
Leather Glue Market
Adhesives & Sealants
Asia-Pacific Cyanoacrylate Adhesives Market
Adhesives & Sealants
Pressure Sensitive Adhesives (PSA) Market