
 Global Spray Adhesive Market | 2026-2036
Global Spray Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Global Spray Adhesive Market Foresight
Aftermarket service revenue for spray adhesive application equipment is narrowing as OEMs bundle consumables with capital sales. Henkel leverages its construction chemical distribution network to sustain European industrial penetration. H.B. Fuller anchors North American packaging demand through hot melt spray technology leadership. 3M competes on aerosol platform breadth across consumer and professional segments.
Spray adhesive denotes an atomized bonding agent delivered through pressurized canisters or spray guns, typically formulated with synthetic elastomers, acrylic resins, or polyurethane prepolymers in solvent or water carriers, achieving tack-free times under sixty seconds for industrial throughput. The technology serves primary industrial purposes in temporary positioning, permanent lamination, and porous substrate bonding across manufacturing lines. Water-based aerosol formulations now lead technology segment growth as VOC regulations tighten across industrialized economies. Solvent-based systems retain margin concentration in aerospace and marine applications where cure speed and environmental resistance override compliance costs. Polyurethane product types capture expanding share in furniture and textile lamination where flexibility and heat resistance differentiate performance tiers.
The US EPA regulates VOC emissions from consumer and industrial adhesive products through 40 CFR Part 59, while the EU REACH framework restricts hazardous substance content in spray formulations. China's MEE enforces parallel GB standards on atmospheric pollutant discharge from coating operations. Stakeholders must monitor evolving state-level amendments to EPA rules and emerging carbon border adjustment mechanisms that will reshape raw material sourcing decisions.
Market Dynamics
The spray adhesive market pivots on regulatory pressure forcing solvent-to-water formulation transitions, with automotive OEMs simultaneously demanding faster-cure bonding systems for lightweight vehicle assembly lines.
Growth Catalysts
- EU REACH VOC limits:Industrial buyers across Germany and France accelerate water-based aerosol procurement to preempt compliance deadlines, expanding addressable market for low-emission suppliers.
- Automotive interior lamination:Seat assembly and headliner bonding operations in Stuttgart and Wolfsburg clusters consume high-tack spray systems for foam-to-fabric attachment cycles under ninety seconds.
- Polyurethane flexibility premium:Furniture manufacturers in North Carolina and Guangdong specify PU spray adhesives for upholstery applications requiring heat resistance above 80°C.
Market Restraints
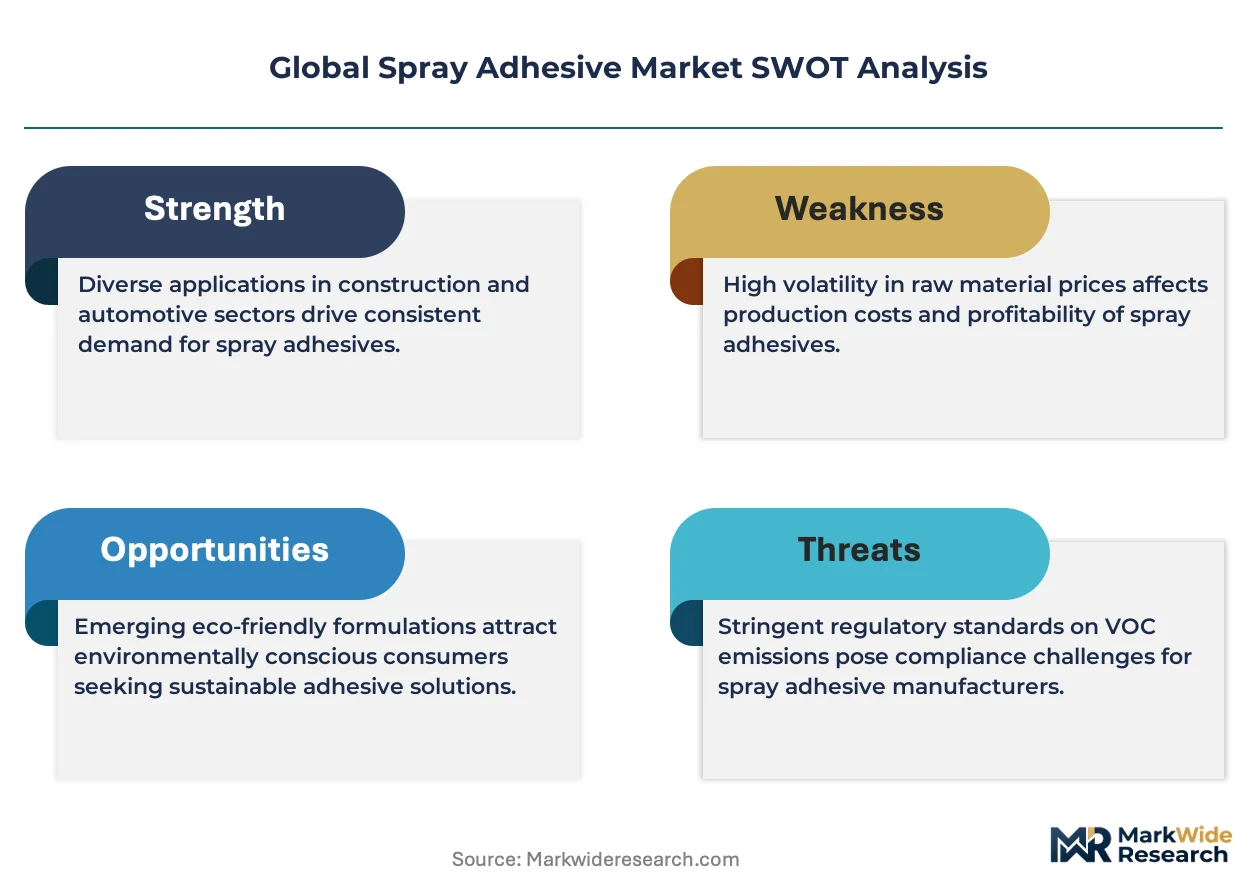
- Petrochemical feedstock volatility:Propylene and isocyanate price swings compress formulation margins, particularly for small-batch custom adhesive producers.
- Solvent-based aerospace lock-in:FAA-certified aircraft interior bonding specifications retain MEK and toluene carriers, blocking water-based substitution in this high-margin segment.
- Technical cure-speed ceiling:Water-based systems require 15-30% longer open times versus solvent equivalents, constraining throughput in high-speed packaging lines.
Strategic Opportunities
- India construction chemical penetration:BIS certification alignment enables European and North American suppliers to access infrastructure and flooring adhesive demand in Mumbai and Delhi NCR.
- Hot melt spray convergence:Packaging converters combine reactive polyurethane hot melts with robotic spray applicators to eliminate compressed air systems and reduce energy intensity.
- China dual carbon policy:Provincial MEE enforcement of GB 37822 standards creates procurement preference for water-based systems in Jiangsu and Zhejiang manufacturing zones.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in rheology modification and aerosol propellant compatibility concentrates among aging technical workforces in Basel and Midland, Michigan.
- Legacy equipment retrofit costs:Existing solvent-optimized spray booths and recovery systems require capital replacement to handle water-based viscosity profiles and flash-off characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Spray Adhesive Market |
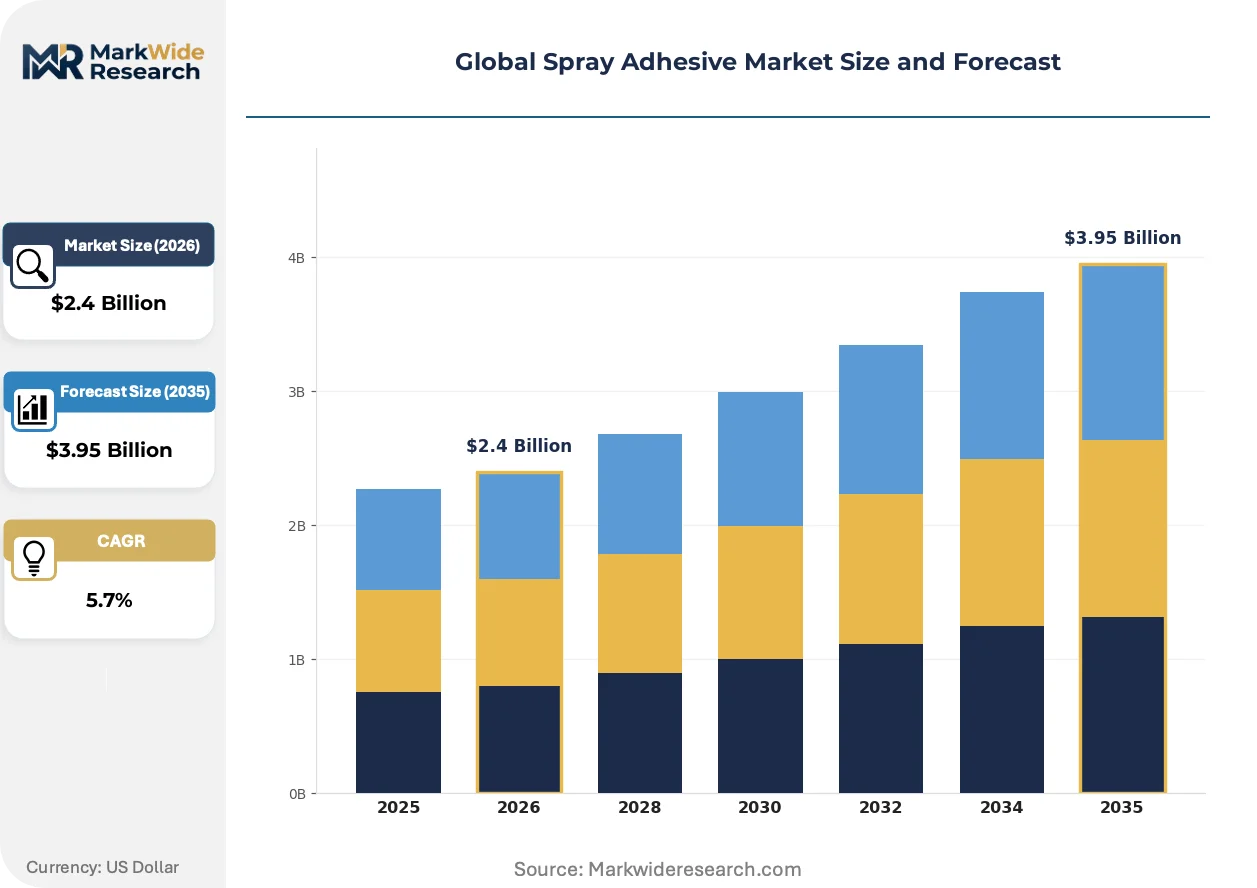
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.95 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Rubber-Based, Polyurethane, Silicone, Epoxy, Cyanoacrylate Technology: Aerosol, Non-Aerosol, Water-Based, Solvent-Based, Hot Melt, UV Cure Application: Packaging, Footwear, Furniture, Textile, Electronics, Paper & Printing End User Industry: Construction, Consumer Goods Manufacturing, Aerospace, Marine, Transportation, Electrical & Electronics |
| Companies Covered | 3M, Henkel, H.B. Fuller, Avery Dennison, Sika, Dow, Arkema, Illinois Tool Works, Bostik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Spray Adhesive Market Shifts & Advancements
Formulation chemistry and application hardware are decoupling from traditional solvent platforms, with regulatory compliance and automation compatibility now dictating R&D allocation across supplier laboratories.
Reactive hot melt polyurethane spray technology is migrating from packaging and woodworking into automotive interior assembly, where Tier 1 suppliers in Detroit and Stuttgart adopt cartridge-fed systems to eliminate compressed air infrastructure and reduce booth ventilation energy loads by forty percent versus conventional aerosol lines.
REACH Annex XVII restrictions on chlorinated solvents are compressing permissible formulation palettes for industrial maintenance adhesives, forcing specialty chemical divisions to requalify aerospace and marine bonding systems ahead of 2025 sunset dates, with German KBA type-approval processes creating bottlenecks for automotive OEM specification updates.
Equipment bundling is displacing standalone consumables procurement in North American industrial accounts, where packaging converters and furniture manufacturers negotiate multi-year adhesive supply agreements locked to capital equipment leases, compressing distributor margins and favoring suppliers with captive applicator manufacturing capabilities.
Global Spray Adhesive Market Segmentation
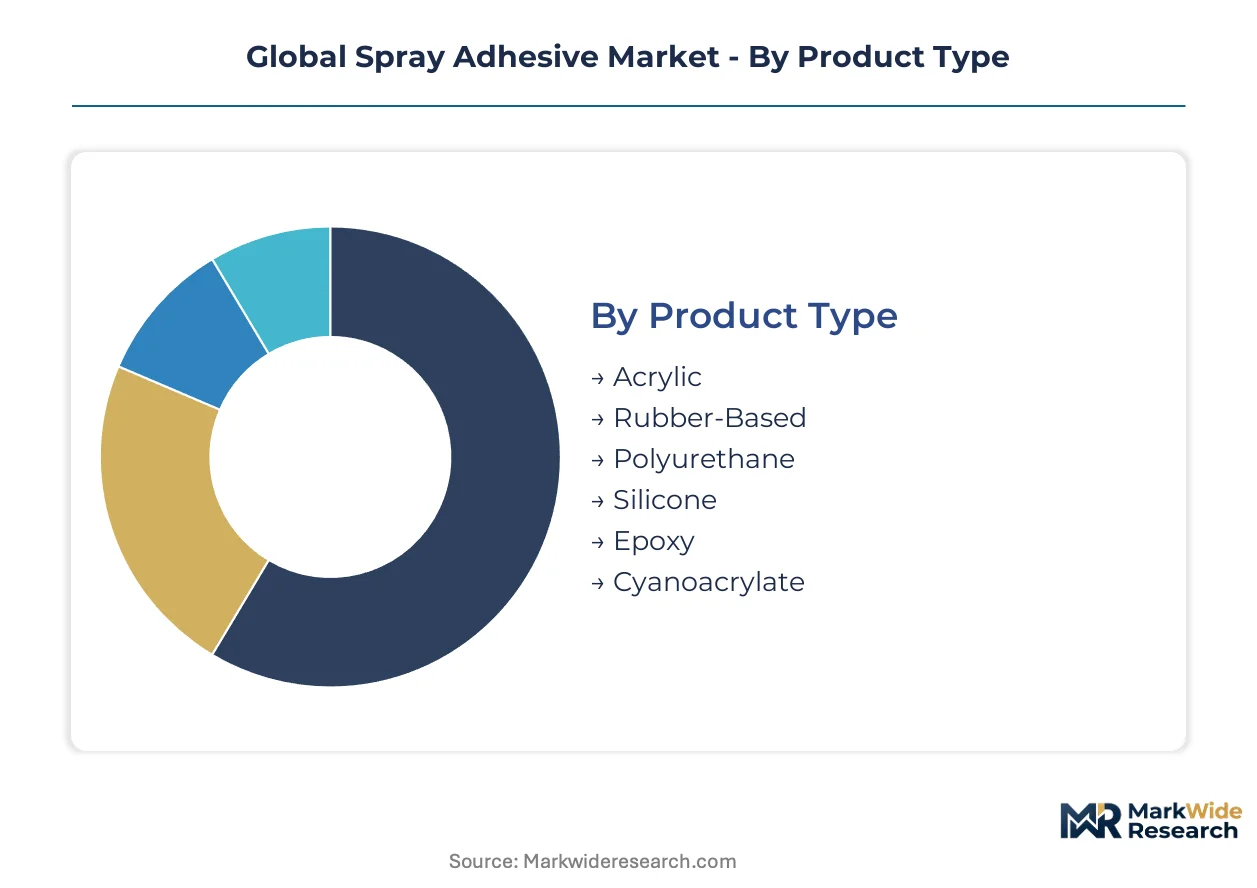
Spray adhesive segmentation reveals distinct turnover velocities across formulation chemistries, with automotive procurement cycles compressing specification timelines while aerospace certification extends product lifespans to decades. Understanding these cadence variations enables suppliers to align R&D pipelines with replacement-driven revenue versus long-tail maintenance contracts.
Product Type:
Cycle times vary dramatically by chemistry platform—polyurethane formulations refresh every 18-24 months as furniture OEMs iterate upholstery specifications, while epoxy systems remain locked for 8-10 years in aerospace structural bonding approvals.
- Acrylic:Water-dispersible copolymers dominate packaging and paper lamination where FDA indirect food contact compliance accelerates specification turnover. German automotive interior suppliers in Wolfsburg specify high-tack acrylics for headliner foam attachment requiring 90-second open times.
- Polyurethane:Prepolymer systems with isocyanate terminals deliver flexible bonds resistant to 80°C heat aging. North Carolina furniture manufacturers specify PU spray adhesives for upholstery applications where seam durability testing exceeds 50,000 cycles.
- Rubber-Based:Synthetic elastomer formulations retain share in marine decking and carpet installation where moisture resistance and initial grab outweigh cure speed requirements.
- Silicone:Room-temperature vulcanizing systems serve high-temperature electronics gasketing and aerospace firewall sealing applications.
- Epoxy:Two-component structural systems anchor composite bonding in FAA-certified aircraft interior assemblies where MEK carrier retention persists despite REACH pressure.
- Cyanoacrylate:Instant-bonding aerosols capture small-assembly electronics manufacturing in Shenzhen and Guadalajara clusters.
Acrylic formulations anchor the volume base while polyurethane gains share at the steepest rate.
Technology:
Cost tiers separate capital-intensive hot melt infrastructure from low-entry aerosol platforms, with water-based systems occupying the middle ground where regulatory compliance costs reshape total cost of ownership calculations.
- Water-Based:Acrylic and polyurethane dispersions in water carriers now lead procurement preference in EU automotive and construction verticals. REACH Annex XVII VOC limits force solvent-to-water transitions across German OEM supply chains.
- Hot Melt:Reactive polyurethane systems eliminate compressed air infrastructure and reduce booth ventilation energy loads by forty percent versus conventional aerosol lines. Detroit and Stuttgart Tier 1 suppliers adopt cartridge-fed robotic applicators for automotive interior assembly.
- Aerosol:Pressurized canister delivery retains consumer and light-industrial penetration where application flexibility outweighs throughput requirements.
- Solvent-Based:Toluene and MEK carriers retain aerospace and marine lock-in where FAA and Lloyd's Register specifications block water-based substitution.
- Non-Aerosol:Bulk pump systems serve high-volume furniture and textile lamination operations in Guangdong and North Carolina.
- UV Cure:Photoinitiator-acrylate systems enable instant polymerization for electronics and medical device assembly where thermal exposure risks component damage.
Solvent-based technology retains the highest margin per liter while water-based platforms expand volume contribution most aggressively.
Application:
Customer type stratification separates high-volume automated packaging converters from project-driven construction contractors, with specification authority residing in distinct organizational functions across each vertical.
- Packaging:Corrugated carton sealing and flexible film lamination drive the highest throughput requirements. H.B. Fuller's hot melt spray leadership anchors North American demand among converters seeking 500+ meter-per-minute line speeds.
- Furniture:Upholstery foam-to-fabric bonding and wood veneer lamination demand flexible, heat-resistant formulations. Guangdong manufacturers specify polyurethane systems for export-grade seating assemblies.
- Textile:Laminated apparel and technical textile bonding requires wash durability and stretch recovery compatibility.
- Footwear:Sole attachment and upper construction utilize solvent-based neoprene systems where open time control enables manual positioning.
- Electronics:Component potting and EMI shielding applications favor UV-cure and silicone platforms for thermal management.
- Paper & Printing:Label stock and bookbinding operations prioritize low-odor acrylic formulations for indoor air quality compliance.
Packaging applications generate the highest absolute volume while furniture represents the most rapid specification-change environment.
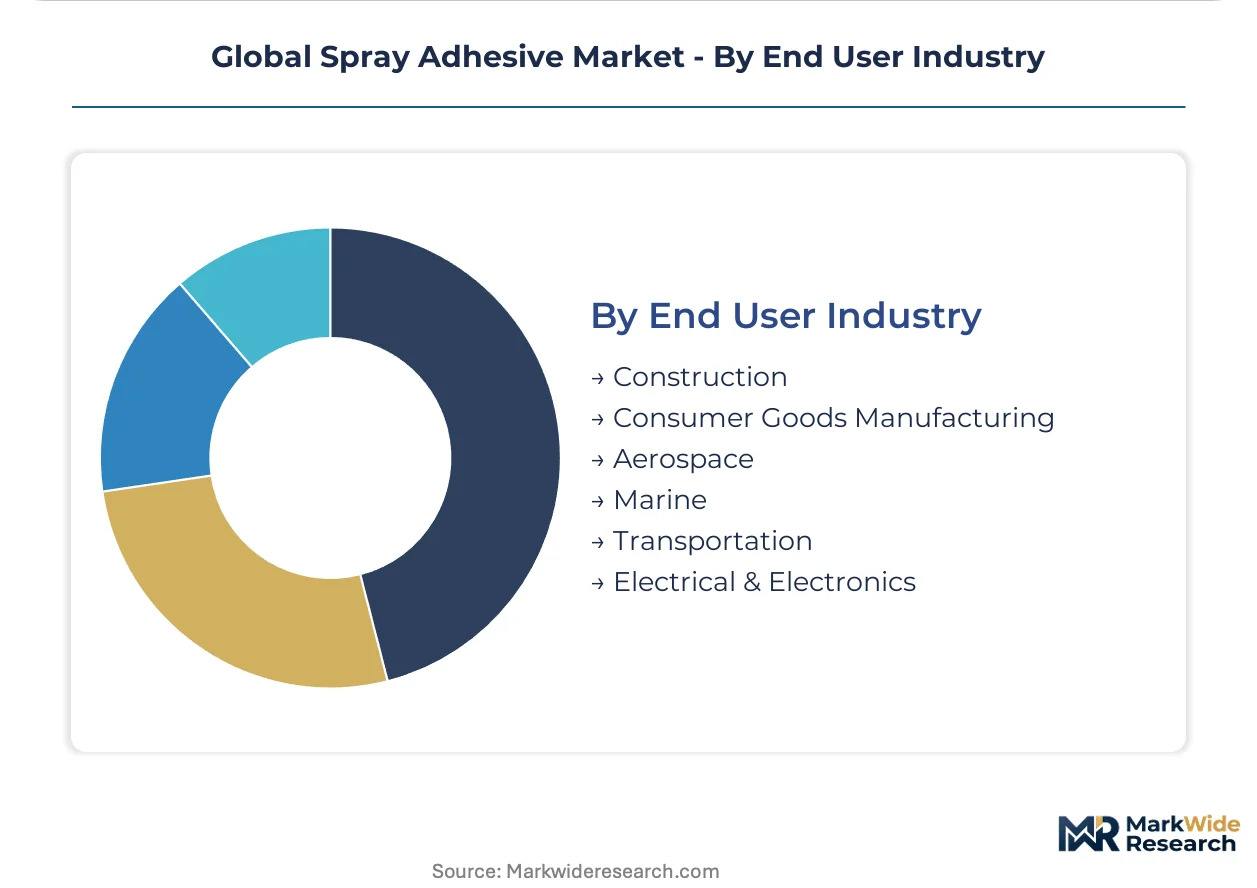
End User Industry:
Maturity gradients separate established construction and consumer goods verticals from emerging transportation electrification applications, with margin concentration inversely correlating to market development stage.
- Transportation:Automotive interior lamination commands premium formulation specifications as Stuttgart and Wolfsburg clusters adopt lightweight bonding for EV range optimization. Seat assembly and headliner operations consume high-tack systems with sub-90-second tack-free requirements.
- Construction:Flooring installation and insulation attachment drive recurring demand in German and US residential renovation cycles. Henkel's construction chemical distribution network sustains European industrial penetration.
- Consumer Goods Manufacturing:Appliance assembly and sporting goods production utilize mid-tier acrylic and rubber-based platforms.
- Aerospace:FAA-certified aircraft interior bonding retains solvent-based lock-in despite REACH pressure, with German KBA type-approval processes creating specification update bottlenecks.
- Marine:Decking and hull construction specifications favor moisture-cure polyurethane and neoprene systems.
- Electrical & Electronics:Battery pack assembly and circuit board protection drive emerging demand for thermal-management-compatible formulations.
Construction anchors current volume generation while transportation electrification presents the steepest expansion trajectory for specialized formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes spray adhesives primarily for automotive interior lamination, while the United States concentrates demand in packaging and furniture verticals, and China splits procurement between export-oriented manufacturing and domestic construction applications.
Germany
Automotive OEMs in Stuttgart and Wolfsburg drive specification intensity for sub-90-second tack-free systems in seat assembly and headliner bonding. EU REACH Annex XVII VOC limits force solvent-to-water formulation transitions across German OEM supply chains. The Rhine-Ruhr industrial corridor anchors construction chemical demand for flooring and insulation attachment.
United States
Packaging converters and North Carolina furniture manufacturers sustain volume demand for hot melt spray and polyurethane systems respectively. US EPA 40 CFR Part 59 regulates VOC emissions from consumer and industrial adhesive products. The Southeast manufacturing belt concentrates textile lamination operations specifying heat-resistant formulations.
China
Export-oriented furniture production in Guangdong and domestic construction activity in Jiangsu and Zhejiang generate dual demand streams for water-based and solvent-based platforms. The MEE enforces GB 37822 standards on atmospheric pollutant discharge from coating operations. Provincial dual carbon policy implementation creates procurement preference for low-emission systems in Yangtze River Delta manufacturing zones.
India
Infrastructure investment and flooring installation in Mumbai and Delhi NCR drive construction adhesive consumption. BIS certification alignment enables European and North American suppliers to access industrial accounts. Western India chemical manufacturing clusters are developing local formulation capabilities for cost-sensitive construction applications.
Japan
Electronics assembly and precision manufacturing in the Kanto and Kansai regions demand UV-cure and silicone spray platforms for thermal management applications. METI industrial standards govern chemical substance emissions from manufacturing operations. Automotive suppliers in the Chubu region specify high-performance bonding systems for lightweight vehicle component assembly.
Global Spray Adhesive Market Competitive Landscape
Capability concentration sits with specialized adhesive formulators possessing aerosol propellant compatibility expertise; scale advantage sits with diversified chemical conglomerates with captive raw material positions. The market structures around three tiers: multinational diversified chemicals with construction chemical networks, mid-cap adhesive specialists with regional formulation leadership, and equipment-integrated system providers. Consolidation pressure favors suppliers with captive applicator manufacturing capabilities. Geographic expansion into India and Southeast Asia represents the dominant competitive move alongside water-based formulation R&D allocation.
Within the diversified chemical tier, 3M and Henkel occupy positions spanning consumer aerosol breadth and industrial construction chemical distribution respectively. H.B. Fuller exemplifies the packaging-focused specialist archetype with hot melt spray technology leadership. These three companies represent distinct strategic vectors: platform breadth, European industrial penetration, and North American packaging vertical integration.
| Leading Market Players |
|---|
| 3M |
| Henkel |
| H.B. Fuller |
| Avery Dennison |
| Sika |
| Dow |
| Arkema |
| Illinois Tool Works |
| Bostik |
| Others |
Supply & Pricing Matrix
Propylene and isocyanate concentration in US Gulf Coast and North Sea petrochemical corridors anchors margin distribution downstream, with formulation specialists in Basel and Midland, Michigan capturing value pools through aerosol propellant compatibility expertise while distributors face compression from equipment bundling trends.
Pricing Analysis
Long-term offtake contracts dominate automotive OEM procurement in Stuttgart and Wolfsburg, locking in volume commitments for water-based polyurethane systems. Price differentiation rests on REACH compliance certification and volume scale, with Tier 1 suppliers least sensitive due to specification lock-in while small-batch custom producers face acute cost compression from feedstock volatility. Pricing pressure intensifies as equipment bundling displaces standalone consumables, squeezing distributor margins.
Supply Chain Analysis
Tariff exposure between China and EU markets dominates supply chain risk assessment for acrylic resin and isocyanate feedstocks. Raw material sourcing draws from Germany, China, and the United States for synthetic elastomers and polyurethane prepolymers, with single-source vulnerability concentrated in specialized propellant compatibility additives. Distribution runs through construction chemical networks in Europe and captive applicator manufacturing channels in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across REACH, EPA, and MEE jurisdictions fragments specification requirements, creating niche opportunities for regional formulation specialists who can navigate compliance complexity faster than multinational incumbents.
For Market Incumbents: Build regulatory compliance moats through early REACH Annex XVII alignment and captive water-based R&D pipelines. Threats from hot melt spray convergence and robotic applicator bundling demand backward integration into equipment manufacturing or exclusive distribution lock-ups with Tier 1 automotive suppliers. For New Entrants and Emerging Players: Build out India construction chemical penetration through BIS certification alignment and Mumbai infrastructure project targeting. White-space exists in Jiangsu and Zhejiang water-based system procurement under dual carbon policy enforcement, with go-to-market anchored through provincial MEE relationship cultivation and local formulation partnerships. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap adhesive specialists with aerosol propellant compatibility expertise and established automotive OEM qualification relationships. Long-term viability over the projection horizon favors suppliers with captive raw material positions and equipment-integrated system capabilities. Watch for KBA type-approval bottlenecks signaling aerospace specification update velocity as inflection indicator for solvent-based margin persistence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propellant Manufacturing | Captive supply of aerosol compatibility additives secures margin pools concentrated in Basel and Midland technical workforces. |
| Water-Based Formulation R&D Scale-Up | REACH Annex XVII alignment enables continued German automotive OEM supply chain participation ahead of sunset dates. |
| Equipment Bundling Partnership | Robotic applicator integration with adhesive supply agreements locks in multi-year procurement with packaging converters. |
| India BIS Certification Investment | Mumbai and Delhi NCR infrastructure demand access requires alignment with national standards body specifications. |
| Hot Melt Spray Technology Licensing | Reactive polyurethane system transfer to Detroit and Stuttgart Tier 1 suppliers eliminates compressed air infrastructure dependence. |
Research Methodology
The analysis maps water-based, solvent-based, hot melt, and UV-cure technology platforms, each validated through formulation chemists, automotive procurement leads, packaging converter operations managers, and construction chemical distributors. Primary interview intelligence triangulates against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and MEE enforcement disclosures. Bottom-up segment sizing and top-down macroeconomic anchoring cross-validate volume and value estimates.
Assumptions held fixed include current REACH Annex XVII VOC limits, EPA 40 CFR Part 59 enforcement levels, and MEE GB 37822 provincial implementation schedules, while variables included automotive EV production mix and furniture export demand volatility. The projection framework models chemistry type, application vertical, technology platform, and end-use industry dimensions. CAGRs derive from segment-level growth rate blending against macroeconomic drivers, with automotive lightweighting intensity and construction renovation cycle amplitude as key spray adhesive demand inputs.
Practitioners should monitor KBA type-approval velocity, propylene and isocyanate price trajectory, and provincial MEE enforcement intensity for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Urea Formaldehyde Concrete Market
Adhesives & Sealants
South America Adhesives Market
Adhesives & Sealants
Global Medical Adhesives Market
Adhesives & Sealants
Asia-Pacific Epoxy Curing Agents Market
Adhesives & Sealants
Solvent-Borne Adhesives Market
Adhesives & Sealants
North America Sealants Market
Adhesives & Sealants
Restorative Materials and Bonding Agents Market
Adhesives & Sealants
Adhesives and Sealants for Handheld Devices Market
Adhesives & Sealants
Dimethylaminoethyl Acrylate Market
Adhesives & Sealants
Specialty Adhesives Market
Adhesives & Sealants
Contact Cement Market
Adhesives & Sealants
North America Reactive Adhesives Market
Adhesives & Sealants
Middle East & Africa Automotive Adhesives & Sealants Market
Adhesives & Sealants
Low Trauma/Skin Friendly Adhesives Market
Adhesives & Sealants
South America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
North America Flock Adhesives Market