
 Thailand Adhesives and Sealants Market | 2026-2036
Thailand Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Adhesives and Sealants Market Analytics
Aftermarket service revenue in adhesive application systems is reshaping margin distribution across the Thailand market. H.B. Fuller Company leverages its regional technical service centers to capture recurring maintenance contracts. Henkel AG & Co. KGaA anchors its position through specialized automotive bonding solutions for Thai assembly plants. Sika AG dominates the construction segment with waterproofing and sealing system packages.
Adhesives and sealants encompass formulations of polymers, resins, and additives that cure through chemical reaction, solvent evaporation, or cooling to form bonded joints with tensile strengths ranging from flexible seals to structural loads exceeding 35 MPa. These materials serve primary industrial purposes including substrate joining, gap filling, environmental sealing, and stress distribution across dissimilar materials. Water-based formulations lead volume in packaging applications due to lower VOC profiles aligned with tightening environmental standards, while reactive systems command premium positioning in automotive and electronics assembly where cure speed and thermal resistance determine process economics. Hot melt technology sustains growth in disposable hygiene and corrugated board sectors driven by high-speed production line compatibility.
Thailand Industrial Standards Institute (TISI) mandates VOC limits under Hazardous Substance Act classifications, compelling reformulation across solvent-based product lines. Department of Industrial Works enforcement of factory emission standards shapes manufacturing site approvals and technology investment decisions for both domestic blenders and multinational subsidiaries. Stakeholders must monitor bio-based feedstock certification developments and Eastern Economic Corridor infrastructure build-out schedules to align capacity expansion with demand nodes.
Market Dynamics
TISI's tightening VOC emission thresholds under the Hazardous Substance Act are forcing wholesale reformulation across solvent-based adhesive portfolios, compressing margins for domestic blenders while advantaging water-based and reactive system specialists with certified low-emission platforms.
Growth Catalysts
- Eastern Economic Corridor infrastructure build-out:Automotive assembly line expansions in Rayong and Chonburi are pulling structural bonding adhesives for lightweight vehicle platforms. Thai Board of Investment incentives accelerate capital deployment into these zones.
- Electronics manufacturing clustering:Bangkok metropolitan area and surrounding industrial zones concentrate demand for thermal interface materials and underfill adhesives. Smartphone and semiconductor packaging operations require precision dispensing compatibility.
- TISI certification harmonization:Alignment with ASEAN mutual recognition arrangements reduces retesting burdens for exporters. Construction material suppliers gain accelerated market access across regional project pipelines.
Market Restraints
- Petrochemical feedstock volatility:Crude oil-linked monomer costs create margin instability for epoxy and polyurethane formulators. Thai blenders lack backward integration into propylene oxide or MDI supply.
- Solvent-based capacity stranding:Existing toluene and xylene-dependent production lines face accelerated obsolescence. Department of Industrial Works enforcement tightens factory emission permits for legacy chemistries.
- Import dependency in specialty additives:Curing agents, rheology modifiers, and adhesion promoters concentrate among Northeast Asian suppliers. Domestic sourcing alternatives remain underdeveloped for high-performance grades.
Strategic Opportunities
- Bio-based feedstock certification:TISI is developing standards for renewable content claims in construction adhesives. Early certification positions suppliers for green public procurement mandates.
- Aftermarket technical service bundling:Application equipment maintenance contracts and on-site formulation support create recurring revenue streams. Automotive OEMs prefer single-source accountability for bonding process yield.
- Reactive hot melt convergence:Moisture-cure polyurethane technology bridges gap-filling capability with high-speed line compatibility. Disposable hygiene manufacturers in Thailand's industrial east represent initial conversion targets.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in rheology design and cure kinetics concentrates among aging technical staff. Thai universities produce limited polymer science graduates with industrial adhesive experience.
- Legacy equipment retrofit costs:Water-based system conversions require heated tank modifications and humidity-controlled dispensing environments. Small and mid-sized converters face capital constraints for compliant infrastructure.
- Multi-standard certification timelines:Simultaneous TISI, ASEAN, and customer-specific qualification protocols extend product launch cycles. Testing backlog at accredited laboratories creates competitive bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Adhesives and Sealants Market |
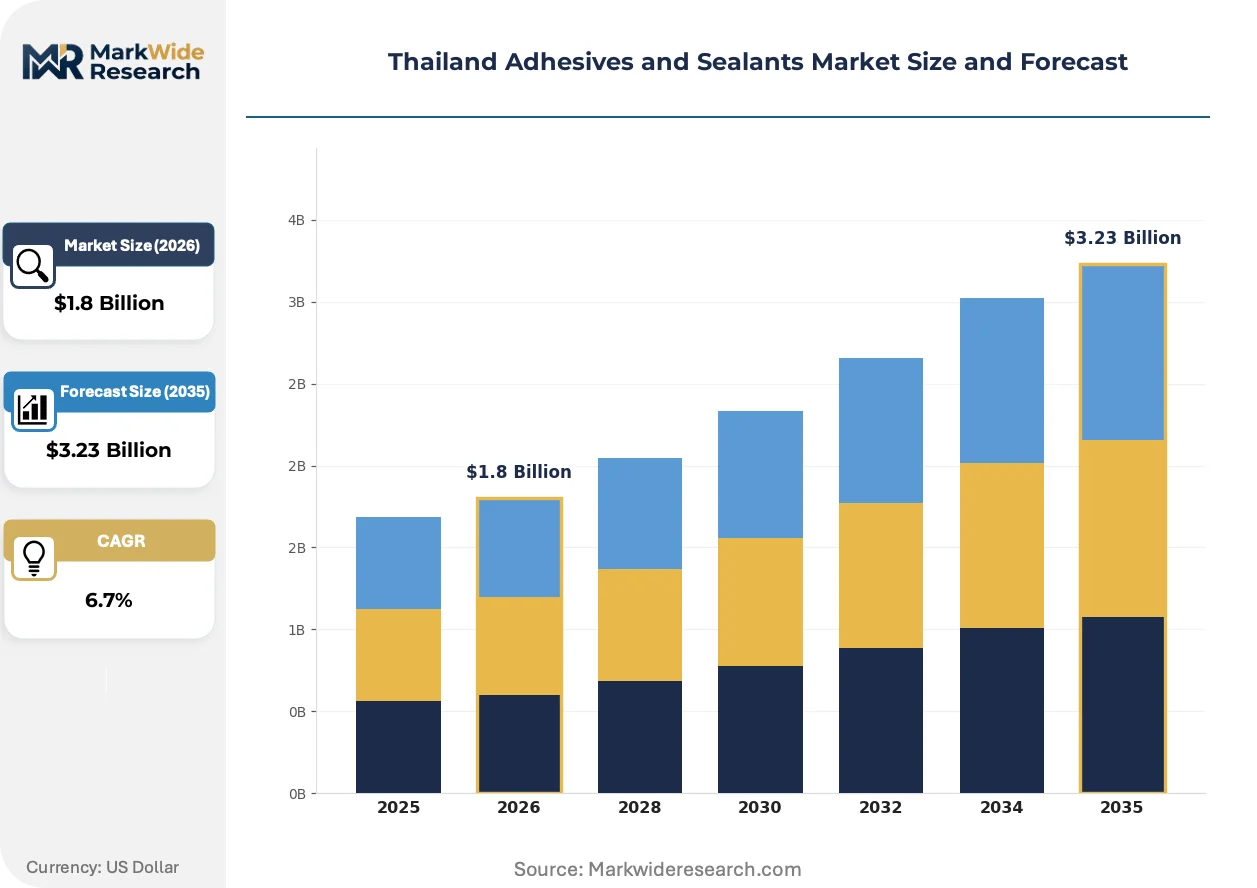
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Hot Melt, Reactive Application: Construction, Automotive, Packaging, Electronics End User: Manufacturers, Contractors, Retailers, Distributors Technology: Synthetic, Natural, Bio-Based, Hybrid |
| Companies Covered | Arkema Group, H.B. Fuller Company, 3M, Dunlop Adhesives (Thailand) Co. Ltd, Huntsman International LLC, Henkel AG & Co. KGaA, Dow, Selic Corp Public Company Limited, Sika AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Adhesives and Sealants Market Evolving Landscape
Thai adhesive markets are experiencing technology substitution accelerated by regulatory compression and end-use precision requirements. Formulation priorities are pivoting toward cure speed, thermal stability, and environmental compliance.
UV-curable acrylic and epoxy systems are rendering obsolete conventional solvent-based coatings in electronics assembly applications. Thai smartphone and semiconductor packaging facilities are converting dispensing lines to accommodate sub-10-second cure cycles. This transition compresses work-in-process inventory requirements while eliminating volatile organic compound handling costs.
TISI's draft standards for bio-based content labeling under the Hazardous Substance Act create compliance architecture for renewable feedstock claims. Construction material suppliers must document carbon-14 content percentages and chain-of-custody certification. Waterproofing and flooring adhesive segments face the steepest reformulation timelines to maintain specification eligibility.
Buyer consolidation among Thai automotive tier-one suppliers is compressing vendor qualification cycles and demanding integrated bonding process guarantees. Procurement teams now bundle adhesive supply with application equipment, training, and yield-loss indemnification. This pattern concentrates most intensely in Rayong province assembly corridors serving export-oriented vehicle platforms.
Thailand Adhesives and Sealants Market Segmentation
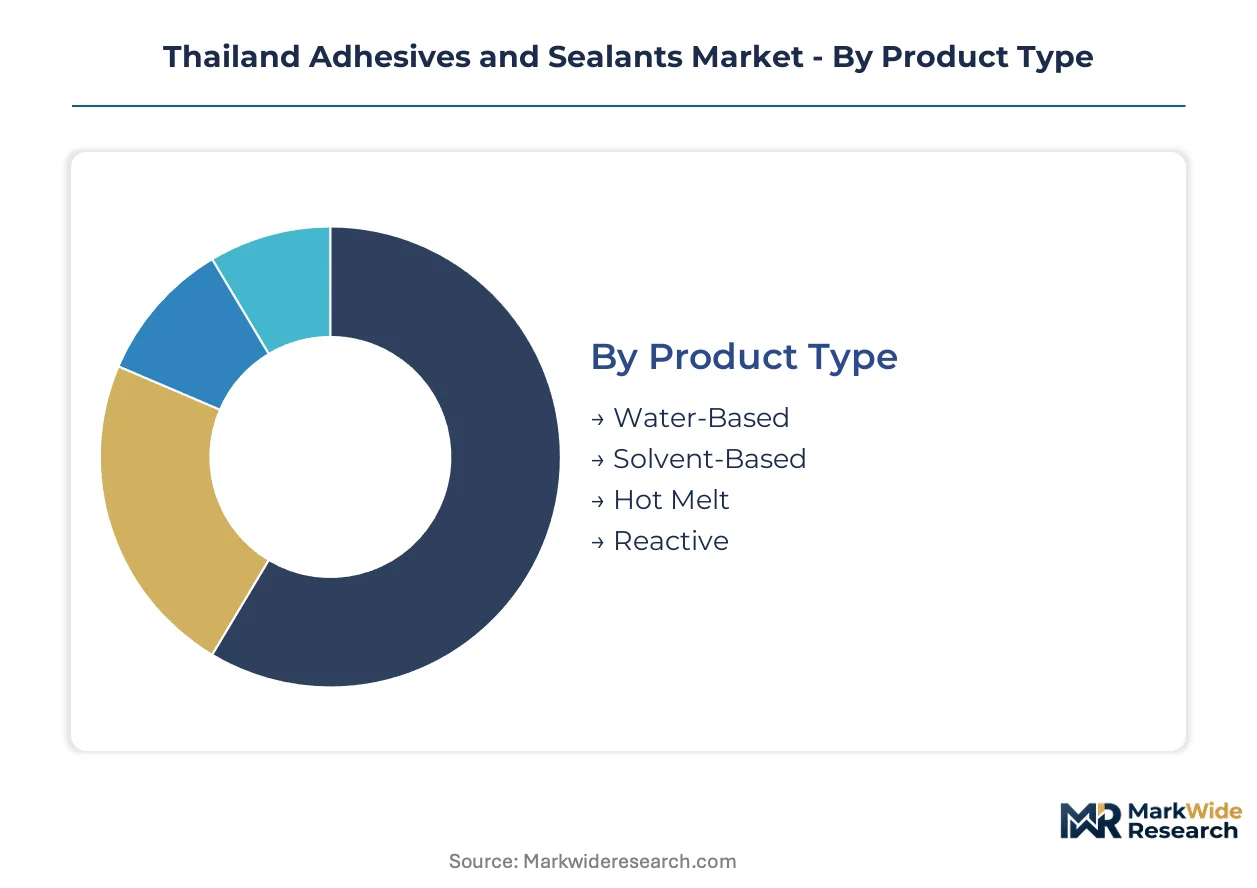
Thailand's adhesives and sealants market segments along formulation chemistry, application intensity, and supply chain position. Each dimension carries distinct regulatory exposure and margin profiles that shape supplier strategy in the Eastern Economic Corridor and Bangkok industrial zones.
Product Type:
Water-based systems dominate mature packaging applications while reactive chemistries capture emerging automotive and electronics precision bonding.
- Water-Based:Acrylic and vinyl acetate emulsions serve corrugated board and paper lamination with low-VOC profiles aligned to TISI emission thresholds. Bangkok metropolitan packaging converters favor these systems for high-speed line compatibility and reduced ventilation infrastructure costs.
- Solvent-Based:Toluene and xylene formulations retain construction adhesive share where open-air application mitigates exposure concerns, though Department of Industrial Works permitting is tightening factory emission limits and accelerating portfolio phase-out.
- Hot Melt:Ethylene-vinyl acetate and polyolefin systems sustain disposable hygiene and bookbinding demand through instant green strength and automated dispensing compatibility.
- Reactive:Epoxy, polyurethane, and cyanoacrylate systems command premium positioning in Rayong automotive assembly and semiconductor packaging where cure speed and thermal resistance determine process economics.
Water-based formulations retain volume leadership; reactive systems hold the steepest expansion curve.
Application:
Construction absorbs commodity-grade tonnage while automotive and electronics pull specialized high-performance formulations.
- Construction:Tile adhesives, waterproofing membranes, and flooring systems concentrate demand in Bangkok and Chonburi infrastructure projects. TISI certification requirements for structural bonding applications are elevating product qualification barriers.
- Automotive:Structural adhesives for lightweight vehicle platforms and NVH damping materials anchor consumption in Rayong province assembly corridors. Thai Board of Investment incentives are accelerating capital deployment into bonding process lines.
- Packaging:Case and carton sealing, label adhesives, and flexible lamination sustain volume throughput in Thailand's food processing and export logistics sectors.
- Electronics:Thermal interface materials, underfill adhesives, and display bonding solutions serve smartphone and semiconductor packaging operations clustered in the Bangkok metropolitan area.
Construction maintains tonnage dominance; electronics applications are expanding most quickly.
End User:
Direct procurement by manufacturers concentrates technical specification power while distributor networks extend geographic coverage.
- Manufacturers:Automotive OEMs and electronics assemblers in the Eastern Economic Corridor specify adhesive systems with integrated application equipment and process yield guarantees.
- Contractors:Waterproofing and flooring specialists in Bangkok and surrounding provinces drive construction adhesive selection based on TISI certification status and job-site cure reliability.
- Retailers:Home improvement channels serve maintenance and small-project demand through consumer-packaged adhesive and sealant SKUs.
- Distributors:Industrial chemical distributors bridge formulation suppliers with mid-sized converters lacking direct technical service relationships.
Manufacturers command specification authority; contractors represent the fastest-growing procurement channel.
Technology:
Synthetic polymers anchor current production while bio-based platforms attract certification investment ahead of green procurement mandates.
- Synthetic:Petrochemical-derived acrylics, polyurethanes, and epoxies constitute the installed formulation base across Thai adhesive manufacturing facilities.
- Natural:Starch and dextrin systems retain niche packaging applications where biodegradability and food-contact compliance outweigh performance limitations.
- Bio-Based:Renewable feedstock adhesives with documented carbon-14 content are advancing through TISI draft standards for construction material certification.
- Hybrid:Synthetic-bio combinations balance performance thresholds with sustainability claims for specification-sensitive building projects.
Synthetic technology retains formulation dominance; bio-based systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's adhesives and sealants consumption diverges from regional peers through its automotive-electronics dual dependency, whereas Vietnam and Indonesia skew toward construction-grade commodities. The Eastern Economic Corridor's bonding-intensive manufacturing creates distinct formulation requirements compared to ASEAN neighbors.
Central Thailand and Bangkok Metropolitan Area
Electronics packaging operations and food processing logistics drive water-based and hot-melt adhesive demand across Samut Prakan and Pathum Thani provinces. TISI's Hazardous Substance Act enforcement tightens VOC thresholds for packaging converters operating near residential zones. Lat Krabang and Bang Na industrial estates concentrate smartphone assembly lines requiring precision dispensing compatibility.
Eastern Economic Corridor
Rayong and Chonburi provinces anchor structural adhesive consumption for lightweight vehicle platforms and NVH damping applications. Thai Board of Investment incentives accelerate capital deployment into bonding process lines for export-oriented automotive assembly. Map Ta Phut and Laem Chabang industrial zones host tier-one suppliers specifying integrated adhesive-application equipment bundles.
Northern Thailand
Chiang Mai and Lampang provinces sustain natural rubber-based adhesive production for footwear and textile bonding applications. Department of Industrial Works permitting for solvent-based facilities faces stricter emission audits outside designated industrial estates. Regional packaging converters serve agricultural export logistics with corrugated board adhesives.
Northeastern Thailand
Khon Kaen and Nakhon Ratchasima provinces concentrate construction adhesive demand for infrastructure build-out and residential development. TISI certification requirements for tile adhesives and waterproofing membranes elevate product qualification barriers for local distributors. Provincial industrial zones attract mid-sized converters seeking lower land costs than Bangkok periphery.
Southern Thailand
Songkhla and Surat Thani provinces support marine and industrial maintenance applications through epoxy and polyurethane sealant distribution networks. Port logistics at Laem Chabang extension facilities pull container sealing and cargo protection adhesives. Regional construction activity concentrates in Hat Yai commercial corridors.
Thailand Adhesives and Sealants Market Competitive Landscape
Capability concentration sits with multinational formulators possessing certified low-emission platforms; scale advantage sits with domestic blenders serving commodity construction segments. The market structures around three tiers: global specialists with integrated technical service networks, regional subsidiaries leveraging ASEAN mutual recognition arrangements, and local compounders focused on price-sensitive packaging and building materials. Dominant competitive moves include portfolio reformulation to meet TISI VOC thresholds and aftermarket service bundling to capture recurring maintenance contracts.
Within the global specialist tier, Henkel AG & Co. KGaA and H.B. Fuller Company exemplify integrated bonding process accountability for Thai automotive OEMs. Sika AG anchors construction segment positioning through waterproofing system packages. Arkema Group and Huntsman International LLC represent reactive chemistry specialists serving electronics and industrial assembly applications. Dow and 3M occupy positions in advanced materials and industrial bonding solutions. Among Thailand-based entities, Selic Corp Public Company Limited and Dunlop Adhesives (Thailand) Co. Ltd sit within the domestic compounder tier serving regional packaging and building material distributors.
| Leading Market Players |
|---|
| Arkema Group |
| H.B. Fuller Company |
| 3M |
| Dunlop Adhesives (Thailand) Co. Ltd |
| Huntsman International LLC |
| Henkel AG & Co. KGaA |
| Dow |
| Selic Corp Public Company Limited |
| Sika AG |
| Others |
Value Network & Pricing Analysis
Petrochemical feedstock volatility tethered to crude oil-linked monomer costs determines both margin compression in solvent-based tiers and the accelerated shift toward water-based and reactive system portfolios across Thai adhesive manufacturing.
Pricing Analysis
Long-term offtake contracts anchor pricing for automotive OEMs in Rayong and Chonburi, while spot purchasing dominates construction-grade commodity adhesives. Three-tier pricing structure across premium certified-reactive, standard water-based, and economy solvent-legacy levels separates specification-grade automotive formulations from packaging converters. Cost compression in solvent-based tiers is intensifying because TISI emission enforcement strands legacy capacity. Packaging converters in Bangkok metropolitan zones exhibit highest price sensitivity; automotive tier-one suppliers prioritize yield guarantees over unit cost.
Supply Chain Analysis
Contract manufacturing concentration for specialty curing agents and rheology modifiers sits with Northeast Asian suppliers in Japan, South Korea, and Taiwan. Thai blenders draw from imported MDI, propylene oxide, and epoxy resins without backward integration into monomer production. Single-source vulnerability concentrates in high-performance adhesion promoters and specialty curing agents. Distribution runs through industrial chemical distributors bridging multinational formulators with mid-sized converters lacking direct technical service relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where TISI certification entrenchment creates switching costs that lock automotive OEMs into qualified supplier relationships.
For Market Incumbents: Entrench position through captive technical service centers in Eastern Economic Corridor industrial zones, bundling adhesive supply with application equipment maintenance and yield-loss indemnification. Deepen backward integration into water-based resin production to offset petrochemical feedstock volatility. Priority lever: accelerate bio-based feedstock certification ahead of green public procurement mandates. For New Entrants and Emerging Players: Northeastern Thailand's provincial industrial zones around Khon Kaen and Nakhon Ratchasima offer underpenetrated construction adhesive demand with lower land costs than Bangkok periphery. Target mid-sized waterproofing and flooring contractors seeking TISI-certified alternatives to established distributors. Go-to-market angle: direct technical support bypassing traditional distributor markups. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors reactive chemistry specialists with certified low-emission platforms and established automotive qualification records. Long-term viability centers on suppliers capable of serving dual automotive-electronics demand clusters. Acquisition target archetype: domestic compounders with Eastern Economic Corridor logistics access and TISI certification infrastructure. Signal to watch: Thai Board of Investment incentive shifts favoring bio-based manufacturing capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Water-Based Resins | Captive acrylic emulsion production insulates Thai blenders from propylene oxide price swings. |
| TISI Bio-Based Certification Program | Carbon-14 documentation positions suppliers for green public procurement mandates in construction. |
| Reactive Hot Melt Capacity Expansion | Moisture-cure polyurethane lines serve disposable hygiene manufacturers in Thailand's industrial east. |
| Technical Service Center Deployment | On-site formulation support captures recurring maintenance contracts from Rayong automotive OEMs. |
| ASEAN Mutual Recognition Alignment | Harmonized testing protocols reduce retesting burdens for construction material exporters. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, Thailand Industrial Standards Institute certification records, Board of Investment incentive disclosures, and petrochemical import statistics. Interviews covered adhesive plant managers, automotive OEM procurement leads, construction contractor purchasing heads, and industrial chemical distribution channel partners. Bottom-up volume estimates from end-use consumption patterns triangulate against top-down production capacity assessments across Thai manufacturing facilities.
Forecast inputs span formulation chemistry segments, application intensity tiers, and supply chain position categories across the projection horizon. Modeled dimensions include water-based versus reactive system splits, automotive-electronics-construction end-use shares, and synthetic-bio-hybrid technology trajectories. CAGRs derive from segment-level demand elasticity analysis calibrated to Eastern Economic Corridor infrastructure build-out schedules and TISI regulatory phase-in timelines. Industry-specific inputs incorporate Thai automotive production forecasts and smartphone packaging operation expansion plans.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Northeast Asian specialty additive suppliers would shift outcomes through import price disruption. Quarterly review of TISI certification backlog durations, Board of Investment incentive allocation rates, and petrochemical monomer import price indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Epoxy Tooling Board Market
Adhesives & Sealants
Wood to Metal Glue Market
Adhesives & Sealants
Europe Contact Adhesives Market
Adhesives & Sealants
High Performance Adhesives Market
Adhesives & Sealants
Global Concrete Bonding Agents Market
Adhesives & Sealants
Cycloaliphatic Epoxy Market
Adhesives & Sealants
Correction Fluid and Tape Market
Adhesives & Sealants
Spain Sealants Market
Adhesives & Sealants
Instant Adhesive Market
Adhesives & Sealants
United States Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Global Bonding Varnish Market
Adhesives & Sealants
Global Adhesive Coating Market
Adhesives & Sealants
North America Cyanoacrylate Adhesives Market
Adhesives & Sealants
Epoxy Putty and Construction Chemicals Market
Adhesives & Sealants
India Adhesives and Sealants Market
Adhesives & Sealants
Low Trauma/Skin Friendly Adhesives Market