
 Land-Based Smart Weapons Market | 2026-2036
Land-Based Smart Weapons Market Size, Share, and Industry Trends Forecast 2026-2036
Land-Based Smart Weapons Market Foresight
Aftermarket service revenue for precision maintenance and software recalibration is tilting toward original equipment manufacturers with embedded platform architectures. Lockheed Martin leverages its vertical integration across seeker manufacturing and mission systems to capture recurring upgrade contracts. Rheinmetall AG anchors European land systems modernization through its Lynx platform and 120mm smoothbore ammunition lines. Rafael Advanced Defense Systems Ltd. differentiates via active protection systems and loitering munition families that extend beyond traditional firepower roles.
Land-based smart weapons encompass precision-strike systems integrating inertial navigation, GPS-aided guidance, semi-active laser seekers, and real-time data links to engage targets with circular error probable measured in single-digit meters. These systems serve military ground forces requiring reduced collateral damage and shortened sensor-to-shooter timelines in contested environments. Missiles and artillery systems command the largest value pools where guidance system integration drives unit economics upward, while unmanned ground vehicles represent the fastest-expanding category as autonomous route planning and swarm coordination mature. Targeting technology segments concentrate margin in electro-optical and multi-spectral seeker development, whereas communication systems face commoditization pressure from commercial waveform adoption.
The U.S. Department of Defense and its Defense Federal Acquisition Regulation Supplement impose stringent cybersecurity and supply chain provenance requirements that reshape vendor qualification processes for smart weapons programs. NATO Standardization Office protocols for interoperability and the Wassenaar Arrangement's munitions list controls further constrain technology transfer and foreign market access. Stakeholders must monitor evolving autonomous engagement rules of engagement and counter-drone treaty developments that could redefine permissible operational boundaries for ground-launched smart weapons.
Market Dynamics
Defense procurement offices across NATO member states are consolidating vendor qualification requirements under the Wassenaar Arrangement's tightened munitions list controls, compressing the supplier base for precision-guided systems while elevating cybersecurity and supply chain provenance as gatekeeping criteria.
Growth Catalysts
- Networked fire-and-forget modernization:Ground forces in the United States, Germany, and South Korea are retiring legacy artillery with GPS-aided and semi-active laser seeker systems to shorten sensor-to-shooter timelines in contested environments.
- Counter-drone treaty momentum:Emerging international frameworks governing autonomous engagement rules are creating procurement windows for active protection systems and loitering munitions that extend beyond traditional firepower roles.
- Embedded platform architectures:Original equipment manufacturers with captive seeker manufacturing and mission systems integration are capturing recurring upgrade contracts through precision maintenance and software recalibration revenue streams.
Market Restraints
- Seeker component supply concentration:Electro-optical and multi-spectral sensor production clusters in select East Asian manufacturing hubs create vulnerability to export control disruptions and geopolitical friction.
- Commercial waveform commoditization:Communication systems face margin compression as military programs adopt adapted commercial data links, eroding proprietary radio revenue pools for traditional defense electronics suppliers.
- Stringent DFARS cybersecurity mandates:The U.S. Defense Federal Acquisition Regulation Supplement imposes supply chain provenance documentation requirements that disqualify smaller vendors lacking compliance infrastructure.
Strategic Opportunities
- Unmanned ground vehicle autonomy:Swarm coordination algorithms and autonomous route planning capabilities represent the fastest-expanding category as ground forces seek reduced-manning forward deployment options.
- European NATO Standardization Office alignment:Interoperability protocols for artillery and missile systems create integrated procurement opportunities for platforms meeting common technical standards across multiple member militaries.
- Aftermarket software recalibration services:Mission system updates and guidance package refreshes offer recurring revenue attachment to hardware platforms with decade-long service lives.
Industry Challenges
- Guidance system integration complexity:Fusing inertial navigation with GPS-aided correction and real-time data links demands specialized firmware engineering talent that defense primes and subcontractors compete aggressively to secure.
- Legacy platform interoperability:Retrofitting circular error probable improvements into existing artillery and missile stocks requires resolving mechanical and electrical interface incompatibilities that extend fielding timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Land-Based Smart Weapons Market |
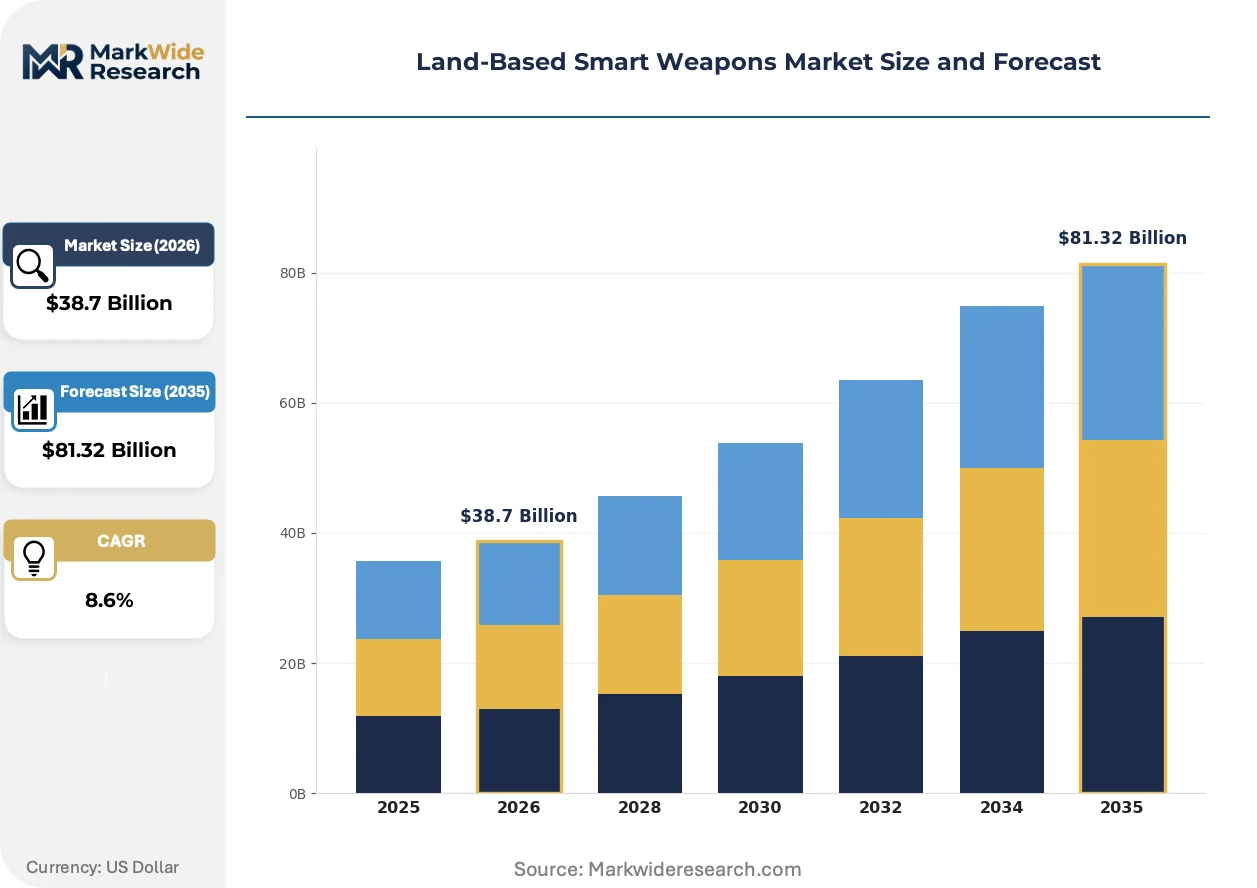
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $81.32 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Weapon Type: Missiles, Drones, Artillery Systems, Unmanned Ground Vehicles Technology: Guidance Systems, Targeting Technology, Communication Systems, Navigation Systems End User: Military, Defense Contractors, Government Agencies, Security Forces Application: Surveillance, Reconnaissance, Target Acquisition, Offensive Operations |
| Companies Covered | Lockheed Martin Corporation, BAE Systems plc, RTX Corporation, MBDA, Rafael Advanced Defense Systems Ltd., Northrop Grumman Corporation, General Dynamics Corporation, Thales Group, Rheinmetall AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Land-Based Smart Weapons Market Shifts & Advancements
Precision engagement architectures are converging with autonomous decision support, reshaping how ground forces allocate firepower across distributed kill chains. Three developments are compressing development cycles and redrawing competitive boundaries.
Multi-spectral seeker technology is migrating from laboratory demonstration to operational fielding across NATO precision-strike programs. Defense procurement offices in Germany and South Korea are accelerating evaluation timelines for systems combining electro-optical and infrared channels. This convergence is compressing vendor qualification windows as primes with in-house sensor production gain schedule advantages over integrators relying on external supply.
The Wassenaar Arrangement's 2023 munitions list revisions have expanded coverage of guidance and navigation components, triggering compliance restructuring across European and North American supply chains. Manufacturers serving multiple national programs must now maintain parallel documentation systems for technology transfer approvals. Missile and artillery system integrators with established export licensing infrastructure are absorbing compliance costs that disqualify smaller component suppliers from multinational competitions.
Buyer concentration within defense ministries is consolidating maintenance and upgrade decisions under original equipment manufacturer relationships. National armaments directors in the United States and Germany are negotiating decade-long performance-based logistics contracts that bundle hardware, software, and sustainment. This reconfiguration favors vertically integrated primes with captive supply chains over specialist subsystem vendors competing for discrete component awards.
Land-Based Smart Weapons Market Segmentation
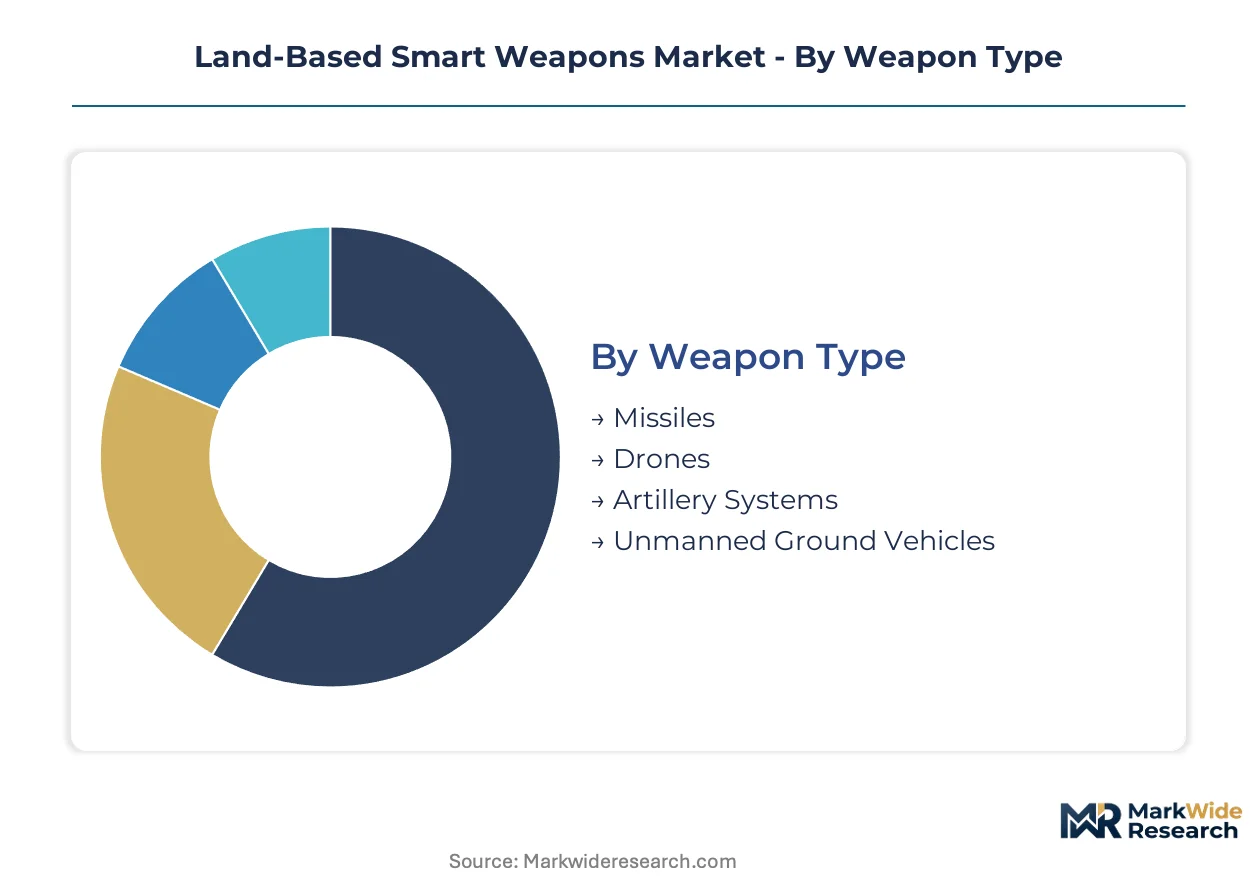
Segmentation of land-based smart weapons reveals how guidance system integration, autonomous platform development, and mission-specific applications concentrate procurement budgets across NATO member states. Weapon type and technology dimensions command the largest value pools where circular error probable improvements and seeker manufacturing drive unit economics.
Weapon Type:
The use-case spectrum spans precision strike against hardened targets, distributed area denial, autonomous route planning, and close fire support with reduced collateral damage profiles.
- Missiles:Fire-and-forget systems integrating inertial navigation with GPS-aided correction and semi-active laser seekers engage point targets with single-digit meter accuracy. Demand concentrates in the United States and Germany where ground forces modernize anti-armor and precision-strike inventories under NATO Standardization Office protocols for interoperability.
- Artillery Systems:Tube-launched precision munitions with guidance kit retrofits transform legacy 155mm and 120mm platforms into networked strike assets. South Korea's military procurement office accelerates evaluation of extended-range guided projectiles to counter massed artillery threats across the Korean Peninsula.
- Drones:Loitering munitions and tactical unmanned aerial systems extend sensor-to-shooter timelines for ground commanders.
- Unmanned Ground Vehicles:Autonomous platforms with swarm coordination capabilities represent the fastest-expanding category as reduced-manning forward deployment options gain traction.
The dominant share belongs to Missiles, while Unmanned Ground Vehicles is closing the gap fastest.
Technology:
Cost tier stratification separates high-margin proprietary seeker development from commoditized communication hardware adapted from commercial waveforms.
- Guidance Systems:Inertial measurement units fused with GPS receivers and terminal seekers constitute the highest-value subsystem category. Defense primes with captive seeker manufacturing capture recurring upgrade contracts through precision maintenance and software recalibration revenue streams.
- Targeting Technology:Electro-optical and multi-spectral sensor development concentrates margin in primes with in-house production. Germany and South Korea accelerate fielding timelines for dual-channel seekers combining infrared and visual spectrum acquisition.
- Navigation Systems:Anti-jam GPS modules and alternative positioning signal processing ensure precision in contested electromagnetic environments.
- Communication Systems:Military waveform radios face margin compression as programs adopt adapted commercial data links.
Guidance Systems retains the largest revenue attachment to hardware platforms, though Targeting Technology is expanding most quickly through multi-spectral convergence.
End User:
Customer type determines procurement authority, with defense ministries consolidating vendor qualification under tightened export control frameworks.
- Military:Ground force modernization programs in the United States, Germany, and South Korea drive volume procurement of precision-guided munitions. National armaments directors negotiate decade-long performance-based logistics contracts bundling hardware, software, and sustainment.
- Defense Contractors:Prime integrators serving multiple national programs must maintain parallel documentation systems for Wassenaar Arrangement technology transfer approvals.
- Government Agencies:Border security and critical infrastructure protection units acquire counter-drone and active protection systems.
- Security Forces:Specialized law enforcement units procure limited quantities of precision systems for high-threat scenarios.
Military accounts anchor procurement volume, while Defense Contractors are capturing the fastest-growing share through integrated sustainment contracts.
Application:
Maturity differentiation separates established surveillance and reconnaissance missions from emerging autonomous engagement protocols.
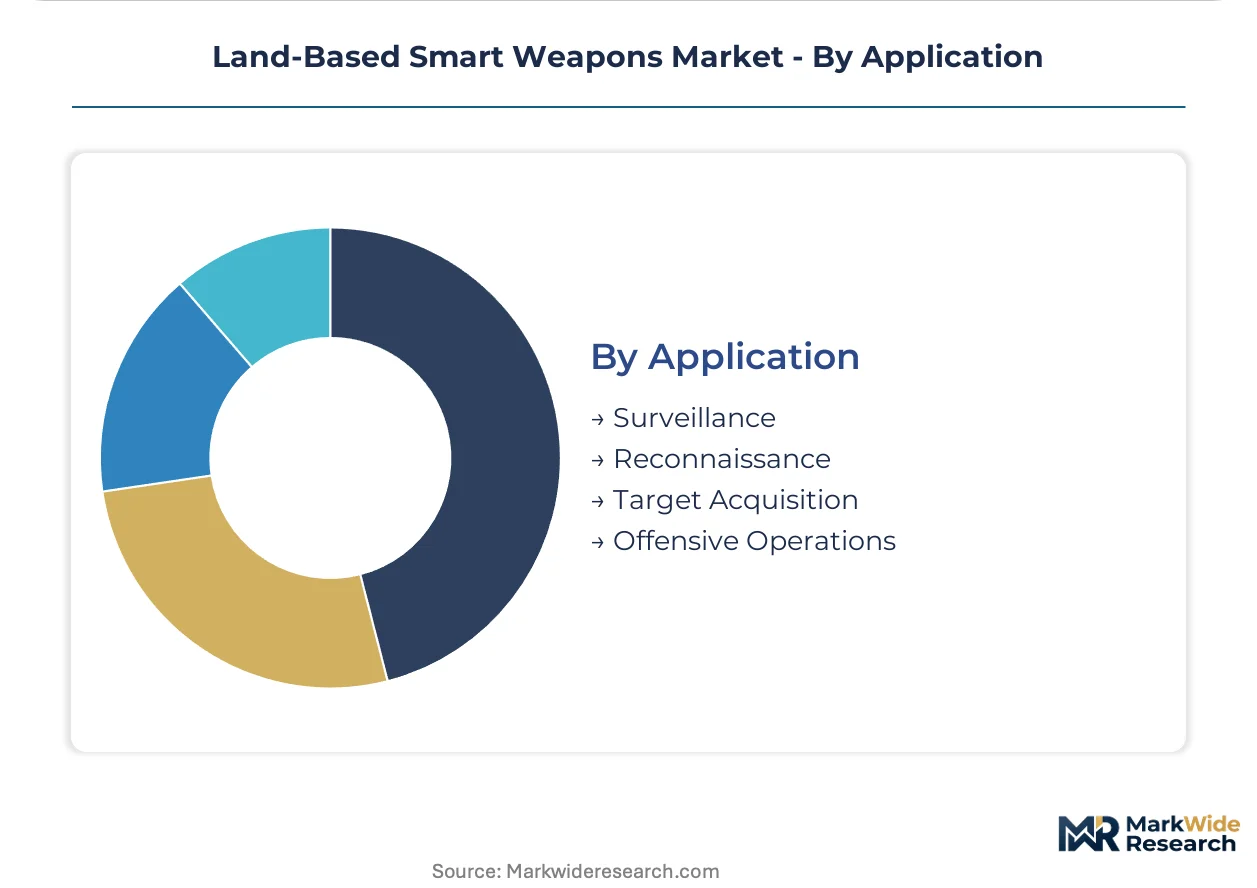
- Offensive Operations:Precision strike against time-sensitive targets demands compressed sensor-to-shooter timelines. Networked fire-and-forget systems with real-time data links enable distributed kill chains across contested environments.
- Target Acquisition:Multi-spectral cueing and automated target recognition reduce operator workload in high-tempo engagements. Active protection systems and loitering munitions extend beyond traditional firepower roles into defensive countermeasures.
- Surveillance:Persistent wide-area coverage supports threat detection and battle damage assessment.
- Reconnaissance:Penetration of denied areas with low-signature platforms precedes precision engagement.
Offensive Operations commands the dominant procurement allocation, while Target Acquisition is gaining share fastest through autonomous decision support integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across procurement theaters: NATO allies prioritize networked interoperability and reduced collateral damage, while Indo-Pacific forces emphasize counter-mass-artillery capabilities against layered threats.
United States
The U.S. Army's Long-Range Precision Fires modernization drives demand for GPS-aided artillery and fire-and-forget missile systems. Defense Federal Acquisition Regulation Supplement cybersecurity mandates reshape vendor qualification, disqualifying suppliers lacking supply chain provenance infrastructure. Huntsville, Alabama anchors missile defense development, while Tucson, Arizona clusters precision seeker manufacturing for ground-launched systems.
Germany
Bundeswehr ground forces accelerate Lynx platform fielding and 120mm precision ammunition procurement under NATO Standardization Office interoperability protocols. The Wassenaar Arrangement's tightened munitions list controls compress the supplier base for guidance components. Unterlüß in Lower Saxony hosts Rheinmetall's land systems integration hub, where active protection systems development converges with loitering munition families.
South Korea
Agency for Defense Development programs counter North Korean massed artillery through extended-range guided projectiles and autonomous engagement systems. Defense Acquisition Program Administration consolidates procurement under performance-based logistics frameworks. Daejeon-Sejong corridor concentrates guidance system integration, while Busan-Ulsan shipyards pivot toward unmanned ground vehicle autonomy for reduced-manning deployment.
Israel
Israel Defense Forces operational requirements drive active protection systems and loitering munition development beyond traditional firepower roles. Ministry of Defense directives emphasize real-time data link resilience in contested electromagnetic environments. Haifa's defense technology cluster specializes in multi-spectral seeker fusion, with Rafael Advanced Defense Systems anchoring electro-optical development for precision-strike applications.
United Kingdom
British Army modernization prioritizes networked sensor-to-shooter architectures under NATO collective defense commitments. UK Strategic Command procurement frameworks emphasize interoperability with European and U.S. systems. Stevenage in Hertfordshire concentrates missile systems engineering, while Glasgow's defense electronics sector supports guidance package development for precision artillery.
Land-Based Smart Weapons Market Competitive Landscape
Capability concentration sits with vertically integrated primes possessing captive seeker manufacturing; scale advantage sits with diversified aerospace conglomerates with established defense electronics divisions. The supplier base compresses under tightened export controls, elevating compliance infrastructure as a competitive barrier. Three archetypes dominate: defense primes with mission systems integration, specialized guidance component manufacturers, and state-affiliated armaments enterprises. Consolidation proceeds through performance-based logistics bundling and strategic partnerships for multi-spectral sensor development.
Among U.S.-based defense conglomerates, Lockheed Martin Corporation and RTX Corporation exemplify the vertically integrated prime archetype, with embedded platform architectures capturing recurring upgrade contracts. Rheinmetall AG represents the European state-affiliated model, anchoring land systems modernization through platform-ammunition integration. Rafael Advanced Defense Systems Ltd. occupies a specialist position, differentiating via active protection systems that extend beyond traditional precision-strike roles.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| BAE Systems plc |
| RTX Corporation |
| MBDA |
| Rafael Advanced Defense Systems Ltd. |
| Northrop Grumman Corporation |
| General Dynamics Corporation |
| Thales Group |
| Rheinmetall AG |
| Others |
Supply & Pricing Matrix
Wassenaar Arrangement export licensing bottlenecks determine both tier spreads in precision-guided munitions and the geographic distribution of component sourcing. Defense primes with established compliance infrastructure command 40-60% pricing premiums over specialist subcontractors while concentrating supply relationships in NATO-aligned manufacturing clusters.
Pricing Analysis
Long-term performance-based logistics contracts dominate procurement, bundling hardware, software, and sustainment over decade-long service lives. Three-tier pricing structure across premium fire-and-forget systems, standard guided artillery, and economy retrofit kits reflects certification grade under DFARS cybersecurity mandates and volume scale of national armaments programs. Pricing pressure stems from commercial waveform adoption eroding proprietary radio margins. Tier 2 defense contractors exhibit highest price sensitivity due to compliance infrastructure costs, while military procurement offices demonstrate lowest sensitivity given mission-critical requirements.
Supply Chain Analysis
The Wassenaar Arrangement's munitions list controls restrict electro-optical seeker flows from East Asian manufacturing hubs to European and North American integrators. Supply chains draw from United States precision seeker clusters, German land systems integration facilities, and South Korean guidance component production. Dependencies center on inertial measurement units, multi-spectral sensors, and anti-jam GPS modules. Single-source vulnerability concentrates in East Asian electro-optical manufacturing. Distribution runs through prime contractor-led vendor networks with captive aftermarket service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense procurement cycles are recovering from post-Afghanistan retrenchment as NATO collective security commitments and Indo-Pacific deterrence requirements accelerate modernization budgets.
For Market Incumbents: Harden embedded platform architectures against emerging autonomous engagement rule changes by deepening in-house seeker manufacturing and securing DFARS-compliant supply chain documentation. Acquire specialist guidance firmware engineering teams to address talent scarcity in inertial-GPS fusion development. Lock in decade-long performance-based logistics contracts before interoperability standardization commoditizes integration services.
For New Entrants and Emerging Players: Establish a beachhead in unmanned ground vehicle autonomy software, the fastest-expanding category with lower capital barriers than hardware platforms. Target South Korean defense acquisition programs seeking counter-artillery solutions with reduced-manning deployment options. Partner with established primes as subsystem suppliers to bypass Wassenaar licensing infrastructure requirements.
For Investors and Strategic Acquirers: Wassenaar Arrangement 2023 munitions list revisions reshape the acquisition landscape by elevating export licensing infrastructure as a scarce asset. Five-to-ten year viability favors vertically integrated primes with captive seeker production over communication systems specialists facing commercial waveform displacement. Acquisition target archetype: mid-cap guidance component manufacturers with DFARS compliance and NATO Standardization Office certification. Signal to watch: autonomous engagement rules of engagement developments that could redefine permissible operational boundaries for ground-launched systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | DFARS compliance infrastructure unlocks U.S. Department of Defense vendor qualification pathways. |
| Multi-Spectral Seeker Development Partnership | Dual-channel electro-optical-infrared fusion accelerates NATO evaluation timelines in Germany and South Korea. |
| Performance-Based Logistics Contracting | Decade-long sustainment bundling captures recurring software recalibration revenue from military procurement offices. |
| Autonomous Engagement Algorithm Investment | Swarm coordination capabilities address reduced-manning requirements in contested Indo-Pacific environments. |
| Export Licensing Infrastructure Expansion | Parallel documentation systems for Wassenaar Arrangement approvals enable multinational program participation. |
Research Methodology
Cross-validation between primary interviews with defense procurement officers, guidance systems engineers, and national armaments directors and secondary validation through NATO Standardization Office protocol documentation, U.S. Defense Federal Acquisition Regulation Supplement filings, and Wassenaar Arrangement munitions list revisions anchors the qualitative findings. Bottom-up triangulation across weapon type, technology, and end-user segmentation dimensions combines with top-down macroeconomic calibration across the analysis window.
Calibration against historical procurement cycles and peer-reviewed defense economics literature validates the analytical framework. Segmentation dimensions modeled include weapon type, guidance technology tier, end-user procurement authority, and regional regulatory cluster throughout the forecast period. CAGRs derive from regression analysis of defense budget allocation trends and technology adoption curves. Industry-specific inputs incorporate DFARS cybersecurity mandate implementation timelines and autonomous engagement rule development trajectories.
Sensitivities concentrate around Wassenaar Arrangement munitions list revisions, autonomous engagement rules of engagement changes, and counter-drone treaty developments. Forecasts reflect documented assumptions regarding NATO interoperability standardization pace and Indo-Pacific deterrence procurement acceleration. Material shifts in export control frameworks or electromagnetic spectrum contestation severity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Smart War Weapon Market
Defense and Military Systems and Equipment
Mergers and Acquisitions (Manda) in Aerospace and Defense Market
Defense and Military Systems and Equipment
Military Exoskeleton Market
Defense and Military Systems and Equipment
Military Aerospace and Defense Lifecycle Management Market
Defense and Military Systems and Equipment
Explosive Ordnance Disposal Market
Defense and Military Systems and Equipment
Counter-IED Systems Market
Defense and Military Systems and Equipment
Global Non Lethal Biochemical Weapon Market
Defense and Military Systems and Equipment
Military Vetronics Market
Defense and Military Systems and Equipment
Middle East and Africa Defense Market
Defense and Military Systems and Equipment
Europe Defense Market
Defense and Military Systems and Equipment
Cognitive Electronic Warfare System Market
Defense and Military Systems and Equipment
Global Military Laser Designator Market
Defense and Military Systems and Equipment
Military High Altitude Radio Jamming System Market
Defense and Military Systems and Equipment
Mine Clearance System Market
Defense and Military Systems and Equipment
United Kingdom Defense Market
Defense and Military Systems and Equipment
Explosive Ordnance Disposal (EOD) Equipment Market