
 Rebars Market | 2026-2036
Rebars Market Size, Share, and Industry Trends Forecast 2026-2036
Rebars Market Analytics
ASTM A615 certification is collapsing the supplier base as mills without accredited melt-and-rolling capabilities lose access to federally funded projects. ArcelorMittal leverages its integrated European-African production network to sustain specification-grade output across multiple heat-treatment standards. Nucor Corporation anchors its position through electric-arc furnace flexibility, allowing rapid chemistry adjustments for seismic-grade orders. POSCO dominates premium alloy-bar segments in Northeast Asian markets where corrosion resistance specifications exceed baseline requirements.
Rebars are steel reinforcement bars, typically manufactured from carbon steel billets through hot rolling to nominal diameters ranging from 6 mm to 50 mm, with ribbed surface patterns engineered to bond mechanically with concrete matrices. Their primary purpose is to carry tensile loads within reinforced concrete structures, compensating for concrete's inherent compressive-strength bias. Black rebars occupy the volume core of developing-market construction, while epoxy-coated variants command margin premiums in marine and de-icing salt exposures across North American infrastructure. Prestressed strand applications in bridge cable-stay systems represent the fastest-expanding specification tier, though from a smaller installed base.
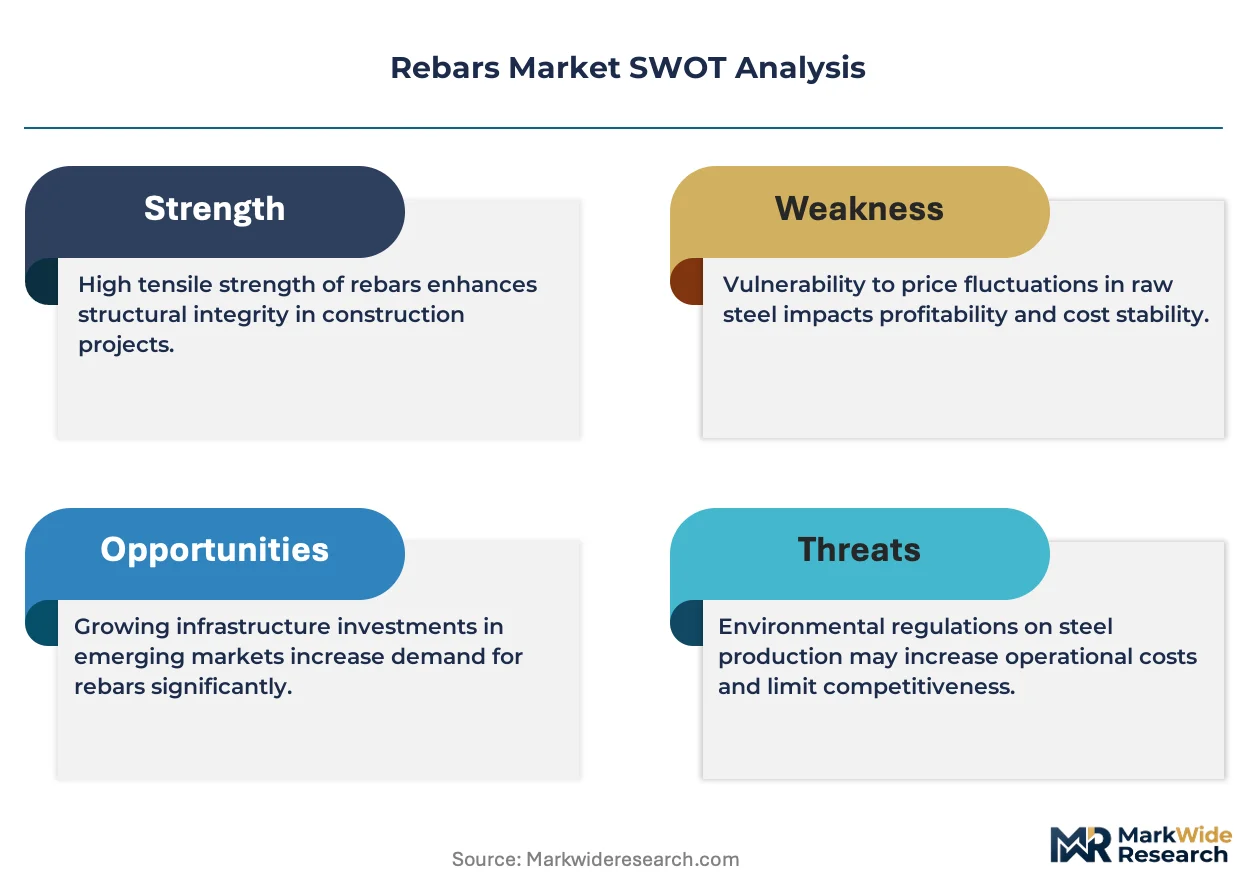
FEMA seismic provisions and AASHTO bridge standards in the United States, alongside China's GB/T 1499 national standards enforced by SAMR, collectively elevate yield-strength minimums and ductility ratios that reshape mill investment priorities. India's BIS certification marks and CDSCO-adjacent construction-product oversight further fragment compliance pathways for exporters. Stakeholders must monitor harmonization gaps between regional rebar-grade designation systems before committing to cross-border capacity expansion or long-term offtake agreements.
Market Dynamics
State-backed infrastructure procurement in China and India's coastal megacities is compressing specification timelines while ASTM A706 and ISO 6935 certification gates eliminate marginal producers from federally funded tenders.
Growth Catalysts
- Seismic-grade mandates:FEMA provisions and AASHTO bridge standards in the United States now require enhanced ductility ratios, forcing mill upgrades that lock in premium-grade offtake for qualified suppliers.
- India's infrastructure pipeline:CDSCO-adjacent construction oversight and BIS certification expansion across highway and metro projects concentrate demand for accredited high-strength rebar grades.
- Urban renewal density:China's SAMR-enforced GB/T 1499 standards in coastal provinces accelerate replacement cycles for older structures, sustaining billet consumption through demolition-rebuild loops.
Market Restraints
- Scrap price volatility:Electric-arc furnace operators face margin compression when shredded auto scrap and heavy melt spreads widen against billet-linked contract formulas.
- Concentrated ore dependency:Blast furnace routes remain tethered to Australian and Brazilian iron ore concentrate, exposing cost structures to seaborne freight and concentrate grade arbitrage.
- Epoxy coating substitution ceiling:Stainless-clad and fiber-reinforced polymer alternatives capture specification share in marine exposure zones where salt degradation exceeds rebar corrosion resistance thresholds.
Strategic Opportunities
- Southeast Asia infrastructure gap:Vietnam and Indonesia highway corridors lack domestic melt-and-roll capacity, creating import windows for accredited foreign mills with ISO 6935 alignment.
- Prestressed strand bridge applications:Cable-stay systems in medium-span crossings represent specification-grade white space where yield-strength minimums exceed standard rebar baselines.
- EU Green Deal carbon border adjustments:CBAM implementation favors electric-arc furnace producers with Scope 1-2 emissions documentation, disadvantaging coal-intensive import competition.
Industry Challenges
- Metallurgical chemist scarcity:Rapid chemistry adjustments for seismic-grade orders require specialized talent pools concentrated in legacy steel regions, constraining capacity expansion timelines.
- Heat-treatment capex cycles:Quench-and-self-tempering lines for Grade 80+ specifications demand 24-36 month installation windows, misaligning with procurement contract start dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rebars Market |
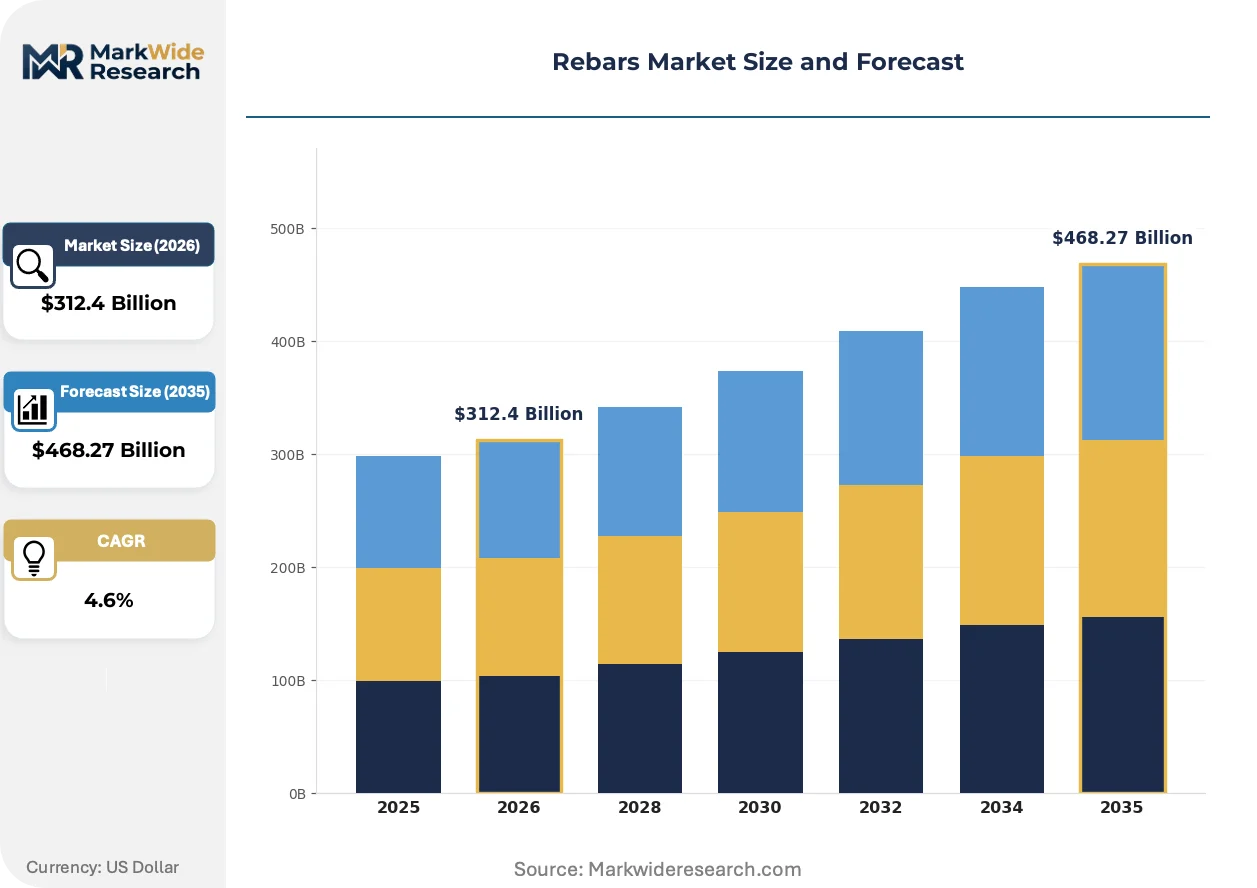
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $468.27 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy Coated, Galvanized, Prestressed, Black End User: Residential, Commercial, Infrastructure, Industrial Application: Building Construction, Bridge Construction, Road Construction, Soil Reinforcement Distribution Channel: Wholesale, Retail, Direct Sale, Online |
| Companies Covered | Gerdau S.A., JSW Steel, ArcelorMittal, Commercial Metals Company, Steel Authority of India Limited, Nucor Corporation, Tata Steel Limited, POSCO, China Baowu Steel Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rebars Market Evolving Landscape
Microalloying chemistries and digital twin process controls are compressing development cycles for specification-grade products while regulatory carbon accounting reshapes mill investment priorities across major steel-consuming economies.
Quench-and-self-tempering (QST) thermomechanical processing is supplanting traditional normalized rolling for Grade 60 and Grade 80 rebar production. Bridge contractors in seismic zones are specifying QST-treated bars for guaranteed yield-strength consistency. The technology is compressing heat-treatment energy costs while enabling thinner-section designs that reduce concrete volume in high-rise cores.
EU CBAM carbon border adjustment mechanisms and China's dual carbon goals are tightening emissions disclosure requirements for imported steel products. Mills without verified Scope 1-2 data face exclusion from public procurement tenders in Germany and France. The policy shift is accelerating electric-arc furnace retrofits in export-oriented production bases while disadvantaging coal-integrated capacity in traditional supply regions.
Buyers in India's state highway authorities are consolidating annual rebar requirements into single-tender frameworks with embedded quality-audit clauses. Long-term offtake agreements with accredited mills are displacing spot-market procurement for projects exceeding 50,000 metric tons. The concentration is most visible in Maharashtra and Gujarat where expressway corridors bundle multiple construction packages under unified material specifications.
Rebars Market Segmentation
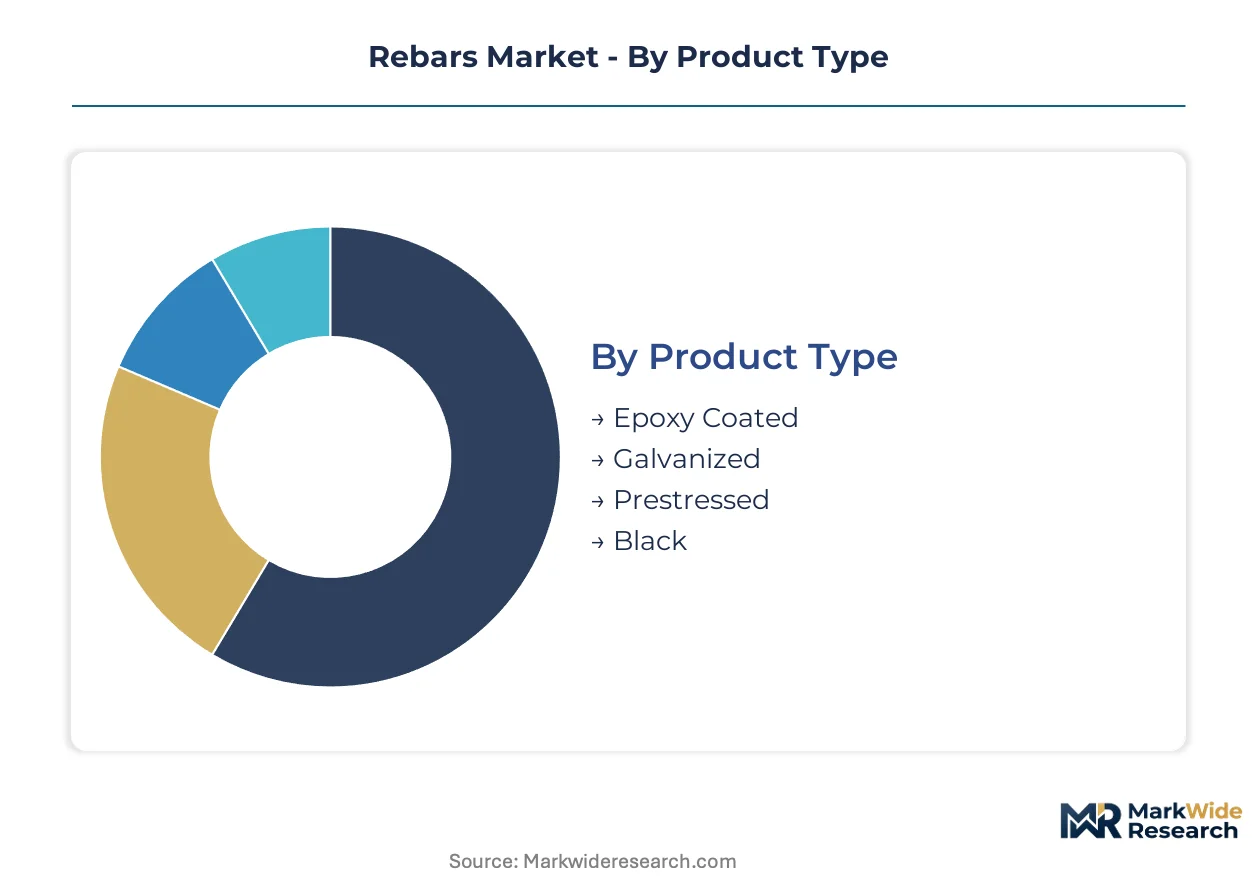
Rebar procurement patterns diverge sharply across specification tiers, coating technologies, and project-scale requirements. Understanding these fault lines reveals where mills capture premium pricing and where volume commoditization erodes margin.
Product Type:
Epoxy-coated and galvanized variants face intensifying substitution pressure from stainless-clad alternatives in marine exposure zones, while uncoated black grades confront fiber-reinforced polymer competition in non-structural applications.
- Epoxy Coated:Fusion-bonded epoxy layers 175-250 microns thick create dielectric barriers against chloride ingress. Bridge contractors in coastal Maharashtra and Gujarat specify these for deck slabs where de-icing salt exposure exceeds corrosion thresholds.
- Black:Uncoated carbon steel bars dominate developing-market volume through cost-minimization in low-exposure residential foundations. China's SAMR-enforced GB/T 1499 standards in coastal provinces sustain billet consumption through urban renewal demolition-rebuild cycles.
- Galvanized:Hot-dip zinc coatings 85-100 microns thick extend service life in moderate humidity environments without epoxy application complexity. Highway authorities in Vietnam specify these for rural overpasses where maintenance access is limited.
- Prestressed:High-tensile alloy strands 15.2-15.7 mm diameter deliver yield strengths exceeding standard rebar baselines for cable-stay bridge systems. Indonesia's Trans-Java toll road corridor drives specification-grade demand for medium-span crossings.
Black retains volume leadership; prestressed holds the steepest expansion curve.
End User:
Cost tier stratification separates specification-intensive infrastructure procurement from price-sensitive residential spot purchasing, with commercial and industrial occupying intermediate positions.
- Infrastructure:State highway authorities and metro rail corporations mandate accredited melt-and-roll capabilities through embedded quality-audit clauses. India's CDSCO-adjacent construction oversight and BIS certification expansion concentrate annual requirements into single-tender frameworks exceeding 50,000 metric tons.
- Residential:Individual home builders and small developers prioritize spot-market availability over specification compliance in low-rise construction. Black rebar procurement through wholesale distributors dominates this tier across Southeast Asian peri-urban zones.
- Commercial:High-rise core and shell contractors balance seismic-grade mandates against concrete volume reduction targets. QST-treated Grade 80 bars enable thinner-section designs that compress construction schedules in Mumbai and Bangalore office towers.
- Industrial:Power plant and refinery projects specify corrosion-resistant alloy grades for containment structures exposed to process chemicals. Heavy industrial procurement runs through direct mill relationships with chemistry adjustment protocols.
Infrastructure commands specification premiums; residential absorbs price volatility most directly.
Application:
Volume concentration in building construction contrasts with margin capture in specialized bridge and soil engineering applications requiring custom metallurgy.
- Building Construction:Vertical structural elements from foundations to roof cores consume standard Grade 60 rebars in highest tonnage. China's coastal province urban renewal sustains replacement-cycle demand through state-backed procurement.
- Bridge Construction:Cable-stay and segmental box-girder systems specify prestressed strands and quench-and-self-tempered bars for guaranteed ductility ratios. AASHTO standards in US federally funded projects lock in premium-grade offtake for qualified suppliers.
- Road Construction:Pavement dowel bars and median barrier anchorage use lower-grade black products with minimal surface preparation. Indonesian and Vietnamese highway corridors lacking domestic melt-and-roll capacity create import windows for ISO 6935-accredited foreign mills.
- Soil Reinforcement:Mechanically stabilized earth walls and slope stabilization deploy grid-pattern geosynthetic-rebar composites. Mining tailings dams in Brazil specify epoxy-coated grades for long-term stability in acidic drainage environments.
Building construction anchors tonnage; bridge applications generate highest per-kilogram value realization.
Distribution Channel:
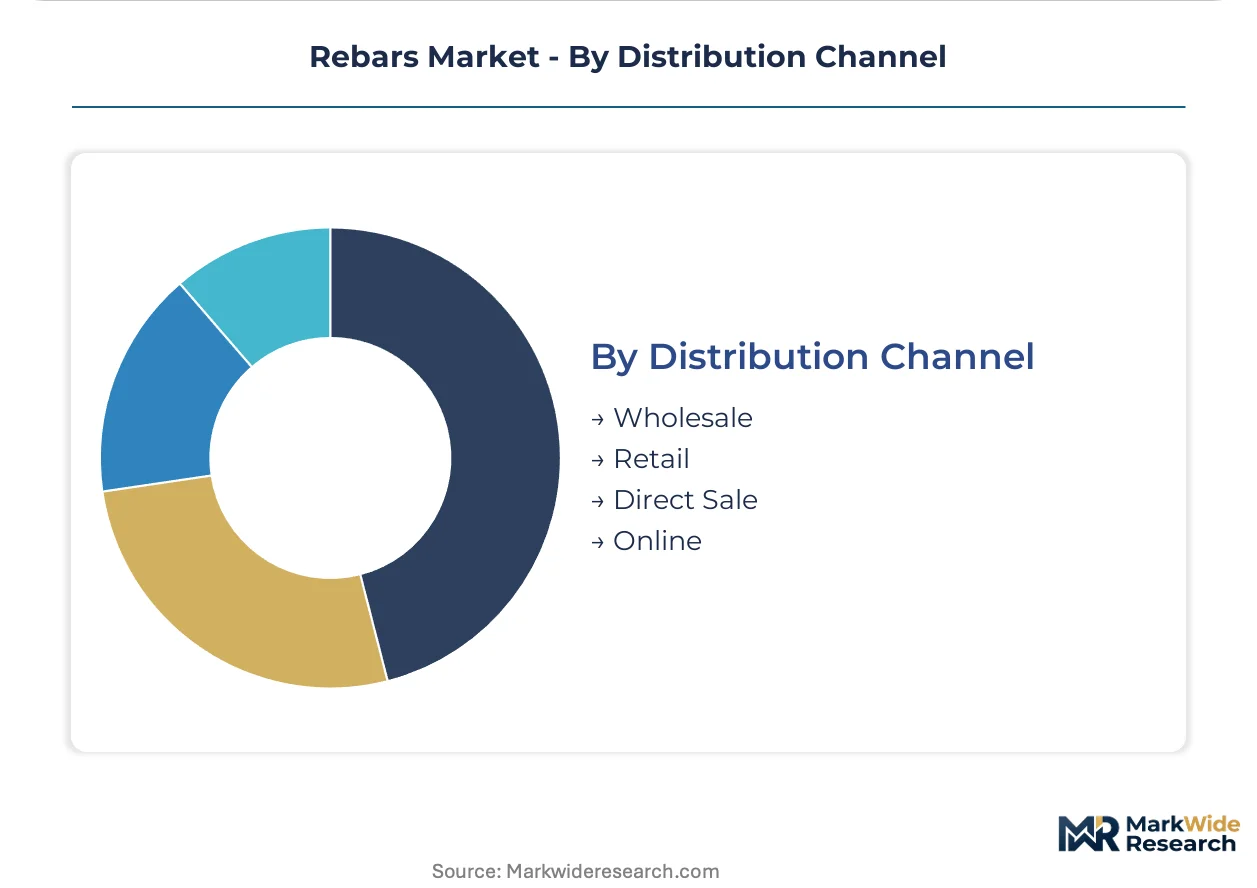
Customer scale and specification complexity determine channel selection, with large infrastructure bundlers bypassing intermediaries while fragmented residential builders rely on inventory-holding distributors.
- Wholesale:Regional distributors maintain accredited stockpiles for immediate availability to mid-size contractors. Maharashtra and Gujarat expressway corridors bundle multiple packages under unified specifications that wholesale networks service.
- Direct Sale:Annual offtake agreements with accredited mills displace spot procurement for projects exceeding volume thresholds. India's state highway consolidation into single-tender frameworks accelerates this channel shift.
- Retail:Small-quantity availability for repair and extension work in established urban areas. Hardware networks in Indian tier-2 cities stock black grades for residential alteration projects.
- Online:Digital platforms emerging for standard-grade spot purchasing with logistics coordination. Southeast Asian construction material marketplaces pilot rebar modules with mill-direct certification verification.
Direct sale captures infrastructure migration; wholesale retains residential and small-contractor access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federally funded infrastructure programs across multiple jurisdictions are tightening certification requirements for structural steel procurement. State-backed urban renewal initiatives in coastal manufacturing zones sustain billet consumption through demolition-rebuild cycles. Cross-border trade flows concentrate among ISO 6935-accredited producers with verified melt-and-roll capabilities.
China
Coastal province urban renewal drives volume concentration in Jiangsu and Guangdong manufacturing corridors. SAMR-enforced GB/T 1499 standards elevate yield-strength minimums for state-backed procurement tenders. Yangtze River Delta steel clusters process demolition scrap into specification-grade billet for high-rise core applications.
India
Expressway corridors in Maharashtra and Gujarat bundle construction packages exceeding 50,000 metric tons annually. BIS certification expansion and CDSCO-adjacent construction oversight consolidate demand around accredited mills. Mumbai and Bangalore high-rise contractors specify quench-and-self-tempered Grade 80 bars for thinner-section concrete designs.
United States
FEMA seismic provisions and AASHTO bridge standards mandate enhanced ductility ratios for federally funded projects. ASTM A706 certification gates eliminate marginal producers from infrastructure tenders. Gulf Coast and Midwest electric-arc furnace operators adjust chemistry rapidly for seismic-grade orders.
Vietnam
Trans-Asia highway corridors lack domestic melt-and-roll capacity, creating import windows for foreign-accredited suppliers. ISO 6935 alignment determines eligibility for state highway authority tenders. Northern industrial zones around Haiphong serve as distribution nodes for cross-border rebar flows.
Germany
EU Green Deal carbon border adjustments favor electric-arc furnace producers with Scope 1-2 emissions documentation. CBAM implementation disadvantages coal-integrated import competition in public procurement. Ruhr Valley and Bavarian steel clusters retrofit capacity to meet verified emissions disclosure requirements.
Rebars Market Competitive Landscape
Player mix skews toward integrated multinational producers with cross-border specification-grade capabilities. Market structure concentrates around mills with accredited melt-and-roll networks spanning multiple heat-treatment standards. Strategic archetypes include electric-arc furnace specialists, blast furnace-integrated giants, and regional long-product champions. Dominant competitive moves encompass capacity retrofits for seismic-grade output and long-term offtake agreements with state infrastructure bundlers.
Among Brazil-based integrated producers, Gerdau S.A. represents the regional long-product champion archetype with South American network density. Indian conglomerate-affiliated mills JSW Steel and Tata Steel Limited exemplify domestic market consolidation through BIS-accredited capacity expansion. Nucor Corporation anchors the electric-arc furnace flexibility archetype, occupying a position where rapid chemistry adjustments serve seismic-grade order flows. ArcelorMittal and POSCO sit within the multinational integrated tier, their geographic span enabling specification-grade output across divergent regional certification regimes.
| Leading Market Players |
|---|
| Gerdau S.A. |
| JSW Steel |
| ArcelorMittal |
| Commercial Metals Company |
| Steel Authority of India Limited |
| Nucor Corporation |
| Tata Steel Limited |
| POSCO |
| China Baowu Steel Group |
| Others |
Value Network & Pricing Analysis
Twenty-four to thirty-six month lead times for quench-and-self-tempering line installation compress pricing power for Grade 80+ specifications while concentrating supply leverage among mills with accredited melt-and-roll capabilities already in place. This inventory cycle mismatch between heat-treatment capex and procurement contract start dates forces buyers into long-term offtake premiums or spot-market vulnerability.
Pricing Analysis
Certification level creates the primary spread between ASTM A706 seismic-grade premiums and black rebar commodity baselines. Contract-based long-term offtake agreements dominate infrastructure procurement above 50,000 metric tons, while spot-market transactions absorb residential builder price sensitivity. Price differentiation hinges on BIS accreditation status and volume scale thresholds embedded in Indian state highway tender frameworks. Cost compression in uncoated black grades intensifies as fiber-reinforced polymer alternatives capture non-structural specification share.
Supply Chain Analysis
Seaborne freight volatility on Australia-China and Brazil-China iron ore lanes feeds directly into blast furnace cost structures and rebar export pricing. Geographic supply concentrates in China, India, and Brazil, with raw material dependencies spanning Australian iron ore concentrate, shredded auto scrap, and ferroalloy microadditives. Tariff exposure on carbon-intensive imports into the European Union under CBAM mechanisms creates supply chain risk for coal-integrated mills. Distribution runs through direct-sale channels for infrastructure bundlers and wholesale networks for fragmented residential contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rebar procurement is consolidating around specification-grade platform economics where BIS and ASTM certification interoperability determines mill access to state-backed tender frameworks. This ecosystem shift rewards accredited producers with embedded quality-audit protocols.
For Market Incumbents: Compound certification moats by accelerating quench-and-self-tempering capacity additions in Maharashtra and Gujarat corridor proximity. Defend against electric-arc furnace entrants through backward integration into demolition scrap collection networks that secure billet feedstock for GB/T 1499 and ISO 6935 grade consistency. For New Entrants and Emerging Players: Lead with prestressed strand specifications for Indonesia's Trans-Java toll road corridor where domestic melt-and-roll capacity gaps create import windows. Target Vietnam's northern industrial zones around Haiphong as the most penetrable geography for ISO 6935-accredited foreign supply. Anchor go-to-market positioning through direct mill relationships with state highway authority quality-audit compliance. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate-affiliated steel divisions lacking standalone BIS or ASTM accreditation for infrastructure-grade output. Long-term viability favors electric-arc furnace assets with verified Scope 1-2 emissions documentation aligned to EU Green Deal procurement gates. Watch CBAM implementation enforcement as the inflection signal for carbon-border-adjusted import displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Quench-and-Self-Tempering Capacity Expansion | Grade 80+ output captures seismic-grade premiums in Mumbai and Bangalore high-rise cores. |
| Backward Integration into Scrap Collection | Demolition scrap feedstock secures billet supply for GB/T 1499 specification compliance. |
| ISO 6935 Accreditation Investment | Vietnam and Indonesia highway tenders exclude non-accredited foreign mills from eligibility. |
| Scope 1-2 Emissions Verification | CBAM-aligned documentation preserves EU public procurement access against coal-integrated competition. |
| Long-Term Offtake Agreement Structuring | Single-tender frameworks exceeding 50,000 metric tons displace spot procurement in Indian expressway corridors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with bridge contractors, state highway procurement officers, metallurgical R&D directors, and electric-arc furnace plant managers. Secondary validation drew from BIS certification registries, SAMR GB/T standard filings, AASHTO bridge specification updates, and customs trade data for billet and rebar flows. Bottom-up volume modeling from project-level procurement data triangulated against top-down capacity assessments from mill equipment disclosures.
Across the analysis window, the forecasting framework modeled rebar demand through segmentation dimensions spanning product type, end-user tier, application category, and distribution channel complexity. CAGRs were derived from regression analysis against infrastructure investment pipelines and urban renewal demolition-rebuild cycles. Industry-specific inputs included FEMA seismic provision adoption curves and India's CDSCO-adjacent construction oversight expansion timelines.
The analysis sits within stated boundaries; outcomes outside sustained state-backed infrastructure procurement intensity or accelerated CBAM enforcement would require recalibration. Forecasts reflect assumptions around certification harmonization gaps and scrap-billet price spread stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Australia Industrial Insulation Market
Building & Construction Materials
Welded Steel Tanks Market
Building & Construction Materials
USA and Canada Pre-Painted Steel Roofing and Cladding Market
Building & Construction Materials
Thinset Mortar Market
Building & Construction Materials
North America Mineral Wool Ceiling Tiles Market
Building & Construction Materials
North America Rainscreen Cladding Market
Building & Construction Materials
Acoustic Plasterboard Market
Building & Construction Materials
Concrete Densifier Market
Building & Construction Materials
Concrete Aggregate Market
Building & Construction Materials
Carbon Steel IBC Market
Building & Construction Materials
Poland Cement Market
Building & Construction Materials
Plumbing Fixtures and Fittings Manufacturing Market
Building & Construction Materials
Household Mosaic Tiles Market
Building & Construction Materials
Global Floor and Wall Glazed Tiles Market
Building & Construction Materials
Autoclave Aerated Concrete Market
Building & Construction Materials
Wood Panel Market