
 Global Screw Piles Market | 2026-2036
Global Screw Piles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Screw Piles Market Outlook
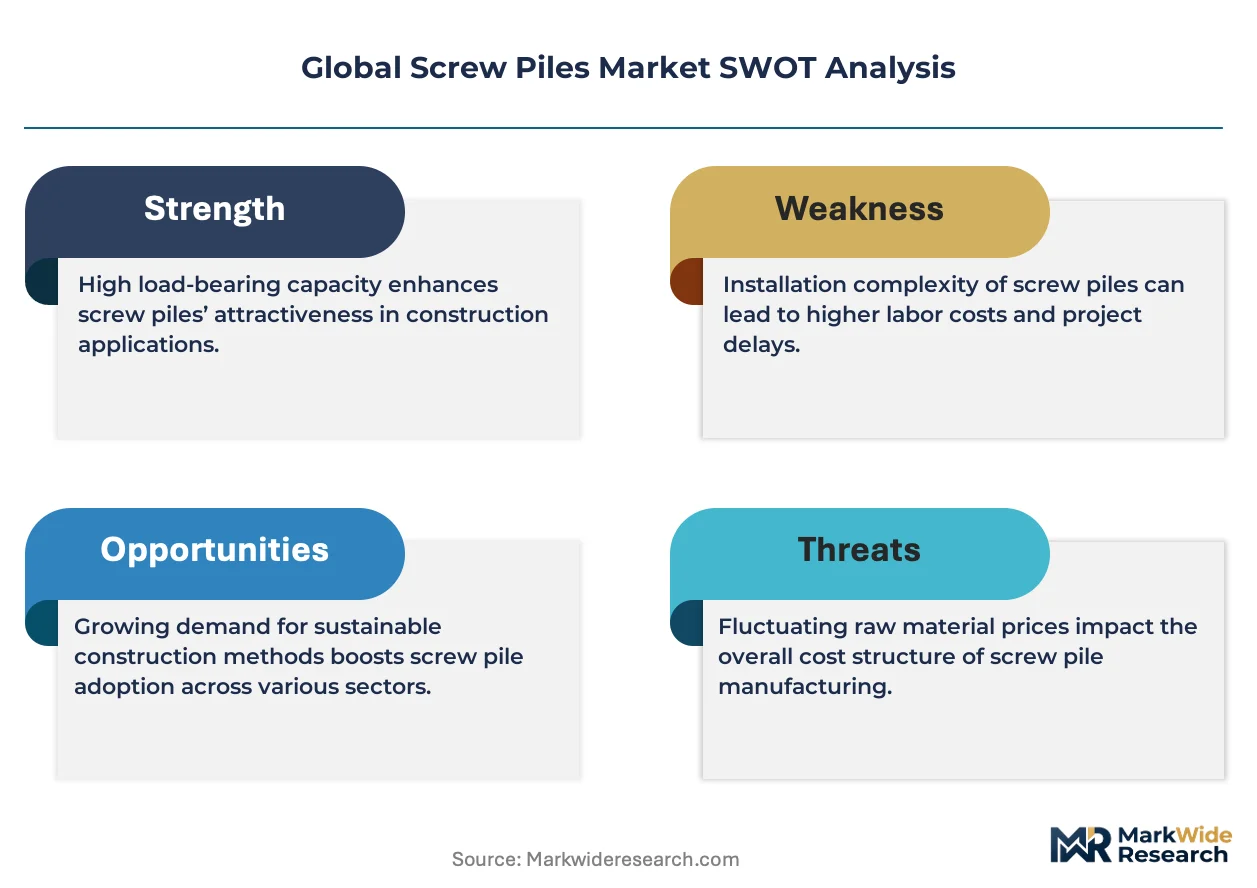
Galvanized steel is pivoting toward high-strength alloy formulations in screw pile manufacturing as fabricators seek weight reduction without load-bearing compromise. TorcSill leverages captive galvanizing capacity to control coating quality across its North American distribution network. Keller Group anchors its competitive stance through integrated geotechnical design services bundled with pile installation. GoliathTech specializes in residential-scale helical systems with modular bracket configurations for deck and fence foundations.
Screw piles are steel shafts with one or more helical plates welded to the lead section, typically installed by torque application to achieve specified embedment depths and load capacities measured in kilonewtons. The product serves as a deep foundation alternative to driven piles or concrete piers, transmitting structural loads through bearing on stable soil strata. Helical and displacement product types dominate current volume, with displacement variants capturing margin pools in urban infill projects where vibration restrictions apply. Foundation applications lead value generation, while earth retention segments show accelerated specification rates in slope-stabilization contracts across mountainous terrain.
ISO 19901-4 offshore foundation standards, ECHA REACH restrictions on hexavalent chromium coatings, and local building codes in seismic zones collectively shape product certification requirements and material selection protocols. The EU Green Deal embodied-carbon tracking rules are pushing manufacturers toward recycled-content steel sourcing and lifecycle-assessment documentation. Stakeholders must monitor evolving torque-capacity verification protocols and soil-condition warranty terms as competitive differentiation shifts from product supply to performance-guaranteed installation contracts.
Market Dynamics
EU Green Deal embodied-carbon tracking rules are forcing screw pile manufacturers toward recycled-content steel sourcing and lifecycle-assessment documentation, compressing legacy supply chains that relied on virgin material flows.
Growth Catalysts
- Offshore wind procurement mandates:Northern European developers are expanding galvanized steel helical pile orders to satisfy ECHA corrosion-resistance requirements for subsea foundations.
- Composite shaft innovation:Reinforced polymer-steel hybrid designs from Canadian fabricators are penetrating permafrost zones across Siberia and Alaska where thermal contraction resistance is critical.
- Seismic zone building codes:Updated structural standards in Japan and California are specifying torque-verified helical piles for residential and commercial foundations in liquefaction-prone soils.
Market Restraints
- Zinc price volatility:Hot-dip galvanizing cost swings tied to London Metal Exchange zinc futures are squeezing margin pools for coating-dependent product lines.
- Specialized torque equipment concentration:High-capacity installation rigs remain concentrated among German and US equipment lessors, creating bottleneck risks for project mobilization.
- Displacement pile substitution:Auger cast-in-place systems are capturing urban infill share where vibration restrictions previously favored helical alternatives.
Strategic Opportunities
- India infrastructure buildout:National highway expansion and renewable energy parks are creating first-mover openings for screw pile suppliers in a historically concrete-dominated foundation market.
- EU circular economy incentives:Recycled steel content mandates under the EU Green Deal are rewarding manufacturers with documented scrap-to-product traceability systems.
- Drone-based site survey integration:LiDAR-enabled geotechnical assessment is unifying with automated torque monitoring to compress pre-installation timelines for remote projects.
Industry Challenges
- ISO 19901-4 certification timelines:Offshore foundation qualification protocols are extending product approval cycles by 12-18 months for new helical pile geometries.
- Geotechnical engineer scarcity:Specialized torque-capacity verification expertise remains concentrated among aging practitioners in North America and Northern Europe.
- Legacy concrete contractor resistance:Established foundation trades in mature markets are slowing helical specification through specification inertia and warranty risk aversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Screw Piles Market |
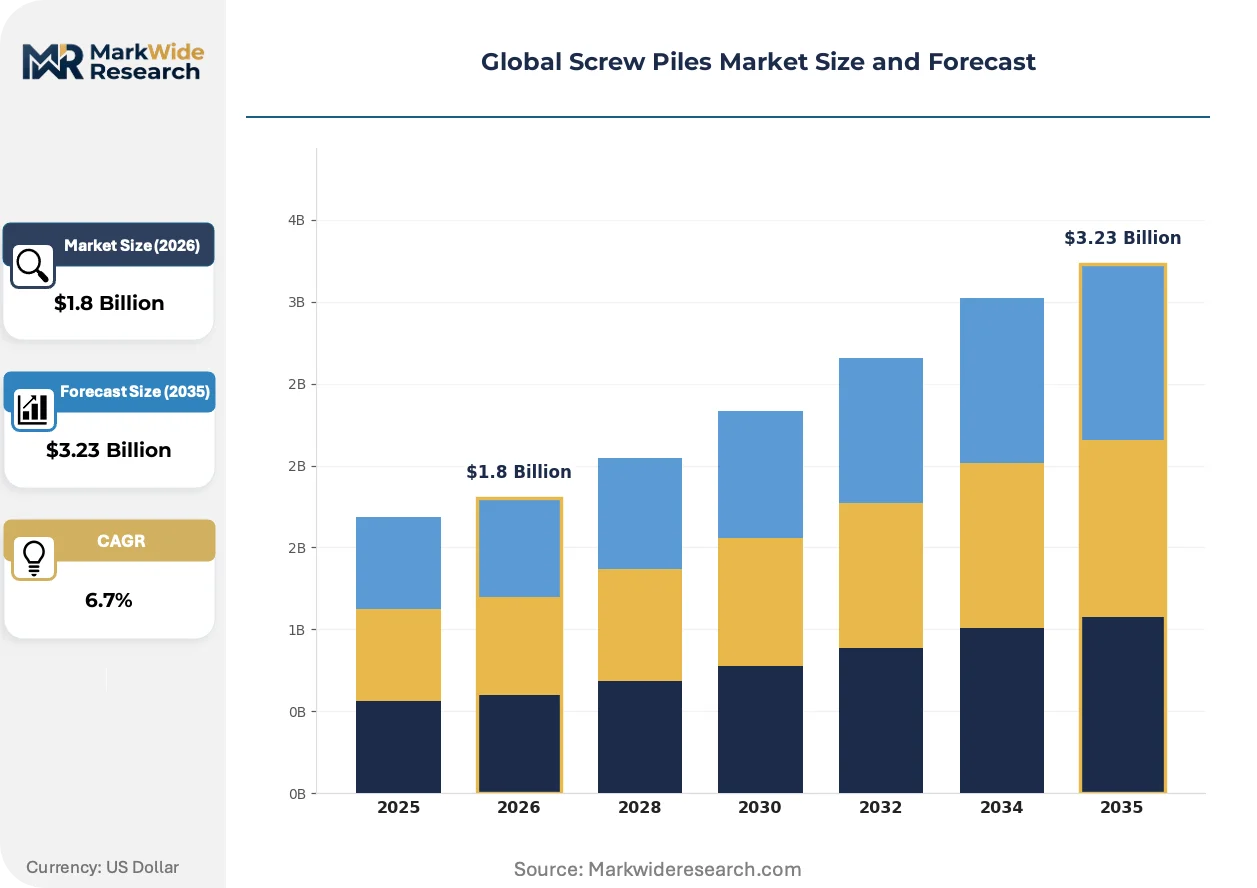
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helical, Displacement, Expandable, Specialty Application: Construction, Landscaping, Earth Retention, Foundation End User: Residential, Commercial, Industrial, Infrastructure Installation Method: Mechanical, Manual, Hydraulic, Self-Installing |
| Companies Covered | Helical Anchors Inc, TorcSill, GoliathTech, Hubbell Power Systems - Chance, Simpson Strong-Tie, Ram Jack Systems, RADIX, Keller Group, Cyntech Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Screw Piles Market Strategic Shifts
Digital torque monitoring and predictive geotechnical modeling are compressing installation timelines while regulatory carbon accounting is reshaping material sourcing protocols across the foundation sector.
Modular bracket systems are unifying residential-scale helical piles with standardized deck, fence, and solar racking connections. US and Canadian contractors are specifying these configurations for single-day foundation completion. This unification is collapsing the traditional separation between structural pile supply and finish carpentry trades, forcing manufacturers to expand hardware SKU breadth.
REACH restrictions on hexavalent chromium coatings are eliminating legacy corrosion protection chemistries from EU supply chains. ECHA enforcement is accelerating migration toward trivalent chromium and zinc-aluminum alloy alternatives. Offshore wind contractors in the North Sea and Baltic are absorbing premium coating costs to maintain ECHA compliance on 25-year design-life foundations.
Performance-guaranteed installation contracts are displacing traditional product-only procurement in commercial and industrial segments. Engineering-procurement-construction firms in Germany and Australia are bundling torque-verified capacity warranties with pile supply. This shift concentrates risk with installers and favors vertically integrated providers with captive geotechnical design capabilities.
Global Screw Piles Market Segmentation
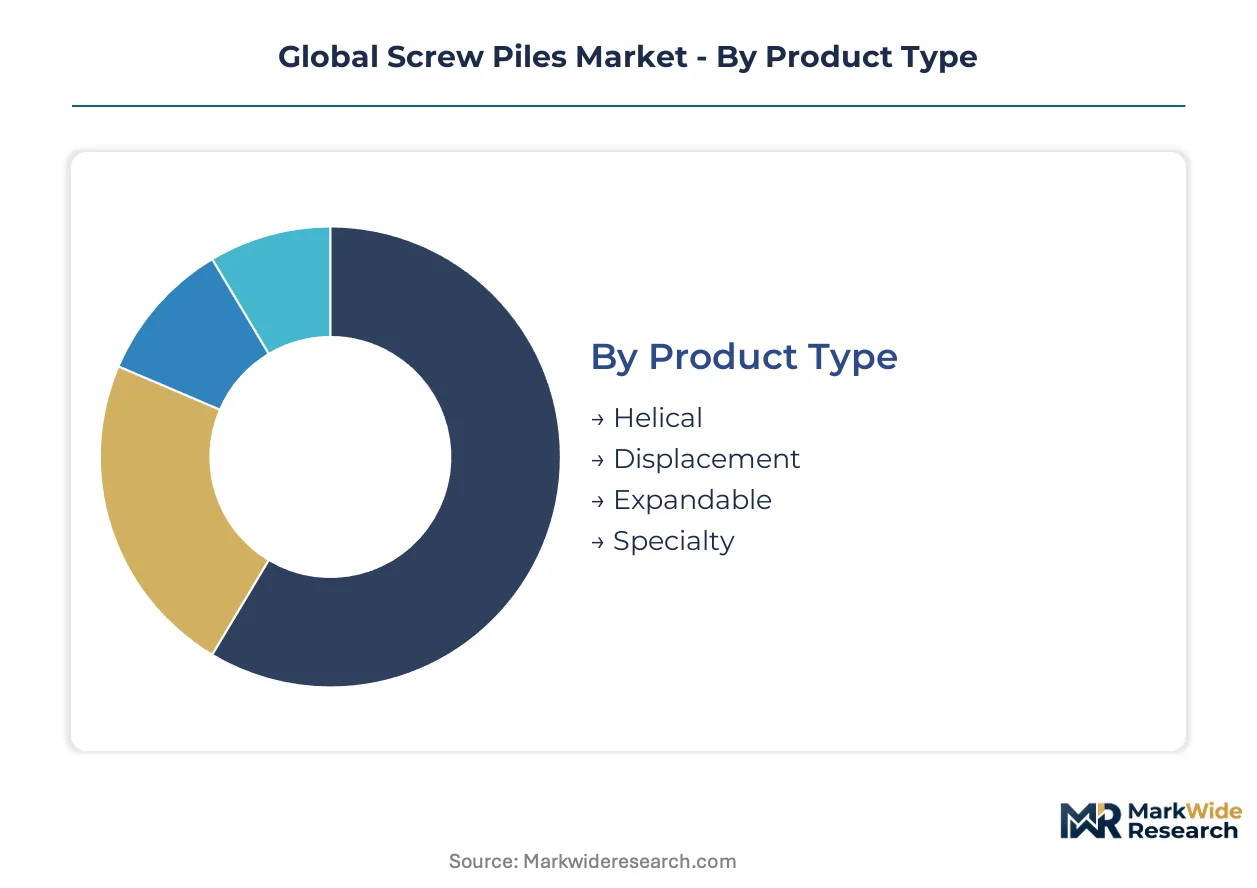
Screw pile segmentation reflects competing technical specifications against project constraints. Specification choices determine torque requirements, corrosion protection levels, and installation economics across foundation applications.
Product Type:
Shaft geometry and soil displacement mechanics define performance ceilings and regulatory compliance pathways.
- Helical:Steel shafts with welded helical plates transmit bearing loads through torque-driven embedment into stable strata. Northern European offshore wind developers specify these for ECHA-mandated corrosion-resistant subsea foundations.
- Displacement:Continuous flight auger designs minimize soil removal and vibration, capturing urban infill projects where neighboring structure protection is mandatory. German and Japanese contractors favor these for dense metropolitan zones with strict disturbance ordinances.
- Expandable:Post-installation expansion mechanisms increase bearing surface area in loose or variable soils. Australian mining camp foundations and Middle East desert solar installations deploy these for rapid capacity verification.
- Specialty:Composite-reinforced or thermally insulated variants address permafrost, seismic liquefaction, or chemically aggressive environments. Canadian fabricators lead supply for Siberian and Alaskan oilfield infrastructure.
Helical piles lead on scale; displacement piles lead on momentum in urban regulatory environments.
Application:
Load-bearing requirements and soil interaction complexity segment demand by project engineering intensity.
- Foundation:Primary structural support for buildings, towers, and heavy equipment transmits vertical and lateral loads through bearing and friction. Japanese and California seismic codes now mandate torque-verified helical systems in liquefaction-prone zones.
- Construction:Temporary access platforms, crane pads, and modular building supports require rapid deployment and extraction. US and Canadian oilfield service contractors drive volume for drill rig matting and pipeline compression stations.
- Earth Retention:Slope stabilization, retaining walls, and landslide mitigation employ screw piles as tie-back anchors. Mountainous terrain across Italy, Switzerland, and Chile generates accelerated specification for infrastructure protection contracts.
- Landscaping:Residential decks, fences, and garden structures utilize small-diameter helical systems with modular brackets. North American big-box retailers stock these for single-day DIY foundation completion.
Foundation applications anchor revenue concentration; earth retention climbs fastest on climate-adaptation infrastructure spending.
End User:
Procurement sophistication and warranty requirements separate customer tiers by technical specification depth.
- Infrastructure:Highway authorities, rail operators, and utility transmission entities demand ISO-certified products with documented lifecycle assessments. EU Green Deal recycled-content mandates are reshaping steel sourcing protocols for German and French public tenders.
- Industrial:Manufacturing facilities, warehouses, and energy processing plants require high-load capacity with minimal settlement tolerance. US Gulf Coast petrochemical expansions and Middle East desalination plants specify hot-dip galvanized systems for corrosive environments.
- Commercial:Office buildings, retail centers, and hospitality structures balance speed-to-market with structural performance. Australian engineering-procurement-construction firms are bundling performance-guaranteed installation contracts in this segment.
- Residential:Single-family homes and small multi-family structures prioritize cost efficiency and rapid installation. Modular bracket systems from Canadian and US suppliers collapse foundation and finish carpentry timelines.
Infrastructure commands specification authority; residential delivers volume velocity through standardized product lines.
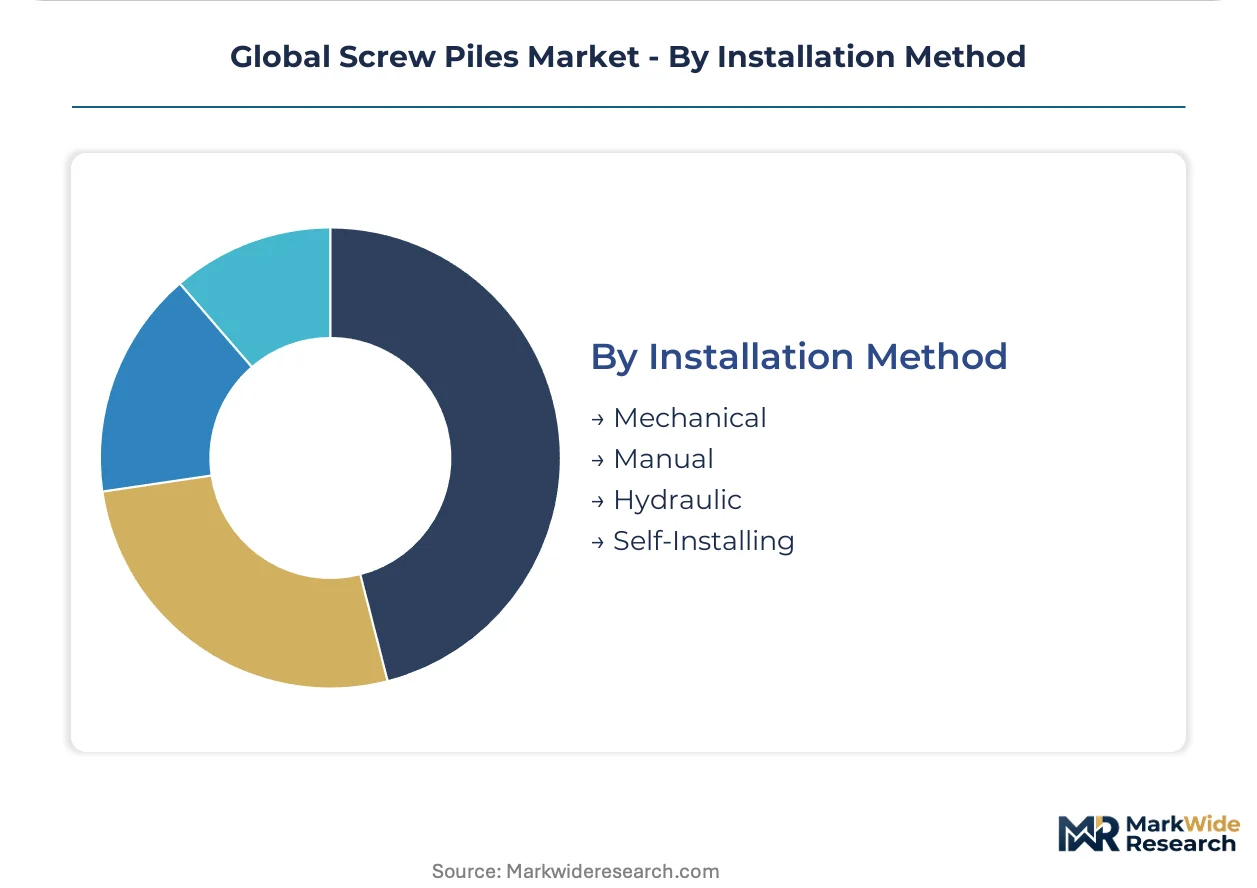
Installation Method:
Equipment capital intensity and labor skill requirements determine market access barriers and project mobilization speed.
- Hydraulic:High-torque rotary drives mounted on excavators or dedicated rigs achieve deep embedment in dense soils and rock. German and US equipment lessors concentrate capacity for offshore wind and heavy industrial foundations.
- Mechanical:Skid-steer and mini-excavator attachments serve medium-load commercial and residential projects with moderate torque demands. North American rental yards stock these for contractor fleet flexibility.
- Manual:Hand-held torque motors and portable drive heads enable restricted-access installations and small-diameter piles. Japanese seismic retrofit contractors and European historic preservation specialists specify these for interior basement work.
- Self-Installing:Gravity-assisted or vibratory systems reduce equipment footprint for remote or environmentally sensitive sites. Arctic research stations and tropical rainforest canopy walkways deploy these where machinery transport is prohibitive.
Hydraulic systems dominate value capture; mechanical methods expand most quickly through equipment rental channel penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea offshore wind cluster drives galvanized steel helical pile procurement as Danish and German developers expand subsea foundation programs.
United States
Gulf Coast petrochemical expansions and California seismic retrofits sustain demand for torque-verified helical systems. FEMA building code updates in liquefaction-prone zones mandate documented installation protocols. Houston fabricators supply hot-dip galvanized shafts for corrosive coastal environments.
Germany
Engineering-procurement-construction firms bundle performance-guaranteed installation contracts with pile supply for commercial developments. EU Green Deal recycled-content steel mandates reshape sourcing for public infrastructure tenders. The Ruhr industrial corridor concentrates fabrication capacity serving North Sea offshore wind projects.
Canada
Permafrost zone infrastructure across Alberta and the Northwest Territories deploys composite-reinforced shaft designs for thermal contraction resistance. National building code harmonization accelerates helical specification in remote mining and oilfield camps. Calgary-based manufacturers lead supply for Siberian and Alaskan export markets.
Japan
Seismic zone residential and commercial construction specifies torque-verified helical piles following updated structural standards for liquefaction-prone soils. METI efficiency regulations push automated torque monitoring adoption. Osaka contractors specialize in restricted-access manual installation for historic preservation and basement retrofit work.
Australia
Mining camp foundations and desert solar installations deploy expandable screw piles for rapid capacity verification in variable soils. Engineering-procurement-construction firms pioneer bundled installation warranties. Perth fabricators serve remote resource projects where machinery transport constraints favor self-installing systems.
Global Screw Piles Market Competitive Environment
Global majors compete with regional champions across installation service bundling and geotechnical design integration. The vendor base stratifies between vertically integrated foundation contractors, specialized helical fabricators, and diversified construction hardware suppliers. Three archetypes dominate: torque-verified installation specialists, modular residential-scale system providers, and offshore-certified heavy industrial suppliers. Competitive moves concentrate on backward integration into captive galvanizing capacity and strategic partnerships with equipment lessors.
Among North American fabricators, TorcSill and GoliathTech exemplify contrasting positioning within the helical foundation segment. TorcSill occupies a position as a vertically integrated provider with captive coating operations, while GoliathTech anchors the residential-scale modular bracket tier. Keller Group represents the engineering-procurement-construction bundling archetype among UK-registered firms.
| Leading Market Players |
|---|
| Helical Anchors Inc |
| TorcSill |
| GoliathTech |
| Hubbell Power Systems - Chance |
| Simpson Strong-Tie |
| Ram Jack Systems |
| RADIX |
| Keller Group |
| Cyntech Group |
| Others |
Value Chain & Pricing Dynamics
Offshore wind engineering-procurement-construction firms concentrate procurement authority for galvanized steel helical piles, locking in project-based pricing with long-term coating-cost pass-through clauses indexed to London Metal Exchange zinc futures.
Pricing Analysis
Input-cost pass-through dominates pricing architecture, with hot-dip galvanizing expenses flowing directly to buyers through zinc-indexed contract adjustments. Three-tier pricing structure across premium, standard, and economy levels separates ISO 19901-4 certified offshore products from commercial foundation systems and residential modular brackets. Pricing pressure stems from volatile zinc futures compressing margin pools for coating-dependent product lines. Residential contractors exhibit highest price sensitivity, while offshore wind developers absorb premium coating costs to maintain ECHA compliance on 25-year design-life foundations.
Supply Chain Analysis
EU Green Deal recycled-content mandates are forcing manufacturers toward scrap-to-product traceability systems and domestic steel sourcing. Supply concentration centers on Germany, the United States, and Canada, with Ruhr corridor fabricators serving North Sea offshore projects and Calgary-based producers exporting composite-reinforced shafts to Siberian permafrost zones. Raw material dependencies rest on high-strength steel coil, zinc ingot for galvanizing, and polymer composites for thermal-resistant variants. Single-source vulnerability concentrates in German and US high-capacity torque equipment lessors. Distribution runs through engineering-procurement-construction bundlers for commercial and industrial segments, with direct-to-contractor channels dominating residential modular bracket sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through captive galvanizing capacity and performance-guaranteed installation contracts that capture premium pricing from risk-averse offshore wind developers.
For Market Incumbents: Acquire captive galvanizing operations to insulate margin pools from zinc price volatility and control coating quality across distribution networks. Expand torque-verified installation service bundling to defend against displacement pile substitution in urban infill markets. Prioritize ISO 19901-4 certification investment for offshore foundation geometries to extend approval timelines as a competitive moat. For New Entrants and Emerging Players: Drone-based LiDAR geotechnical assessment technology offers a technology-first wedge for remote project mobilization where established players lack automated site survey integration. Target Indian highway expansion and renewable energy parks as first-mover openings in a historically concrete-dominated foundation market. Pursue equipment-lessor partnerships to bypass capital barriers in high-torque hydraulic rig concentration. For Investors and Strategic Acquirers: Engineering-procurement-construction firms are the most active acquirer in this space, seeking vertically integrated foundation capabilities to bundle performance-guaranteed installation contracts. Long-term viability hinges on circular economy compliance and embodied-carbon documentation proficiency. Monitor ECHA enforcement intensity on hexavalent chromium REACH restrictions as the signal indicating coating technology inflection and stranded asset risk in legacy chemistries.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Galvanizing | TorcSill controls coating quality and zinc cost exposure across North American distribution networks. |
| Performance-Guaranteed Installation Contracts | Keller Group bundles torque-verified capacity warranties with pile supply for German commercial developments. |
| Composite-Reinforced Shaft Development | Canadian fabricators penetrate Siberian and Alaskan permafrost zones with thermal contraction-resistant designs. |
| Drone-Based Site Survey Integration | LiDAR-enabled geotechnical assessment compresses pre-installation timelines for remote Arctic and tropical projects. |
| EU Circular Economy Compliance Documentation | Scrap-to-product traceability systems unlock public infrastructure tenders under Green Deal recycled-content mandates. |
Study Parameters
Coverage spans North America, Northern Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation across trade and regulatory databases. Primary interviews engaged foundation contractors, geotechnical engineers, equipment lessors, and offshore wind project developers, supplemented by secondary analysis of ISO certification registries, ECHA REACH filings, EU tender databases, and customs trade flows. Bottom-up project pipeline tracking triangulates with top-down steel consumption estimates.
Granularity-level modeling disaggregates volume and value across product type, application, end user, and installation method dimensions, with additional segmentation by corrosion protection grade and torque capacity tier. CAGRs derive from fitted growth curves applied to project-based demand forecasts. Industry-specific inputs include offshore wind capacity installation pipelines, seismic code adoption timelines in Japan and California, and permafrost infrastructure spending across Alberta and the Northwest Territories.
The model holds under continued ECHA corrosion-resistance mandate enforcement and EU Green Deal recycled-content trajectory; deviation in zinc price volatility extremes or ISO 19901-4 certification timeline extensions would shift supply-side capacity deployment. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Steel Service Centers Market
Building & Construction Materials
Tower Bolt Market
Building & Construction Materials
United States I-Joist Market
Building & Construction Materials
North America Concrete Cellulose Fiber Reinforcement Market
Building & Construction Materials
North America Residential Water Heater Market
Building & Construction Materials
Global Raised Access Floor Systems Market
Building & Construction Materials
Dimension Stone Market
Building & Construction Materials
Ceiling Tiles Market
Building & Construction Materials
Cleanroom Flooring Market
Building & Construction Materials
Brick Market
Building & Construction Materials
Curtain Wall Market
Building & Construction Materials
Germany Foam Insulation Market
Building & Construction Materials
Global Formwork Market
Building & Construction Materials
North America Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
North America Particle Board Market
Building & Construction Materials
United Kingdom Timber Cladding Market