
 Israel Ceramic Tiles Market | 2026-2036
Israel Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Israel Ceramic Tiles Market Outlook
Israeli Standard SI 984 certification is bifurcating the competitive landscape into qualified suppliers and marginal participants. Caesarstone Ltd leverages its quartz-composite expertise to anchor premium positioning across kitchen and bath segments. Negev Ceramics Ltd sustains domestic manufacturing scale with fired-clay capacity in the southern district. Marazzi Group competes through imported porcelain collections distributed via national retail partnerships.
Ceramic tiles are thin, flat slabs manufactured from clay, silica, and flux minerals, fired at temperatures exceeding 1,000°C to achieve hardness and water resistance below 0.5% absorption for porcelain grades. Their primary purpose spans interior flooring, wall cladding, and exterior facades where durability and aesthetic customization matter. Porcelain tiles command structural margin pools due to density and through-body color advantages in high-traffic commercial spaces. Mosaic tiles occupy artisanal niches in restoration and luxury residential projects across Jerusalem's historic districts. Digital printing technology is displacing traditional screen methods, enabling batch-size-one customization that reshapes inventory economics for distributors.
The Israeli Standards Institute (SII) mandates SI 984 compliance for slip resistance and chemical durability, filtering import channels and elevating local testing costs. The Ministry of Environmental Protection enforces emissions controls on kiln operations, pushing producers toward natural gas conversion or filtration investments. The Ministry of Finance's construction-linked VAT framework indirectly steers tile specification through contractor procurement behavior. Stakeholders must monitor how SII's anticipated expansion of recycled-content thresholds will reshape raw-material sourcing and supplier qualification timelines.
Market Dynamics
Digital printing technology is decomposing traditional ceramic tile manufacturing economics in Israel, compressing batch minimums and enabling mass customization that redraws competitive boundaries between domestic producers and import channels.
Growth Catalysts
- Luxury residential construction:Tel Aviv and Jerusalem's high-end housing developments specify large-format porcelain tiles with through-body color consistency, pulling volume toward premium-grade domestic and imported collections.
- SI 984 certification expansion:The Israeli Standards Institute's stricter slip-resistance and chemical-durability thresholds filter marginal import suppliers, consolidating qualified vendor relationships with established distributors.
- Natural gas kiln conversion:Ministry of Environmental Protection emissions mandates accelerate capital deployment toward cleaner firing technologies, reducing particulate output and qualifying producers for green building credit specifications.
Market Restraints
- Feldspar and kaolin import dependency:Raw material sourcing concentrates on Turkish and Spanish suppliers, exposing margins to shipping-rate volatility and currency fluctuation against the shekel.
- SII testing cost burden:Certification laboratory fees and sample submission timelines add fixed overhead that disadvantages smaller distributors against vertically integrated retail chains.
- Engineered stone substitution:Quartz-composite surfacing materials capture kitchen countertop specifications that ceramic tiles historically dominated, narrowing the addressable residential renovation market.
Strategic Opportunities
- Recycled-content thresholds:Anticipated SII expansion of post-industrial waste incorporation requirements creates first-mover advantage for producers with established supply partnerships with glass and construction debris processors.
- Negev manufacturing cluster:Southern district industrial zones offer land and energy cost arbitrage versus central Israel, supporting fired-clay capacity expansion with lower per-unit overhead.
- Digital-to-physical workflow integration:Convergence of 3D surface scanning and inkjet deposition enables batch-size-one replication of Jerusalem stone and historic mosaic patterns for restoration architects.
Industry Challenges
- Glaze formulation chemistry expertise:Digital printing adoption outpaces the domestic talent pipeline for color-matching and ink rheology optimization, forcing reliance on foreign equipment vendor training programs.
- Legacy distributor inventory systems:Small-format tile SKUs accumulated under screen-printing economics resist SKU rationalization, tying working capital to obsolete patterns with declining turn rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Israel Ceramic Tiles Market |
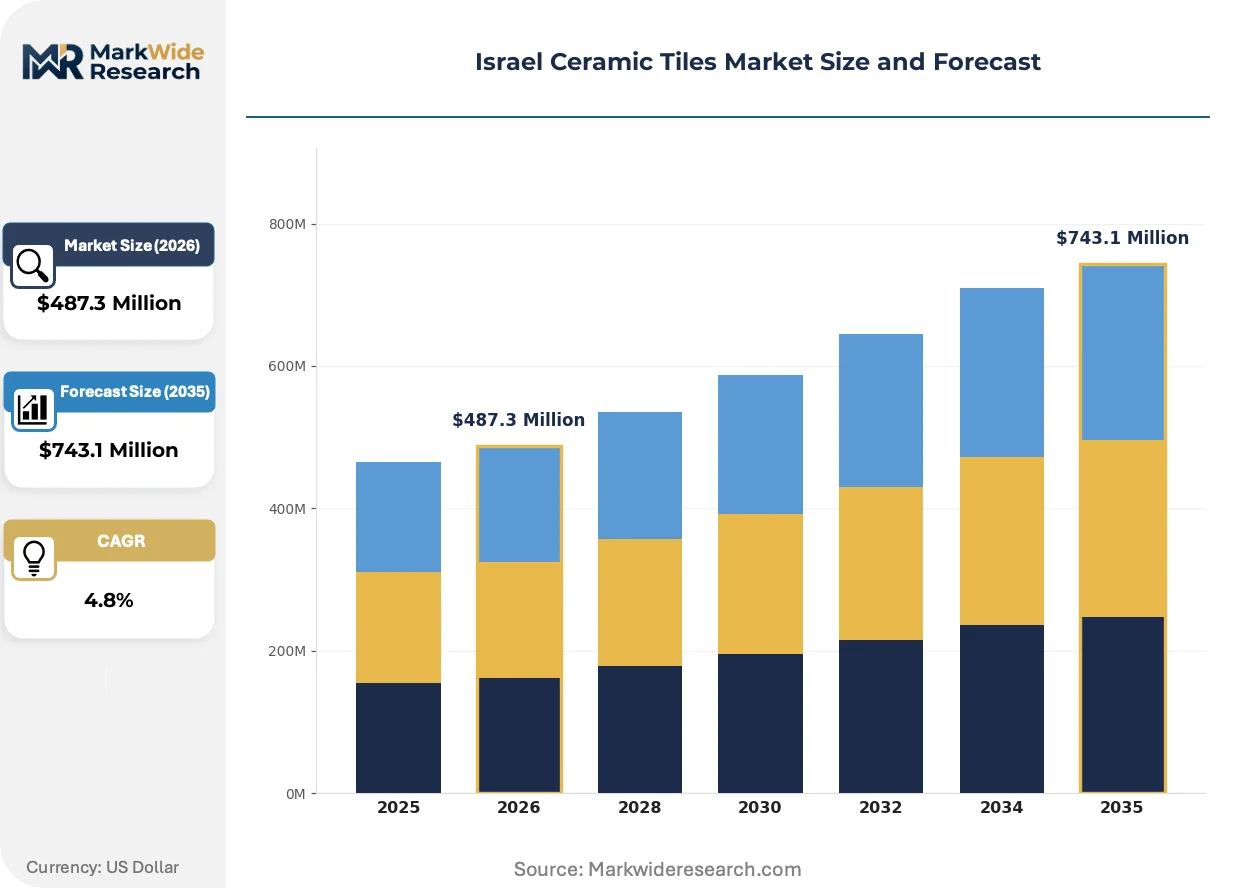
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glazed Tiles, Porcelain Tiles, Terracotta Tiles, Mosaic Tiles End User: Residential Buildings, Commercial Spaces, Industrial Facilities, Outdoor Applications Technology: Digital Printing, Traditional Printing, Pressed Technique, Extrusion Method Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Distributors |
| Companies Covered | Caesarstone Ltd, Negev Ceramics Ltd, Marazzi Group, Zuk Marble Products Ltd, Pekiin Tiles, Balian Armenian Ceramics Tiles of Jerusalem, Milstone Marble Works Ltd, Harash, Ceramic Depot, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Israel Ceramic Tiles Market Strategic Shifts
Production technology and certification requirements are simultaneously compressing manufacturing batch sizes and elevating performance specifications, forcing asset-light business models and capital-heavy compliance investments.
Inkjet digital printing is decomposing the economics of ceramic tile decoration by eliminating screen-making costs and setup waste. Luxury residential developers in Herzliya Pituach and Caesarea now specify single-batch custom patterns for individual penthouse projects. This capability compresses distributor inventory requirements while fragmenting supplier relationships toward technology-integrated manufacturers.
The Israeli Standards Institute's SI 984 certification protocol tightens slip-resistance testing protocols for wet-area installations. Bathroom and pool-deck specifications now require documented coefficient-of-friction ratings that many Mediterranean import suppliers cannot consistently achieve. Domestic producers with in-house laboratory capabilities capture specification authority in hospitality and healthcare verticals.
Architect specification behavior is rotating toward performance-documented materials with environmental product declarations. Ministry of Finance construction-linked VAT frameworks indirectly reward contractors who source SII-certified tiles with traceable recycled content. This preference shift concentrates procurement authority with national retail chains that maintain dedicated compliance documentation teams.
Israel Ceramic Tiles Market Segmentation
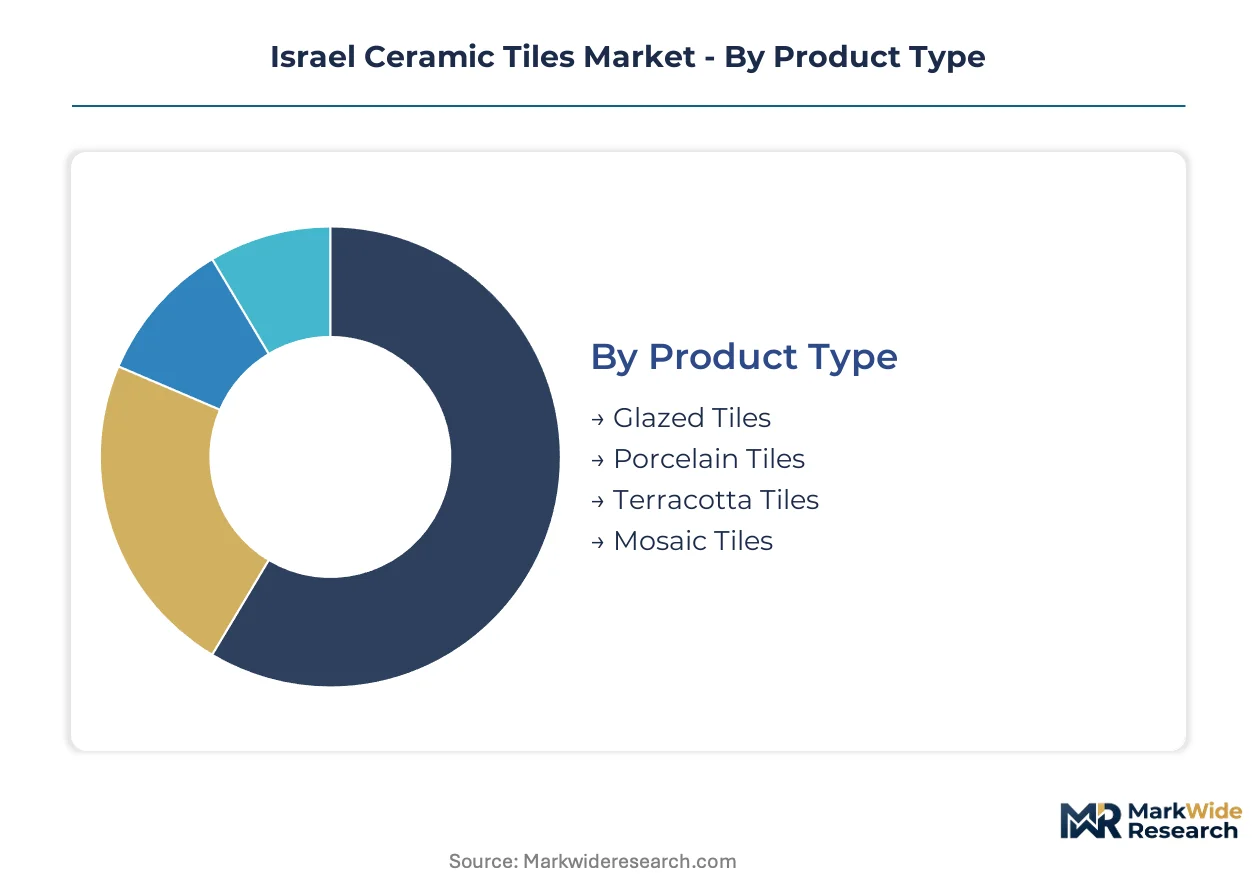
Segmentation in Israel's ceramic tiles market reveals how certification requirements and digital capabilities reshape channel economics. Each dimension exposes different pressure points on margin capture and supplier qualification.
Product Type:
Channel mix varies sharply across product types, with porcelain and glazed tiles flowing through national retail chains while mosaic and terracotta segments rely on specialized distributors with restoration expertise.
- Glazed Tiles:Clay-based slabs with vitreous surface coating fired at moderate temperatures, offering color variety at accessible price points. Demand concentrates in central Israel's mid-market residential renovations where budget constraints meet SII slip-resistance requirements for wet areas.
- Porcelain Tiles:Dense, low-absorption ceramics fired above 1,200°C with through-body color consistency. Tel Aviv luxury developers specify large-format porcelain for high-rise residential lobbies and penthouse flooring where durability and aesthetic uniformity justify premium positioning.
- Terracotta Tiles:Unglazed, porous clay products traditional to Mediterranean architecture. Jerusalem restoration architects source these for historic district facades requiring material authenticity.
- Mosaic Tiles:Small-format tesserae assembled in mesh-mounted sheets. Artisanal workshops in Jaffa and Safed supply custom patterns for boutique hospitality projects.
By volume, glazed tiles lead. By growth pace, porcelain is ahead.
End User:
Cost tier stratification separates specification authority, with commercial and industrial buyers demanding performance documentation that residential and outdoor segments rarely require.
- Residential Buildings:Single-family homes and multi-unit housing developments specify tiles across all price tiers, with central Israel luxury projects driving porcelain adoption and peripheral regions maintaining glazed tile dominance.
- Commercial Spaces:Retail, hospitality, and office installations require SII-certified slip resistance and documented environmental product declarations. Hospital and hotel procurement teams source through qualified distributors with compliance documentation capabilities.
- Industrial Facilities:Manufacturing plants and warehouses prioritize chemical resistance and load-bearing capacity over aesthetics. Negev manufacturing zones generate localized demand for heavy-duty porcelain with abrasion-resistant surfaces.
- Outdoor Applications:Pool decks, terraces, and public plazas face strict wet-area friction requirements. Mediterranean climate exposure demands frost-resistant porcelain grades that many import suppliers cannot consistently deliver.
Residential captures the largest revenue pool. Commercial applications are expanding most quickly.
Technology:
Volume concentration favors traditional methods in commodity segments, while margin capture concentrates with digital capabilities in premium and custom specifications.
- Digital Printing:Inkjet deposition enables photorealistic surface replication and batch-size-one customization. Herzliya Pituach developers commission single-run Jerusalem stone patterns for individual penthouse projects, compressing inventory requirements while fragmenting supplier relationships.
- Traditional Printing:Screen-based glaze application persists in high-volume standardized production. Cost efficiency sustains market presence in peripheral housing developments with limited customization requirements.
- Pressed Technique:Dry powder compaction forms dense ceramic bodies. Standard for porcelain manufacturing across Israeli producers with natural gas kiln capacity.
- Extrusion Method:Clay forcing through dies creates hollow or profiled shapes. Limited to specialized architectural terracotta and structural clay products.
Traditional printing still dominates unit volume. Digital printing claims the steepest expansion trajectory.
Distribution Channel:
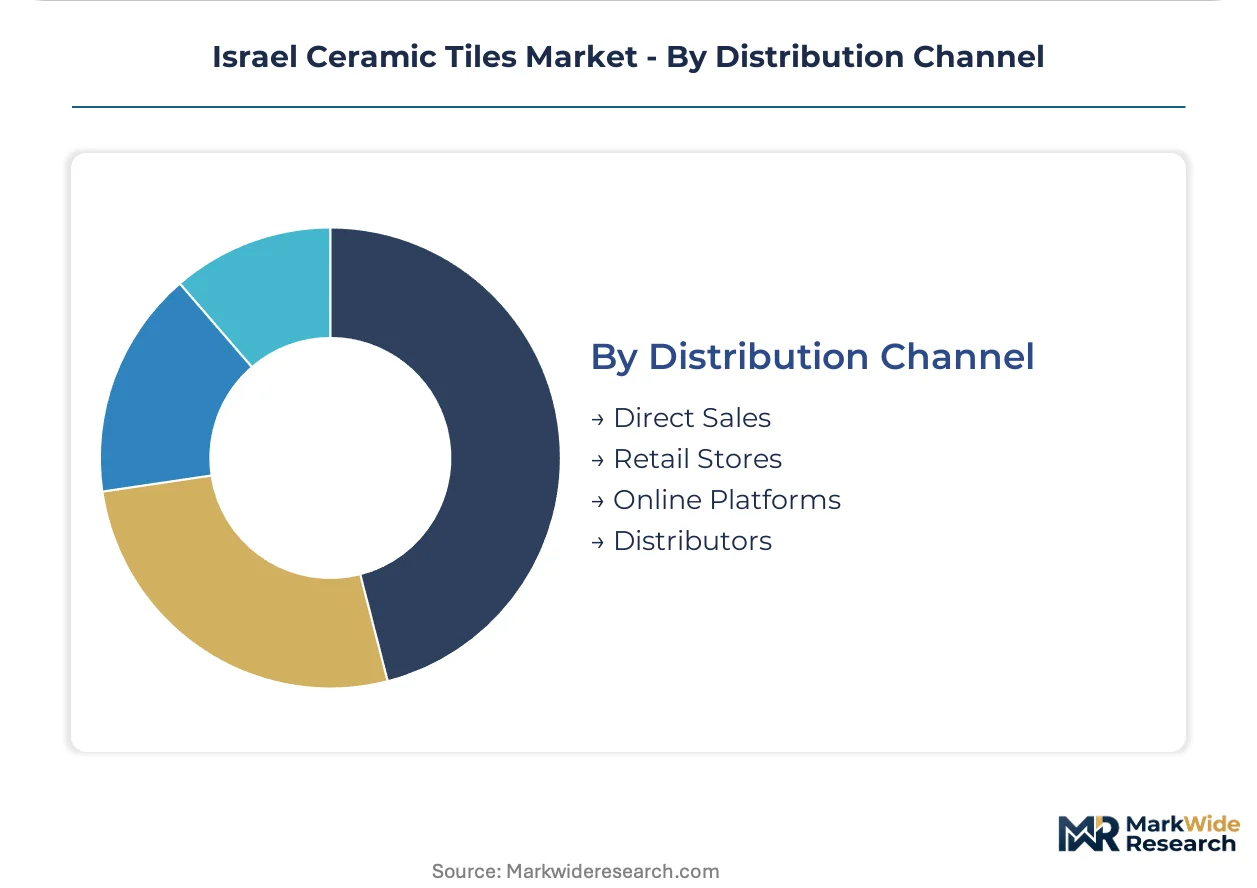
Customer type determines channel selection, with contractors and architects favoring direct relationships while retail consumers and small renovators default to accessible storefronts.
- Direct Sales:Manufacturer-to-contractor relationships for large-scale developments. Caesarstone and Negev Ceramics maintain specification engineers who interface directly with Tel Aviv project architects.
- Retail Stores:National chains with showroom displays and in-house design consultation. Concentrate volume in central Israel's renovation-driven suburbs.
- Online Platforms:Emerging channel for standardized products with documented specifications. Growth constrained by tactile evaluation requirements and SII certification verification challenges.
- Distributors:Regional wholesalers linking import suppliers with local retailers. Inventory risk concentrates here as digital printing compresses batch economics.
Retail stores lead by transaction volume. Direct sales are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Luxury residential developers in Tel Aviv and Jerusalem concentrate procurement authority, while industrial buyers in the Negev and northern districts anchor volume demand for heavy-duty specifications.
Central District
Tel Aviv's high-rise residential towers and Herzliya Pituach luxury developments specify large-format porcelain with through-body color consistency. The Ministry of Finance's construction-linked VAT framework indirectly steers contractor procurement toward SII-certified suppliers. Industrial zones around Petah Tikva host distributor showrooms that maintain dedicated compliance documentation teams for commercial specifications.
Jerusalem District
Historic district restoration projects and boutique hospitality developments drive demand for artisanal mosaic and terracotta authenticity. Jerusalem's municipal preservation codes mandate material compatibility with Ottoman and British Mandate-era architecture. Artisan workshops in the Old City and adjacent industrial areas supply custom tesserae patterns for heritage-sensitive renovations.
Southern District
Negev manufacturing clusters leverage land and natural gas cost arbitrage versus central Israel for fired-clay capacity expansion. The Ministry of Environmental Protection's emissions mandates accelerate kiln conversion investments in Be'er Sheva industrial zones. Heavy-duty porcelain for industrial flooring concentrates procurement relationships with Negev-based producers serving local manufacturing plants.
Haifa District
Northern Israel's port infrastructure facilitates import channels for Mediterranean porcelain collections. Haifa's chemical and manufacturing sectors generate steady demand for chemical-resistant industrial tile specifications. Regional distributors here manage inventory exposure as digital printing compresses batch economics and import lead times fluctuate.
Northern District
Galilee residential construction and kibbutz industrial renovations sustain mid-market glazed tile volume. Safed's artisan community supplies decorative mosaic for regional hospitality projects. The district's distance from central certification laboratories elevates logistics costs for SII compliance verification.
Israel Ceramic Tiles Market Competitive Environment
Player mix skews toward domestic manufacturers with kiln assets and import-dependent distributors with retail scale. Market structure concentrates qualified supply around SII-certified producers while fragmenting marginal participation among uncertified import channels. Three archetypes dominate: vertically integrated domestic manufacturers, national retail chains with compliance documentation capabilities, and specialized artisan workshops serving restoration niches. Competitive moves center on natural gas kiln conversion for emissions compliance and digital printing technology licensing for customization capabilities.
Among Israel-based producers, Caesarstone Ltd and Negev Ceramics Ltd occupy positions within the domestic manufacturing tier, while Marazzi Group exemplifies the import-channel archetype with Mediterranean-sourced porcelain distribution. Caesarstone represents quartz-composite expertise extending into premium surfacing segments. Negev Ceramics sits within the southern manufacturing cluster with fired-clay capacity serving industrial and residential specifications. Marazzi anchors the import-dependent retail partnership model for large-format porcelain collections.
| Leading Market Players |
|---|
| Caesarstone Ltd |
| Negev Ceramics Ltd |
| Marazzi Group |
| Zuk Marble Products Ltd |
| Pekiin Tiles |
| Balian Armenian Ceramics Tiles of Jerusalem |
| Milstone Marble Works Ltd |
| Harash |
| Ceramic Depot |
| Others |
Value Chain & Pricing Dynamics
Natural gas kiln capacity utilization at Negev manufacturing clusters anchors scale economies that compress per-unit firing costs and establish price floors domestic competitors struggle to breach. Turkish feldspar and Spanish kaolin import contracts, indexed to Mediterranean shipping rates and euro-shekel cross-rates, transmit volatility directly into landed raw material costs that reshape procurement timing and inventory depth decisions.
Pricing Analysis
Cost-plus contracts with Turkish feldspar suppliers tie glaze formulation costs to Baltic Dry Index movements, forcing domestic producers to absorb currency swing exposure or pass through via quarterly price adjustments. Three-tier pricing structure across SII-certified premium, standard-grade domestic, and uncertified import economy levels separates specification authority in commercial verticals from price-sensitive residential renovation segments. Pricing pressure stems from engineered stone substitution in kitchen countertop applications, compressing ceramic tile addressable share in the residential renovation tier. Small distributors face acute price sensitivity as SII laboratory testing fees and sample submission timelines add fixed overhead that national retail chains amortize across higher volume throughput.
Supply Chain Analysis
Haifa port congestion and container availability fluctuations on the Turkey-Israel trade lane elevate inbound logistics costs and extend order-to-delivery windows for Mediterranean porcelain collections. Geographic supply concentration centers on Turkey for feldspar and glaze minerals, Spain for high-grade kaolin, and Italy for digital printing equipment and ink formulations. Raw material dependencies rest on flux minerals for vitreous body formation, zirconium silicates for opacity control, and proprietary ink chemistries for digital surface decoration. Single-source vulnerability concentrates in Italian inkjet equipment vendors whose training programs and spare parts networks dominate technology transfer pathways. Distribution runs through national retail chains with dedicated SII compliance documentation teams serving commercial specification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital printing technology disruption compresses batch minimums and fragments supplier relationships, creating acceleration windows for technology-integrated manufacturers while threatening screen-printing legacy capacity. SI 984 certification expansion filters marginal import channels and consolidates qualified vendor relationships with established domestic producers.
For Market Incumbents: Shield specification authority in hospitality and healthcare verticals by deepening in-house SII laboratory capabilities and documented environmental product declaration portfolios. Defend against engineered stone substitution by extending quartz-composite expertise into premium surfacing segments that anchor kitchen and bath project relationships. Prioritize natural gas kiln conversion investments in Negev manufacturing clusters to capture green building credit specifications and emissions compliance advantages.
For New Entrants and Emerging Players: Lead with digital-to-physical workflow integration targeting Jerusalem restoration architects who commission batch-size-one Jerusalem stone and historic mosaic pattern replication. Capture white-space in artisanal mosaic segments where Safed and Jaffa workshops face capacity constraints on boutique hospitality timelines. Deploy direct sales specification engineers to interface with Tel Aviv project architects on large-format porcelain penthouse developments.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors domestic manufacturers with captive kiln assets and digital printing licensing relationships over import-dependent distributors facing inventory risk compression. Long-term viability over the next decade hinges on recycled-content threshold compliance capabilities and post-industrial waste supply partnerships. Monitor SII announcements on expanded recycled-content mandates as the inflection signal for raw-material sourcing qualification timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Natural Gas Kiln Conversion | Ministry of Environmental Protection emissions mandates qualify producers for green building credit specifications. |
| Digital Printing Technology Licensing | Inkjet deposition capabilities enable batch-size-one customization that fragments supplier relationships toward technology-integrated manufacturers. |
| Recycled-Content Supply Partnerships | Anticipated SII expansion of post-industrial waste thresholds creates first-mover advantage for qualified producers. |
| In-House SII Laboratory Investment | Domestic testing capabilities capture specification authority in commercial verticals requiring documented slip-resistance ratings. |
| Negev Manufacturing Cluster Expansion | Southern district land and energy cost arbitrage supports fired-clay capacity with lower per-unit overhead. |
Study Parameters
Cross-validation between distributor procurement data and Ministry of Finance construction-linked VAT frameworks anchors the qualitative findings on specification behavior and contractor decision patterns. Primary interviews with plant managers at domestic manufacturing facilities, procurement leads at national retail chains, specification engineers at vertically integrated producers, and restoration architects in Jerusalem historic districts combined with secondary validation from Israeli Standards Institute certification records, Ministry of Environmental Protection emissions filings, and customs/trade data on feldspar and kaolin imports. Bottom-up triangulation across product type, end user, technology, and distribution channel dimensions converged with top-down macroeconomic and construction activity indicators.
Sensitivity analysis around natural gas price trajectories, shekel-euro cross-rate assumptions, and SI 984 certification expansion timelines tested forecast robustness across the projection horizon. Segmentation dimensions modeled include product type, end user category, production technology, and distribution channel, with geographic sub-regional clusters as an industry-specific overlay. CAGRs were derived from trend extrapolation adjusted for technology adoption curves and regulatory compliance phase-in schedules, incorporating construction permit data and luxury residential development pipelines as Israel-specific demand inputs.
Underlying assumptions cover sustained Ministry of Finance construction-linked VAT framework stability and gradual SI 984 certification threshold expansion, with deviation risk concentrated in Turkish feldspar supply disruptions and engineered stone substitution acceleration in residential kitchen applications. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Piping Systems Market
Building & Construction Materials
India Ceramic Tiles Market
Building & Construction Materials
Hygienic Cladding Market
Building & Construction Materials
Global Concrete Surface Retarders Market
Building & Construction Materials
Sheet Metal Market
Building & Construction Materials
Chain Link Fencing Market
Building & Construction Materials
Concrete Waterproofing with Crystalline Technology Market
Building & Construction Materials
Fiberglass Light Poles Market
Building & Construction Materials
Drywall Compound and Drywall Mud Market
Building & Construction Materials
Concrete Repair Product Market
Building & Construction Materials
Door Canopy Market
Building & Construction Materials
US Ceiling Tiles Market
Building & Construction Materials
Rubble Sacks Market
Building & Construction Materials
Balustrade Market
Building & Construction Materials
Roof Coating Market
Building & Construction Materials
Plastic Door and Window Market