
 Concrete Repair Product Market | 2026-2036
Concrete Repair Product Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Repair Product Market Insights
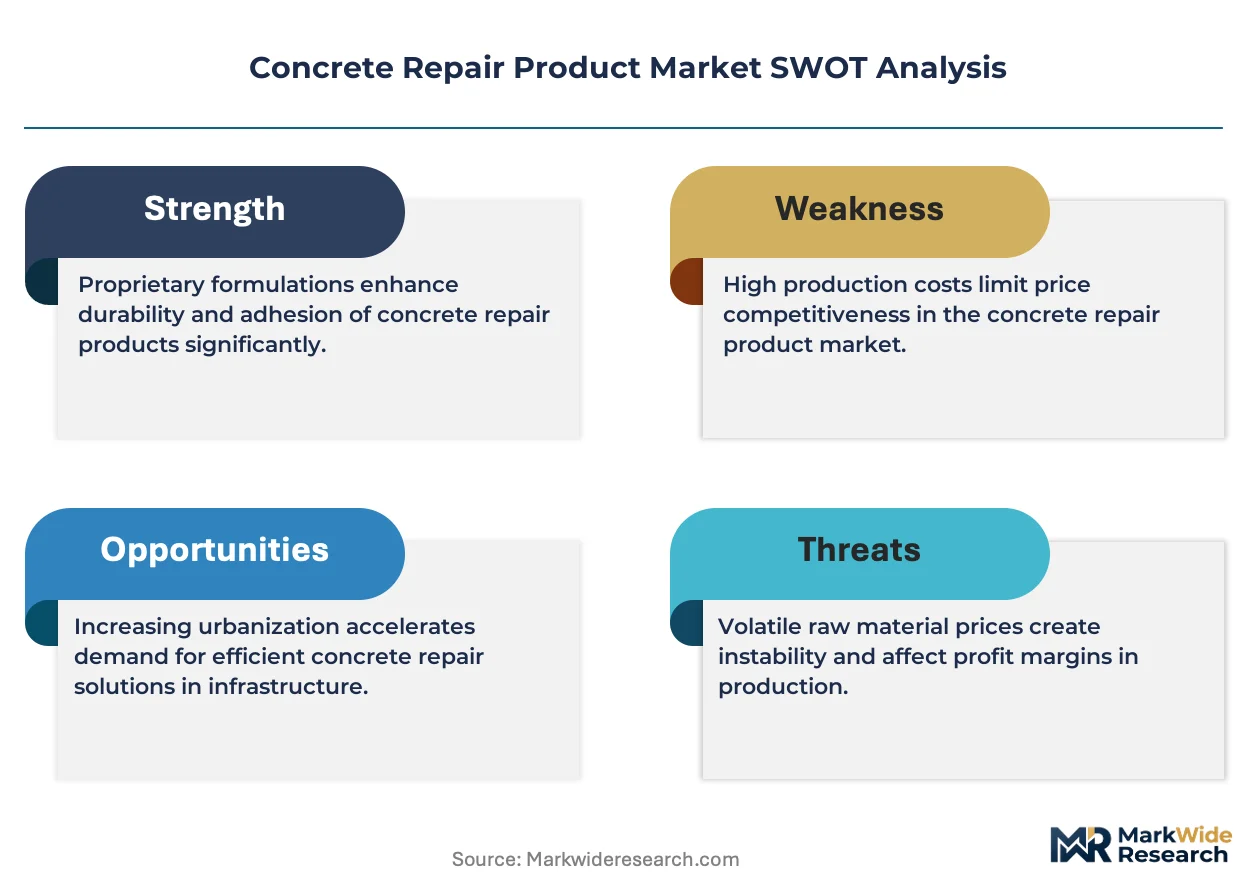
A shortage of certified concrete repair technicians is reorganizing project timelines and contractor bidding patterns across developed markets. Sika AG leverages its global distribution network to secure specification locks on major bridge contracts. Mapei S.p.A. competes through specialized polymer-modified cement formulations for tunnel environments. BASF SE anchors its position with R&D intensity in low-carbon repair chemistries.
Concrete repair products encompass engineered cementitious and resin-based systems formulated to restore structural integrity, durability, and load-bearing capacity to deteriorated concrete elements. These materials typically achieve compressive strengths exceeding 30 MPa and bond to substrates through mechanical interlock and chemical adhesion, serving primarily to extend service life of infrastructure and buildings rather than full replacement. Cementitious mortars dominate volume demand in roadway maintenance due to cost efficiency and compatibility with existing concrete, while epoxy mortars command premium positioning in industrial flooring where chemical resistance and rapid return-to-service justify higher material costs. Polyurethane foams represent the fastest-growing product category in tunnel rehabilitation, driven by injection applications sealing active water ingress where traditional grouts fail.
ASTM International standards govern product performance testing and acceptance criteria in the United States, while the EU Construction Products Regulation mandates CE marking for repair mortars used in structural applications across Europe. China's GB standards and Ministry of Housing and Urban-Rural Development technical codes increasingly incorporate durability requirements that favor polymer-modified systems over plain cement repairs. Stakeholders must monitor evolving carbon-emission thresholds for construction materials, as environmental product declarations and embodied-carbon limits are reshaping specification criteria and supplier qualification processes.
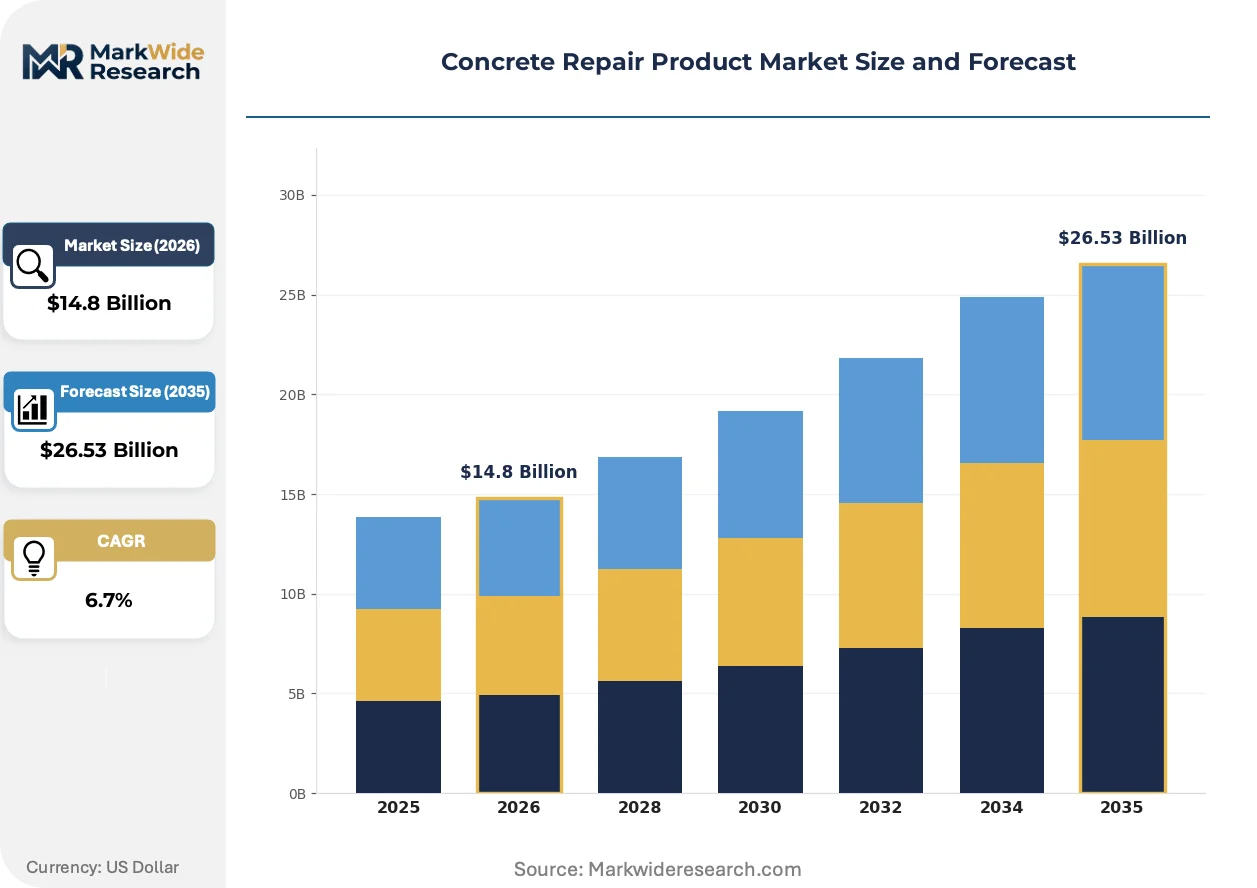
Market Dynamics
Aging bridge and tunnel infrastructure across developed economies is forcing specification shifts toward polymer-modified and low-carbon repair systems, compressing traditional cement mortar volumes as asset owners prioritize extended service life over first-cost savings.
Growth Catalysts
- EU Construction Products Regulation:CE marking mandates for structural repair mortars are accelerating polymer-modified system adoption across European infrastructure tenders.
- China's dual carbon goals:MEE emission thresholds for construction materials are redirecting specification authority toward low-carbon repair chemistries in municipal contracts.
- Water ingress sealing:Polyurethane foam injection technology is capturing tunnel rehabilitation applications where conventional grouts fail under hydrostatic pressure.
Market Restraints
- Epoxy resin cost volatility:Petrochemical feedstock price swings compress margins for industrial flooring contractors specifying premium mortar systems.
- Specialized applicator concentration:Certified concrete repair technicians cluster in Germany, the United States, and Japan, creating project timeline bottlenecks elsewhere.
- Plain cement substitution threat:Unmodified cementitious mortars retain specification lock on non-structural roadway maintenance due to cost floors.
Strategic Opportunities
- India's infrastructure pipeline:National highway expansion and urban metro construction are opening specification windows for polymer-modified repair systems in bridge deck applications.
- Carbon accounting integration:Environmental product declarations are becoming mandatory pre-qualification documents in German and Dutch public procurement frameworks.
- Drone-assisted damage assessment:Remote sensing convergence with repair specification software is compressing bid preparation cycles for asset management contractors.
Industry Challenges
- Certified technician scarcity:ICRI and ACI credential programs cannot match training throughput to project backlog in North American bridge rehabilitation.
- Multi-standard compliance:Contractors face conflicting ASTM, EN, and GB testing protocols when sourcing materials for cross-border infrastructure portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Repair Product Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy Mortars, Polymer-Modified Cement, Polyurethane Foams, Cementitious Mortars, Acrylic Resins Application: Bridge Restoration, Tunnel Rehabilitation, Roadway Maintenance, Parking Garage Repair, Industrial Flooring End User: Construction Contractors, Infrastructure Developers, Property Managers, Municipal Authorities, Facility Operators Deployment Method: Spray Coating, Troweling, Injection, Pouring, Brush Application |
| Companies Covered | Sika AG, Saint-Gobain Weber, Fosroc, Inc., BASF SE, Mapei S.p.A., Pidilite Industries Ltd., RPM International Inc., The Euclid Chemical Company, Remmers Baustofftechnik GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Repair Product Market Trends and Innovations
Specification authority is migrating from first-cost procurement toward lifecycle carbon accounting and performance-based material selection, compressing traditional supply relationships and opening entry paths for specialized formulation houses.
Geopolymer binders formulated from industrial byproducts are displacing Portland cement in repair mortars for chloride-exposed marine structures. Port authorities in the Netherlands and Australia are specifying these systems for quay wall rehabilitation. The technology is displacing conventional repair volumes in environments where sulfate resistance and reduced embodied carbon carry tender weight.
REACH restrictions on epoxy hardener chemistries are forcing reformulation of high-performance industrial flooring systems across European manufacturing facilities. ECHA substance evaluations are compressing the approved substance list for structural adhesives. German automotive plant operators are accelerating qualification of alternative polyurethane and methyl methacrylate systems to maintain production line uptime.
Asset owners are unbundling material supply from installation service contracts, creating direct procurement relationships with specialty chemical suppliers. Infrastructure funds managing toll road and tunnel portfolios are establishing approved vendor lists independent of general contractor preferences. This pattern is most visible in Australian and British P3 concession structures where operational cost accountability sits with long-term facility managers.
Concrete Repair Product Market Segmentation
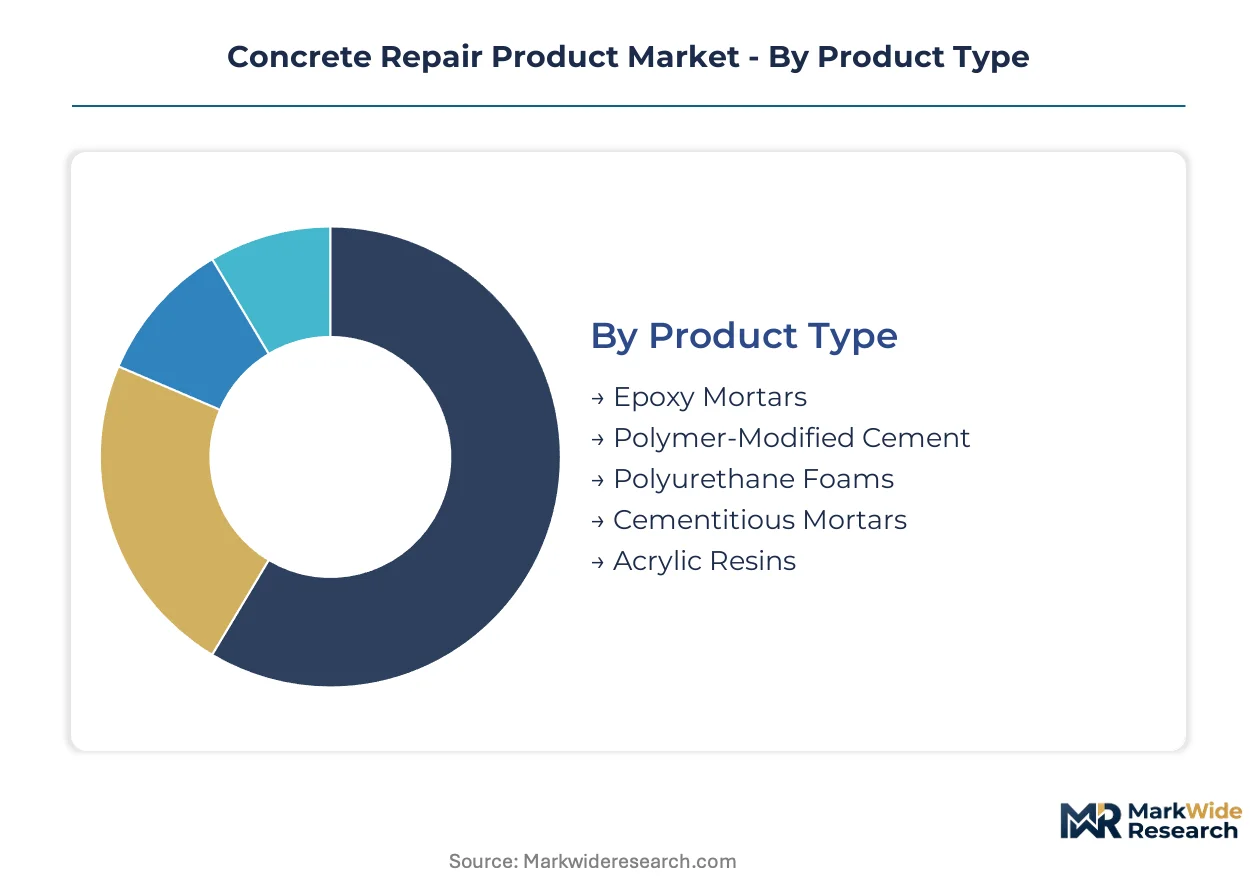
Segmentation in concrete repair products reveals divergent margin structures and specification pathways. Product chemistry determines procurement channel—commodity mortars flow through distributor networks while specialty resins route through direct manufacturer relationships with certified applicators.
Product Type:
Channel configuration splits sharply: cementitious systems move through construction supply distributors serving general contractors, while epoxy and polyurethane formulations route through manufacturer-direct specifications to specialized applicators.
- Epoxy Mortars:Two-part thermosetting systems achieve compressive strengths exceeding 80 MPa with near-zero shrinkage. German automotive plants and US chemical processing facilities specify these for industrial flooring where chemical resistance and rapid return-to-service override material cost premiums. REACH restrictions on traditional hardener chemistries are accelerating reformulation cycles.
- Polymer-Modified Cement:Portland cement base enhanced with latex or acrylic polymers improves flexural strength and substrate adhesion. Chinese municipal authorities under MEE emission thresholds increasingly specify these for bridge deck overlays, displacing unmodified cement in structural applications. CE marking mandates across Europe reinforce this shift.
- Polyurethane Foams:Hydrophobic injection systems seal active water ingress under hydrostatic pressure where conventional grouts fail. Tunnel rehabilitation in Alpine regions drives specification.
- Cementitious Mortars:Plain or fiber-reinforced Portland cement formulations dominate roadway maintenance volume through cost floors and compatibility with existing substrates.
- Acrylic Resins:Single-component moisture-cure systems serve decorative and waterproofing overlays with simplified application protocols.
Cementitious mortars dominate installed base. Polyurethane foams are where expansion concentrates.
Application:
Project scale and asset ownership structure determine margin tier—large infrastructure tenders favor lifecycle-cost procurement while commercial maintenance contracts prioritize speed-to-completion.
- Bridge Restoration:Structural repair of load-bearing elements including decks, girders, and substructures demands high-bond-strength materials meeting ASTM C881 or EN 1504 standards. US state DOTs and German federal transport authorities concentrate specification authority for major rehabilitation programs.
- Tunnel Rehabilitation:Waterproofing, lining repair, and fire protection upgrades require injection systems and spray-applied mortars compatible with confined-space application. Swiss and Austrian alpine tunnel operators lead adoption of polyurethane foam injection for active leak sealing.
- Roadway Maintenance:Pothole repair, joint restoration, and surface scaling treatments favor rapid-setting cementitious patches applied through maintenance crews.
- Parking Garage Repair:Carbonation-induced corrosion protection and deck waterproofing drive polymer-modified system specification in urban commercial assets.
- Industrial Flooring:Chemical-resistant epoxy and methyl methacrylate systems serve manufacturing facilities where production downtime costs exceed material premiums.
Roadway maintenance absorbs highest volume. Tunnel rehabilitation offers steepest expansion trajectory.
End User:
Procurement sophistication varies—municipal authorities increasingly unbundle material supply from installation contracts while facility operators retain turnkey relationships.
- Construction Contractors:General and specialty contractors executing repair projects under design-bid-build or design-build arrangements. Australian and British P3 concession structures are shifting procurement toward direct manufacturer relationships.
- Infrastructure Developers:Public and private entities funding large-scale bridge, tunnel, and highway renewal. These stakeholders concentrate in the United States, Germany, and China where public infrastructure renewal budgets are largest.
- Property Managers:Commercial and residential portfolio operators managing parking structures and building envelopes.
- Municipal Authorities:City, county, and state agencies maintaining public roadways and civic structures through in-house crews or maintenance contracts.
- Facility Operators:Industrial plant and warehouse operators prioritizing production continuity in flooring repair decisions.
Construction contractors control current volume. Infrastructure developers are consolidating specification authority.
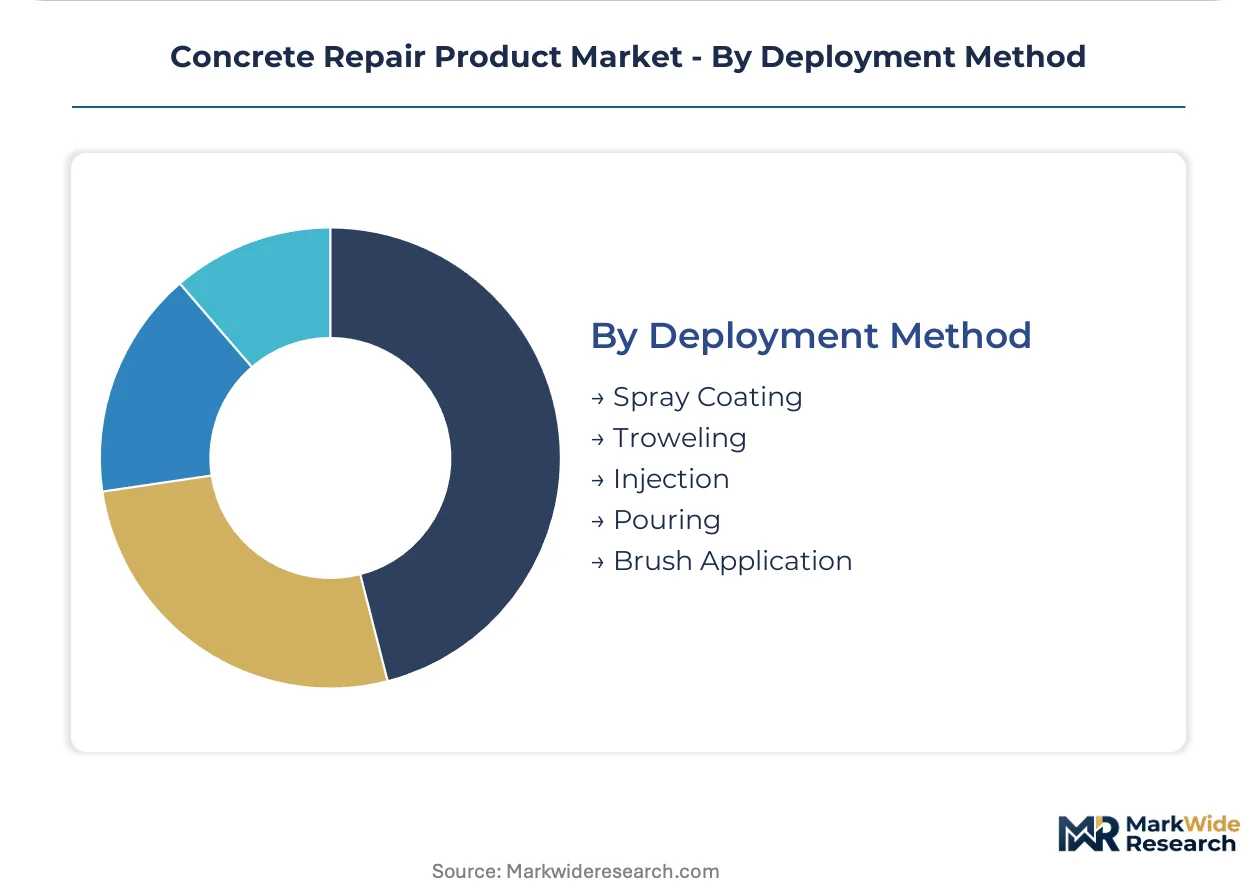
Deployment Method:
Application technique constrains product selection—spray and injection methods require specialized equipment and certified technicians, creating entry barriers that protect premium formulations.
- Spray Coating:High-volume application of repair mortars and protective coatings using wet-mix or dry-mix shotcrete equipment. Tunnel lining rehabilitation in Norway and Japan relies on robotic spray systems for consistent coverage in confined spaces.
- Troweling:Hand or power trowel application of stiff-consistency mortars for vertical and overhead repairs. Bridge soffit and column repairs in the United States depend on ICRI-certified technicians for quality assurance.
- Injection:Pressure-injection of liquid resins or foams into cracks and voids. This method commands premium positioning for active water ingress sealing.
- Pouring:Gravity or pumped placement of flowable grouts and self-leveling toppings.
- Brush Application:Manual coating of protective and waterproofing systems on accessible surfaces.
Troweling dominates technician-installed volume. Injection methods are gaining share fastest in water-exposed applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ASTM International standards anchor specification authority in the United States, while CE marking mandates and China's GB standards reshape procurement patterns across their respective jurisdictions. Infrastructure renewal budgets concentrate in three national markets where aging civil works exceed design lifespans.
United States
State DOTs concentrate bridge rehabilitation funding through federal infrastructure legislation. ICRI certification requirements for concrete repair technicians create project timeline bottlenecks in North American bridge programs. Metropolitan clusters in the Northeast Corridor and California maintain the densest concentration of certified applicators.
Germany
Federal transport authorities prioritize lifecycle-cost procurement for tunnel and bridge assets. REACH restrictions on epoxy hardener chemistries force reformulation of industrial flooring systems across manufacturing facilities. The Ruhr industrial region and Bavarian automotive corridor drive specification of low-carbon repair chemistries.
China
MEE emission thresholds redirect municipal contracts toward polymer-modified systems over plain cement repairs. Ministry of Housing and Urban-Rural Development technical codes increasingly incorporate durability requirements favoring advanced formulations. Yangtze River Delta infrastructure developers lead adoption of extended-service-life materials.
India
National highway expansion and urban metro construction open specification windows for polymer-modified repair systems. BIS standards for construction materials evolve toward performance-based criteria. Maharashtra and Karnataka state authorities concentrate bridge deck rehabilitation project awards.
Australia
Port authorities specify geopolymer binders for quay wall rehabilitation in chloride-exposed marine environments. P3 concession structures unbundle material supply from installation contracts, creating direct procurement relationships. Sydney and Melbourne infrastructure funds establish approved vendor lists independent of general contractor preferences.
Concrete Repair Product Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational chemical conglomerates controlling distribution networks for specification-sensitive infrastructure contracts. Regional formulation houses compete through polymer-modified cement expertise and tunnel-environment specialization. Two strategic archetypes dominate: global distributors securing specification locks on major bridge contracts, and technology-focused developers of low-carbon repair chemistries. Competitive moves concentrate on backward integration into raw material supply and geographic expansion through distributor acquisition.
Among European-based chemical specialists, Sika AG, Mapei S.p.A., and BASF SE occupy positions across the integrated leader tier. Sika AG exemplifies the global distribution archetype through its specification presence in major infrastructure tenders. Mapei S.p.A. represents specialized formulation capability in polymer-modified systems. BASF SE anchors the technology-intensive segment through its positioning in low-carbon repair chemistry development.
| Leading Market Players |
|---|
| Sika AG |
| Saint-Gobain Weber |
| Fosroc, Inc. |
| BASF SE |
| Mapei S.p.A. |
| Pidilite Industries Ltd. |
| RPM International Inc. |
| The Euclid Chemical Company |
| Remmers Baustofftechnik GmbH |
| Others |
Pricing and Supply Chain Analysis
Project-based procurement with multi-year framework agreements locks in supply access for certified applicators while anchoring price visibility for infrastructure developers across German tunnel rehabilitation and US bridge programs. This contract structure compresses spot-market exposure for polymer-modified systems while leaving plain cement mortars exposed to commodity volatility.
Pricing Analysis
Geographic price spreads between German industrial flooring specifications and Indian roadway maintenance contracts exceed material cost differentials by wide margins. Three-tier pricing structure across premium, standard, and economy levels separates epoxy mortar systems certified to EN 1504 from polymer-modified cements and unmodified cementitious patches. Cost compression in economy-tier roadway materials is intensifying because of petrochemical feedstock volatility and plain cement substitution. Municipal authorities in India and China exhibit highest price sensitivity, while German automotive plant operators prioritize performance over material premiums.
Supply Chain Analysis
Baltic Sea port congestion periodically chokes epoxy resin deliveries to Central European formulation plants, forcing inventory buffers at German distributors. Manufacturing gravity centers on Germany, China, and the United States for polymer-modified systems, with specialty resin production anchored in Belgium and the Netherlands. Formulation draws from petrochemical feedstocks, Portland cement clinker, and industrial byproducts for geopolymer binders. Single-source vulnerability concentrates in certified technician training throughput, not raw material supply. Distribution runs through manufacturer-direct specifications for specialty resins and construction supply distributors for commodity mortars.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification authority fragmentation across infrastructure funds, municipal authorities, and facility operators creates white-space niches for specialized formulation houses as asset owners unbundle material supply from installation contracts.
For Market Incumbents: Fortify specification locks on major bridge and tunnel contracts through backward integration into certified technician training programs, countering the ICRI and ACI credential bottlenecks that compress project timelines. Deepen captive supply of low-carbon repair chemistries to meet tightening MEE emission thresholds in China and REACH-compliant formulations in Europe. Channel control through distributor acquisition in India protects margin position against regional formulation houses targeting national highway expansion. For New Entrants and Emerging Players: Anchor in tunnel rehabilitation applications for polyurethane foam injection systems, where Alpine region operators lead adoption and certified applicator scarcity protects premium positioning. Target India's bridge deck overlay segment as municipal specifications shift toward polymer-modified systems under evolving BIS standards. Pursue direct procurement relationships with Australian and British P3 infrastructure funds that have unbundled material supply from general contractor arrangements. For Investors and Strategic Acquirers: Capital is best deployed toward technology-focused developers of geopolymer and low-carbon repair chemistries with established qualification at Netherlands port authorities and Australian marine structures. Long-term viability hinges on positioning ahead of embodied-carbon limits becoming mandatory pre-qualification criteria in German and Dutch public procurement. Watch for Environmental Product Declaration mandates spreading from European infrastructure tenders into Asian municipal contracts as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Supply | Captive sourcing of low-carbon binders secures qualification under China's MEE emission thresholds. |
| Certified Technician Training Program Expansion | ICRI-credential pipeline expansion in North America compresses project timeline bottlenecks for bridge contractors. |
| Geopolymer Formulation Development | Industrial byproduct-based binders displace Portland cement in Netherlands port authority quay wall specifications. |
| Distributor Network Acquisition in India | Channel control captures specification windows opening in Maharashtra and Karnataka state bridge programs. |
| Environmental Product Declaration Investment | EPD documentation becomes mandatory pre-qualification for German federal transport authority tenders. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC filings from listed construction chemical suppliers, and technical standards documentation from ASTM International and EN committees. Primary interviews engaged plant managers at formulation facilities, procurement leads at infrastructure developers, distribution channel partners serving general contractors, and technical R&D directors at polymer-modified system suppliers. Bottom-up volume estimates triangulate against top-down infrastructure spending allocations across national transportation budgets.
Segmentation dimensions modeled include product chemistry tier, application environment, end-user procurement sophistication, and deployment method complexity across the analysis window. CAGRs derive from elasticity-adjusted demand projections tied to infrastructure renewal backlog data and specification shift velocities. Forecast inputs incorporate certified technician training throughput constraints and evolving carbon-emission thresholds for construction materials.
Material uncertainties — petrochemical feedstock volatility, REACH substance evaluation outcomes, and MEE threshold enforcement consistency — sit outside the modeled envelope. Forecasts reflect assumptions about specification migration rates and unbundling of material supply from installation contracts. Practitioners should keep alternative scenarios live as carbon accounting integration timelines and technician certification program expansions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Carbon Textile Reinforced Concrete Market
Building & Construction Materials
Global Concrete Repair Mortars Market
Building & Construction Materials
Point Fixing Glass Curtain Wall Market
Building & Construction Materials
Asphalt Shingles Market
Building & Construction Materials
Insulated Wall Panels Market
Building & Construction Materials
Canada Asphalt Shingles Market
Building & Construction Materials
Blanket Insulation Market
Building & Construction Materials
Asia-Pacific Gypsum Board Market
Building & Construction Materials
Construction Elastomers Market
Building & Construction Materials
Corrugated Steel Panels Market
Building & Construction Materials
Concrete Densifier Market
Building & Construction Materials
GCC Concrete Blocks Market
Building & Construction Materials
India Ready-Mix Concrete Market
Building & Construction Materials
Global Stucco Market
Building & Construction Materials
Asia-Pacific Flanges Market
Building & Construction Materials
UPVC Doors and Windows Market