
 Welding Alloys Market | 2026-2036
Welding Alloys Market Size, Share, and Industry Trends Forecast 2026-2036
Welding Alloys Market Insights
Flux-cored wire is expanding its share in heavy fabrication as fabricators switch from solid wire to cut deposition costs and raise travel speeds. Lucas-Milhaupt anchors its position through captive supply of precision brazing alloys for automotive thermal systems. Nihon Superior specializes in lead-free solder formulations that navigate Japan's JIS standards and REACH-aligned export requirements. Materion extends its technology leadership into high-purity vacuum induction melted products for aerospace turbine repair.
Welding alloys are consumable metallic materials formulated with precise compositions of nickel, chromium, molybdenum, or manganese, designed to fuse with base metals under controlled thermal cycles and restore mechanical integrity. They serve primarily to join structural components, overlay wear surfaces, and rebuild degraded equipment in capital-intensive industries. Stainless steel products command the deepest margin pools due to alloy surcharges and certification burdens for pressure vessel applications. Nickel alloys represent the fastest-growing product category as superalloy deposition expands in aerospace engine maintenance. Arc welding technology dominates volume through shielded metal and submerged arc processes, while TIG welding captures premium pricing on exotic material joints.
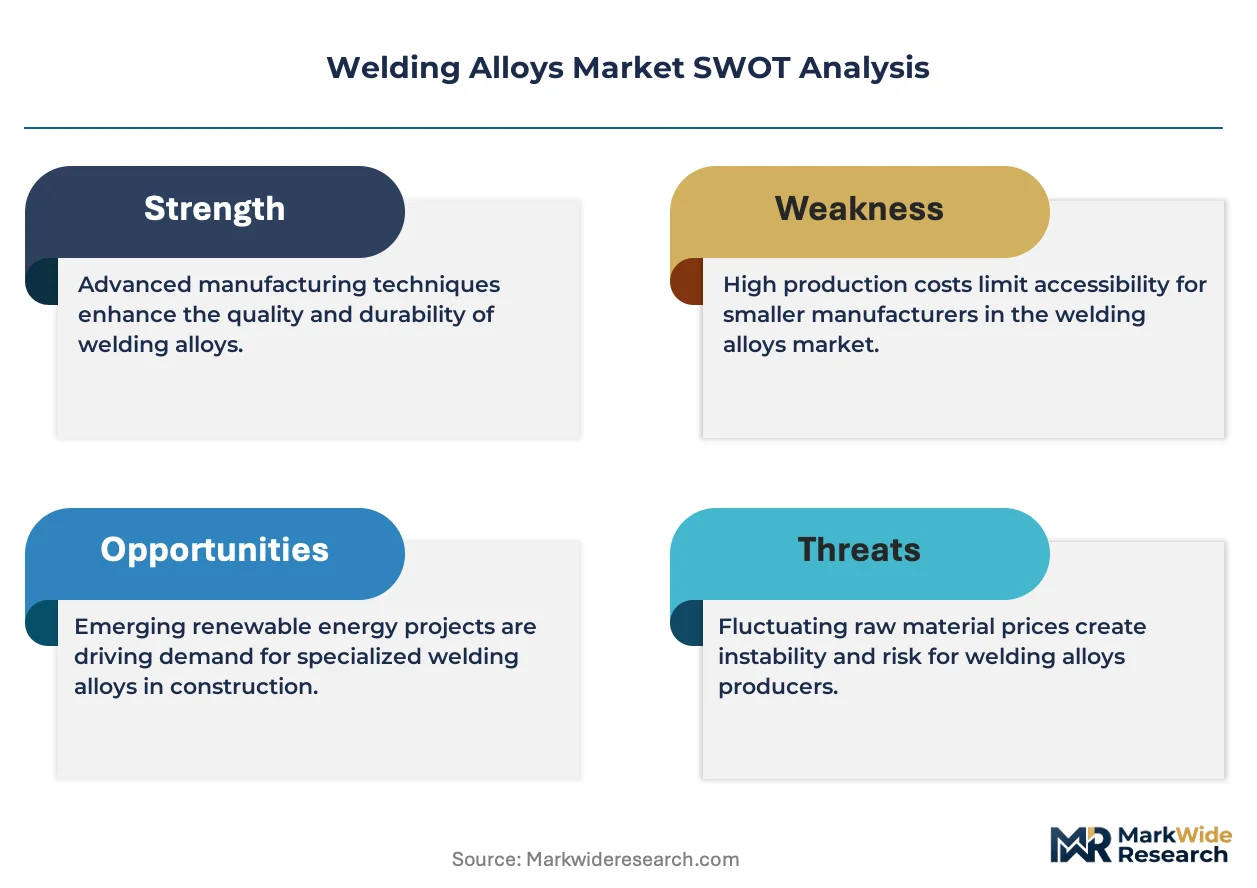
FDA oversight of medical device welding and EPA emissions rules for smelting operations shape product formulations and facility siting in the United States. REACH and RoHS frameworks in Europe restrict cadmium and lead content in filler metals, forcing reformulation across export-oriented suppliers. China's MEE enforces dual carbon goals that elevate energy costs for ferroalloy production. Stakeholders must monitor how carbon border adjustments and alloy surcharge volatility reshape sourcing economics between integrated mills and specialized wire producers.
Market Dynamics
Flux-cored wire substitution is compressing solid wire volumes in heavy fabrication, while China's MEE dual carbon enforcement is elevating energy costs for ferroalloy smelters and reshaping sourcing economics between integrated mills and specialized wire producers.
Growth Catalysts
- Aerospace engine maintenance cycles:Superalloy deposition demand for turbine blade repair is pulling nickel alloy consumption upward as fleet ages expand shop visit frequency.
- REACH and RoHS alignment:European restrictions on cadmium and lead in filler metals are forcing reformulation investments that lock in compliant suppliers with certified product lines.
- South Korean shipyard clustering:Ulsan and Geoje production hubs concentrate hull fabrication and repair demand, creating predictable offtake for high-strength consumables.
Market Restraints
- Ferrochrome and nickel price volatility:Alloy surcharge fluctuations compress margin visibility for wire producers who cannot pass through input spikes immediately.
- Smelter concentration in China:MEE emissions enforcement is idling marginal ferroalloy capacity, tightening feedstock availability for non-integrated consumable manufacturers.
- Technical limitation in exotic material joints:TIG welding's travel speed constraints cap productivity gains on titanium and nickel superalloy applications despite premium pricing.
Strategic Opportunities
- India's PLI-linked manufacturing expansion:Domestic fabrication incentives are building industrial gas and welding consumable demand outside traditional import-dependent channels.
- Vacuum induction melted aerospace grades:High-purity deposition alloys for turbine repair command technical barriers that screen out commodity competitors.
- Digital distributor platforms:Specialized alloy procurement is fragmenting toward technical e-commerce channels that bypass traditional welding supply house networks.
Industry Challenges
- Certified welder scarcity:Pressure vessel and aerospace joint qualifications require ASME Section IX or AWS D17.1 credentials that training pipelines cannot replenish at replacement rates.
- Dual qualification timelines:OEM approvals for new alloy formulations demand 18-36 month validation cycles that freeze product development roadmaps.
Report Scope
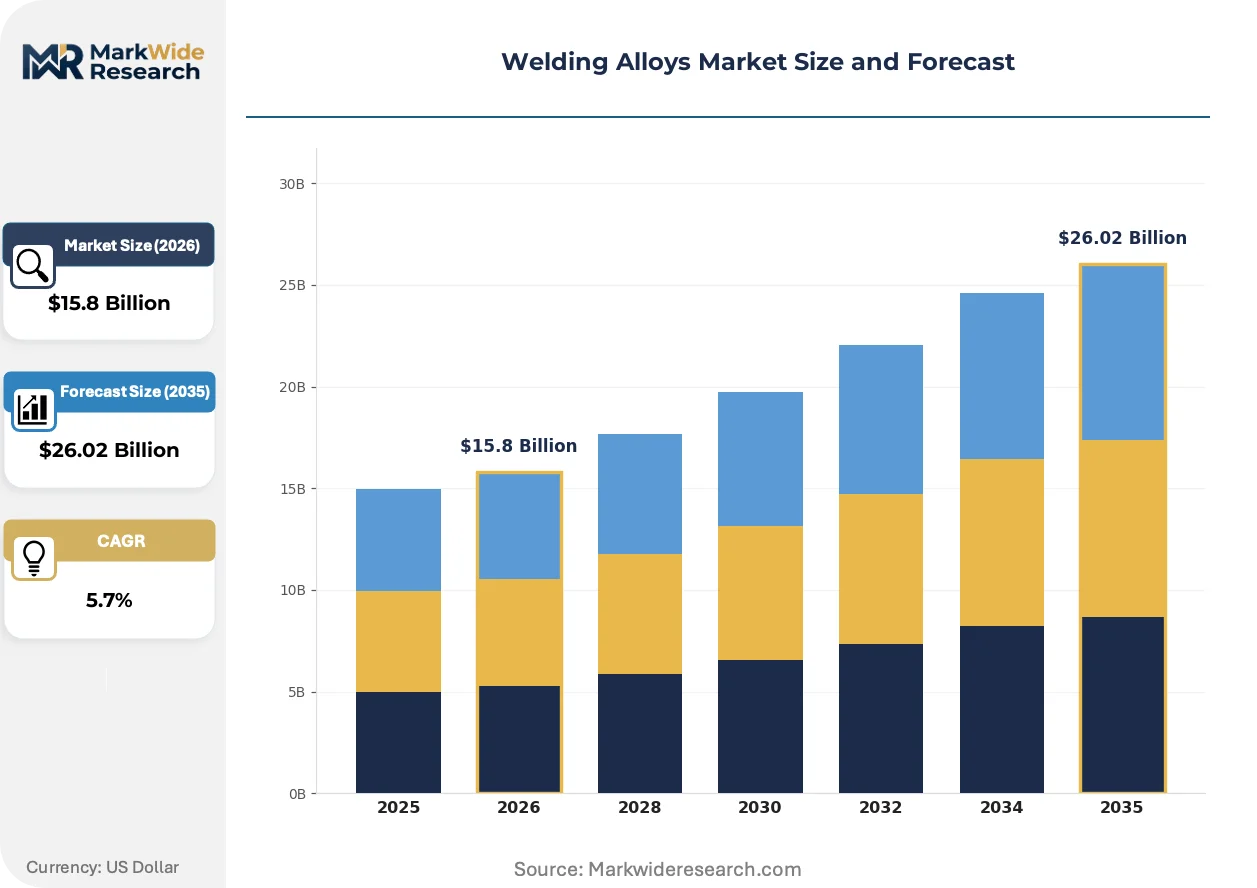
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Welding Alloys Market |
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $26.02 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mild Steel, Stainless Steel, Aluminum, Nickel Alloys Application: Construction, Automotive, Aerospace, Shipbuilding End User: Manufacturers, Fabricators, Repair Shops, Service Providers Technology: Arc Welding, MIG Welding, TIG Welding, Resistance Welding |
| Companies Covered | Harris Products, Lucas-Milhaupt, Umicore, Nihon Superior, Morgan, Prince & Izant, Saxonia, Aimtek, Materion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Welding Alloys Market Trends and Innovations
Metal deposition technologies and regulatory chemistry mandates are converging to redefine competitive advantage around purity certification, deposition efficiency, and carbon-accounted supply chains rather than commodity scale.
Metal-cored wire formulations are rewriting productivity benchmarks in automated heavy fabrication. Automotive chassis and construction equipment manufacturers are adopting these products at accelerating rates to compress cycle times on robotic cells. The technology is rewriting the cost structure of high-volume structural welding by cutting rework rates and extending contact tip life.
China's MEE dual carbon goals are tightening emissions standards for ferroalloy smelting operations. Energy cost elevation is forcing capacity consolidation among marginal producers and redirecting feedstock sourcing toward integrated mills with captive power. Nickel-based consumable manufacturers with China exposure are responding by diversifying alloy sourcing toward South African and Indonesian ferrochrome channels.
Technical procurement teams are consolidating qualified supplier lists around carbon-accounted product lines. Industrial gas distributors and specialized wire houses are losing share to direct mill relationships and digital platforms that document scope-three emissions. This pattern is most visible in German and Dutch fabrication clusters where CSRD reporting requirements flow down to tier-one suppliers.
Welding Alloys Market Segmentation
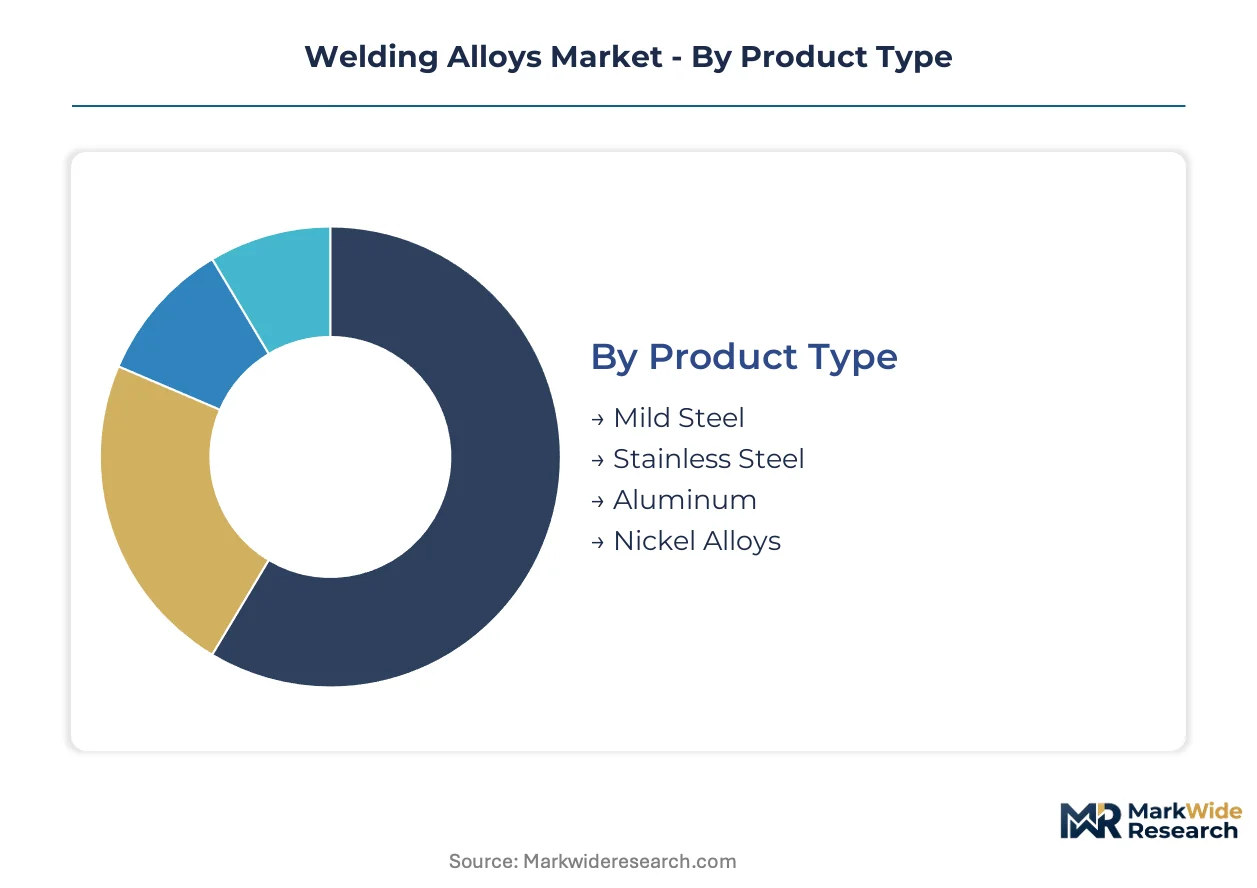
Welding alloys segment by metallurgical composition, thermal process requirements, and structural application demands. Each dimension carries distinct margin profiles and qualification barriers that shape supplier positioning.
Product Type:
Supply concentration in ferroalloy smelting operations directly shapes which product categories command pricing power and which face margin compression from feedstock volatility.
- Stainless Steel:Chromium-nickel formulations with certified low-carbon specifications for pressure vessel construction. Demand clusters in German and Dutch fabrication hubs where CSRD reporting requirements flow down to tier-one suppliers, locking in qualified vendors with documented scope-three emissions.
- Nickel Alloys:Superalloy deposition materials vacuum induction melted for turbine blade repair applications. Aerospace engine maintenance cycles in the United States and Western Europe are pulling consumption upward as fleet ages expand shop visit frequency.
- Mild Steel:Carbon-manganese consumables for structural fabrication with the lowest alloy surcharge exposure.
- Aluminum:Silicon-magnesium wire and rod formulations for automotive chassis and aerospace skin joining.
Today's leader: Stainless Steel. Tomorrow's challenger: Nickel Alloys.
Application:
Cost tier differentiation separates high-qualification segments with 18-36 month OEM approval cycles from commodity construction offtake.
- Shipbuilding:High-strength consumables for hull fabrication and repair in South Korean yard clusters around Ulsan and Geoje. China's MEE dual carbon enforcement is elevating energy costs for ferroalloy feedstock, tightening availability for non-integrated manufacturers serving this segment.
- Aerospace:Superalloy deposition for engine component maintenance with ASME Section IX and AWS D17.1 qualification requirements. Certified welder scarcity constrains capacity expansion despite premium pricing.
- Construction:Structural steel joining for commercial and infrastructure projects with high volume but compressed margins.
- Automotive:Robotic MIG and metal-cored wire applications for chassis and body-in-white assembly.
Volume concentrates in Construction. Margin concentrates in Aerospace.
End User:
Customer type determines procurement channel—direct mill relationships versus distributor networks—and technical support intensity.
- Fabricators:Heavy equipment and structural steel contractors switching from solid wire to flux-cored and metal-cored formulations to cut deposition costs and raise travel speeds on automated cells.
- Repair Shops:Maintenance welding operations with fragmented demand and price-sensitive purchasing patterns.
- Manufacturers:OEM captive welding operations with qualified supplier lists and carbon-accounted procurement requirements.
- Service Providers:Field welding contractors serving oil and gas, power generation, and infrastructure maintenance.
Procurement consolidation favors Manufacturers. Channel fragmentation persists in Repair Shops.
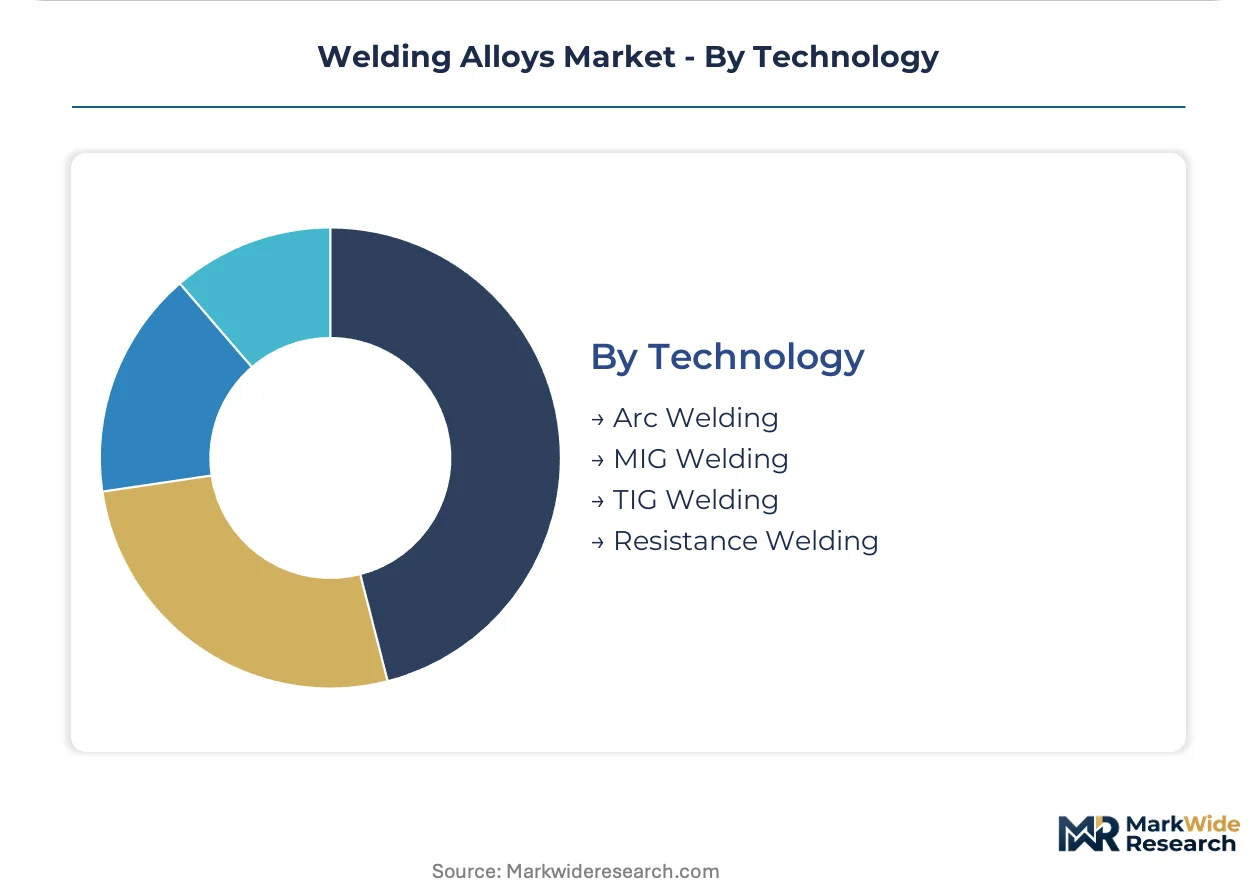
Technology:
Maturity curves separate established arc processes from premium-positioned precision welding with technical barriers that screen out commodity competitors.
- Arc Welding:Shielded metal and submerged arc processes dominating volume through heavy fabrication and shipyard applications. Flux-cored wire substitution is compressing solid wire volumes in this segment.
- TIG Welding:Gas tungsten arc precision for exotic material joints on titanium and nickel superalloys. Travel speed constraints cap productivity gains despite premium pricing.
- MIG Welding:Gas metal arc processes with metal-cored wire adoption accelerating in automotive and construction equipment manufacturing.
- Resistance Welding:Spot and seam welding for sheet metal assembly with limited alloy consumable intensity.
Volume leadership sits with Arc Welding. Technical premium accrues to TIG Welding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ulsan and Geoje anchor shipbuilding demand for high-strength consumables, while regulatory enforcement across major economies reshapes alloy sourcing economics and emissions-accounted supply chains.
United States
Aerospace engine maintenance cycles drive superalloy deposition demand as aging fleets expand shop visit frequency. FDA oversight of medical device welding and EPA emissions rules for smelting operations shape product formulations and facility siting. Houston-Gulf Coast fabrication clusters concentrate oil and gas field welding services with carbon-accounted procurement requirements flowing from CSRD-aligned multinational customers.
Germany
Automotive chassis manufacturers adopt metal-cored wire formulations to compress robotic cell cycle times. REACH and RoHS frameworks restrict cadmium and lead content in filler metals, forcing reformulation across export-oriented suppliers. Ruhr industrial corridor fabricators consolidate qualified supplier lists around documented scope-three emissions for pressure vessel construction.
China
Shipbuilders and heavy equipment fabricators consume nickel alloy and stainless steel consumables for hull construction and repair. MEE enforces dual carbon goals that elevate energy costs for ferroalloy smelting operations and idle marginal capacity. Yangtze River Delta steel fabrication hubs face tightening feedstock availability as non-integrated manufacturers diversify toward Indonesian ferrochrome channels.
South Korea
Ulsan and Geoje shipyard clusters concentrate hull fabrication and repair demand, creating predictable offtake for high-strength consumables. KBA-aligned industrial standards govern automotive welding applications as domestic EV production expands. Busan-Gyeongnam regional suppliers face margin compression from alloy surcharge volatility on nickel and ferrochrome inputs.
India
PLI-linked manufacturing expansion builds industrial gas and welding consumable demand outside traditional import-dependent channels. BIS certification requirements for structural steel welding create qualification barriers for non-domestic suppliers. Maharashtra-Gujarat industrial corridors attract fabrication investment as multinational OEMs diversify supply chains from China exposure.
Welding Alloys Market Competitive Landscape
Global majors compete with regional champions across alloy purity grades and qualification-intensive segments, producing a tiered structure where scale-driven wire producers, precision brazing specialists, and vacuum-melted aerospace-grade suppliers occupy distinct competitive positions. Consolidation pressures concentrate around carbon-accounted supply chains and dual-certificate manufacturing capabilities. Strategic moves center on backward integration into ferroalloy sourcing and direct mill relationships that bypass traditional distributor networks.
Specialists in lead-free solder and precision brazing include Nihon Superior and Lucas-Milhaupt, which occupy positions aligned with REACH-export requirements and automotive thermal system specifications. Materion exemplifies the vacuum induction melted tier serving aerospace turbine repair applications with high-purity deposition alloys. Harris Products, Umicore, and Prince & Izant represent diversified consumable portfolios spanning solid wire, flux-cored formulations, and specialized filler metals across multiple qualification grades.
| Leading Market Players |
|---|
| Harris Products |
| Lucas-Milhaupt |
| Umicore |
| Nihon Superior |
| Morgan |
| Prince & Izant |
| Saxonia |
| Aimtek |
| Materion |
| Others |
Pricing and Supply Chain Analysis
Carbon-accounted procurement mandates from German and Dutch fabrication clusters are forcing supply chain reconfiguration toward integrated mills with documented scope-three emissions, compressing margin visibility for non-integrated wire producers who cannot pass through alloy surcharge spikes immediately.
Pricing Analysis
Alloy surcharge pass-through mechanics dominate transaction structures across stainless steel and nickel alloy consumables. Price differentiation rests on certification grade—ASME Section IX and AWS D17.1 qualified products command substantial premiums over commercial-grade equivalents—and captive ferroalloy sourcing that insulates against nickel and ferrochrome volatility. Pricing pressure stems from China's MEE dual carbon enforcement elevating energy costs for smelting operations. Repair shops exhibit highest price sensitivity due to fragmented demand and spot purchasing patterns, while aerospace manufacturers with long-term OEM contracts demonstrate lowest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with Chinese ferroalloy smelting capacity, where MEE emissions enforcement has idled marginal producers and tightened feedstock availability. Geographic supply concentration centers on China, South Africa, and Indonesia for ferrochrome and nickel inputs. Raw material dependencies draw from nickel ore, ferrochrome, and manganese alloys. Supply chain risk manifests through regulatory restriction as carbon border adjustments reshape sourcing economics. Distribution runs through industrial gas distributors and specialized welding supply houses, though direct mill relationships and digital procurement platforms are gaining share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate around vacuum induction melted aerospace grades and metal-cored wire productivity gains, as technical barriers screen out commodity competitors and automation adoption compresses rework costs.
For Market Incumbents: Lock in carbon-accounted supply chain positioning through backward integration into ferroalloy sourcing or captive partnerships with Indonesian and South African feedstock channels. Defend against digital distributor disruption by establishing direct mill relationships with German and Dutch fabrication clusters that bypass traditional welding supply house networks. Prioritize dual-certificate manufacturing capabilities spanning REACH-RoHS compliance and ASME aerospace qualifications to freeze out reformulation laggards. For New Entrants and Emerging Players: Vacuum induction melting technology for turbine blade repair alloys offers a technology-first wedge into aerospace maintenance cycles, where 18-36 month OEM approval cycles create entrenched supplier lock-in for incumbents but also white-space for purity-certified challengers. Target India's PLI-linked manufacturing expansion as the most penetrable geography, where BIS certification requirements favor domestic qualification investment. Pursue technical e-commerce channels as the go-to-market angle, bypassing fragmented distributor networks with documented emissions transparency. For Investors and Strategic Acquirers: Asymmetric upside sits with precision brazing specialists and vacuum-melted aerospace-grade suppliers, where technical barriers and qualification intensity create durable margin pools resistant to commodity cyclicality. Long-term viability favors acquisition targets with demonstrated OEM approval pipelines and carbon-accounted product lines aligned to CSRD reporting requirements. Watch alloy surcharge volatility and MEE enforcement intensity as the inflection indicator for integrated versus non-integrated supplier profitability divergence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferroalloy Sourcing | Captive nickel and ferrochrome supply insulates margin from China's MEE-driven energy cost spikes. |
| Vacuum Induction Melting Capacity Expansion | High-purity aerospace grades for turbine repair command technical barriers that screen commodity competitors. |
| Carbon-Accounted Product Line Certification | Documented scope-three emissions align with CSRD requirements flowing to German and Dutch tier-one suppliers. |
| Digital Platform Direct Distribution | Technical e-commerce channels bypass welding supply house fragmentation with transparent procurement. |
| Dual REACH-RoHS and ASME Qualification Investment | Locked-in compliant status freezes out reformulation laggards across European and aerospace export markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at ferroalloy smelters, procurement leads at South Korean shipyards, technical R&D directors at wire producers, and aftermarket service heads at aerospace MRO facilities with secondary validation from customs and trade data, SEC filings of listed consumable manufacturers, American Welding Society technical specifications, and Chinese MEE emissions disclosures. Bottom-up alloy consumption modeling triangulated against top-down fabrication output forecasts across shipbuilding, aerospace, and automotive end-uses.
Comparable-period anchoring linked projection assumptions to historical reference periods across the analysis window, with segmentation modeling spanning metallurgical composition, thermal process technology, structural application demand, and regional production hub concentration. CAGRs derived from alloy intensity coefficients applied to fabrication output forecasts, incorporating nickel superalloy deposition rates for turbine maintenance cycles and metal-cored wire substitution elasticities in automated heavy fabrication.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon border adjustment implementation, alloy surcharge volatility, and MEE enforcement intensity on Chinese smelting capacity. Forecasts reflect documented assumptions about fleet age expansion, PLI scheme execution in India, and CSRD reporting cascade to tier-one suppliers. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Global Aluminum Foams Market
Advanced Alloys
Oxide Dispersion Strengthened (ODS) Alloys Market
Advanced Alloys
Precipitation Hardening Market
Advanced Alloys
Global Metal Injection Molding Market
Advanced Alloys
Maraging Steel Market
Advanced Alloys
Global Metal Foams Market
Advanced Alloys
Titanium Alloys Market
Advanced Alloys
Ultra High Strength Steel Market
Advanced Alloys
Aramid Prepreg Market
Advanced Alloys
India Shape Memory Alloy Market
Advanced Alloys
Global Amorphous Alloy Band Market
Advanced Alloys
Plastic-Metal Hybrids Market
Advanced Alloys
Middle East and Africa Aluminum Casting Market
Advanced Alloys
Battery Alloys Market
Advanced Alloys
Super Alloys Market
Advanced Alloys
Global Aluminum Alloys Market