
 Global Aluminum Silicon Carbide (Alsic) Market | 2026-2036
Global Aluminum Silicon Carbide (Alsic) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aluminum Silicon Carbide (Alsic) Market Foresight
A shortage of metallurgists trained in metal-matrix composite processing is unwinding capacity expansion timelines across the Alsic supply base. Materion Corporation leverages its beryllium and advanced materials heritage to sustain premium positioning in thermal management substrates. CPS Technologies Corporation anchors North American supply for infiltrated Alsic components serving power electronics. Denka Company Limited dominates Japanese output of composite powders with tightly controlled particle size distributions.
Aluminum silicon carbide denotes a metal-matrix composite wherein silicon carbide particulate reinforces an aluminum alloy matrix, typically achieving thermal conductivity of 170-200 W/mK with coefficient of thermal expansion tunable to match semiconductor substrates. The material primarily serves applications demanding heat dissipation paired with dimensional stability under thermal cycling. Composite powders and preforms together command the largest value share, with powder metallurgy routes attracting investment for near-net-shape capability. Infiltration technology leads in structural component yield, while squeeze casting competes for brake rotor and wear-resistant part volumes where porosity control determines service life.
EPA regulations on particulate emissions constrain powder handling and machining operations in United States manufacturing facilities. REACH registration requirements in Europe elevate documentation burdens for silicon carbide feedstock importers, favoring suppliers with established EU chemical compliance infrastructure. Japan's METI energy efficiency standards for power electronics indirectly drive specification of Alsic heat sinks in consumer and industrial applications. Stakeholders must monitor divergence between regional material certification timelines when siting production capacity or qualifying alternative suppliers.
Market Dynamics
Thermal management requirements in power electronics and aerospace are compressing qualification timelines for metal-matrix composites while metallurgist scarcity extends ramp-up schedules. Suppliers face simultaneous pressure to certify new grades and constrain capacity expansion.
Growth Catalysts
- Power electronics densification:Silicon carbide MOSFET adoption in EV inverters and renewable energy converters demands substrate materials with matched thermal expansion coefficients.
- EPA particulate standards:Tighter emissions controls on aluminum smelting and powder processing accelerate investment in closed-loop manufacturing systems that favor Alsic's near-net-shape capability.
- Japan METI efficiency mandates:Industrial and consumer electronics manufacturers specify Alsic heat sinks to meet energy conservation standards for power conversion equipment.
Market Restraints
- Silicon carbide feedstock concentration:High-purity SiC powder supply concentrates among Chinese and Japanese producers, exposing processors to export licensing volatility and freight cost spikes.
- REACH documentation burdens:ECHA registration requirements for SiC particulate imports into Europe favor incumbent suppliers with established compliance infrastructure, raising barriers for new entrants.
- Copper-molybdenum substitution:Established thermal management materials retain design-in preference for legacy aerospace programs with frozen specifications and long qualification cycles.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor and component production create first-mover advantage for Alsic suppliers establishing local powder processing or infiltration partnerships.
- Space qualification pathways:Satellite constellation deployments require radiation-hardened thermal management substrates with heritage traceability, opening premium pricing tiers for certified suppliers.
- Additive manufacturing convergence:Hybrid processes combining selective laser melting of aluminum with SiC particulate integration enable topology-optimized heat sink geometries previously unmanufacturable.
Industry Challenges
- Metal-matrix composite metallurgist scarcity:Universities have shuttered dedicated composite processing programs, forcing manufacturers to train infiltration technicians in-house and extending process development timelines.
- Multi-jurisdiction certification synchronization:Divergent EPA, REACH, and METI approval schedules force suppliers to maintain parallel qualification batches, inflating inventory carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aluminum Silicon Carbide (Alsic) Market |
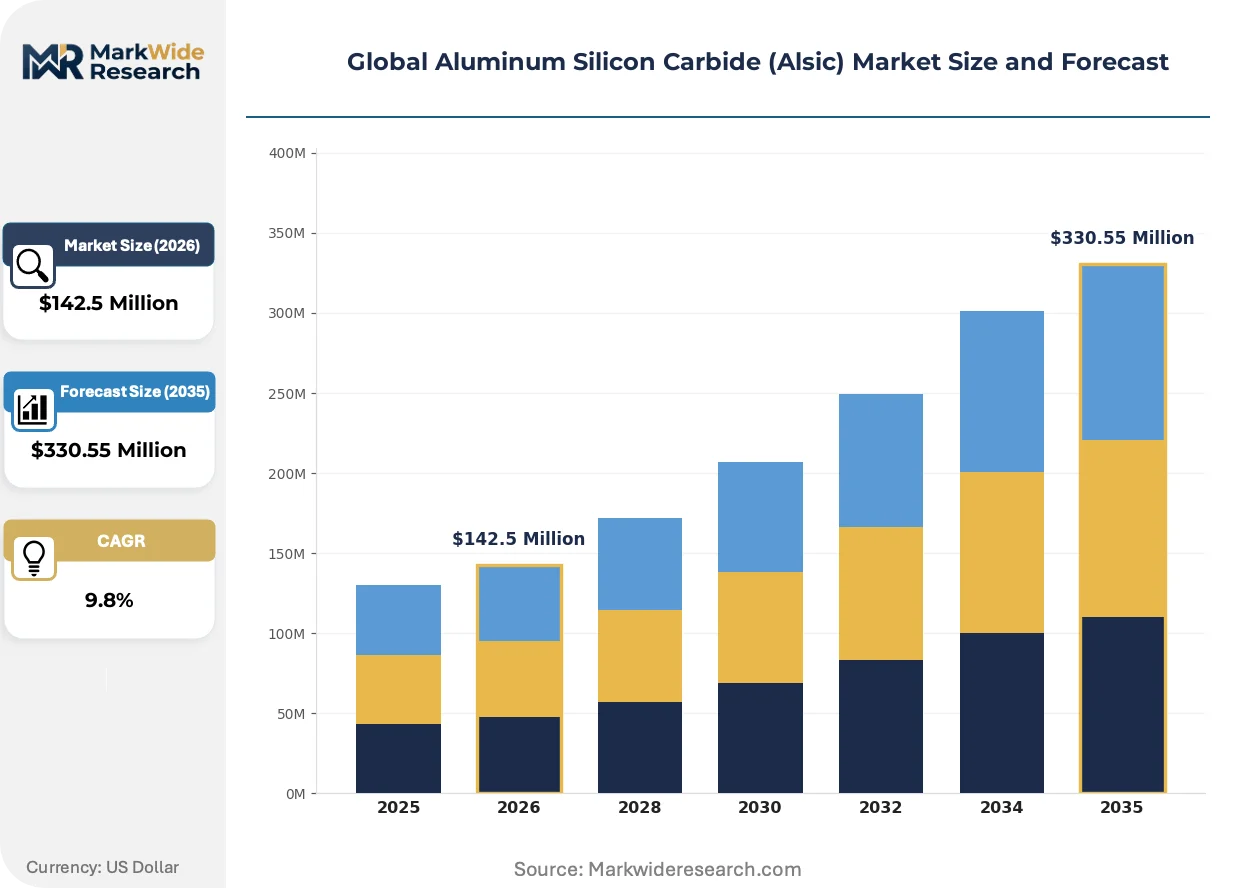
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $330.55 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite Powders, Preforms, Coatings, Particulate Dispersions, Foams Technology: Stir Casting, Powder Metallurgy, Squeeze Casting, Infiltration, Pressureless Infiltration Application: Electronics Housings, Heat Sinks, Structural Components, Brake Rotors, Wear-resistant Parts End User: Consumer Electronics, Aerospace Manufacturers, Foundries, Defense Contractors, Toolmakers |
| Companies Covered | Infineon Technologies AG, Materion Corporation, CPS Technologies Corporation, Denka Company Limited, DWA Aluminum Composites, Sumitomo Electric Industries, STMicroelectronics, Wolfspeed, Inc., Ferrotec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aluminum Silicon Carbide (Alsic) Market Shifts & Advancements
Process intensification and regulatory convergence are reshaping how Alsic components move from powder to qualified assembly. Suppliers compete on certification velocity rather than unit cost alone.
Squeeze casting with real-time porosity monitoring is displacing conventional gravity infiltration for brake rotor and structural aerospace applications. Tier-1 automotive suppliers in Germany and Japan are adopting these systems to meet void fraction specifications below 0.5 percent. The technology is displacing secondary machining operations and reducing material scrap rates by enabling near-net-shape production of complex geometries.
REACH authorization requirements for silicon carbide feedstock are tightening documentary evidence standards for supply chain due diligence. Importers must now demonstrate full substance volume tracking from carbothermal reduction through final composite processing. European electronics housings and heat sink manufacturers are responding by consolidating supplier panels to three qualified sources with pre-submitted dossiers.
Specification-driven procurement now dominates thermal substrate selection for high-reliability electronics. Buyers in South Korea and Taiwan are unbundling material certification from component fabrication, engaging Alsic suppliers directly rather than through integrated module manufacturers. This pattern is most visible in 5G base station and datacenter power supply contracts where substrate thermal performance guarantees determine system-level reliability warranties.
Global Aluminum Silicon Carbide (Alsic) Market Segmentation
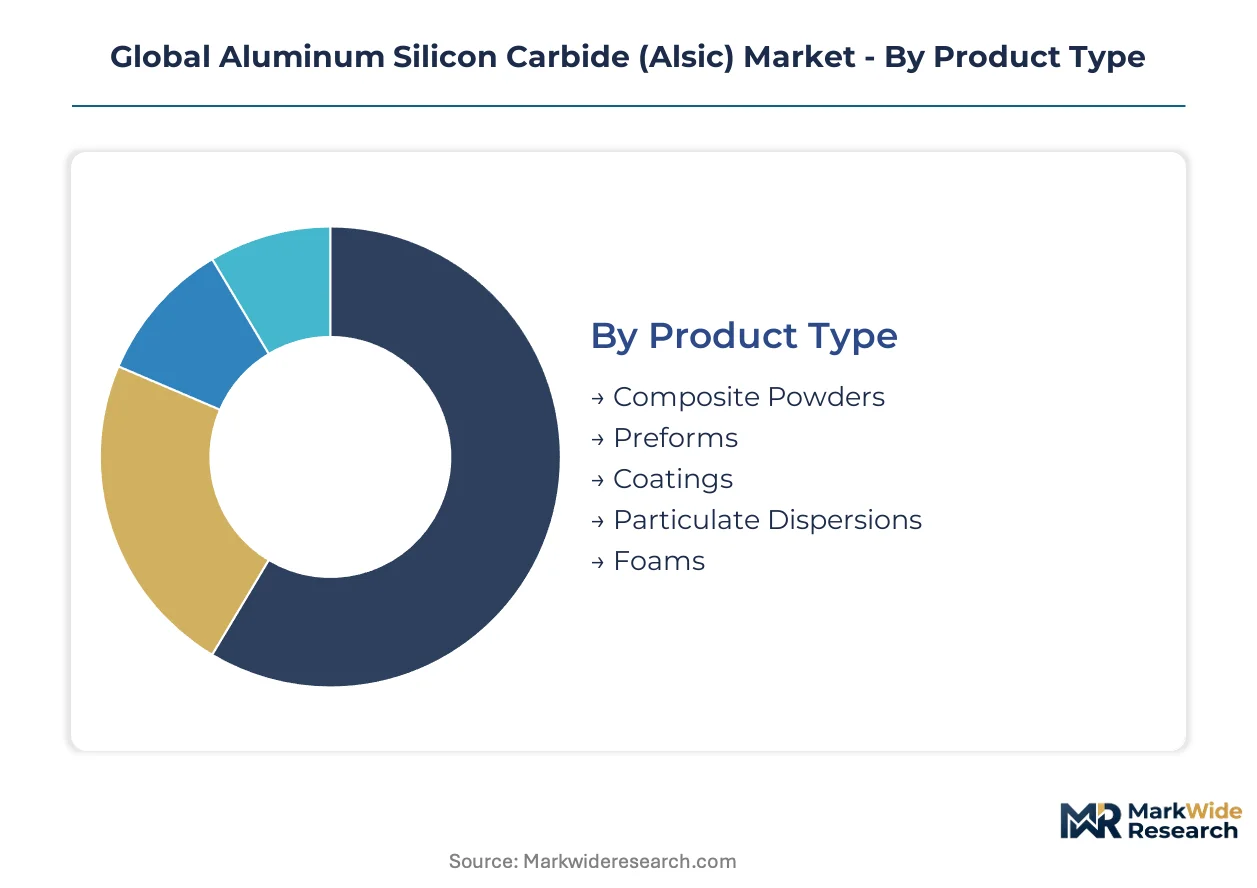
Segmentation in the Alsic market reveals how thermal performance requirements and manufacturing constraints fragment procurement patterns. Buyers prioritize either near-net-shape capability for complex geometries or established infiltration routes for structural reliability. Understanding these trade-offs exposes where substitution threats from copper-molybdenum or pure aluminum alloys concentrate.
Product Type:
Coatings and foams face the most acute substitution pressure from thermal interface materials and phase-change compounds, while composite powders and preforms defend their positions through integration with powder metallurgy infrastructure.
- Composite Powders:Silicon carbide particulate dispersed in aluminum alloy matrices, typically with 30-60 volume percent reinforcement, enable tailored thermal expansion coefficients. Japanese electronics manufacturers concentrate procurement here for 5G base station substrates, driven by METI energy efficiency mandates that specify precise thermal management performance. Composite powders retain volume leadership; preforms hold the steepest expansion curve.
- Preforms:Rigid porous ceramic structures designed for liquid metal infiltration, offering controlled porosity gradients that optimize heat transfer pathways. German automotive suppliers and South Korean semiconductor packaging houses dominate demand, constrained by REACH documentation requirements for silicon carbide feedstock traceability.
- Coatings:Surface-deposited Alsic layers for thermal protection and wear resistance, applied via plasma spraying or cold spraying onto aluminum substrates.
- Particulate Dispersions:Slurry-based suspensions of SiC in aluminum for casting feedstock or additive manufacturing precursors.
- Foams:Cellular metal-matrix structures with extreme specific stiffness, serving niche aerospace damping and impact absorption applications.
Preforms command premium pricing for aerospace qualification batches; composite powders scale most efficiently into consumer electronics volumes.
Technology:
Cost tier stratification separates capital-intensive squeeze casting systems from lower-barrier stir casting operations, with infiltration technologies occupying the middle ground on equipment investment and part complexity.
- Infiltration:Liquid aluminum wicking into porous SiC preforms under vacuum or pressure, achieving near-theoretical density with minimal porosity. CPS Technologies Corporation anchors North American supply using this route for power electronics substrates, though EPA particulate emissions standards constrain powder handling operations in United States facilities. Infiltration retains volume leadership; pressureless infiltration holds the steepest expansion curve.
- Squeeze Casting:High-pressure solidification in closed dies with real-time porosity monitoring, displacing gravity infiltration for brake rotor applications. German and Japanese Tier-1 automotive suppliers adopt these systems to meet void fraction specifications below 0.5 percent, eliminating secondary machining operations.
- Stir Casting:Mechanical mixing of SiC particulate into molten aluminum, the lowest-capital entry point for foundries with existing melting infrastructure.
- Powder Metallurgy:Consolidation of Alsic powders via sintering or hot isostatic pressing, attracting investment for near-net-shape capability in complex heat sink geometries.
- Pressureless Infiltration:Spontaneous melt penetration driven by alloy chemistry and surface energy, reducing equipment complexity versus forced infiltration.
Squeeze casting captures the highest-value automotive contracts; pressureless infiltration expands most quickly among cost-sensitive industrial applications.
Application:
Customer type divergence splits the market between specification-driven electronics procurement and performance-validated aerospace qualification, with automotive applications bridging both regimes.
- Heat Sinks:Finned or pin-array thermal dissipators for power semiconductors, where matched coefficient of thermal expansion prevents solder joint fatigue. South Korean and Taiwanese buyers unbundle material certification from module fabrication, engaging Alsic suppliers directly for 5G and datacenter power supply warranties. Heat sinks retain volume leadership; electronics housings hold the steepest expansion curve.
- Electronics Housings:Enclosures combining electromagnetic shielding with thermal management for high-density power converters. Chinese, Japanese, and South Korean manufacturers concentrate procurement here, responding to METI efficiency mandates and domestic energy conservation standards.
- Structural Components:Load-bearing aerospace parts where specific stiffness and thermal stability outweigh absolute strength requirements.
- Brake Rotors:High-thermal-mass rotating components for performance and heavy-duty vehicles, where wear resistance and thermal fatigue life determine replacement intervals.
- Wear-resistant Parts:Industrial tooling and machine components exposed to abrasive environments, competing against ceramic-matrix and cemented carbide alternatives.
Heat sinks dominate unit volumes across consumer and industrial electronics; electronics housings climb fastest as power density increases in renewable energy inverters.
End User:
Geography and margin structure concentrate supply relationships, with aerospace and defense contractors demanding heritage traceability while consumer electronics manufacturers prioritize scale and certification velocity.
- Aerospace Manufacturers:Prime contractors and subsystem suppliers requiring full material pedigree for thermal management substrates in satellites and aircraft. Satellite constellation deployments drive radiation-hardened substrate specifications, opening premium pricing tiers for suppliers with space qualification pathways. Aerospace manufacturers retain volume leadership; consumer electronics holds the steepest expansion curve.
- Consumer Electronics:Original equipment manufacturers and contract assemblers specifying Alsic for smartphones, laptops, and power adapters. India's PLI scheme incentives for semiconductor and component production create first-mover opportunities for suppliers establishing local powder processing partnerships.
- Foundries:Metal casting operations purchasing Alsic feedstock or processing services for third-party component production.
- Defense Contractors:National security-focused procurement with frozen specifications and extended qualification cycles, limiting design flexibility.
- Toolmakers:Cutting tool and industrial equipment manufacturers integrating wear-resistant Alsic components into metalworking and material handling systems.
Aerospace manufacturers lock in long-term supply agreements; consumer electronics segments gain share fastest as EV and renewable energy inverter volumes accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA particulate emissions standards constrain powder handling operations across United States manufacturing facilities, while REACH documentation requirements in Europe elevate compliance burdens for silicon carbide feedstock importers. China, Japan, and South Korea concentrate procurement for electronics housings and heat sink applications as thermal management requirements intensify in power electronics.
United States
Aerospace manufacturers drive specification of radiation-hardened thermal management substrates for satellite constellation deployments. EPA regulations on particulate emissions constrain powder handling and machining operations in domestic facilities, accelerating investment in closed-loop manufacturing systems. CPS Technologies Corporation anchors North American supply for infiltrated Alsic components serving power electronics from Massachusetts-based operations.
Germany
Tier-1 automotive suppliers adopt squeeze casting systems with real-time porosity monitoring to meet void fraction specifications below 0.5 percent for brake rotor applications. ECHA registration requirements under REACH favor incumbent suppliers with established EU chemical compliance infrastructure for silicon carbide feedstock traceability. Industrial clusters in Bavaria and Baden-Württemberg concentrate precision casting operations for near-net-shape thermal management components.
Japan
METI energy efficiency standards for power electronics indirectly drive specification of Alsic heat sinks in consumer and industrial applications through thermal performance mandates. Denka Company Limited dominates domestic output of composite powders with tightly controlled particle size distributions from Tokyo-based production. The Kanto and Kansai regions house concentrated electronics manufacturing procurement for 5G base station substrates.
China
High-purity silicon carbide powder supply concentrates among domestic producers, exposing processors to export licensing volatility and freight cost spikes. MIIT industrial standards for semiconductor materials shape qualification protocols for metal-matrix composite substrates in power electronics applications. Yangtze River Delta manufacturing clusters concentrate electronics housings and heat sink fabrication for renewable energy inverter supply chains.
South Korea
Buyers unbundle material certification from component fabrication, engaging Alsic suppliers directly for 5G base station and datacenter power supply warranties. MFDS chemical substance management requirements align with broader East Asian regulatory convergence on composite material traceability. Seoul Capital Area semiconductor packaging houses dominate demand for preforms with controlled porosity gradients optimizing heat transfer pathways.
Global Aluminum Silicon Carbide (Alsic) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Alsic supply base, with metallurgist scarcity extending ramp-up schedules for capacity expansion. The structure fragments across powder metallurgy routes, infiltration specialists, and near-net-shape fabricators competing on certification velocity rather than unit cost alone. Strategic archetypes include beryllium heritage materials companies, infiltrated component specialists, and composite powder producers with particle size control capabilities. Dominant competitive moves center on backward integration into silicon carbide feedstock sourcing and geographic expansion into India electronics manufacturing corridors.
Among Japan-based materials producers, Denka Company Limited exemplifies the composite powder archetype with tightly controlled particle size distribution capabilities. Materion Corporation represents the beryllium and advanced materials heritage positioning in thermal management substrates. CPS Technologies Corporation occupies a position within the North American infiltrated component specialist tier serving power electronics applications.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| Materion Corporation |
| CPS Technologies Corporation |
| Denka Company Limited |
| DWA Aluminum Composites |
| Sumitomo Electric Industries |
| STMicroelectronics |
| Wolfspeed, Inc. |
| Ferrotec Corporation |
| Others |
Supply & Pricing Matrix
REACH authorization requirements for silicon carbide feedstock simultaneously gate supply qualification and stratify price tiers, forcing European buyers to consolidate supplier panels while paying premiums for pre-submitted dossiers that compress procurement timelines.
Pricing Analysis
Geographic price spreads of 15-25 percent separate Japanese composite powder deliveries from Chinese-origin material, with Denka Company Limited commanding premiums for tightly controlled particle size distributions. Pricing stratifies across aerospace qualification batches, industrial heat sink volumes, and automotive brake rotor contracts, with certification grade and volume scale as primary differentiation drivers. Cost compression in consumer electronics tiers is intensifying because South Korean and Taiwanese buyers unbundle material certification from module fabrication. Foundries and stir-casting operations exhibit highest price sensitivity; satellite constellation prime contractors demonstrate lowest sensitivity due to heritage traceability requirements.
Supply Chain Analysis
Strategic stockpiling of high-purity SiC powder dominates procurement behavior among Japanese and German manufacturers, insulating against export licensing volatility from Chinese producers. Supply concentrates in China, Japan, and Germany, with raw material dependencies on carbothermal reduction feedstock, aluminum alloy master alloys, and vacuum infiltration equipment. Single-source vulnerability in high-purity SiC powder exposes processors to freight cost spikes and licensing delays. Distribution runs through qualified supplier panels of three pre-approved sources for European electronics housings manufacturers, with direct engagement replacing module-integrated procurement in South Korea and Taiwan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates switching costs: once qualified for aerospace or automotive programs, suppliers face multi-year replacement cycles that freeze incumbent positions.
For Market Incumbents: Compound certification velocity advantages by backward integration into silicon carbide feedstock sourcing, capturing margin from powder processing while insulating against Chinese export volatility. Expand squeeze casting capacity in Germany and Japan to serve Tier-1 automotive contracts demanding void fractions below 0.5 percent. Metallurgist scarcity threatens ramp-up timelines; in-house training academies anchored at Massachusetts and Tokyo operations defend process development speed against specialist competitors. For New Entrants and Emerging Players: Rapid qualification services for mid-tier industrial applications represent the most acute service-layer gap, with incumbents prioritizing aerospace and consumer electronics volumes. Target India's PLI scheme corridors for semiconductor component manufacturing, establishing powder processing partnerships before local supply chains mature. Lead with additive manufacturing convergence offerings—hybrid selective laser melting with SiC integration—enabling topology-optimized geometries that bypass incumbent infiltration infrastructure. For Investors and Strategic Acquirers: REACH authorization milestones reshape the acquisition landscape by elevating compliance infrastructure to strategic asset status, with dossier-ready suppliers commanding scarcity premiums. Five-to-ten year viability favors composite powder producers with particle size control capabilities and established space qualification pathways. Monitor divergence between EPA, REACH, and METI approval schedules as the critical signal: synchronization failures inflate inventory carrying costs and strain working capital across supplier tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Feedstock | Captures margin from carbothermal reduction while insulating Chinese export licensing exposure. |
| Squeeze Casting Capacity Expansion | Meets German and Japanese automotive void fraction specifications below 0.5 percent. |
| Additive Manufacturing Convergence | Enables topology-optimized heat sink geometries previously unmanufacturable via infiltration routes. |
| India PLI Scheme Localization | Secures first-mover positioning in semiconductor packaging corridors before supply chain maturation. |
| Space Qualification Pathway Investment | Opens premium pricing tiers for radiation-hardened substrates serving satellite constellation deployments. |
Research Methodology
Operator-level perspectives from infiltration technicians, powder metallurgy plant managers, aerospace procurement leads, power electronics substrate engineers, and REACH compliance officers anchored the qualitative base. Primary fieldwork combined with secondary validation from SEC 10-K filings, ECHA registration databases, METI energy efficiency standard disclosures, and customs trade data for silicon carbide powder movements. Bottom-up capacity assessments across Massachusetts, Tokyo, and Bavaria operations triangulated against top-down demand modeling from EV inverter and 5G base station deployment forecasts.
Sensitivity analysis tested forecast robustness across variable SiC powder pricing, divergent regulatory approval timelines, and metallurgist training pipeline scenarios. Segmentation dimensions modeled include product type, manufacturing technology, application thermal performance tier, end-user industry, and regional regulatory cluster. CAGRs derived from installed base expansion rates in power electronics and aerospace qualification batch volumes. Industry-specific inputs encompassed squeeze casting equipment deployment schedules and satellite constellation launch manifests.
Underlying assumptions cover sustained silicon carbide MOSFET adoption, stable REACH authorization timelines, and continued METI efficiency mandate enforcement, with deviation risk concentrated in Chinese export licensing volatility and university composite processing program closures. Revision becomes warranted when metallurgist training pipeline recovery crosses thresholds that compress capacity expansion timelines below modeled ranges.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Aramid Prepreg Market
Advanced Alloys
Lithium Nitride Market
Advanced Alloys
North America Green Steel Market
Advanced Alloys
Chromium Carbide Overlay Plate Market
Advanced Alloys
Soft Magnetic Material for Electric Vehicle Market
Advanced Alloys
Nickel Alloy Market
Advanced Alloys
Global Ferroalloys Market
Advanced Alloys
Tungsten Alloy Market
Advanced Alloys
Nitinol Market
Advanced Alloys
North America Braze Alloys Market
Advanced Alloys
Aluminum Die Casting Market
Advanced Alloys
Medium Entropy Alloys Market
Advanced Alloys
High Strength Steel (HSS) Market
Advanced Alloys
Global Quartz Countertops Market
Advanced Alloys
Cermet Market
Advanced Alloys
Ultra High Strength Steel Market