
 Cermet Market | 2026-2036
Cermet Market Size, Share, and Industry Trends Forecast 2026-2036
Cermet Market Analysis
Modular coating kits are recalibrating buyer choice in the cermet supply chain, letting end users mix ceramic-metal composite layers rather than accepting fixed formulations. Kyocera Corporation anchors Japanese production of sintered cermet substrates for cutting tool inserts. Materion Corporation leverages its beryllium alloy expertise to dominate aerospace-grade ceramic-metal composites. CPS Technologies Corporation specializes in aluminum nitride cermet packaging for high-reliability electronics.
Cermets are composite materials combining ceramic phases with metallic binders, typically fabricated through powder metallurgy sintering at temperatures between 1300°C and 1700°C to achieve hardness exceeding 90 HRA alongside fracture toughness above 10 MPa·m½. Ceramic-metal composites command the largest volume share due to entrenched demand from indexable cutting tool inserts. Coatings represent the fastest-expanding product type as thermal barrier deposition shifts from superalloys to cermet systems in gas turbine hot sections. Sprayed form factors are gaining share in repair and overhaul applications where localized resurfacing reduces material waste versus full component replacement.
REACH registration in Europe mandates full substance disclosure for cobalt and nickel binder chemistries, pushing reformulation toward iron-based metallic phases. EPA hazardous air pollutant standards under the National Emission Standards for Hazardous Air Pollutants constrain spray deposition operations in US manufacturing facilities. ISO 45001 occupational health frameworks are becoming a de facto market access requirement for defense and energy sector procurement. Stakeholders must monitor binder metal substitution pathways and deposition technology shifts to maintain specification compliance across regulated end-use verticals.
Market Dynamics
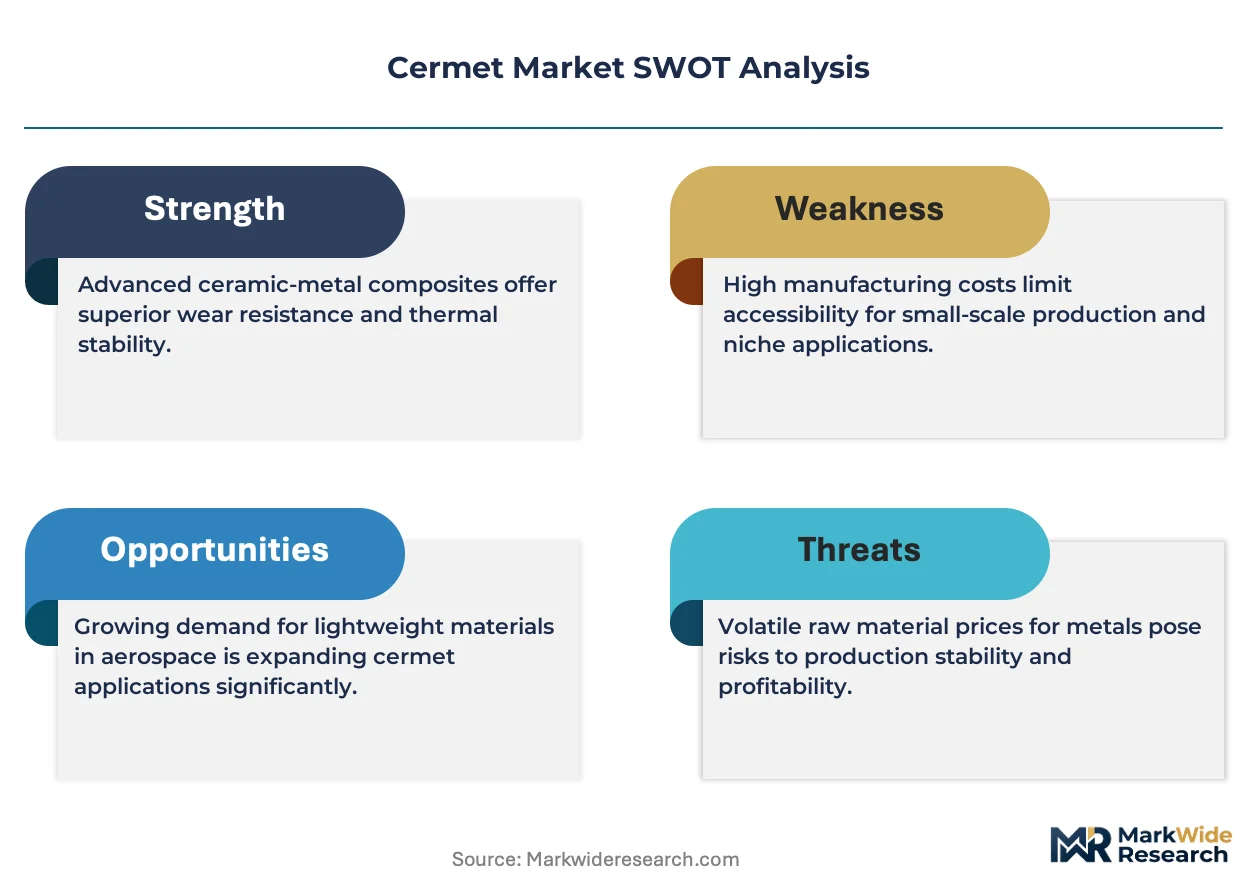
Modular coating architectures are restructuring buyer-supplier relationships in cermet systems, as end users demand layer-by-layer configurability rather than fixed ceramic-metal formulations from single-source vendors.
Growth Catalysts
- EPA hazardous air pollutant standards:NESHAP constraints on spray deposition operations in US manufacturing are accelerating closed-loop thermal spray system upgrades, expanding addressable equipment revenue streams.
- Aerospace turbine blade refurbishment:Hot-section component repair cycles are shortening as airlines extend engine on-wing times, driving localized cermet resurfacing demand over full replacement.
- Germany's precision manufacturing corridor:Concentrated cutting tool production around Stuttgart and Aachen sustains premium sintered substrate offtake for indexable insert applications.
Market Restraints
- Cobalt supply concentration:Metallic binder sourcing depends on politically unstable copper-cobalt belt extraction, exposing formulation costs to DRC-Zambia logistics disruptions.
- Sintering temperature requirements:Furnace energy intensity at 1300°C–1700°C constrains facility siting near renewable power grids, limiting greenfield expansion in carbon-regulated jurisdictions.
- Superalloy thermal barrier competition:Established yttria-stabilized zirconia coatings on nickel-base substrates retain incumbent specification lock-in across legacy turbine fleets.
Strategic Opportunities
- India's defense aerospace indigenization:HAL and DRDO supplier qualification pathways are opening for cermet-coated compressor blade domestic production under import substitution mandates.
- Iron-based binder reformulation:REACH-registered cobalt alternatives enable European market re-entry for reformulated cutting tool substrates previously restricted by substance disclosure requirements.
- Directed energy deposition repair:Laser cladding of cermet layers onto worn hot-section components is creating service-revenue models distinct from virgin material sales.
Industry Challenges
- Powder metallurgy talent scarcity:Sintering process engineers with ceramic-metal composite expertise are concentrated in Japan's Nagoya-Osaka corridor, constraining global facility replication.
- ISO 45001 certification timelines:Occupational health framework compliance for defense and energy procurement is extending vendor qualification cycles by 12–18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cermet Market |
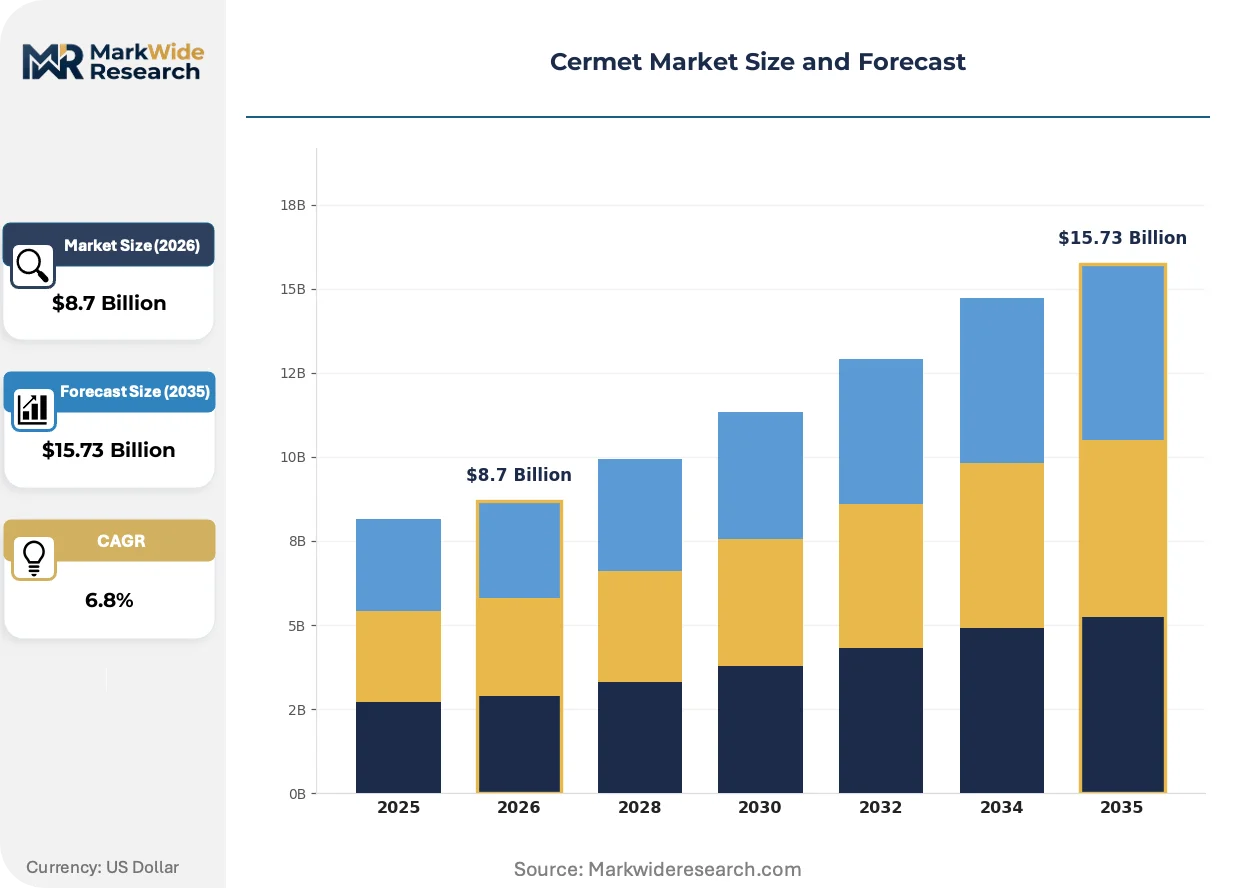
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic-Metal Composites, Monolithic Cermets, Coatings, Pellets Application: Aerospace, Automotive, Electronics, Cutting Tools Form: Powder, Sintered, Sprayed, Compacted End User: Manufacturing, Defense, Energy, Telecommunications |
| Companies Covered | Materion Corporation, 3M, CPS Technologies Corporation, Metal Cast Technologies, AMETEK, Ultramet, Alvant Ltd, CeramTec, Kyocera Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cermet Market Emerging Trajectories
Thermal spray deposition is fragmenting into discrete, remixable process modules while regulatory chemistry disclosure tightens binder metal selection. Buyer behavior is compressing toward specification-driven spot purchasing.
Modular coating kits for gas turbine hot-section repair is modularizing the traditional integrated spray service model. Maintenance, repair, and overhaul providers now procure ceramic feedstock, metallic binders, and deposition parameters as separable inputs. This architecture compresses supplier switching costs and enables in-house process optimization at airline engine shops.
REACH substance disclosure mandates for cobalt and nickel chemistries are forcing European formulation reformulation toward iron-molybdenum binder systems. ECHA registration dossiers now require full toxicological profiles for sintered cermet outputs. German cutting tool manufacturers are responding with pre-certified substrate lines that bundle compliance documentation with material shipments.
Spot specification purchasing is displacing long-term formulation supply agreements in precision machining. Tier-two automotive suppliers now issue material calls against published ceramic-metal composite standards rather than sole-source qualifications. This pattern is most visible in Japan's Aichi prefecture machine tool cluster, where buyers maintain qualified vendor pools of three to five interchangeable substrate sources.
Cermet Market Segmentation
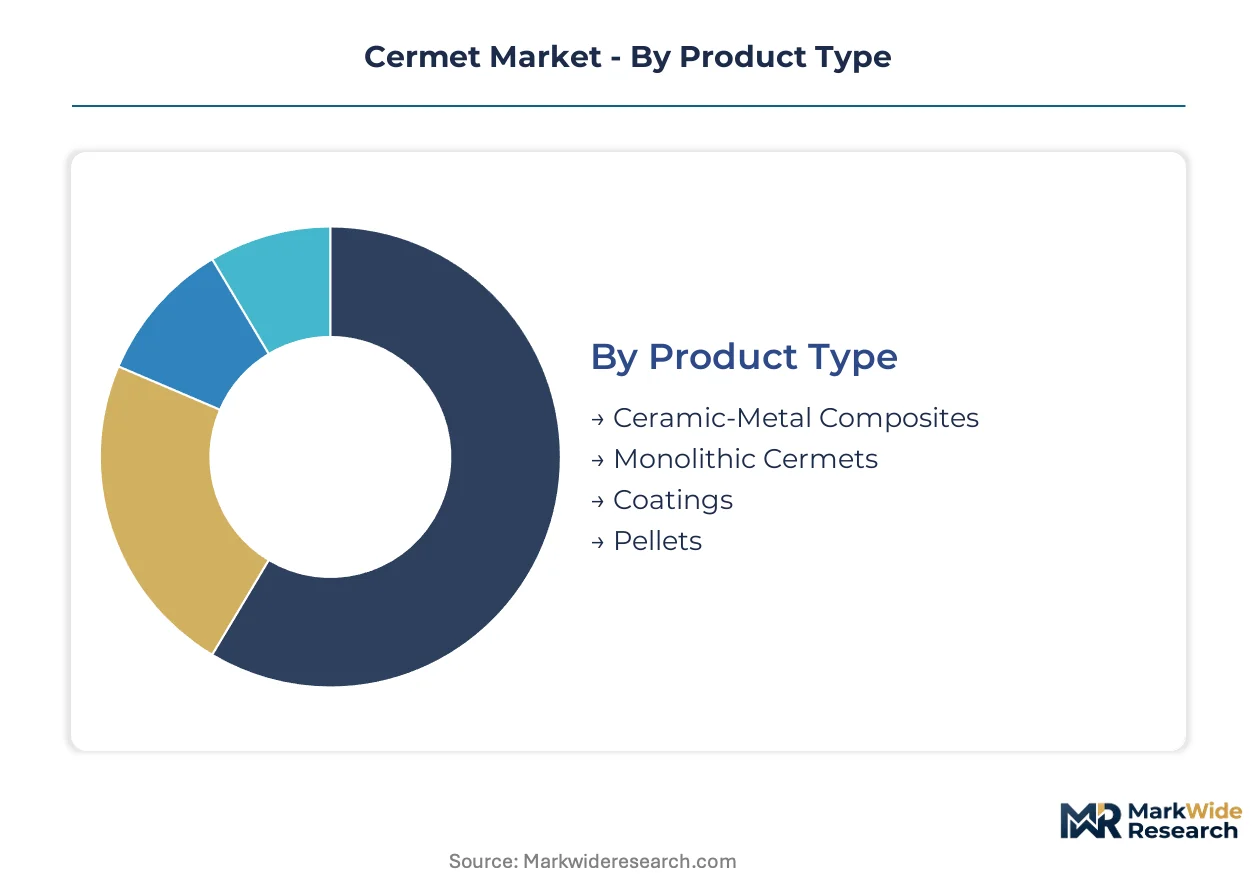
Cermet market segmentation reveals divergent technical requirements across powder metallurgy, thermal spray deposition, and precision machining end uses. Specification granularity varies sharply between standardized sintered substrates for mass-production cutting tools versus bespoke layered architectures for aerospace hot-section refurbishment.
Product Type:
Customization intensity spans from commodity powder blends to engineered multi-layer coating systems with binder-specific compliance documentation.
- Ceramic-Metal Composites:Sintered tungsten carbide-cobalt and titanium carbonitride-nickel formulations dominate indexable cutting tool inserts. Demand concentrates in Germany's Stuttgart-Aachen manufacturing corridor, where precision machining OEMs specify exact hardness-fracture toughness tradeoffs for high-speed steel replacement applications.
- Coatings:Thermal barrier deposition systems combine ceramic topcoats with metallic bond layers for gas turbine blade resurfacing. Airlines in Japan and the United States are shortening hot-section repair cycles, driving localized cermet application over full component replacement to extend engine on-wing times.
- Monolithic Cermets:Homogeneous ceramic-metal structures serve nuclear control rod applications and specialized electrical contacts.
- Pellets:Pressed pre-forms feed high-volume sintering operations for standardized insert geometries.
Most installed capacity flows through Ceramic-Metal Composites. Expansion is steepest in Coatings.
Application:
Performance thresholds separate aerospace qualification pathways from automotive volume procurement, with electronics representing an emerging precision niche.
- Aerospace:Turbine blade thermal barrier systems and compressor seal coatings demand FAA-certified deposition parameters. Repair shops in Japan's Nagoya-Osaka corridor and US Southwest maintenance hubs are adopting modular spray kits to mix ceramic feedstock and metallic binders in-house rather than sourcing fixed formulations.
- Cutting Tools:Indexable inserts for CNC machining require consistent 90+ HRA hardness across batch production. Germany's precision manufacturing sector sustains premium substrate offtake despite REACH-mandated cobalt binder reformulation pressures.
- Automotive:Powertrain component wear coatings and brake system applications specify cost-optimized iron-based binder alternatives.
- Electronics:Aluminum nitride cermet packaging addresses high-reliability thermal management in telecommunications infrastructure.
Volume concentrates in Cutting Tools. Specification complexity peaks in Aerospace.
Form:
Process stage determines supply chain position, with raw powder commanding commodity margins versus sprayed deposits capturing service-integrated value.
- Sintered:Fully densified components from 1300°C–1700°C furnace cycles yield finished cutting inserts and structural parts. Japan's ceramics cluster around Kyocera's production base anchors global supply of premium substrates for precision machining.
- Sprayed:Thermal spray deposition enables localized resurfacing without substrate distortion. EPA NESHAP constraints on US manufacturing facilities are accelerating closed-loop system upgrades, expanding equipment revenue streams alongside consumables.
- Powder:Unprocessed ceramic-metal blends feed captive sintering operations and third-party toll processors.
- Compacted:Green-state pre-forms reduce shipping costs and enable just-in-time sintering for custom geometries.
Value capture is highest in Sprayed form factors. Throughput dominance rests with Sintered outputs.
End User:
Procurement rigor separates defense qualification cycles from commercial manufacturing spot purchasing, with energy sector applications emerging at technology readiness thresholds.
- Manufacturing:Cutting tool OEMs and precision machining job shops drive standardized insert consumption. Japan's Aichi prefecture machine tool cluster exemplifies spot specification purchasing, where buyers maintain qualified vendor pools of three to five interchangeable substrate sources rather than sole-source agreements.
- Defense:Aerospace and naval applications mandate ISO 45001 occupational health certification, extending vendor qualification timelines by 12–18 months. India's HAL and DRDO supplier pathways are opening for cermet-coated compressor blade domestic production under import substitution mandates.
- Energy:Nuclear control rods and geothermal drilling components specify radiation-stable ceramic-metal compositions.
- Telecommunications:5G infrastructure thermal management drives aluminum nitride cermet packaging demand for high-frequency power electronics.
Procurement volume concentrates in Manufacturing. Compliance burden is heaviest in Defense.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cermet technology traces its industrial lineage to post-war Japan, where powder metallurgy expertise concentrated around Nagoya and Osaka. German precision engineering subsequently commercialized sintered substrates for cutting tool applications. Contemporary demand now spans aerospace refurbishment in the United States, regulatory-driven reformulation in Europe, and defense indigenization in India.
United States
EPA NESHAP constraints on spray deposition operations are accelerating closed-loop thermal spray system upgrades at manufacturing facilities. FAA-certified deposition parameters govern turbine blade thermal barrier applications for commercial aviation. Maintenance hubs in the US Southwest are adopting modular spray kits to enable in-house ceramic-metal composite layer optimization.
Germany
REACH substance disclosure mandates for cobalt and nickel chemistries are pushing cutting tool substrate reformulation toward iron-molybdenum binder systems. ECHA registration dossiers now require full toxicological profiles for sintered cermet outputs. Stuttgart and Aachen sustain premium substrate offtake despite compliance-driven chemistry transitions.
Japan
Airlines are shortening hot-section repair cycles to extend engine on-wing times, driving localized cermet resurfacing demand. METI industrial standards govern ceramic-metal composite specifications for domestic procurement. Kyocera's production base in the Nagoya-Osaka corridor anchors global supply of premium sintered substrates.
India
HAL and DRDO supplier qualification pathways are opening for cermet-coated compressor blade domestic production under import substitution mandates. BIS standards and defense procurement frameworks constrain vendor selection to certified domestic fabricators. Precision machining clusters in Pune and Bangalore are developing captive sintering capabilities.
China
Dual carbon goals are constraining furnace energy intensity at 1300°C–1700°C sintering temperatures, limiting greenfield expansion in carbon-regulated jurisdictions. MIIT industrial policy directs ceramic-metal composite development toward aerospace and nuclear applications. Yangtze River Delta manufacturing bases are consolidating powder metallurgy capacity.
Cermet Market Vendor Landscape
The competitive structure tilts toward technology-anchored specialists rather than diversified materials conglomerates. Japanese and German fabricators dominate premium sintered substrates, while US-based players concentrate on aerospace-grade deposition systems. Three archetypes define positioning: integrated ceramics manufacturers with captive powder metallurgy, aerospace-focused coating specialists, and toll processors serving spot specification purchasing. Capacity expansion and strategic partnerships represent the dominant competitive moves, with reformulation capabilities becoming critical for European market access.
Among Japan-based integrated manufacturers, Kyocera Corporation exemplifies the captive sintering archetype with deep ceramic substrate expertise. Materion Corporation occupies a position among US aerospace-grade specialists leveraging metallic binder capabilities. CPS Technologies Corporation represents the electronics-facing specialization vector with aluminum nitride packaging focus.
| Leading Market Players |
|---|
| Materion Corporation |
| 3M |
| CPS Technologies Corporation |
| Metal Cast Technologies |
| AMETEK |
| Ultramet |
| Alvant Ltd |
| CeramTec |
| Kyocera Corporation |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between REACH-compliant iron-molybdenum substrates and legacy cobalt-bound formulations splits pricing power across European and Asian supply corridors, with compliant materials commanding premium positioning while non-compliant inventory faces forced discounting or market exclusion.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs cermet procurement, with aerospace-qualified deposition systems separating from automotive iron-binder grades and commodity powder blends. Price differentiation hinges on ECHA registration documentation and ISO 45001 certification status. Cost compression in standard-grade cutting tool substrates is intensifying because Japanese buyers maintain interchangeable vendor pools of three to five qualified sources. Tier-two automotive suppliers exhibit highest price sensitivity, while defense aerospace procurement shows lowest elasticity due to qualification lock-in.
Supply Chain Analysis
Single-source vulnerability sits with cobalt feedstock extraction from the DRC-Zambia copper belt, where logistics disruptions propagate formulation cost volatility. Manufacturing draws from Japan's Nagoya-Osaka ceramics corridor, Germany's Stuttgart-Aachen precision cluster, and China's Yangtze River Delta consolidation. Raw material dependencies encompass tungsten carbide powders, titanium carbonitride precursors, and metallic binder alloys. Tariff exposure on ceramic powder imports constrains margin flexibility. Distribution runs through qualified OEM supply agreements and spot specification purchasing at tier-two machine tool shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where REACH substance disclosure mandates and EPA NESHAP emissions constraints continuously reshape formulation economics and procurement access.
For Market Incumbents: Anchor compliance capabilities as the primary defensive moat by pre-certifying substrate lines that bundle ECHA documentation with material shipments. Deepen captive sintering capacity in Japan's ceramics corridor to offset powder metallurgy talent scarcity. Vertical integration into iron-molybdenum binder production reduces exposure to DRC-Zambia cobalt logistics disruptions.
For New Entrants and Emerging Players: Launch via directed energy deposition repair services targeting airline maintenance hubs in the US Southwest and Japan's Nagoya-Osaka corridor, where modular spray kit adoption creates service-revenue entry points distinct from virgin material sales. India's HAL and DRDO supplier qualification pathways offer the most penetrable white-space for defense aerospace indigenization mandates.
For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 45001 certification timelines extend vendor qualification cycles by 12–18 months, favoring scaled incumbents with established defense and energy sector access. Target vertically integrated ceramics manufacturers with captive powder metallurgy and REACH-registered formulation libraries. Watch iron-based binder substitution rates as the signal indicating European market re-entry viability for reformulated product lines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallic Binder Production | Captive iron-molybdenum alloy supply secures REACH compliance and insulates against DRC cobalt disruption. |
| REACH-Pre-Certified Substrate Line Launch | Bundled ECHA documentation accelerates European customer procurement cycles and commands price premiums. |
| Directed Energy Deposition Repair Service Buildout | Localized cermet resurfacing at airline engine shops captures recurring revenue from turbine blade refurbishment demand. |
| ISO 45001 Certification Investment | Occupational health framework compliance unlocks defense and energy sector procurement access with extended vendor lock-in. |
| Joint Venture with Indian Domestic Fabricator | HAL and DRDO supplier qualification pathways open under import substitution mandates for compressor blade production. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with powder metallurgy process engineers, cutting tool procurement managers at precision machining OEMs, thermal spray deposition technicians, aerospace maintenance directors, and regulatory compliance officers with secondary validation from ECHA registration dossiers, EPA NESHAP compliance records, METI industrial standards publications, and SEC filings from listed ceramics manufacturers. Bottom-up substrate consumption estimates and top-down aerospace refurbishment demand projections were triangulated against trade flow data.
Segment-weighted modeling distributed value and volume across ceramic-metal composites, coatings, monolithic structures, and pellet form factors, further disaggregated by sintered, sprayed, powder, and compacted processing stages. End-use weights incorporated cutting tool insert consumption patterns, gas turbine hot-section repair cycles, automotive powertrain coating specifications, and electronics packaging demand. CAGRs were derived from fitted growth curves against historical qualification timeline data and regulatory implementation schedules. Forecast inputs included furnace energy intensity constraints, cobalt price volatility bands, and defense procurement indigenization policy trajectories.
Several conditions sit outside the modeled scope, including breakthrough sintering temperature reductions below 1300°C, novel ceramic phase discoveries displacing tungsten carbide-titanium carbonitride systems, and geopolitical trade restrictions exceeding current tariff exposure levels. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Steel Fiber Market
Advanced Alloys
Aramid Prepreg Market
Advanced Alloys
Precipitation Hardening Market
Advanced Alloys
Forgings Market
Advanced Alloys
Oxide Dispersion Strengthened (ODS) Alloys Market
Advanced Alloys
Global Quartz Countertops Market
Advanced Alloys
Titanium Alloys Market
Advanced Alloys
Tantalum Carbide Market
Advanced Alloys
Aluminum Die Casting Market
Advanced Alloys
Global High Performance Alloys Market
Advanced Alloys
Global Shape Memory Materials Market
Advanced Alloys
US Green Steel Market
Advanced Alloys
Global Stainless Steel Forgings Market
Advanced Alloys
Master Alloys Market
Advanced Alloys
Global Metal Injection Molding Market
Advanced Alloys
Polymer Blends Alloys Market